
 Lactoferrin Market | 2026-2036
Lactoferrin Market Size, Share, and Industry Trends Forecast 2026-2036
Lactoferrin Market Analysis
Australia is reshaping supply dynamics through Synlait Milk Ltd's expansion of pharmaceutical-grade fractionation capacity. Fonterra Co-operative Group Limited anchors Oceania output with integrated whey processing networks spanning multiple sites. FrieslandCampina leverages its Dutch dairy cooperative structure to sustain European lactoferrin availability for infant nutrition customers. MILEI GmbH specializes in German-engineered isolation protocols that differentiate its ingredient purity profiles for clinical applications.
Lactoferrin is an iron-binding glycoprotein comprising approximately 690 amino acids with molecular weight near 80 kDa, isolated from bovine milk whey through cation exchange chromatography and membrane filtration; its primary commercial purpose centers on antimicrobial, anti-inflammatory, and iron-regulation functions across nutrition and therapeutic formulations. The infant formula segment leads volume absorption due to mandatory iron fortification protocols and gut microbiome research, while functional foods represent the fastest-growing margin pool as sports nutrition brands incorporate lactoferrin for recovery positioning. Pharmaceutical applications occupy the highest value tier, where regulatory-grade purity requirements create substantial entry barriers and pricing power for certified manufacturers.
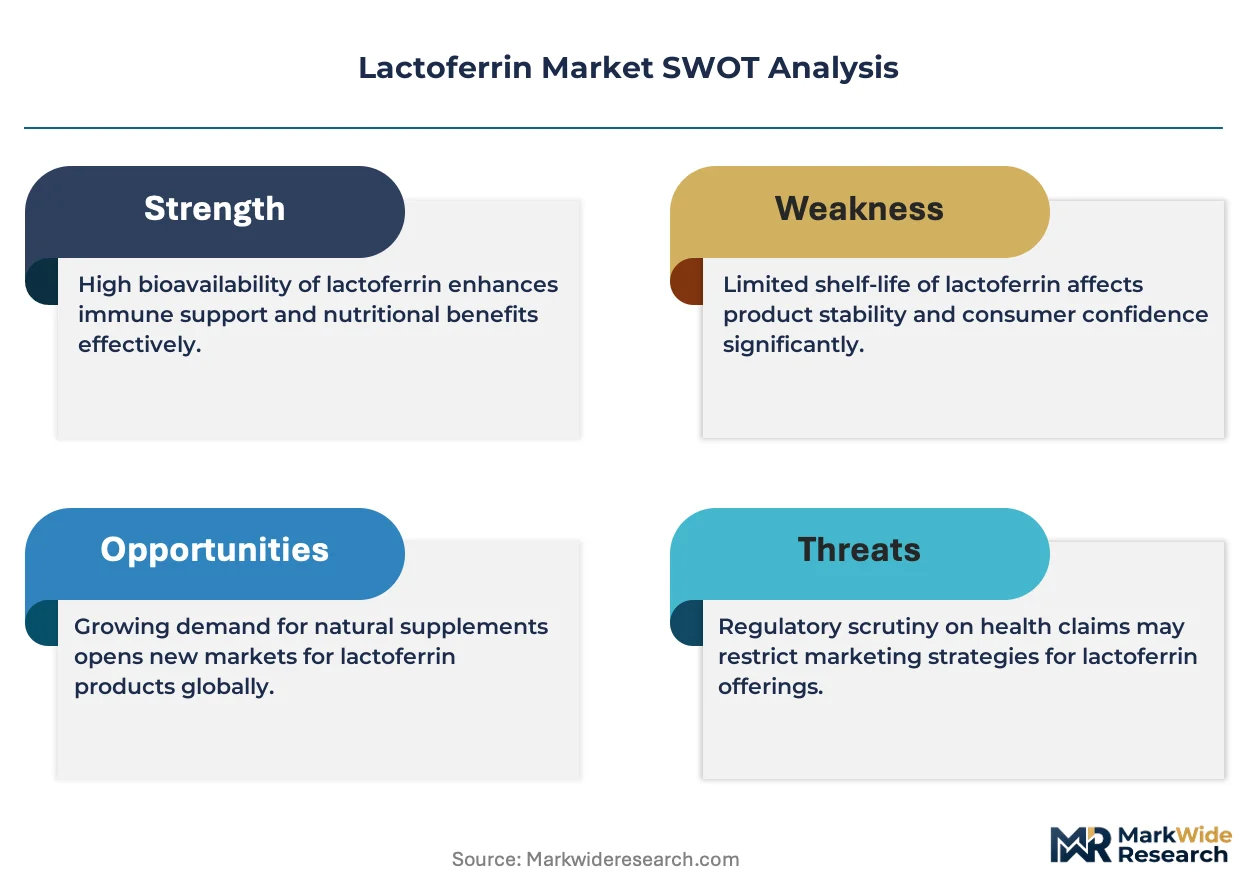
The FDA oversees lactoferrin as a GRAS substance for infant formula applications, while EFSA establishes European purity thresholds that shape import compliance costs for non-EU suppliers. China's NMPA and SAMR enforce dual carbon goals that pressure domestic dairy processors to adopt energy-efficient fractionation technologies or face operational constraints. Stakeholders must monitor evolving pharmacopeial monograph harmonization between USP, EP, and JIS standards, as divergence in iron-saturation testing protocols could fragment market access requirements and force redundant certification investments.
Market Dynamics
Fractionation technology advancement and regulatory purity mandates are compressing supplier margins while concentrating production among integrated dairy processors capable of pharmaceutical-grade certification.
Growth Catalysts
- EFSA purity thresholds:European regulatory tightening around protein standards accelerates investment in cation exchange chromatography and membrane filtration systems among non-EU suppliers seeking market access.
- Clinical nutrition expansion:Gut microbiome research validates antimicrobial and anti-inflammatory properties, widening applications beyond infant formula into therapeutic formulations and sports recovery products.
- China's captive capacity buildout:Domestic dairy processors construct in-house fractionation facilities to reduce import dependency, creating localized supply ecosystems around major urban manufacturing clusters.
Market Restraints
- Whey protein input volatility:Bovine milk supply fluctuations and dairy commodity price cycles create margin pressure for fractionation operators without backward integration into milk collection.
- Supplier concentration risk:Oceania and European cooperatives control disproportionate share of pharmaceutical-grade output, exposing buyers to geographic supply disruption.
- Iron-saturation testing divergence:Non-harmonized protocols between USP, EP, and JIS standards force redundant certification investments and fragment market access requirements.
Strategic Opportunities
- Sports nutrition functional foods:Recovery-positioned products incorporating lactoferrin represent an underexploited margin pool as athletic supplement brands seek differentiation through bioactive ingredients.
- China's dual carbon policy:NMPA and SAMR enforcement of energy-efficiency mandates creates competitive advantage for processors adopting low-temperature fractionation technologies.
- Pharmacopeial harmonization:Convergence of iron-binding assay standards between major regulatory jurisdictions would unlock streamlined certification pathways for multi-region suppliers.
Industry Challenges
- Specialized chromatography engineering talent:Scarcity of process engineers experienced in dairy protein isolation constrains capacity expansion timelines for new market entrants.
- Pharmaceutical-grade validation timelines:Extended regulatory approval cycles for clinical applications delay revenue realization from highest-value product tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactoferrin Market |
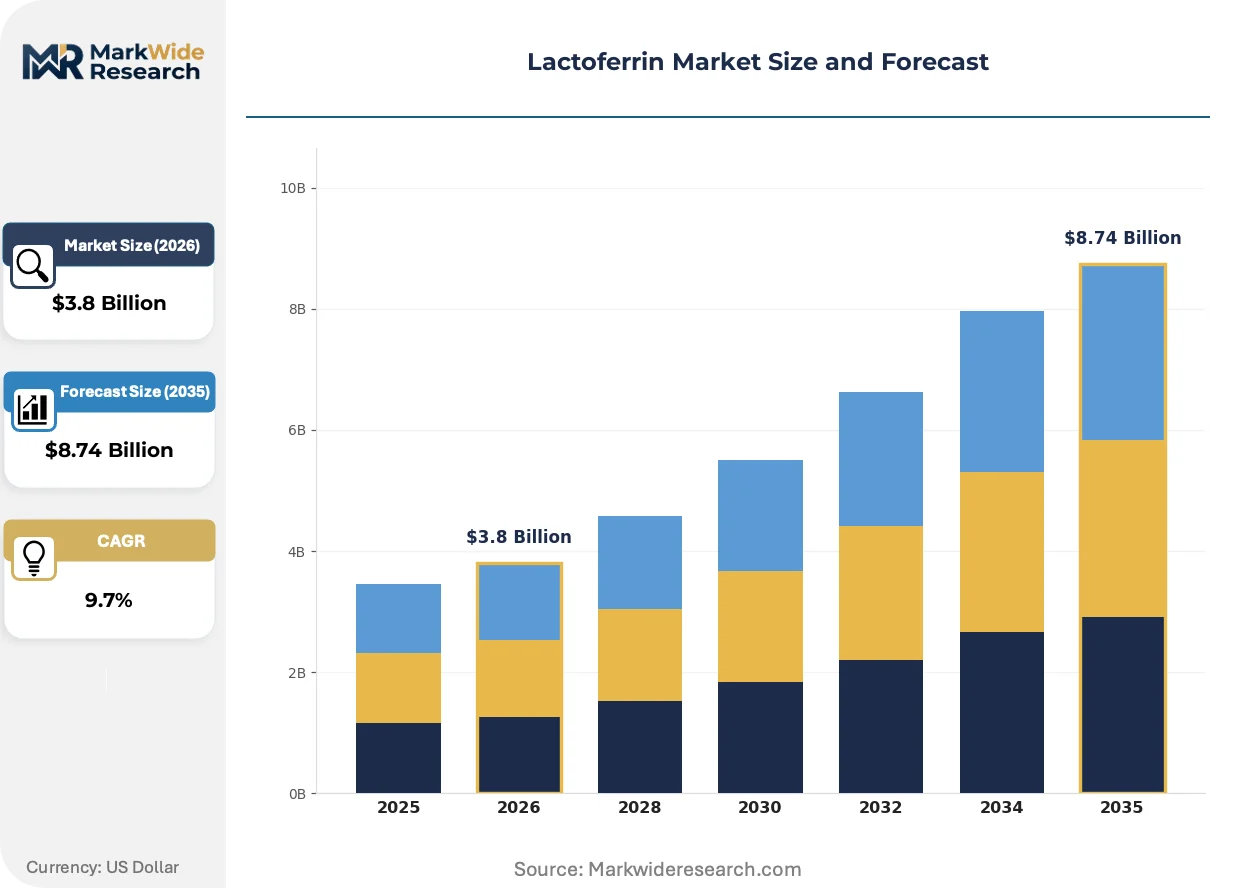
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
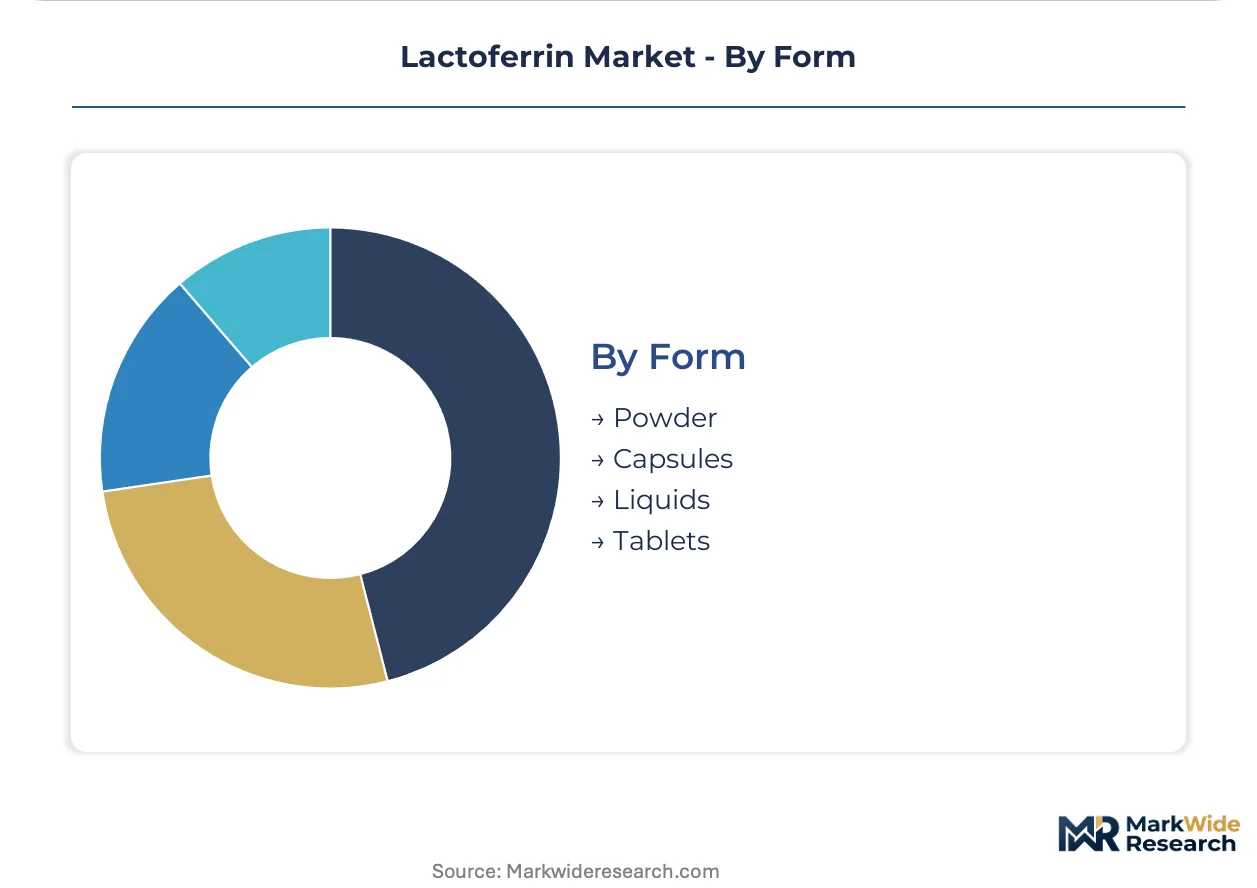
| Segmentation | Product Type: Feminine Health, Infant Formula, Functional Foods, Pharmaceuticals Application: Dietary Supplements, Nutraceuticals, Clinical Nutrition, Sports Nutrition End User: Healthcare Providers, Consumers, Fitness Enthusiasts, Manufacturers Form: Powder, Capsules, Liquids, Tablets |
| Companies Covered | Hilmar Cheese Company, Synlait Milk Ltd, FrieslandCampina, Bega Cheese Limited, Fonterra Co-operative Group Limited, Glanbia Plc, MILEI GmbH, Royal FrieslandCampina N.V., Ingredia SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactoferrin Market Emerging Trajectories
Digital process control systems and predictive analytics are transforming fractionation economics, while regulatory convergence efforts and shifting procurement patterns reshape competitive positioning across supply tiers.
Continuous chromatography systems equipped with real-time purity monitoring are virtualizing traditional batch-based fractionation workflows. Infant formula manufacturers in Asia-Pacific adopt these platforms fastest, compressing production cycles from days to hours while reducing solvent consumption and energy intensity. This virtualization enables smaller production runs with pharmaceutical-grade consistency, eroding the scale advantages historically held by large integrated cooperatives.
REACH registration requirements for novel protein isolates are tightening substance documentation obligations across European supply chains. Manufacturers must now demonstrate full toxicological profiles and environmental fate data for fractionation byproducts, elevating compliance costs for non-EU exporters. Clinical nutrition applications face the steepest documentation burdens, prompting some suppliers to pivot toward food-grade certifications with lower regulatory thresholds.
Direct sourcing contracts between sports nutrition brands and fractionation specialists are displacing traditional ingredient distributor intermediaries. Tier-one athletic supplement companies now embed quality auditors at supplier facilities, unbundling certification verification from conventional procurement relationships. This pattern concentrates most visibly in North American and Australian markets where brand equity depends on transparent supply chain documentation.
Lactoferrin Market Segmentation
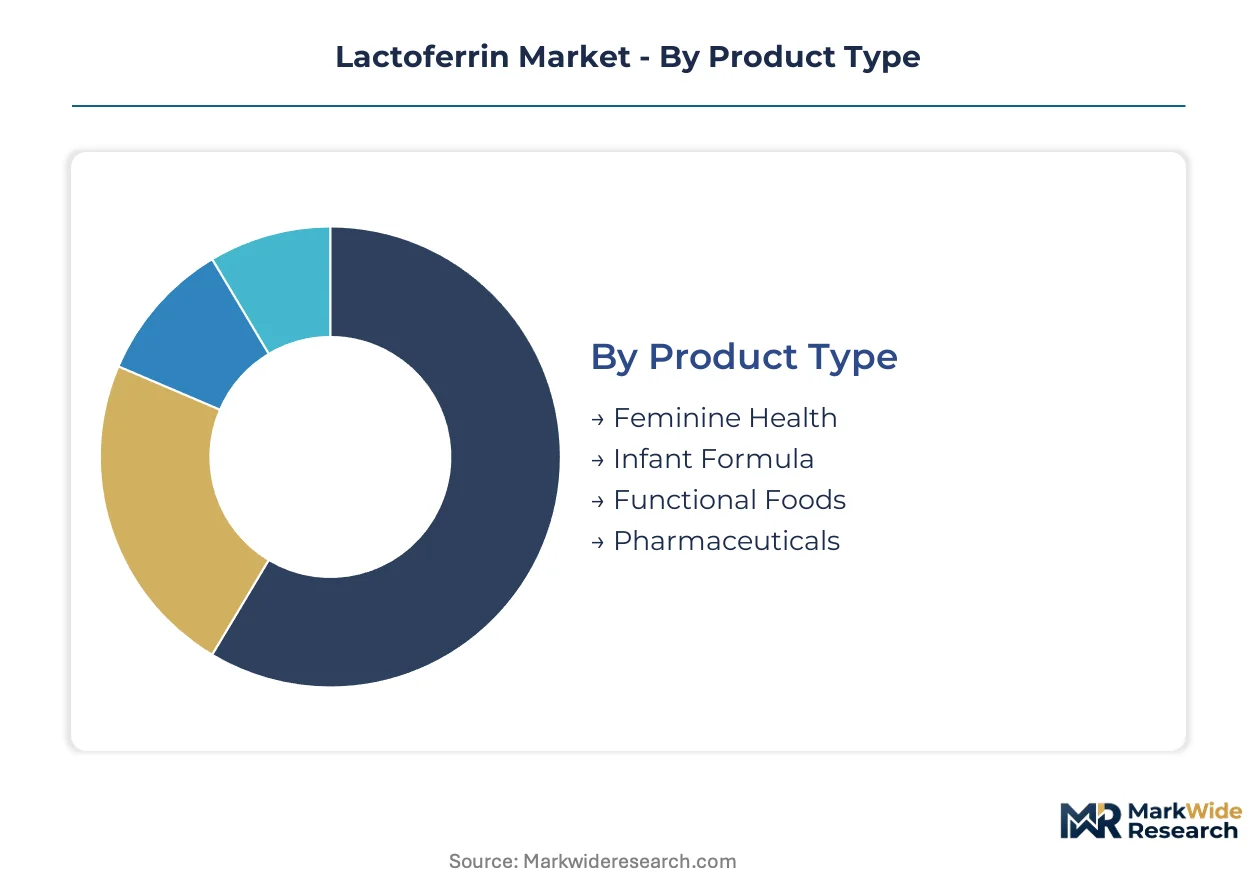
Segmentation in the Lactoferrin Market reveals divergent purity requirements and regulatory pathways that reshape supplier economics across each tier. Pharmaceutical-grade isolation commands fundamentally different production infrastructure than food-grade applications, creating distinct competitive arenas with limited overlap.
Product Type:
After-sales technical support intensity varies dramatically across product tiers, with pharmaceutical-grade customers demanding ongoing validation documentation and batch-specific certificates of analysis that extend relationships well beyond initial sale.
- Infant Formula:Iron-binding glycoprotein with mandatory fortification protocols under FDA GRAS and EFSA purity thresholds. Demand concentrates in China as domestic processors build captive fractionation capacity to reduce import dependency from Oceania cooperatives.
- Pharmaceuticals:Regulatory-grade lactoferrin requiring cation exchange chromatography and membrane filtration to meet USP, EP, and JIS iron-saturation testing standards. Extended validation timelines with FDA and EMA create substantial entry barriers and pricing power for certified manufacturers.
- Functional Foods:Sports nutrition brands embed quality auditors at supplier facilities, unbundling certification verification from conventional procurement relationships.
- Feminine Health:Emerging applications in intimate care products leverage antimicrobial properties validated through gut microbiome research.
Infant Formula holds the largest share; momentum sits with Pharmaceuticals.
Application:
Margin profiles across applications correlate directly with documentation burden, where clinical nutrition faces the steepest REACH registration requirements for toxicological profiles and environmental fate data.
- Clinical Nutrition:Therapeutic formulations targeting antimicrobial and anti-inflammatory functions. European supply chains face elevated compliance costs under EFSA purity mandates, prompting some suppliers to pivot toward food-grade certifications.
- Sports Nutrition:Recovery-positioned products represent an underexploited margin pool as athletic supplement brands seek differentiation through bioactive ingredients. Direct sourcing contracts displace traditional ingredient distributor intermediaries in North American and Australian markets.
- Dietary Supplements:Capsule and tablet formats target consumer self-directed health management with lower regulatory thresholds than clinical applications.
- Nutraceuticals:Positioned at the intersection of nutrition and pharmaceutical benefit claims, requiring careful navigation of jurisdiction-specific marketing regulations.
Clinical Nutrition commands premium positioning; Sports Nutrition is climbing the fastest.
End User:
Procurement authority concentration determines contract structures, with integrated dairy processors and pharmaceutical manufacturers exercising volume leverage unavailable to fragmented consumer channels.
- Manufacturers:Infant formula and sports nutrition producers with embedded quality auditors at fractionation facilities. China's domestic dairy processors construct in-house capacity to reduce dependency on Synlait Milk and Fonterra supply.
- Healthcare Providers:Hospitals and clinical settings prescribing therapeutic lactoferrin formulations under pharmacopeial monograph standards.
- Consumers:Direct-to-market purchasers of dietary supplement formats through retail and e-commerce channels with minimal technical support requirements.
- Fitness Enthusiasts:Athletic supplement consumers driving demand for transparent supply chain documentation and recovery-positioned bioactive ingredients.
Manufacturers dominate procurement volume; Fitness Enthusiasts are gaining share fastest.
Form:
Production economics favor powder formats for bulk pharmaceutical and infant formula applications, while finished dose forms capture downstream margin in consumer-facing channels.
- Powder:Bulk pharmaceutical-grade and infant formula input material. Continuous chromatography systems with real-time purity monitoring enable smaller production runs with pharmaceutical-grade consistency.
- Capsules:Dietary supplement and nutraceutical delivery format with convenience positioning for consumer self-administration.
- Liquids:Ready-to-use formulations for clinical nutrition and pediatric applications requiring precise dosing control.
- Tablets:Compressed solid dose forms with extended shelf stability for sports nutrition and general wellness positioning.
Powder holds the largest share; Capsules show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade lactoferrin production clusters in dairy-processing regions with established whey fractionation infrastructure. Oceania and European cooperatives anchor supply capacity, while Asian markets drive demand absorption through infant formula fortification mandates.
China
Domestic dairy processors build captive fractionation facilities in Hebei and Inner Mongolia to reduce import dependency from Oceania suppliers. NMPA and SAMR enforce dual carbon goals that pressure manufacturers toward energy-efficient cation exchange technologies. Qingdao and Tianjin clusters concentrate pharmaceutical-grade capacity expansion as local infant formula brands seek supply security.
United States
FDA GRAS oversight of lactoferrin fortification supports steady demand from clinical nutrition and sports recovery formulations. California and Wisconsin dairy cooperatives maintain whey processing networks that feed downstream fractionation specialists. Hilmar Cheese Company anchors domestic supply through integrated cheese-making and protein isolation operations in the Central Valley.
Germany
EFSA purity thresholds shape import compliance costs for non-EU suppliers seeking European market access. Bavaria and North Rhine-Westphalia host precision-engineered fractionation facilities serving pharmaceutical and infant nutrition customers. MILEI GmbH exemplifies German-engineered isolation protocols that differentiate regional output for clinical applications.
Netherlands
Dutch dairy cooperative structures sustain European lactoferrin availability through integrated whey valorization networks. FrieslandCampina leverages domestic milk collection density to maintain pharmaceutical-grade output consistency. Wageningen University corridor anchors research partnerships that advance membrane filtration and chromatography process efficiencies.
Australia
Synlait Milk Ltd expands pharmaceutical-grade fractionation capacity in Victoria and New South Wales, reshaping regional supply dynamics. TGA oversight aligns with international pharmacopeial standards, streamlining export certification for Asian markets. Melbourne and Sydney manufacturing clusters concentrate sports nutrition and clinical formulation demand from domestic brands.
Lactoferrin Market Vendor Landscape
Integrated dairy cooperatives and specialized fractionation engineers split the market between scale-driven commodity supply and precision-isolation premium tiers. Production concentrates among Oceania and European players with backward integration into milk collection and whey processing infrastructure. Two archetypes dominate: large cooperatives with multi-site fractionation networks, and regional specialists with pharmaceutical-grade certification depth. Competitive moves center on captive capacity construction in demand-proximate markets and continuous chromatography technology licensing to compress production cycle economics.
Within the integrated cooperative tier, Fonterra Co-operative Group Limited and FrieslandCampina occupy positions defined by geographic milk shed control and multi-decade whey processing experience. Synlait Milk Ltd represents the specialist-engineering archetype with pharmaceutical-grade fractionation focus. Glanbia Plc and Bega Cheese Limited exemplify mid-scale processors expanding protein isolation capabilities to capture margin from bioactive ingredient demand.
| Leading Market Players |
|---|
| Hilmar Cheese Company |
| Synlait Milk Ltd |
| FrieslandCampina |
| Bega Cheese Limited |
| Fonterra Co-operative Group Limited |
| Glanbia Plc |
| MILEI GmbH |
| Royal FrieslandCampina N.V. |
| Ingredia SA |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Oceania whey fractionation capacity compresses pricing tier spreads while forcing Asian infant formula manufacturers toward captive supply investments or premium import premiums.
Pricing Analysis
EFSA purity thresholds dictate the pricing tier structure across the lactoferrin market, separating pharmaceutical-grade isolates certified under USP and EP standards from food-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks iron-saturation certification depth and batch documentation intensity. Cost compression in food-grade tiers is intensifying because Chinese domestic processors are scaling captive fractionation with government subsidy support. Sports nutrition brands exhibit lowest price sensitivity due to recovery-positioning premium capture, while commodity infant formula blenders face acute margin pressure from whey protein input volatility.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk calculus for pharmaceutical-grade lactoferrin procurement. Production gravity centers on New Zealand, the Netherlands, and Germany, with each node drawing from concentrated bovine milk shed networks and integrated whey processing infrastructure. Raw material dependencies rest on cheese whey availability, cation exchange resin supply, and pharmaceutical-grade membrane filtration systems. Single-source vulnerability concentrates in chromatography engineering talent pools. Distribution runs through direct sourcing contracts that displace traditional ingredient distributor intermediaries, particularly in North American and Australian sports nutrition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as clinical nutrition applications splinter into therapeutic, sports recovery, and feminine health niches with divergent purity requirements and procurement authority structures.
For Market Incumbents: Harden pharmaceutical-grade certification moats by accelerating continuous chromatography technology licensing to compress production cycle economics. Deepen backward integration into milk collection in Hebei and Inner Mongolia clusters to preempt Chinese captive capacity erosion. Fonterra and FrieslandCampina should embed quality auditors at downstream infant formula facilities to lock in validation documentation relationships beyond transactional supply.
For New Entrants and Emerging Players: Pursue sports nutrition functional foods as the most penetrable margin pool, where recovery-positioned bioactive demand outruns incumbent supply focus on infant formula. Target German-engineered isolation protocol licensing from MILEI GmbH to differentiate purity profiles for clinical applications. Direct sourcing contract structures with tier-one athletic supplement brands offer unbundled certification verification pathways absent in commodity dairy ingredient channels.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors continuous chromatography specialists with pharmaceutical-grade validation depth. Long-term viability over the next decade hinges on regulatory convergence between USP, EP, and JIS iron-saturation testing standards that would unlock streamlined multi-region certification. Watch pharmacopeial harmonization negotiations as the inflection signal determining redundant compliance investment burdens versus consolidated market access economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography Technology Licensing | Virtualizes batch workflows for Synlait Milk and reduces solvent consumption under China's dual carbon enforcement. |
| Pharmaceutical-Grade Certification Investment | Creates EFSA and FDA GRAS compliance moats that non-EU suppliers must match for European infant formula access. |
| Captive Fractionation Capacity Buildout | Enables Qingdao and Tianjin clusters to reduce import dependency from Fonterra's Oceania supply networks. |
| Direct Sourcing Contract Structuring | Allows sports nutrition brands to embed auditors at MILEI GmbH facilities, displacing distributor intermediaries. |
| Energy-Efficient Cation Exchange Adoption | Aligns Hebei processors with NMPA and SAMR dual carbon goals while lowering operational cost structures. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with infant formula procurement directors, pharmaceutical regulatory affairs leads, dairy cooperative technical managers, and sports nutrition brand supply chain heads. Secondary validation drew from FDA GRAS filings, EFSA purity threshold documentation, NMPA dual carbon policy directives, and customs trade data tracking whey protein isolate flows. Bottom-up volume modeling triangulated against top-down market sizing from pharmaceutical-grade certification capacity assessments.
Calibration against historical fractionation capacity utilization and infant formula fortification mandate adoption patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product purity grade, application clinical depth, end-user procurement authority concentration, and regional regulatory cluster stringency. CAGRs derived from slope analysis of technology adoption curves and capacity expansion timelines, with specific inputs from continuous chromatography virtualization rates and Chinese captive buildout completion schedules.
Sensitivities concentrate around pharmacopeial harmonization failure, whey protein commodity price spikes, and regulatory chokepoints in REACH registration for novel protein isolates. Forecasts reflect documented assumptions on technology diffusion rates and policy enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Calcium Malate Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Fish Oil Supplements Market