
 North America Mattress Market | 2026-2036
North America Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mattress Market Analytics
Hospitality procurement is consolidating as hotel chains standardize sleep programs across properties. Tempur Sealy International leverages its institutional sales infrastructure to anchor major franchise contracts. Serta Simmons Bedding sustains broad manufacturing scale across multiple domestic plants. Sleep Number Corporation differentiates through adjustable air-chamber technology in the premium commercial segment.
A mattress is a fabricated sleep surface combining core support layers with comfort upholstery, typically measured by density in pounds per cubic foot for foam and coil count for innerspring units, engineered to provide spinal alignment and pressure relief during rest. Memory foam formulations now incorporate gel infusions and phase-change materials to address thermal retention, while hybrid constructions merge pocketed coils with foam comfort layers to capture performance-seeking buyers. The online retail channel continues expanding fastest as direct-to-consumer logistics mature, though specialty stores retain higher margin pools through white-glove delivery and financing attachment rates. Budget tiers face compression from private-label imports, while luxury segments defend through certified organic latex and hand-tufted construction.
The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability standards, while California's Bureau of Electronic and Appliance Repair mandates additional chemical disclosure through SB 1019. The EPA's formaldehyde emission regulations under TSCA Title VI further constrain composite wood components in foundation bases. Stakeholders must monitor state-level extended producer responsibility proposals and decide whether to front-run recycling infrastructure investments or absorb pending compliance costs.
Market Dynamics
California's SB 1019 chemical disclosure mandate and the EPA's TSCA Title VI formaldehyde rules are forcing material substitutions across foam and foundation supply chains, compressing margins for manufacturers reliant on legacy composite wood and petroleum-based polyurethane formulations.
Growth Catalysts
- Sun Belt Migration:Residential construction in Texas, Florida, and Arizona is absorbing mattress demand as population inflows sustain new household formation.
- 16 CFR Part 1633:Federal flammability standards create compliance barriers that favor domestic producers with certified testing infrastructure over import competitors.
- Gel-Infused Memory Foam:Thermal regulation improvements in open-cell formulations are expanding addressable share among heat-sensitive sleepers.
Market Restraints
- TDI/MDI Volatility:Polyurethane precursor costs swing with crude oil and natural gas pricing, destabilizing foam layer economics.
- Asian Foundation Imports:Concentrated offshore supply of slatted bases and adjustable frames exposes distributors to tariff and logistics risk.
- Recycling Infrastructure Gaps:Absence of scaled mattress dismantling capacity in most US states leaves producers exposed to pending extended producer responsibility legislation.
Strategic Opportunities
- Mexico Nearshoring:Maquiladora capacity expansion offers tariff-advantaged export platforms for US-bound hospitality contract volume.
- Organic Latex Certification:GOLS and GOTS standards command 40-60% retail premiums in coastal metropolitan markets.
- Direct-to-Consumer Logistics:Compressed-roll packaging and last-mile partnerships are compressing delivery timelines for online mattress orders.
Industry Challenges
- Polymer Chemist Shortage:Formulation expertise for viscoelastic and high-resilience foams concentrates among retiring baby-boomer technical staff.
- California Proposition 65 Defense:Litigation exposure over chemical warning labels demands dedicated compliance legal spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mattress Market |
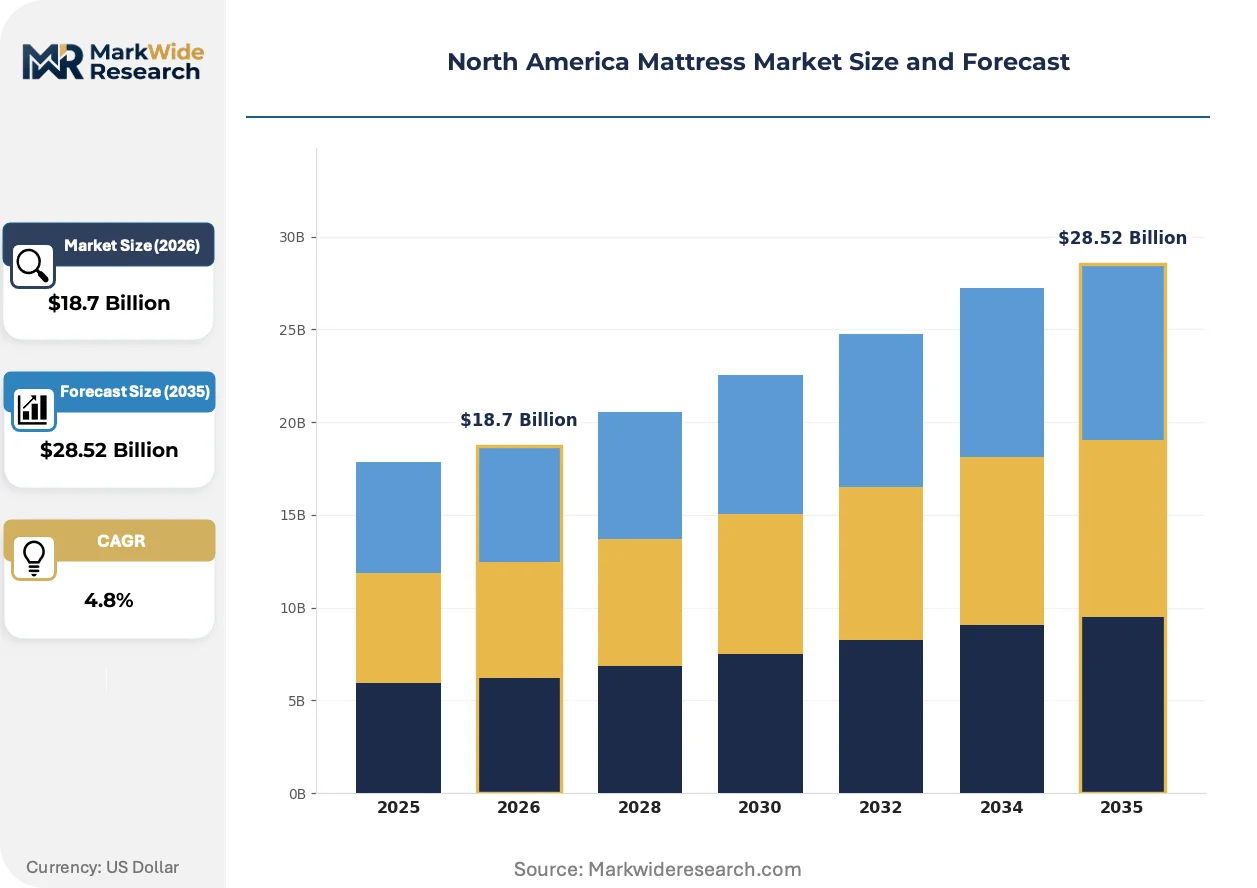
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Price Tier: Premium, Mid-range, Budget, Luxury Distribution Channel: Online Retail, Specialty Stores, Department Stores, Warehouse Clubs End User: Residential, Hospitality, Healthcare, Commercial |
| Companies Covered | Tempur Sealy International, Serta Simmons Bedding, Sleep Number Corporation, Casper Sleep, Kingsdown, Leesa Sleep, Saatva, Spring Air International, Purple Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mattress Market Evolving Landscape
Material science and channel economics are converging to fragment how mattresses are specified, purchased, and delivered across residential and commercial end uses.
Modular mattress architecture is modularizing product design by separating interchangeable comfort layers from standardized support cores. Hospitality procurement teams at major franchise operators are piloting zippered component systems to extend asset life and reduce replacement capex. This architecture is modularizing supplier relationships by decoupling foam specialists from spring manufacturers.
California's Bureau of Electronic and Appliance Repair enforces SB 1019 disclosure requirements for flame retardant chemicals, compelling suppliers to reformulate or label components. Foam producers are shifting to halogen-free barrier fabrics and inherent fiber fire-blocking to preempt liability. The premium residential segment absorbs these material costs most readily, while budget private-label imports face margin compression.
White-glove delivery unbundling is fragmenting the traditional specialty retail value proposition. Online pure-plays now offer removal and setup as à-la-carte services rather than bundled financing attachments. This shift is most visible in secondary metropolitan areas where regional furniture chains lack dedicated mattress logistics infrastructure.
North America Mattress Market Segmentation
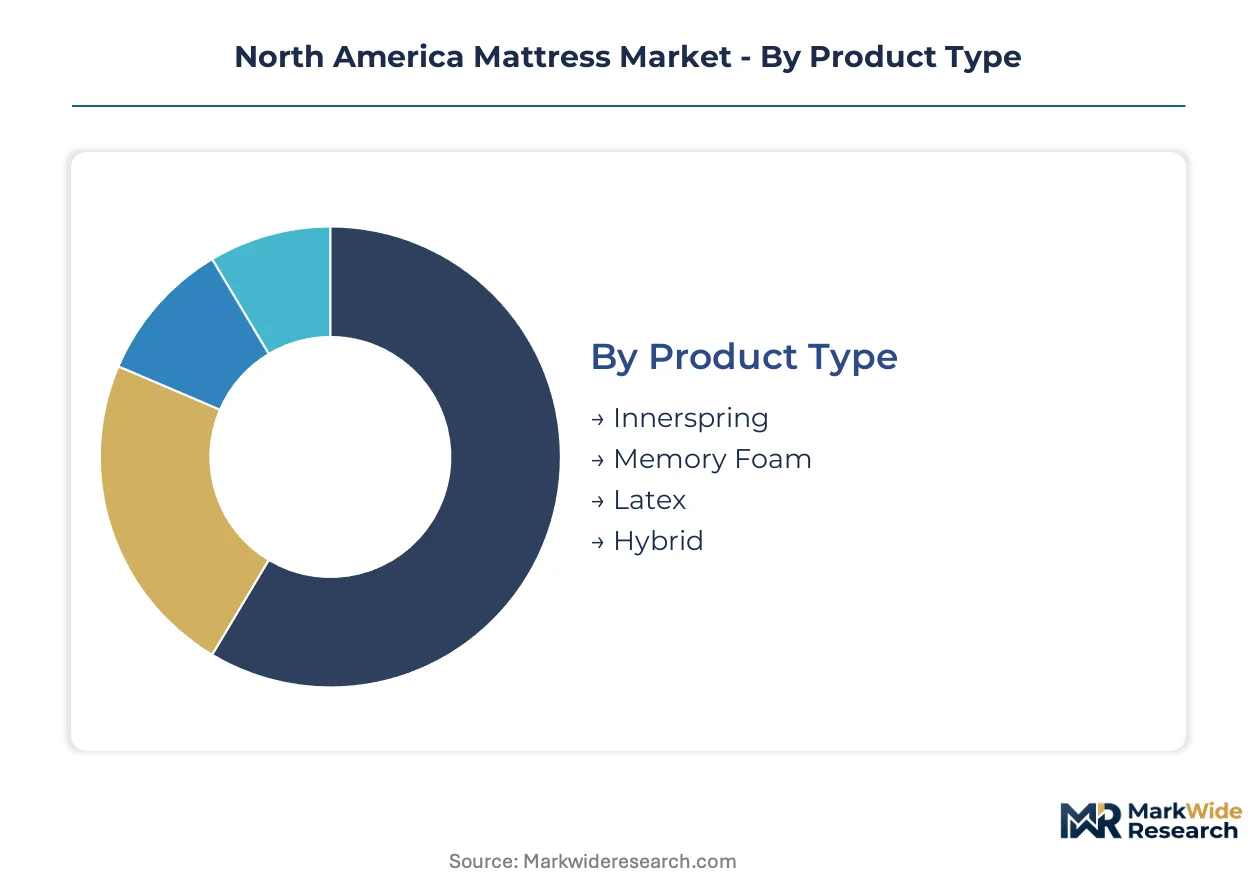
Mattress segmentation in North America reflects divergent capital requirements across manufacturing technologies and channel infrastructure. Foam pouring equipment and coil winding machinery demand distinct asset bases, while distribution economics separate scalable e-commerce from high-touch retail footprints.
Product Type:
Innerspring and hybrid platforms absorb the heaviest upfront tooling investments, with pocketed coil assembly lines requiring precision welding stations and automated quilting systems.
- Innerspring:Steel coil matrices with border rod reinforcement and fiber padding remain the volume backbone. Demand concentrates in the US Midwest and Southeast where replacement cycles drive bulk purchases through warehouse clubs, though coil count specifications face compression from foam alternatives.
- Hybrid:Pocketed coil bases layered with memory foam or latex comfort zones command the highest unit economics. Hospitality procurement in Texas and Florida favors these constructions for durability claims and guest satisfaction metrics.
- Memory Foam:Viscoelastic polyurethane formulations poured in molded slabs dominate online retail with compressed-roll logistics.
- Latex:Dunlop and Talalay processed rubber sap serves certified organic segments in California and Pacific Northwest metropolitan corridors.
Most installed capacity flows through innerspring platforms. Expansion is steepest in hybrid constructions.
Price Tier:
Margin architecture separates segments by material certification burden and white-glove service attachment, with luxury tiers absorbing GOLS and GOTS compliance costs most readily.
- Premium:Gel-infused memory foam and zoned support systems with 10-year warranties anchor specialty store assortments. Demand clusters in Sun Belt states where household formation outpaces national averages and financing penetration runs highest.
- Luxury:Hand-tufted organic latex and adjustable air-chamber systems with biometric tracking defend price points through white-glove delivery and extended trial periods. Coastal California and Northeast corridor markets absorb these units despite housing cost pressures.
- Mid-range:Basic hybrid constructions and private-label memory foam serve mass merchant channels with compressed packaging.
- Budget:Polyurethane block foam and Bonnell coil imports face margin compression from tariff exposure and compressed logistics.
Unit volume concentrates in mid-range tiers. Value expansion is climbing fastest in luxury certified organic segments.
Distribution Channel:
Fulfillment infrastructure requirements fragment this category, with online pure-plays demanding compressed-roll packaging partnerships while specialty stores maintain localized delivery fleets.
- Online Retail:Direct-to-consumer logistics with 100-day trial periods and compressed-roll shipping have redefined customer acquisition economics. Secondary metropolitan areas in Arizona and Nevada show the steepest channel shift as regional furniture chains lack dedicated mattress infrastructure.
- Specialty Stores:White-glove delivery, old mattress removal, and financing attachment sustain margin pools despite showroom cost burdens. Texas and Florida retain the densest specialty store networks aligned with new construction cycles.
- Department Stores:Curated brand boutiques within broader home goods footprints serve suburban replacement demand.
- Warehouse Clubs:Limited SKU depth and bulk pricing target multi-unit residential and institutional buyers.
Customer acquisition spend flows heaviest through online retail. Physical footprint expansion is gaining share fastest in warehouse clubs.
End User:
Contract specification complexity varies sharply, with hospitality procurement demanding flame certification documentation and healthcare requiring pressure-relief clinical validation.
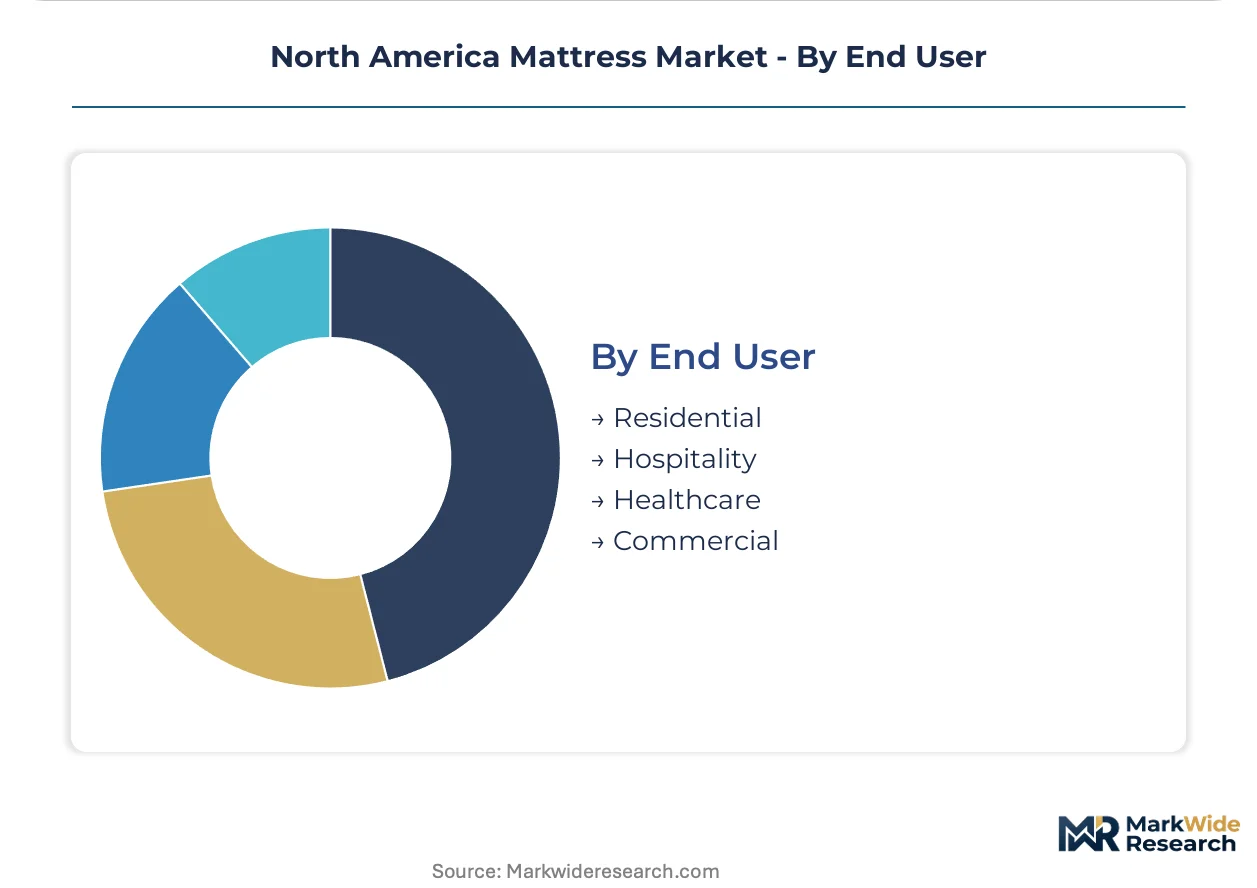
- Residential:Individual household purchases driven by lifecycle replacement and household formation dominate absolute volume. Sun Belt migration into Texas, Florida, and Arizona sustains new construction-linked demand.
- Hospitality:Franchise-standardized sleep programs with bulk replacement schedules and fire barrier compliance anchor institutional procurement. Major hotel chains are consolidating supplier relationships around fewer contract manufacturers with certified testing infrastructure.
- Healthcare:Pressure-mapping validation and antimicrobial ticking serve long-term care and acute care facilities.
- Commercial:Dormitory, military barracks, and correctional facility contracts prioritize durability specifications over comfort layering.
Replacement volume concentrates in residential channels. Procurement consolidation is accelerating most quickly in hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Sun Belt corridor anchors North American mattress demand through residential construction velocity and interstate migration flows. Texas, Florida, and Arizona absorb the majority of new household formation, while regulatory divergence between federal and state jurisdictions reshapes material sourcing economics across production clusters.
United States
Texas and Florida construction cycles drive replacement demand through warehouse club and specialty store channels. The US Consumer Product Safety Commission enforces 16 CFR Part 1633 flammability certification, favoring domestic producers with testing infrastructure. Charlotte, North Carolina hosts concentrated foam pouring and coil assembly operations serving eastern seaboard distribution networks.
California
Coastal metropolitan markets absorb premium organic latex units despite housing cost pressures. The Bureau of Electronic and Appliance Repair administers SB 1019 chemical disclosure mandates, compelling foam reformulation toward halogen-free barrier fabrics. Los Angeles and San Francisco Bay Area retail corridors concentrate certified GOLS and GOTS inventory for health-conscious consumer segments.
Texas
Hospitality procurement in Dallas-Fort Worth and Houston favors hybrid constructions for franchise-standardized sleep programs. State-level extended producer responsibility proposals remain under legislative review, creating compliance uncertainty for recycling infrastructure investment. The I-35 corridor from San Antonio to Austin anchors expanding maquiladora logistics partnerships for tariff-advantaged contract volume.
Florida
Retirement migration and second-home construction sustain replacement cycles across the peninsula. The EPA's TSCA Title VI formaldehyde emission regulations constrain composite wood foundation sourcing from Asian suppliers. Tampa and Orlando distribution hubs coordinate compressed-roll logistics for online retail penetration into secondary southeastern markets.
Canada
Ontario and Quebec manufacturing bases serve domestic replacement demand with limited export orientation. Health Canada and PMRA chemical safety standards align partially with US EPA frameworks, reducing cross-border compliance friction. Toronto and Montreal retail networks emphasize white-glove delivery attachment rates over direct-to-consumer channel shift.
North America Mattress Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers position compressed-roll logistics and nearshored hospitality contract infrastructure. The vendor base separates into three tiers: integrated foam-and-spring producers with certified testing facilities, specialty online pure-plays with direct fulfillment networks, and regional assemblers serving private-label import channels. Strategic archetypes include hospitality contract specialists, certified organic premium positioning, and mass-market volume scale. M&A activity and maquiladora capacity expansion represent the dominant competitive moves as tariff exposure reshapes sourcing decisions.
Among integrated North American producers, Tempur Sealy International and Serta Simmons Bedding exemplify the contract manufacturing archetype with institutional sales infrastructure, while Sleep Number Corporation occupies a position within the adjustable air-chamber premium segment. These three entities represent divergent strategic bets on hospitality procurement consolidation, material science differentiation, and technology-enabled sleep systems respectively.
| Leading Market Players |
|---|
| Tempur Sealy International |
| Serta Simmons Bedding |
| Sleep Number Corporation |
| Casper Sleep |
| Kingsdown |
| Leesa Sleep |
| Saatva |
| Spring Air International |
| Purple Innovation |
| Others |
Value Network & Pricing Analysis
Polyurethane precursor costs originating from Gulf Coast petrochemical complexes flow through foam layer economics into retail price tiers, with TDI and MDI volatility compressing margins most acutely in budget private-label imports while certified organic latex commands absorption capacity at the top end.
Pricing Analysis
Retailer markup layers separate specialty store white-glove bundles from direct-to-consumer discounts, with three-tier pricing structure across premium, standard, and economy levels stratifying by certification burden and delivery service attachment. Price differentiation hinges on GOLS organic certification and compressed-roll logistics capability. Pricing pressure stems from Asian foundation imports exposing distributors to tariff exposure. Budget tiers show highest price sensitivity; luxury segments demonstrate inelastic demand.
Supply Chain Analysis
Certification gating through 16 CFR Part 1633 flammability testing and California SB 1019 chemical disclosure requirements concentrates qualified supply among domestic producers with accredited laboratory infrastructure. Foam pouring capacity clusters in the United States, Mexico, and Canada; coil assembly concentrates in North Carolina and Texas. Raw material dependencies include petroleum-based polyurethane, natural rubber latex, and steel wire rod. Single-source vulnerability runs through concentrated Asian slatted base supply. Distribution runs through hybrid networks blending compressed-roll direct fulfillment with localized white-glove fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America mattress market reads as a late-cycle quality story, with hospitality procurement consolidation and Sun Belt household formation shifting demand toward durable hybrid constructions and certified organic specifications.
For Market Incumbents: Extend certified testing infrastructure investments to preempt extended producer responsibility legislation, while deepening backward integration into foam pouring capacity to offset TDI/MDI volatility. Defend against import competition by leveraging 16 CFR Part 1633 compliance barriers and hospitality contract consolidation trends. For New Entrants and Emerging Players: Enter via modular mattress architecture partnerships with hospitality procurement teams seeking zippered component systems for asset life extension. Target secondary metropolitan areas in Arizona and Nevada where regional furniture chains lack dedicated mattress logistics infrastructure, deploying compressed-roll direct-to-consumer fulfillment with à-la-carte white-glove services. For Investors and Strategic Acquirers: Consolidation pressure builds where maquiladora capacity expansion offers tariff-advantaged export platforms and certified organic certification commands retail premiums. Long-term viability favors integrated foam-and-spring producers with hospitality contract infrastructure over pure-play online retailers facing customer acquisition cost inflation. Watch state-level extended producer responsibility legislation as inflection signal for recycling infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Maquiladora Capacity Expansion | Tariff-advantaged export platforms for US-bound hospitality contract volume reshape competitive economics. |
| Organic Certification Investment | GOLS and GOTS standards defend 40-60% retail premiums in California and Pacific Northwest corridors. |
| Compressed-Roll Logistics Partnership | Last-mile delivery compression enables online retail penetration into secondary metropolitan markets. |
| Modular Architecture Development | Zippered component systems extend hospitality asset life and decouple supplier relationships. |
| Flammability Testing Infrastructure | 16 CFR Part 1633 certification creates compliance barriers favoring domestic producers over imports. |
Research Methodology
Direct dialogue with foam formulation chemists, hospitality procurement directors, specialty store operators, and mattress recycling facility managers grounded qualitative findings, cross-referenced against US EPA TSCA filings, California Bureau of Electronic and Appliance Repair enforcement data, customs import records, and hospitality franchise contract disclosures. Bottom-up unit economics triangulated against top-down construction and migration flow indicators.
Segment-level value outputs across product type, price tier, distribution channel, and end-use dimensions were modeled through the projection horizon, with CAGRs derived from housing starts velocity, replacement cycle assumptions, and channel shift elasticity parameters. Forecast inputs incorporated Sun Belt migration patterns, polyurethane precursor cost indices, and state-level regulatory proposal tracking.
Inputs from hospitality procurement databases and foam producer technical disclosures were available through the study window; gaps in real-time recycling infrastructure cost curves introduce uncertainty bands around extended producer responsibility compliance scenarios. Forecasts reflect documented assumptions regarding tariff stability and petrochemical feedstock pricing. A model refresh is warranted upon material change in California or federal flammability regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bedding Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Japan Mattress Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Latin America Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Bed Wedge Market