
 Luxury Mattress Market | 2026-2036
Luxury Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Mattress Market Outlook
Modular mattress configurations with zippered comfort layers and split firmness zones is hardening as the dominant product architecture. Saatva leverages its vertically integrated domestic manufacturing to control delivery timelines and customization depth. Brooklyn Bedding specializes in hybrid constructions that blend pocketed coils with proprietary foam formulations. Nectar competes through compressed-shipping logistics that reduce last-mile costs without compromising foam density ratings.
A luxury mattress denotes a high-performance sleep system engineered with premium materials such as natural latex, gel-infused memory foam, or tempered steel coils, typically exceeding twelve inches in profile and carrying extended warranty terms. These products serve residential master suites, hospitality properties, and clinical recovery settings where pressure relief and thermal regulation justify price premiums. Hybrid configurations now anchor the fastest-growing product category as consumers reject pure foam heat retention without surrendering motion isolation. Smart mattress features with biometric tracking and automated firmness adjustment concentrate margin pools at the top tier, while innerspring remains the mature volume segment facing gradual displacement.
EPA formaldehyde emission standards and state-level flammability regulations in California govern foam composition and fire barrier chemistry, compelling reformulation investments across domestic supply chains. CertiPUR-US and OEKO-TEX certification programs function as de facto market access filters for premium positioning, particularly among eco-conscious residential buyers. Stakeholders must monitor how evolving chemical disclosure rules and extended producer responsibility frameworks reshape material sourcing economics and brand differentiation pathways.
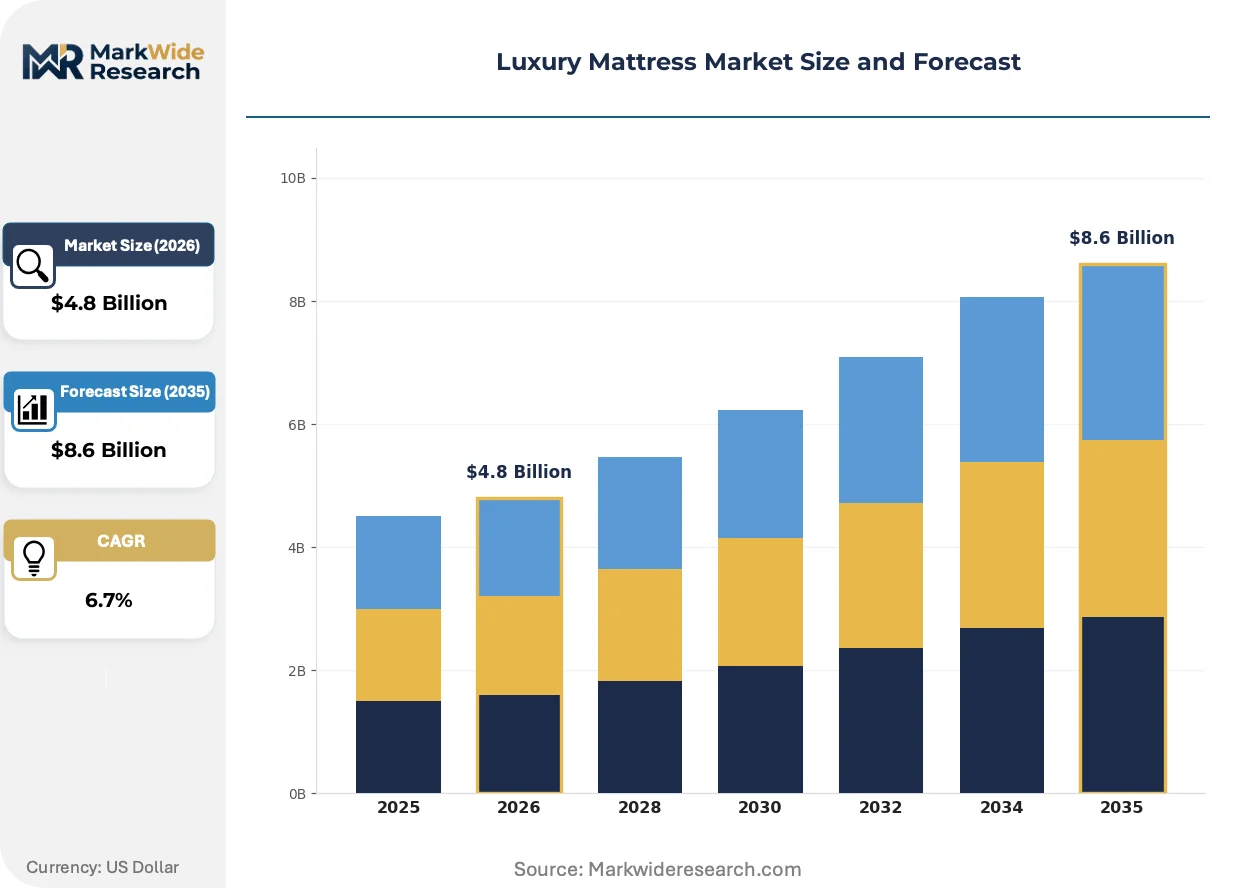
Market Dynamics
Hybrid construction architectures are forcing foam-centric manufacturers to retool production lines or surrender share to coil-foam integrators. The shift compresses margins for pure-play memory foam suppliers while rewarding vertical control over tempered steel sourcing and natural latex procurement.
Growth Catalysts
- REACH chemical restrictions:ECHA's evolving substance restrictions on flame retardants and VOC-emitting adhesives favor European manufacturers with certified clean chemistry pipelines, creating regulatory moats against uncertified imports.
- Hospitality procurement specifications:Boutique hotel chains now mandate 14-inch minimum profiles with zippered comfort layers for asset refresh cycles, pulling premium unit volumes through B2B channels.
- Talalay latex production:Vacuum-sealed continuous-pour latex manufacturing is expanding capacity in Southeast Asian processing hubs, reducing raw material cost volatility for hybrid builders.
Market Restraints
- Natural latex price volatility:Hevea brasiliensis harvest sensitivity to monsoon patterns in Sri Lanka and Thailand injects input cost unpredictability into COGS calculations for botanical foam layers.
- California flammability codes:TB 117-2013 and its successor requirements force reformulation of fire barrier chemistry every 3-5 years, straining R&D budgets without commensurate price recovery mechanisms.
- Compressed foam substitutes: Roll-packed polyurethane mattresses from Southeast Asian exporters compete on last-mile logistics cost, pressuring domestic manufacturers to match shipping economics or surrender entry-luxury positioning.
Strategic Opportunities
- Clinical recovery settings:Post-surgical and chronic pain management facilities represent an underpenetrated end-use vertical where pressure-mapping and zero-gravity positioning justify 40-60% price premiums over residential equivalents.
- Smart mattress convergence:Integration of biometric sleep tracking with automated firmness adjustment creates subscription revenue potential and locks in replacement cycles through software-locked hardware ecosystems.
- Extended producer responsibility frameworks:EU circular economy directives and emerging state-level mattress recycling mandates in California and New York favor manufacturers with established take-back infrastructure and recyclable component design.
Industry Challenges
- CertiPUR-US compliance timelines:Third-party foam certification requires 90-120 day testing windows that delay new product launches and compress seasonal selling windows.
- Coil-foam integration complexity:Hybrid assembly demands precision alignment of pocketed spring units with multiple foam layers, raising defect rates and warranty claim exposure for manufacturers transitioning from single-material platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Mattress Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Hybrid, Latex End User: Residential, Hospitality, Healthcare, Retail Features: Cooling Technology, Adjustable Firmness, Eco-Friendly Materials, Smart Mattress Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | WinkBed, Nolah, Saatva, Leesa, DreamCloud, Nectar, Brooklyn Bedding, Stearns & Foster, Helix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Mattress Market Strategic Shifts
Modular sleep systems are fragmenting the traditional replacement cycle while biometric-enabled products capture recurring revenue streams. These shifts compress brand loyalty windows and redistribute margin pools toward software-integrated hardware.
Zippered comfort layer architectures are decentralizing control over firmness specification from manufacturers to end users. Residential buyers in metropolitan corridors now expect 30-night adjustment periods with component swaps rather than full-unit returns. This modular flexibility is decentralizing inventory risk onto consumers while compressing warranty claim rates for structural defects.
ECHA's expanding REACH substance restrictions on organophosphate flame retardants are compelling reformulation of fire barrier textiles. European manufacturers with OEKO-TEX Standard 100 certification pipelines capture preferential placement in eco-conscious retail channels. California's Bureau of Electronic and Appliance Repair is monitoring these developments for potential adoption, creating transatlantic regulatory convergence pressure on chemical suppliers.
Direct-to-consumer trial periods have compressed from 100 nights to 30-45 nights as logistics costs harden. Hospitality procurement teams now demand white-glove delivery and old-mattress removal as table stakes, forcing pure-play e-commerce brands to build last-mile service partnerships or surrender commercial accounts. This service bundling is most visible in New York, Los Angeles, and London corridor markets where building access constraints favor full-service fulfillment models.
Luxury Mattress Market Segmentation
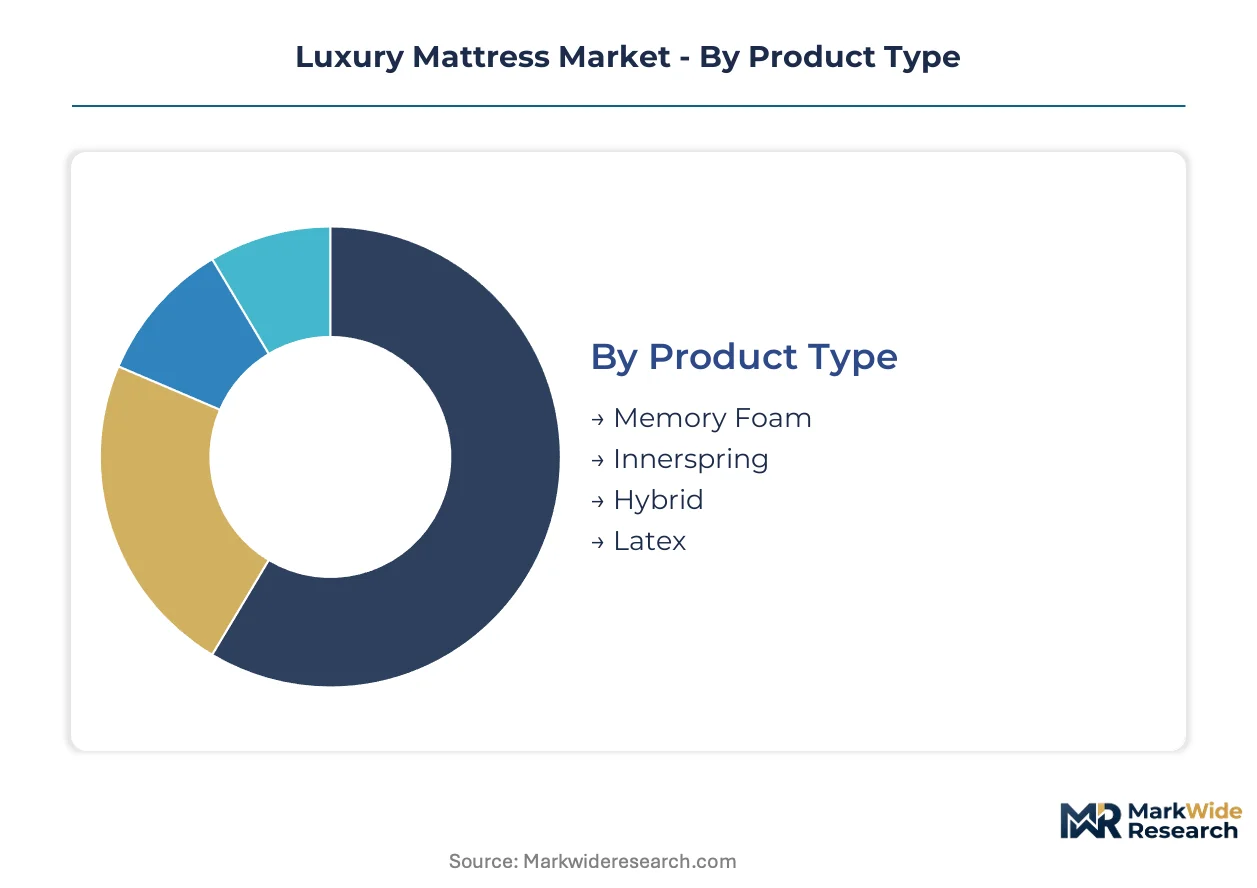
Luxury mattress architectures fragment across material science, end-use requirements, and channel economics. Procurement teams in hospitality and healthcare now specify performance tiers that residential channels rarely match, compressing margin structures for undifferentiated builders.
Product Type:
Standalone sleep systems dominate residential fulfillment, while embedded modular configurations serve hospitality asset-refresh cycles requiring field-replaceable comfort layers.
- Hybrid:Combines pocketed tempered steel coils with gel-infused memory foam or Talalay latex comfort layers. Demand concentrates in United States metropolitan corridors where high-net-worth buyers reject pure-foam heat retention without sacrificing motion isolation.
- Latex:Natural botanical foam derived from Hevea brasiliensis sap, processed via Dunlop or vacuum-sealed continuous-pour methods. Hospitality procurement in California and New York corridor markets specifies 14-inch minimum profiles with zippered covers for extended asset lifecycles.
- Memory Foam:High-density viscoelastic polyurethane with open-cell or gel-infusion architectures for thermal regulation.
- Innerspring:Traditional Bonnell or offset coil systems, now facing displacement as hybrid configurations capture premium positioning.
Volume placements concentrate in Innerspring legacy stock-keeping units; the faster expansion belongs to Hybrid configurations with coil-foam integration.
End User:
Cost tier differentiation separates institutional specification buyers from discretionary residential purchasers, with healthcare and hospitality commanding stricter performance validation.
- Hospitality:Boutique hotel chains mandate white-glove delivery, old-mattress removal, and zippered comfort layers for franchise-standard compliance. Procurement teams in Los Angeles, London, and Dubai corridor markets now require 30-night trial periods with component-swap flexibility rather than full-unit returns.
- Healthcare:Post-surgical and chronic pain management facilities demand pressure-mapping validation and zero-gravity positioning capabilities. Clinical recovery settings in Germany and Switzerland justify 40-60% price premiums over residential equivalents through reimbursable therapeutic claims.
- Residential:Master suite purchases in United States metropolitan corridors, driven by high-net-worth demographic concentration and extended warranty expectations.
- Retail:Floor model exposure and immediate fulfillment for consumers rejecting compressed-shipping logistics.
Residential channels absorb the highest unit volumes; Healthcare applications are climbing the fastest as clinical reimbursement frameworks expand.
Features:
Customer type stratification separates subscription-enabled software buyers from specification-driven procurement teams seeking passive durability.
- Smart Mattress:Biometric sleep tracking with automated firmness adjustment via pneumatic or electromechanical actuators. United States and South Korean early adopters lock replacement cycles through software-locked hardware ecosystems generating recurring subscription revenue.
- Eco-Friendly Materials:OEKO-TEX Standard 100 certified textiles and CertiPUR-US validated foam chemistry. European Union markets under REACH substance restrictions favor manufacturers with clean-chemistry pipelines, creating regulatory moats against uncertified imports.
- Cooling Technology:Phase-change materials, copper-infused foams, or graphite-distributed thermal conductors.
- Adjustable Firmness:Manual air chambers or modular foam inserts enabling end-user customization without full-unit replacement.
Cooling Technology commands the broadest placement across price tiers; Smart Mattress features are gaining share fastest through hardware-software convergence.
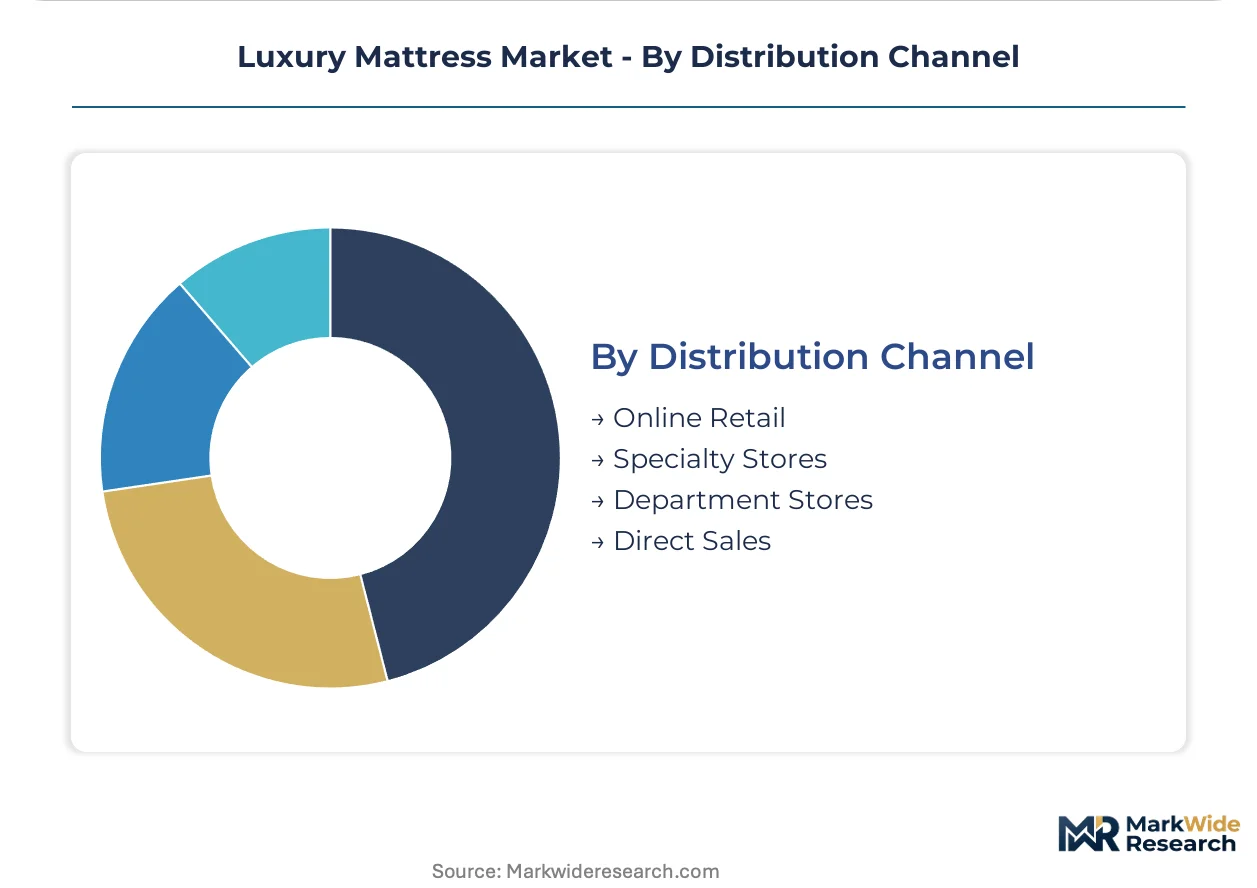
Distribution Channel:
Margin structure varies sharply between logistics-heavy direct fulfillment and service-bundled specialty retail, with geography dictating viable channel economics.
- Specialty Stores:White-glove delivery, old-mattress removal, and pressure-mapping consultation services. New York and Los Angeles building-access constraints favor full-service fulfillment models that pure-play e-commerce brands struggle to replicate without partnership investments.
- Online Retail:Compressed-shipping logistics reducing last-mile costs, now compressed to 30-45 night trial periods as return logistics harden.
- Direct Sales:Manufacturer-controlled fulfillment enabling customization depth and delivery timeline compression.
- Department Stores:Legacy foot traffic exposure with declining mattress category investment.
Online Retail processes the highest transaction velocity; Specialty Stores are expanding most quickly as service bundling becomes table stakes for hospitality accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the UAE and Singapore's Jurong Innovation District concentrate luxury mattress assembly and regional distribution hubs serving high-net-worth corridors across Asia-Pacific and Middle Eastern markets.
United States
Metropolitan corridors in New York, Los Angeles, and Chicago drive residential demand among high-net-worth buyers seeking 14-inch hybrid profiles with zippered comfort layers. EPA formaldehyde emission standards and California's TB 117-2013 flammability codes govern foam composition and fire barrier chemistry. The Pacific Northwest cluster around Seattle anchors sustainable material innovation, with manufacturers integrating CertiPUR-US certified foams for eco-conscious West Coast consumers.
Germany
Clinical recovery facilities in Munich and Hamburg justify 40-60% price premiums for pressure-mapping and zero-gravity positioning capabilities. ECHA's REACH substance restrictions on organophosphate flame retardants favor domestic manufacturers with OEKO-TEX Standard 100 certification pipelines. The Baden-Württemberg industrial corridor hosts precision coil-foam integrators supplying boutique hotel chains across Central Europe with modular sleep systems.
United Kingdom
London's luxury residential market and hospitality procurement teams mandate white-glove delivery with old-mattress removal as standard service terms. The UK Environment Agency's emerging extended producer responsibility frameworks for mattress recycling favor manufacturers with established take-back infrastructure. The Greater Manchester manufacturing cluster specializes in Talalay latex processing for hospitality accounts requiring field-replaceable comfort layers.
China
Yangtze River Delta metropolitan zones in Shanghai and Hangzhou concentrate demand for smart mattresses with biometric sleep tracking and automated firmness adjustment. GB standards for indoor air quality and VOC emissions shape foam chemistry specifications for domestic premium positioning. The Pearl River Delta assembly corridor exports compressed-shipping hybrid configurations to Southeast Asian hospitality markets seeking cost-optimized logistics.
United Arab Emirates
Dubai's luxury hospitality sector and high-net-worth residential towers in Abu Dhabi specify 14-inch minimum profiles with cooling technology integration. The UAE's Ministry of Climate Change and Environment monitors EU REACH developments for potential chemical disclosure rule adoption. Jebel Ali Free Zone hosts regional distribution centers for European and Asian manufacturers serving Gulf Cooperation Council markets with white-glove fulfillment capabilities.
Luxury Mattress Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered positioning bands. The vendor base separates into three strategic archetypes: vertically integrated domestic manufacturers controlling delivery timelines, compressed-shipping logistics specialists optimizing last-mile economics, and hybrid construction integrators blending coil and foam technologies. Competitive moves concentrate on strategic partnerships with hospitality procurement teams and portfolio diversification into smart mattress subscription ecosystems.
Within the vertically integrated tier, Saatva anchors domestic manufacturing control while Brooklyn Bedding exemplifies hybrid construction specialization. Nectar occupies a position representing compressed-shipping logistics optimization. These three entities collectively illustrate the competitive tension between customization depth, material integration complexity, and fulfillment economics that defines current market positioning.
| Leading Market Players |
|---|
| WinkBed |
| Nolah |
| Saatva |
| Leesa |
| DreamCloud |
| Nectar |
| Brooklyn Bedding |
| Stearns & Foster |
| Helix |
| Others |
Value Chain & Pricing Dynamics
California's TB 117-2013 flammability mandates gate qualified supply and premium-tier pricing access, compelling manufacturers to absorb reformulation costs or surrender positioning to certified competitors with established clean-chemistry pipelines.
Pricing Analysis
Margin tightening in entry-luxury tiers reflects compressed trial periods and elevated return logistics costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and white-glove service bundling. Hospitality procurement teams in corridor markets exhibit lowest price sensitivity, while direct-to-consumer residential buyers demand 30-night component-swap flexibility without premium surcharges. Cost-down pressure on hybrid configurations accelerates because Southeast Asian roll-packed substitutes match domestic shipping economics.
Supply Chain Analysis
Natural latex supply rests on Sri Lankan and Thai Hevea brasiliensis plantations, with vacuum-sealed continuous-pour processing expanding in Southeast Asian hubs. Tempered steel coil feedstock draws from domestic foundries, while gel-infused memory foam chemistry sources from certified polyurethane producers. Single-source vulnerability concentrates in botanical latex harvests exposed to monsoon disruption. Distribution runs through white-glove specialty retail partnerships in building-constrained corridor markets alongside compressed-shipping direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions and state-level flammability code convergence force consolidation, eliminating uncertified foam suppliers unable to sustain 90-120 day certification timelines.
For Market Incumbents: To counter Southeast Asian roll-packed substitutes, deepen captive supply of Talalay latex through Southeast Asian processing partnerships and secure OEKO-TEX Standard 100 certification pipelines ahead of ECHA substance restriction expansions. Control last-mile service partnerships in New York and Los Angeles corridor markets where building access constraints favor full-service fulfillment. For New Entrants and Emerging Players: Biometric sleep tracking with automated firmness adjustment offers technology-first wedge into clinical recovery settings in Germany and Switzerland, where reimbursable therapeutic claims justify 40-60% price premiums over residential equivalents. Target post-surgical facilities with pressure-mapping validation requirements and zero-gravity positioning capabilities as the most penetrable healthcare vertical. For Investors and Strategic Acquirers: Boutique hotel chain procurement teams mandating 14-inch minimum profiles with zippered comfort layers is the leading indicator that modular sleep system specialists with established hospitality B2B channels will command acquisition premiums. Focus on vertically integrated domestic manufacturers controlling delivery timelines and customization depth rather than pure-play compressed-shipping logistics operators facing margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Mattress Platform Integration | Biometric tracking with automated firmness adjustment locks replacement cycles through software-locked hardware ecosystems generating recurring subscription revenue. |
| Backward Integration into Latex Processing | Vacuum-sealed continuous-pour capacity in Southeast Asian hubs reduces raw material cost volatility for hybrid builders dependent on Hevea brasiliensis supply. |
| Certification Pipeline Investment | OEKO-TEX Standard 100 and CertiPUR-US validation creates regulatory moats against uncertified imports under ECHA REACH substance restrictions. |
| White-Glove Service Partnership | Full-service fulfillment with old-mattress removal captures hospitality procurement in New York, Los Angeles, and London corridor markets with building access constraints. |
| Clinical Recovery Vertical Expansion | Pressure-mapping validation and zero-gravity positioning capabilities access reimbursable therapeutic claims in German and Swiss post-surgical facilities. |
Study Parameters
Document review covered regulatory filings with EPA and ECHA, hospitality procurement specifications, and foam chemistry certification databases, complemented by interviews with mattress manufacturing executives, boutique hotel procurement directors, specialty retail channel partners, and clinical facility purchasing managers. Secondary validation drew from customs trade records, SEC 10-K disclosures of diversified conglomerates, and CertiPUR-US certification registries. Bottom-up demand modeling across end-use segments triangulated against top-down value chain analysis.
Historical shipment data cross-referenced against panel input from industry stakeholders established baseline trajectories across the projection horizon. Segmentation dimensions modeled include product architecture, end-use vertical, distribution channel, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating hospitality asset refresh cycles and residential replacement patterns. Forecast inputs included Hevea brasiliensis harvest variability indices and state-level flammability code amendment timelines.
Several conditions sit outside the modeled scope, including unannounced ECHA substance restriction expansions, California Bureau of Electronic and Appliance Repair rule adoptions, and extended producer responsibility framework implementations in New York. Forecasts reflect assumptions around certification timeline stability and latex harvest normalization. A small set of named triggers warrants ongoing watch: REACH flame retardant amendments, boutique hotel chain bankruptcy filings, and Southeast Asian logistics cost shocks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Bed Formers Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Bed Wedge Market
Bedroom Furniture
Comforter Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
North America Wall Bed Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Home Bedding Market