
 Australia Mattress Market | 2026-2036
Australia Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Mattress Market Outlook
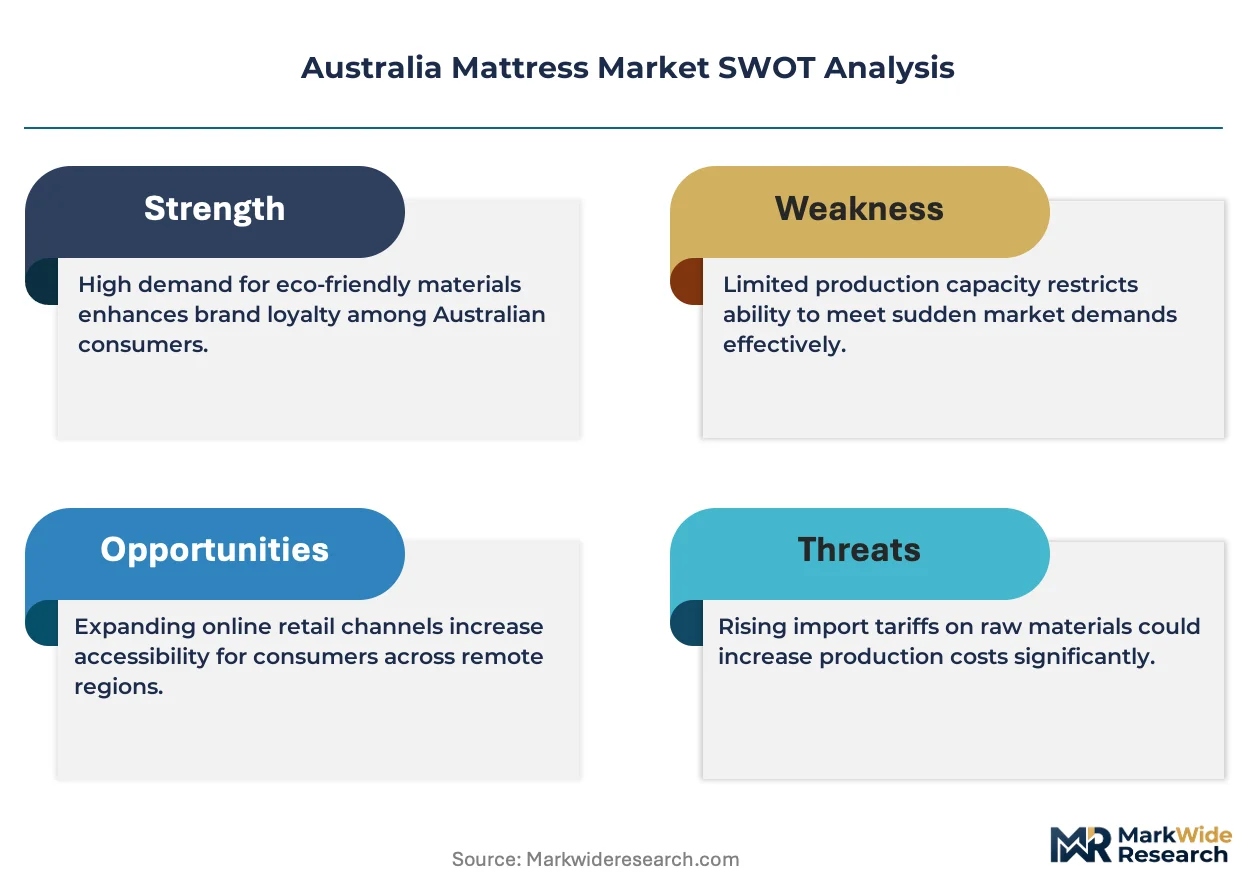
Skilled upholstery labor availability is rotating toward constraint as domestic foam-cutting and quilting technician pipelines thin across regional Victoria and Queensland. A.H. Beard leverages its Brisbane manufacturing footprint to sustain vertical control over spring assembly and final quilting operations. SleepMaker competes through specialized hospital and aged-care contract channels that anchor recurring institutional volume. Koala dominates the direct-to-consumer segment by controlling its Sydney-based logistics network and same-day delivery promise.
A mattress is a padded, fabric-topped sleep support system constructed with a steel innerspring core, polyurethane or viscoelastic foam comfort layers, and a quilted textile cover, designed to distribute body weight and maintain spinal alignment during rest. Innerspring units remain the mature volume base across Australian retail, though hybrid constructions combining pocketed coils with gel-infused memory foam are capturing margin-rich replacement cycles. Online retail is accelerating fastest among distribution channels as mattress-in-a-box logistics compress delivery costs, while specialty stores still occupy the premium consultation layer where queen and king sizes concentrate average transaction value.
TGA product safety standards govern flammability and chemical emissions for polyurethane foam components, compelling manufacturers to reformulate adhesives and fire retardants. The ACCC mandatory reporting framework shapes recall exposure and warranty claim transparency across all price tiers. Standards Australia AS/NZS 8811.1 infant mattress protocols extend compliance obligations into adjacent nursery product lines. Stakeholders must monitor how proposed national circular economy regulations will mandate foam recycling take-back schemes and reshape end-of-life cost structures.
Market Dynamics
The Australia mattress market is tightening around TGA-aligned foam certification standards that are forcing nationwide reformulation of adhesives and fire retardants, compressing margins for manufacturers dependent on legacy chemical inputs while creating compliance moats for early certifiers.
Growth Catalysts
- Urban density concentration:Victoria and New South Wales population clusters support economically viable same-day delivery logistics for direct-to-consumer mattress-in-a-box models.
- AS/NZS 8811.1 infant mattress protocols:Mandatory safety standards for nursery products extend compliance-driven replacement cycles into adjacent product lines.
- Boutique hotel renovation wave:Melbourne and Sydney hospitality procurement is accelerating premium mattress replacement schedules.
Market Restraints
- Polyol and isocyanate cost volatility:Imported polyurethane foam precursors expose Australian manufacturers to freight and currency fluctuation risk.
- Regional Victoria and Queensland labor thinning:Domestic foam-cutting and quilting technician pipelines are constraining production scaling.
- ACCC mandatory reporting framework:Recall exposure and warranty claim transparency requirements elevate legal and reputational liability across all price tiers.
Strategic Opportunities
- Proposed national circular economy regulations:Pending foam recycling take-back mandates will reshape end-of-life cost structures and create first-mover advantages for certified recyclers.
- Aged-care contract anchoring:Institutional recurring volume in hospital and residential care segments offers counter-cyclical revenue stability.
- Hybrid construction convergence:Pocketed coil and gel-infused memory foam combinations are capturing margin-rich replacement demand from pure innerspring owners.
Industry Challenges
- Skilled upholstery technician scarcity:Regional training program gaps are lengthening onboarding timelines for foam-cutting and quilting operations.
- Multi-standard certification complexity:Simultaneous TGA flammability, chemical emissions, and AS/NZS infant protocol compliance extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Mattress Market |
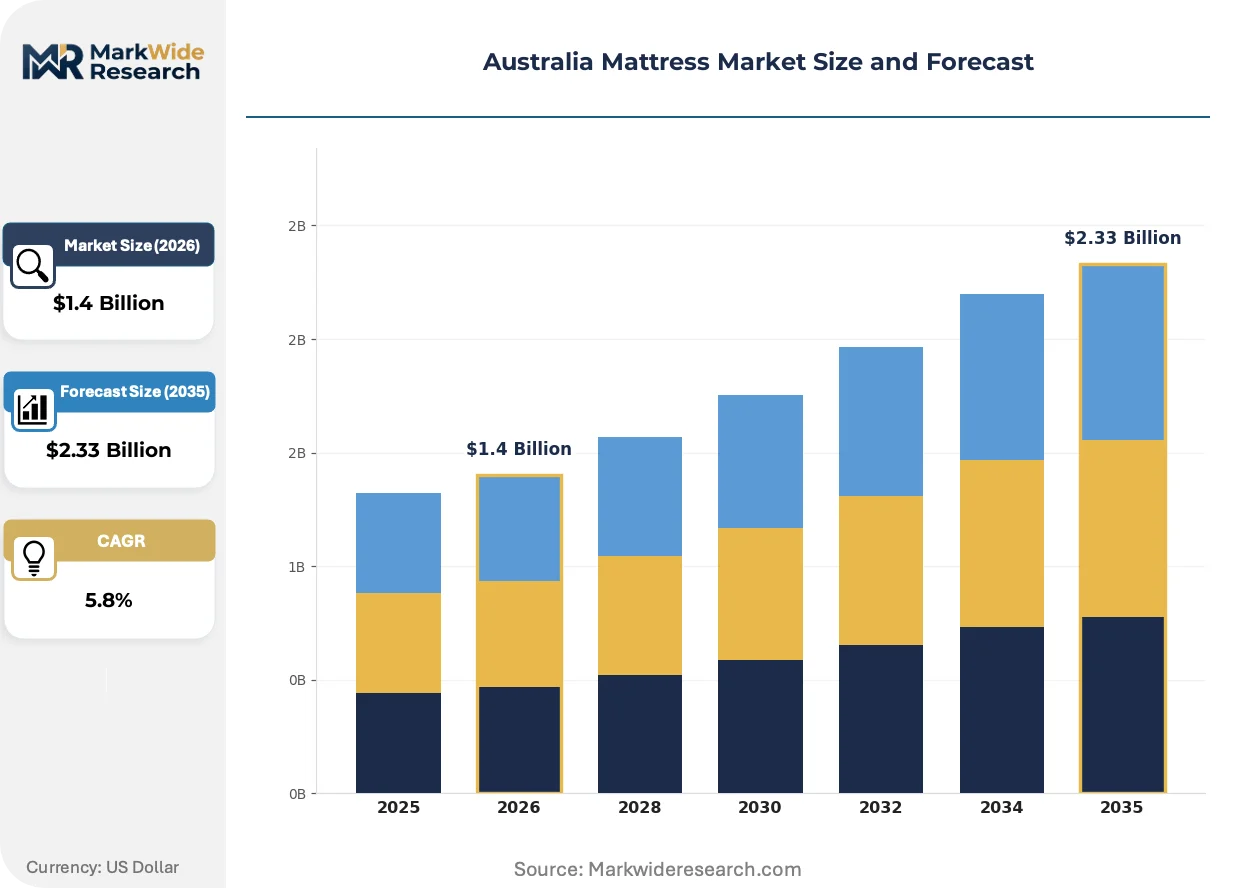
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Size: Single, King Single, Double, Queen, King Distribution Channel: Online Retail, Specialty Stores, Department Stores, Warehouse Clubs Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Sealy of Australia, A.H. Beard, SleepMaker, Sleepyhead, Koala, Tempur Australia, Ecosa, Sleeping Duck, Emma Sleep, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Mattress Market Strategic Shifts
Product architecture and distribution logistics are diverging sharply as compressed-pack mattress-in-a-box logistics compress last-mile costs while hybrid material stacks capture premium positioning.
Gel-infused viscoelastic foam layers are displacing conventional polyurethane comfort layers in mid-to-premium retail tiers. Sydney and Melbourne direct-to-consumer brands are adopting this construction fastest, compressing traditional innerspring-only average selling prices while expanding margin capture on replacement cycles.
TGA product safety standards governing flammability and chemical emissions are compelling adhesive and fire-retardant reformulation across domestic manufacturing. Brisbane-based vertically integrated producers are responding fastest, while import-dependent distributors face extended compliance timelines and inventory write-down risk.
Same-day delivery promises are consolidating buyer preference around Sydney-based logistics networks that control urban fulfillment density. Boutique hotel procurement teams and residential consumers are both compressing purchase consideration windows, forcing specialty retailers to unbundle in-store consultation from fulfillment or cede volume to online channels.
Australia Mattress Market Segmentation
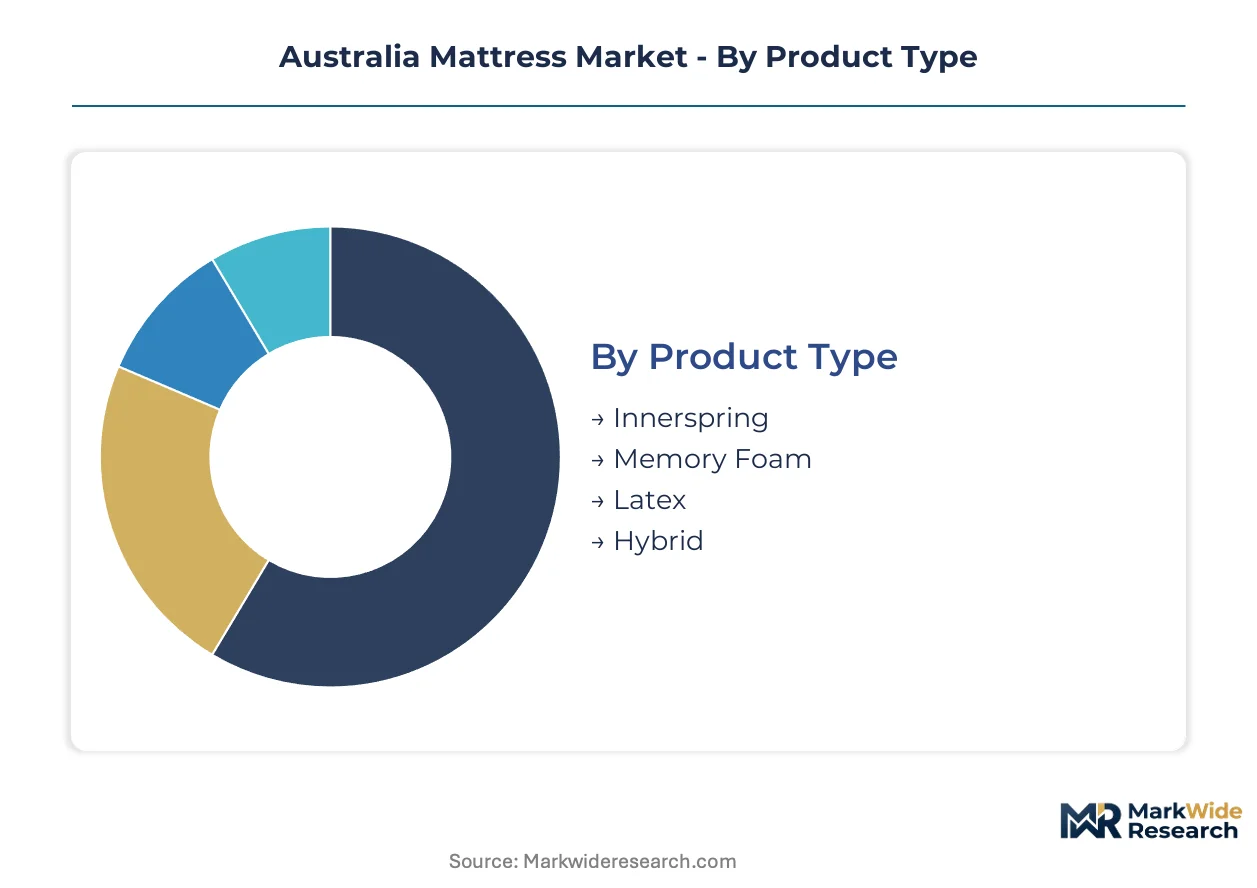
Mattress segmentation in Australia tracks divergent margin economics across construction technologies and fulfillment models. TGA compliance costs and logistics density create distinct competitive arenas where premium hybrid constructions and direct-to-consumer channels capture disproportionate value.
Product Type:
Margin pools concentrate in hybrid constructions that command replacement premiums from aging innerspring owners, while pure foam categories face chemical reformulation cost pressure under tightening TGA emissions standards.
- Innerspring:Steel coil core systems with Bonnell or pocketed spring configurations remain the volume foundation across Australian retail. Victoria and New South Wales specialty stores anchor this segment's average transaction value through queen and king size concentration, though margin compression intensifies as hybrid alternatives capture replacement demand.
- Hybrid:Pocketed coil bases layered with gel-infused memory foam comfort stacks are climbing fastest in Sydney and Melbourne direct-to-consumer channels. Boutique hotel renovation procurement across these cities favors this construction for durability-warranty alignment, creating institutional volume anchors.
- Memory Foam:Viscoelastic polyurethane formulations face TGA chemical emissions recertification timelines that extend product development cycles.
- Latex:Natural rubber derivatives occupy niche positioning with limited domestic manufacturing capacity.
Innerspring holds installed capacity. Hybrid is rotating up the share rankings.
Size:
Customer type determines dimensional demand, with residential couples driving premium surface area upgrades and institutional buyers standardizing on mid-tier formats for operational efficiency.
- Queen:The dominant residential format for coupled households captures the highest average transaction value in specialty retail consultation environments. Melbourne and Sydney urban density supports same-day delivery logistics for this segment's compressed-pack formats, consolidating direct-to-consumer preference.
- King:Expanded surface dimensions command premium positioning in master bedroom renovations across New South Wales and Victoria metropolitan fringes. Aged-care contract channels increasingly specify king-single variants for bariatric accommodation, extending institutional demand.
- Double:Compact coupled format concentrates in entry-level replacement cycles and guest room applications.
- Single:Standardized dimensions dominate hostel, student accommodation, and institutional procurement.
- King Single:Extended length variant captures adolescent growth transitions and tall demographic residential demand.
Queen maintains volume leadership. King is gaining share fastest among residential upgraders.
Distribution Channel:
Cost tier stratification runs through fulfillment economics, where last-mile compression enables online challengers to undercut specialty retail overhead while warehouse clubs capture price-sensitive bulk volume.
- Online Retail:Mattress-in-a-box logistics with compressed vacuum packaging slash delivery costs and enable same-day fulfillment promises across Sydney and Melbourne urban cores. Koala's captive logistics network demonstrates how vertical control over fulfillment creates preference consolidation.
- Specialty Stores:In-person consultation environments with lie-test facilities maintain premium positioning for queen and king size transactions. Melbourne and Sydney showroom concentration supports hospitality procurement teams requiring bulk specification review.
- Department Stores:Mid-range brand aggregation captures browsing traffic with limited technical consultation depth.
- Warehouse Clubs:Bulk packaging and membership pricing structures concentrate budget-tier volume in suburban fringe locations.
Specialty stores hold premium transaction value. Online retail is expanding most quickly in metropolitan fulfillment zones.
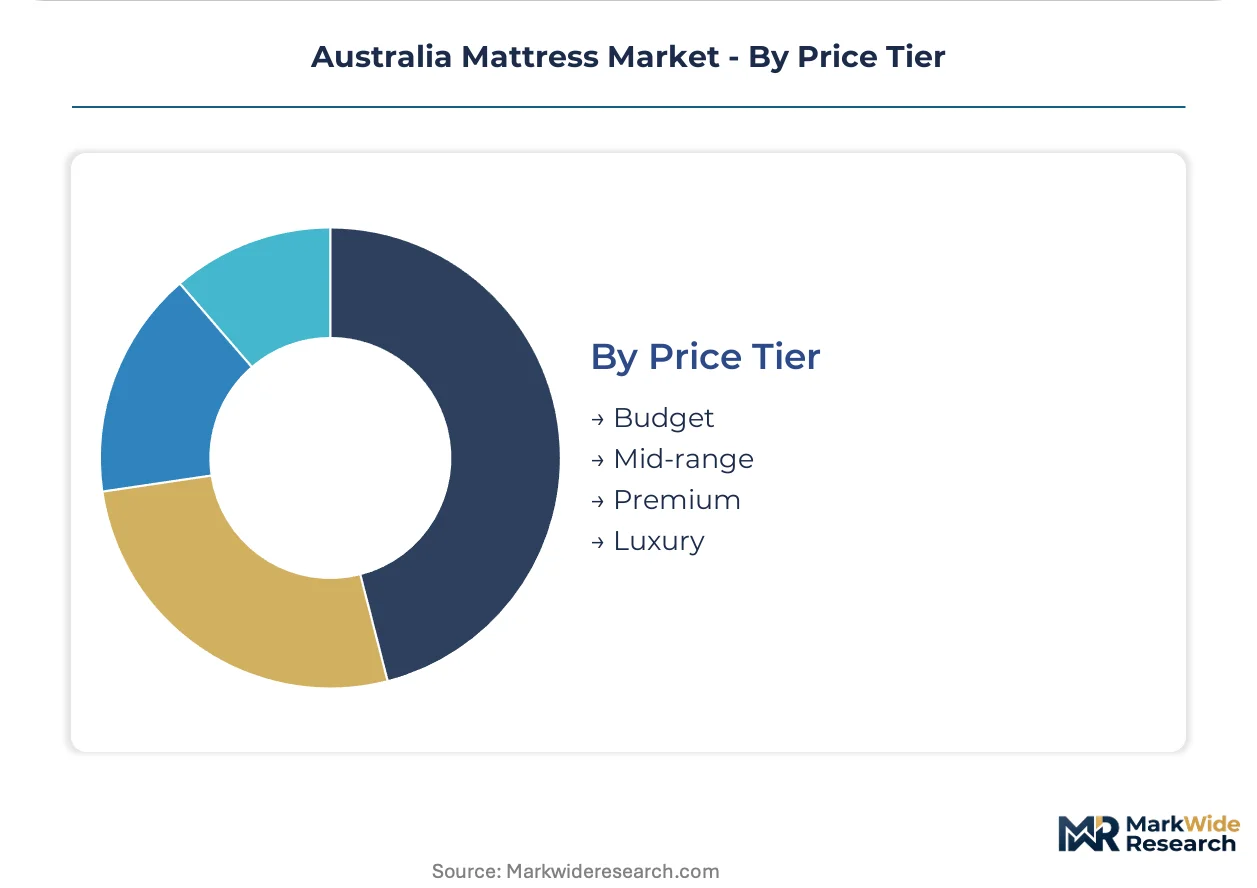
Price Tier:
Maturity gradients separate entrenched budget competition from emerging luxury positioning, where certification storytelling and material provenance command sustained margin premiums.
- Premium:Hybrid constructions with TGA-certified foam components and extended warranty terms capture replacement cycles from quality-conscious upgraders. Sydney and Melbourne direct-to-consumer brands dominate this tier through controlled logistics and review aggregation.
- Mid-range:Standardized innerspring and entry-memory foam configurations balance durability claims with accessible price points for first-time buyers.
- Budget:Basic Bonnell spring and conventional polyurethane constructions face margin compression from import cost volatility and ACCC warranty transparency requirements.
- Luxury:Natural latex, hand-tufted covers, and Australian-made certification command niche positioning with limited volume scale.
Mid-range holds household penetration depth. Premium is climbing fastest in replacement-driven metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mattress demand concentrates in coastal metropolitan corridors where urban density enables compressed-pack logistics, while interior regions rely on specialty retail networks with extended delivery windows. Victoria and New South Wales generate disproportionate replacement volume through renovation-driven household formation.
New South Wales
Sydney's same-day delivery infrastructure anchors direct-to-consumer fulfillment for mattress-in-a-box operators. TGA chemical emissions standards govern foam certification for products entering the state through Port Botany import channels. The Greater Sydney metropolitan fringe drives king-size premium upgrades in master bedroom renovations.
Victoria
Melbourne's boutique hotel renovation wave accelerates institutional procurement for hybrid constructions with extended warranty terms. AS/NZS 8811.1 infant mattress protocols extend compliance obligations into nursery product lines sold through Melbourne retail channels. Regional Victoria faces skilled upholstery technician scarcity as foam-cutting training programs thin.
Queensland
Brisbane-based vertically integrated manufacturers sustain captive spring assembly and quilting operations. The state's hospitality procurement concentrates on Gold Coast resort refurbishments with standardized queen-format specifications. TGA-aligned adhesive reformulation timelines compress margins for import-dependent distributors serving Queensland markets.
Western Australia
Perth's geographic isolation from eastern manufacturing centers elevates freight costs for compressed-pack deliveries. The state's mining sector generates transient workforce demand for single and king-single mattress formats in fly-in-fly-out accommodation. ACCC mandatory reporting requirements shape warranty claim transparency for products distributed through Perth specialty retail.
South Australia
Adelaide's manufacturing base captures mid-range innerspring volume through warehouse club distribution. The state's aged-care contract channels standardize on king-single variants for bariatric accommodation. Proposed national circular economy regulations will mandate foam recycling take-back schemes affecting South Australian end-of-life cost structures.
Australia Mattress Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturers controlling captive spring assembly against import-dependent distributors facing extended compliance timelines. The market structure tilts toward vertical integration in Brisbane and Sydney logistics corridors while fragmenting across regional specialty retail. Three archetypes dominate: vertically integrated domestic producers, direct-to-consumer logistics operators, and import-reliant brand aggregators. Capacity expansion in compressed-pack fulfillment and strategic partnerships with hospitality procurement teams represent the dominant competitive vectors.
Among domestic integrated manufacturers, A.H. Beard anchors the vertically controlled production archetype through its Brisbane manufacturing footprint. SleepMaker occupies a position within the institutional contract channel, exemplifying recurring revenue stability in hospital and aged-care segments. Koala represents the direct-to-consumer logistics archetype through its Sydney-based fulfillment network and same-day delivery infrastructure.
| Leading Market Players |
|---|
| Sealy of Australia |
| A.H. Beard |
| SleepMaker |
| Sleepyhead |
| Koala |
| Tempur Australia |
| Ecosa |
| Sleeping Duck |
| Emma Sleep |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Queensland spring manufacturers and Sydney direct-to-consumer brands lock in foam supply access and price visibility across volatile polyol and isocyanate import cycles. TGA-aligned adhesive reformulation timelines compress negotiation windows as certifiers command premium positioning.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Brisbane vertically integrated producers and institutional hospitality buyers, while spot purchasing concentrates among import-dependent distributors facing currency fluctuation exposure. Price differentiation rests on TGA certification tier and urban logistics density, with Sydney same-day delivery networks capturing premium-mid-economy pricing stratification. Cost compression in budget-tier Bonnell spring configurations is intensifying because ACCC warranty transparency requirements elevate compliance overhead. Hostel and student accommodation procurement teams exhibit highest price sensitivity; boutique hotel renovation committees demonstrate lowest sensitivity due to durability-warranty alignment priorities.
Supply Chain Analysis
Inventory lead times for gel-infused viscoelastic foam layers stretch when TGA emissions recertification delays Chinese and Malaysian chemical precursor shipments. Geographic supply concentration centers on China for polyurethane foam precursors, Malaysia for viscoelastic chemical inputs, and domestic Queensland for steel spring coil fabrication. Raw material dependencies hinge on polyol formulations, isocyanate hardeners, and Australian-sourced steel wire. Single-source vulnerability runs through Port Botany import channels for compressed-pack vacuum machinery. Distribution runs through Sydney and Melbourne urban fulfillment networks for direct-to-consumer channels, with regional specialty retail maintaining extended delivery windows across interior states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from mattress-in-a-box logistics operators capturing metropolitan replacement cycles through compressed-pack economics and same-day delivery infrastructure.
For Market Incumbents: Compound defensive positioning by securing captive foam-cutting technician pipelines through regional Victoria training partnerships before labor scarcity deepens. Anchor recurring revenue through aged-care contract standardization on king-single bariatric specifications. TGA early-certification investment creates compliance moats against import-dependent distributors facing extended reformulation timelines.
For New Entrants and Emerging Players: Lead with circular economy certification as hospitality procurement teams in Melbourne and Sydney prioritize sustainability storytelling for boutique hotel renovations. Target Western Australia mining fly-in-fly-out accommodation for single and king-single format penetration where freight cost isolation weakens incumbent logistics advantage. Deploy direct-to-consumer same-day delivery promises in Perth metropolitan fringe to compress consideration windows.
For Investors and Strategic Acquirers: Brisbane-based vertically integrated manufacturers with captive spring assembly and in-house quilting operations represent the priority acquisition archetype for supply chain control in TGA-tightening environments. Long-term viability hinges on circular economy regulation preparedness across foam recycling take-back infrastructure. Watch pending national circular economy legislation passage as inflection indicator for end-of-life cost structure reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Early Certification Investment | Creates compliance moats against import-dependent distributors facing extended adhesive reformulation timelines. |
| Circular Economy Infrastructure Buildout | Positions certified recyclers for first-mover advantage under pending national foam take-back mandates. |
| Direct-to-Consumer Logistics Expansion | Koala's Sydney fulfillment network demonstrates how urban density control compresses last-mile delivery costs. |
| Institutional Contract Anchoring | SleepMaker's hospital and aged-care channels illustrate counter-cyclical revenue stability through recurring volume. |
| Hybrid Construction R&D Investment | Pocketed coil and gel-infused memory foam combinations capture margin-rich replacement demand from pure innerspring owners. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with mattress manufacturing plant managers, hospitality procurement directors, aged-care facility purchasing committees, and direct-to-consumer logistics operators; and secondary validation through TGA regulatory filings, ACCC mandatory reporting disclosures, Standards Australia AS/NZS protocol documentation, and customs import records for polyurethane foam precursors. Bottom-up segment sizing triangulated against top-down market value reconstruction across product type, size, distribution channel, and price tier dimensions.
The forecasting boundary spans the analysis window with projections derived from replacement cycle modeling, urban density logistics viability thresholds, and regulatory compliance cost trajectories. Segmentation dimensions include construction technology, dimensional format, fulfillment channel, and certification tier. CAGRs were computed from installed base depreciation rates and household formation patterns in Victoria and New South Wales metropolitan corridors. Industry-specific inputs incorporated boutique hotel renovation pipelines and skilled upholstery technician training program enrollment trends.
The analysis sits within stated boundaries; outcomes outside TGA regulatory timeline assumptions or polyol cost volatility parameters would require recalibration. Forecasts reflect documented assumptions regarding circular economy legislation progression and regional labor pipeline restoration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Bed Head Panel Market
Bedroom Furniture
Brazil Mattress Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Malaysia Pillow Market
Bedroom Furniture
Adjustable Beds and Mattress Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
US Wall Beds Market
Bedroom Furniture
Closets, Nightstands, and Dressers Market
Bedroom Furniture
Canopy Beds Market
Bedroom Furniture
United Kingdom Mattress Market
Bedroom Furniture
Bedding Market