
 Latin America Mattress Market | 2026-2036
Latin America Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Mattress Market Foresight
Specialty store networks across Latin America are reshaping how mattress brands reach middle-class consumers. Tempur Sealy International leverages its premium foam technology to anchor positioning in Mexico's urban centers. Serta Simmons Bedding sustains broad retail coverage through partnerships with regional department store chains. Zinus competes aggressively on compressed-pack logistics, lowering last-mile costs for e-commerce fulfillment.
A mattress is a padded, fabric-encased sleep support system constructed from steel coils, polyurethane or memory foam, latex rubber, or layered hybrid combinations, designed to provide ergonomic spinal alignment and pressure relief for residential or commercial sleeping applications. Innerspring units remain the volume backbone across Latin America due to lower unit costs and familiar consumer preferences, though hybrid constructions are gaining share where consumers trade up for foam comfort layers. The hospitality customer segment commands above-average unit values as hotel operators specify durable, fire-rated products for high-turnover installations.
INMETRO in Brazil and Mexico's national standardization body enforce flammability resistance and dimensional labeling requirements that filter lower-quality imports from informal channels. The EU-CELAC partnership dialogues are beginning to reference REACH-aligned chemical restrictions for foam additives, creating compliance pre-work for exporters. Stakeholders must monitor whether Mercosur harmonizes mattress safety protocols ahead of bilateral trade negotiations with the European Union.
Market Dynamics
Hospitality chains across Brazil and Mexico are driving a structural upgrade cycle as operators replace mattresses on compressed replacement schedules and specify fire-rated, durable units for high-turnover installations. This demand concentration is reshaping supplier priorities and certification investments across the value chain.
Growth Catalysts
- INMETRO Certification Mandates:Brazil's tightened flammability and labeling requirements are filtering informal imports and elevating compliant domestic manufacturers into formal retail channels.
- Hospitality Inventory Expansion:Hotel operators in São Paulo and Mexico City are adding rooms and upgrading sleep amenities, creating sustained pull for commercial-grade mattress specifications.
- Compressed-Pack Logistics:Roll-pack foam technology is lowering last-mile fulfillment costs and enabling e-commerce penetration into secondary cities previously served only by brick-and-mortar networks.
Market Restraints
- Petrochemical Input Volatility:Polyurethane foam producers face margin pressure from benzene and TDI price swings that compress working capital cycles.
- Import Concentration Risk:Specialty fabric ticking and fire-barrier textiles rely heavily on Asian suppliers, exposing assemblers to shipping rate spikes and customs delays.
- Substitution by Rental Models:Furniture-as-a-service platforms in urban Brazil are displacing ownership among younger demographics in dense metropolitan zones.
Strategic Opportunities
- Colombia's Underpenetrated Secondary Cities:Medellín and Cali lack dedicated mattress retail density, creating whitespace for specialty store networks and direct-to-consumer fulfillment.
- Eco-Foam Certification Tailwinds:EU-CELAC partnership dialogues referencing REACH-aligned chemical restrictions are creating first-mover advantages for foam producers pre-certifying additive compliance.
- Hybrid Construction Convergence:The pairing of pocketed coil bases with memory foam comfort layers is opening premium positioning for mid-market assemblers previously limited to innerspring volume.
Industry Challenges
- Fire-Certification Timeline Compression:INMETRO laboratory backlogs are extending product approval cycles, delaying new model launches and freezing inventory commitments.
- Skilled Upholstery Labor Scarcity:Sewing and tape-edge finishing expertise is concentrating in aging workforce cohorts across São Paulo state's manufacturing belt, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Mattress Market |
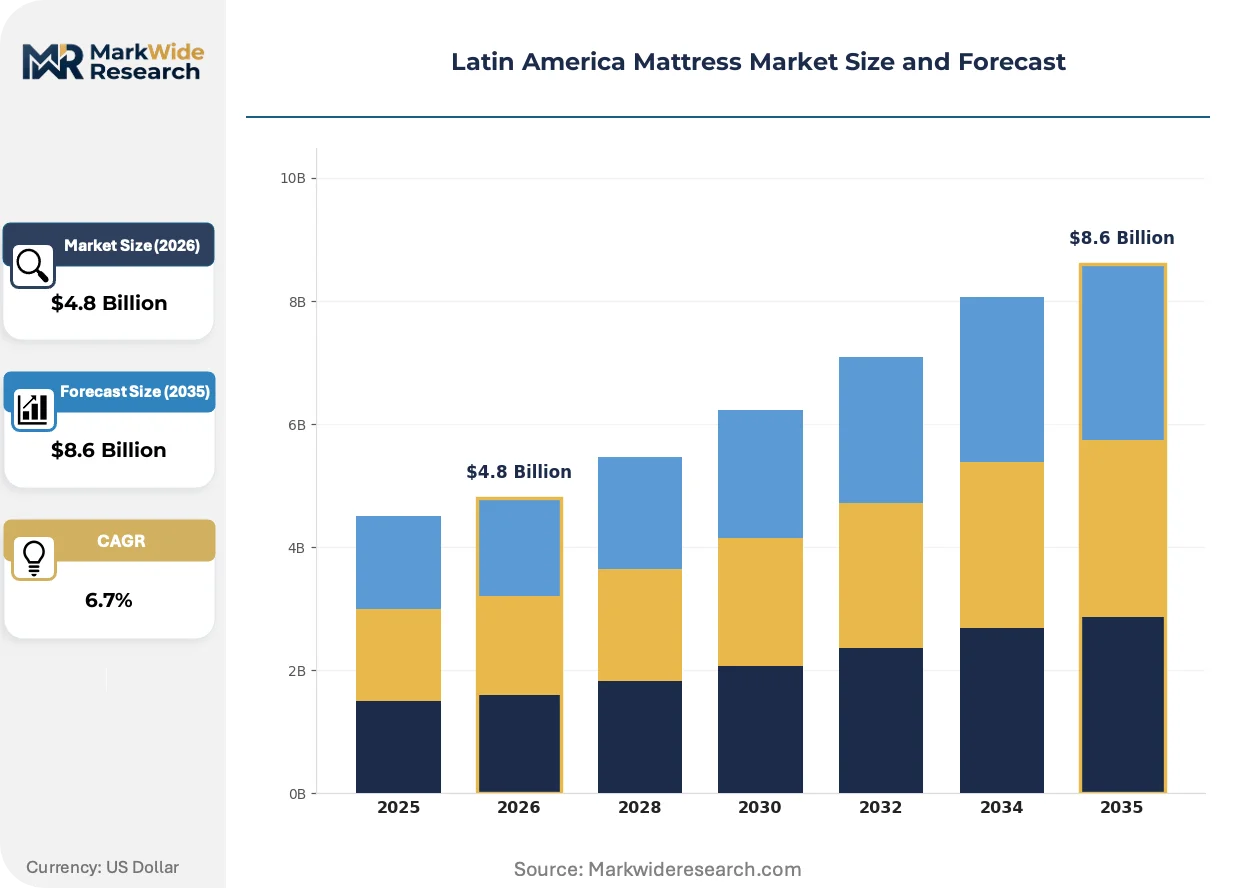
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Latex, Hybrid Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Stores Customer Type: Residential, Commercial, Hospitality, Industrial Size: King, Queen, Twin, Full |
| Companies Covered | Tempur Sealy International, Inc., Colchão Inteligente, Dunlopillo, Paramount Bed Holdings Co. Ltd, Casper Sleep, Inc., Serta Simmons Bedding, LLC, King Koil, Spring Air International, Zinus, Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Mattress Market Shifts & Advancements
Sleep technology is digitizing quality assurance and personalization across Latin American production floors and retail floors alike. Three interconnected shifts are redefining how mattresses are specified, manufactured, and sold.
Sensor-embedded sleep tracking is digitizing product differentiation as foam producers integrate pressure-mapping arrays and biometric monitors into premium units. Hospitality procurement teams in Mexico City are piloting these smart mattresses for guest experience analytics, compressing the traditional specification cycle from annual bids to continuous performance contracts.
REACH-aligned chemical restrictions are surfacing in EU-CELAC technical dialogues, forcing Brazilian foam additive suppliers to reformulate flame retardants and plasticizers ahead of formal harmonization. Manufacturers serving export markets are accelerating substitution timelines, while domestic-only assemblers face compliance pre-work that strains R&D budgets.
Direct-to-consumer channel migration is fragmenting traditional retail gatekeeper power as compressed-pack logistics enable bypass of department store commissions. Younger buyers in São Paulo and Buenos Aires are researching online, ordering trial periods, and returning units via reverse logistics networks that did not exist five years ago, compressing brand loyalty cycles and forcing heritage manufacturers to rebuild digital capabilities.
Latin America Mattress Market Segmentation
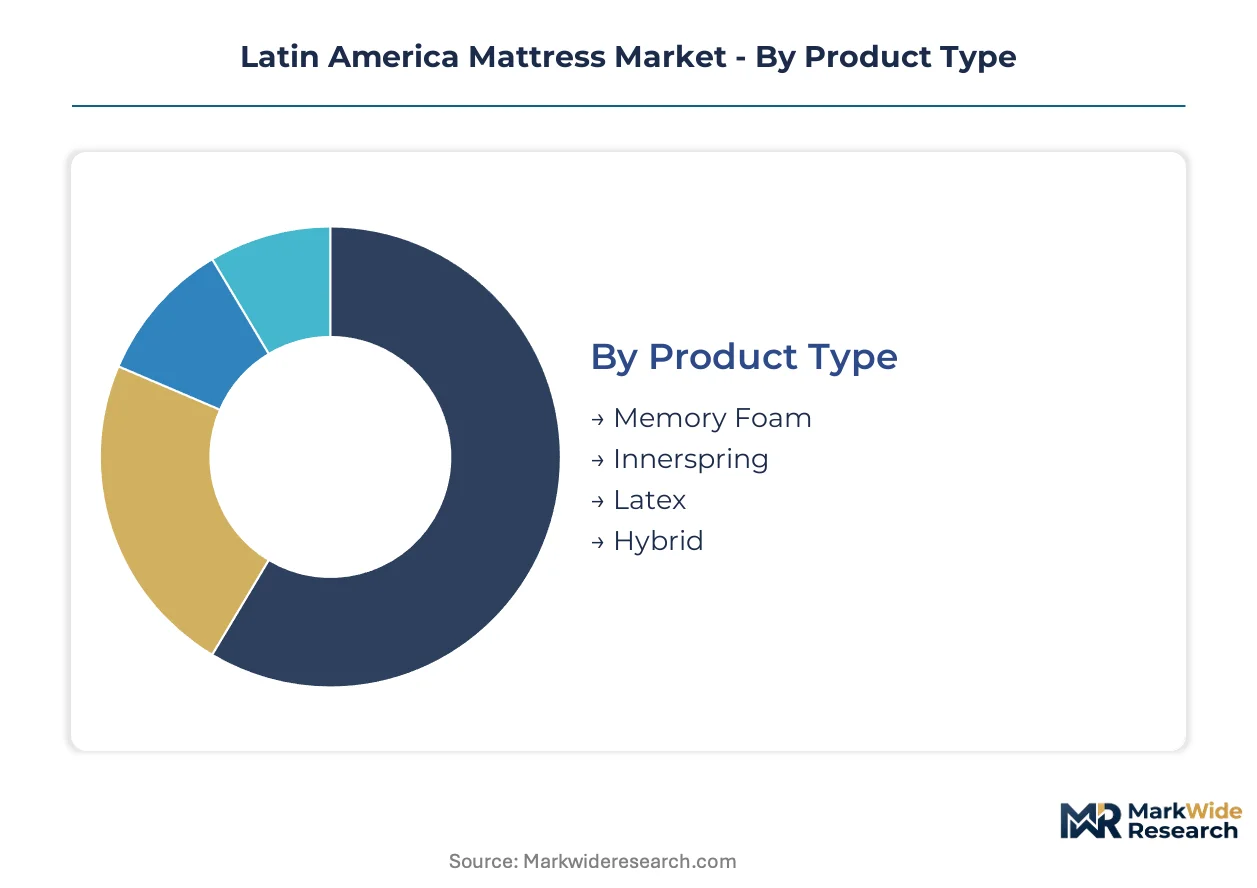
Mattress segmentation across Latin America reveals divergent replacement rhythms and margin profiles. Product type and distribution channel decisions determine working capital intensity, while customer type shapes fire-certification requirements and unit economics.
Product Type:
Replacement cycles vary dramatically across construction technologies, with hospitality-grade units turning over every 3-5 years versus 8-12 year residential lifespans.
- Innerspring:Steel coil systems with fabric-encased padding dominate volume across Brazil's informal retail corridors and Mexico's price-sensitive central states. São Paulo's manufacturing belt still orients assembly lines around coil-pressing equipment, though margin compression from petrochemical volatility is forcing selective line conversions.
- Memory Foam:Viscoelastic polyurethane constructions with density ratings above 3.0 lb/ft³ command premium positioning in Mexico City's urban specialty stores. Roll-pack logistics enable e-commerce penetration into Guadalajara and Monterrey secondary markets previously unreachable through traditional freight networks.
- Latex:Natural rubber or synthetic SBR foam layers cater to allergy-sensitive buyers in Argentina's Buenos Aires province and Chile's Santiago metropolitan region. Domestic latex tapping operations in Brazil's Pará state remain insufficient for mass-market scaling.
- Hybrid:Pocketed coil bases paired with memory foam or latex comfort layers are gaining traction among trade-up consumers in Colombia's Bogotá and Medellín. These units bridge the gap between familiar spring support and pressure-relieving foam surfaces.
Innerspring dominates installed base. Memory foam is where expansion concentrates.
Distribution Channel:
Channel economics separate high-touch service models from logistics-driven fulfillment, with capital requirements and margin structures diverging accordingly.
- Specialty Stores:Dedicated mattress retailers with trained sleep consultants capture the highest conversion rates in Brazil's São Paulo state and Mexico's Nuevo León. These outlets absorb inventory risk through floor model programs but extract 35-45% gross margins on premium constructions.
- Online Retail:Direct-to-consumer platforms leveraging compressed-pack shipping are displacing department store commissions in Buenos Aires and Santiago. Trial-period return rates of 15-20% strain reverse logistics networks that remain underdeveloped outside capital cities.
- Department Stores:Multi-category retailers like Liverpool in Mexico and Casas Bahia in Brazil sustain broad brand exposure but cede pricing power to promotional calendars. Mattress categories compete for floor space against furniture and appliance divisions.
- Discount Stores:Price-focused chains serve cash-constrained buyers in Brazil's Northeast and Mexico's southern states with stripped-down specifications and minimal warranty coverage. These channels filter non-compliant imports that bypass INMETRO certification.
Specialty stores capture the highest unit margins. Online retail is climbing the fastest.
Customer Type:
End-use specifications diverge sharply on fire-rating requirements, durability testing, and procurement contract structures.
- Residential:Individual households purchasing through retail channels drive volume but fragment demand across size and firmness preferences. São Paulo's apartment-dwelling millennials are compressing replacement cycles through furniture-as-a-service subscriptions.
- Hospitality:Hotel operators in Mexico City and Rio de Janeiro specify commercial-grade units with reinforced edge support and fire-barrier ticking. Procurement teams negotiate 3-5 year replacement schedules with performance penalties for premature sagging.
- Commercial:Extended-stay apartments, dormitories, and healthcare facilities in Colombia and Chile require institutional durability ratings. These buyers prioritize total cost of ownership over upfront unit price.
- Industrial:Worker housing camps and offshore platforms in Brazil's pre-salt oil regions demand specialized moisture-resistant and antimicrobial specifications. Order quantities are large but irregular, straining production scheduling.
Residential absorbs the greatest unit volume. Hospitality commands the steepest expansion trajectory.
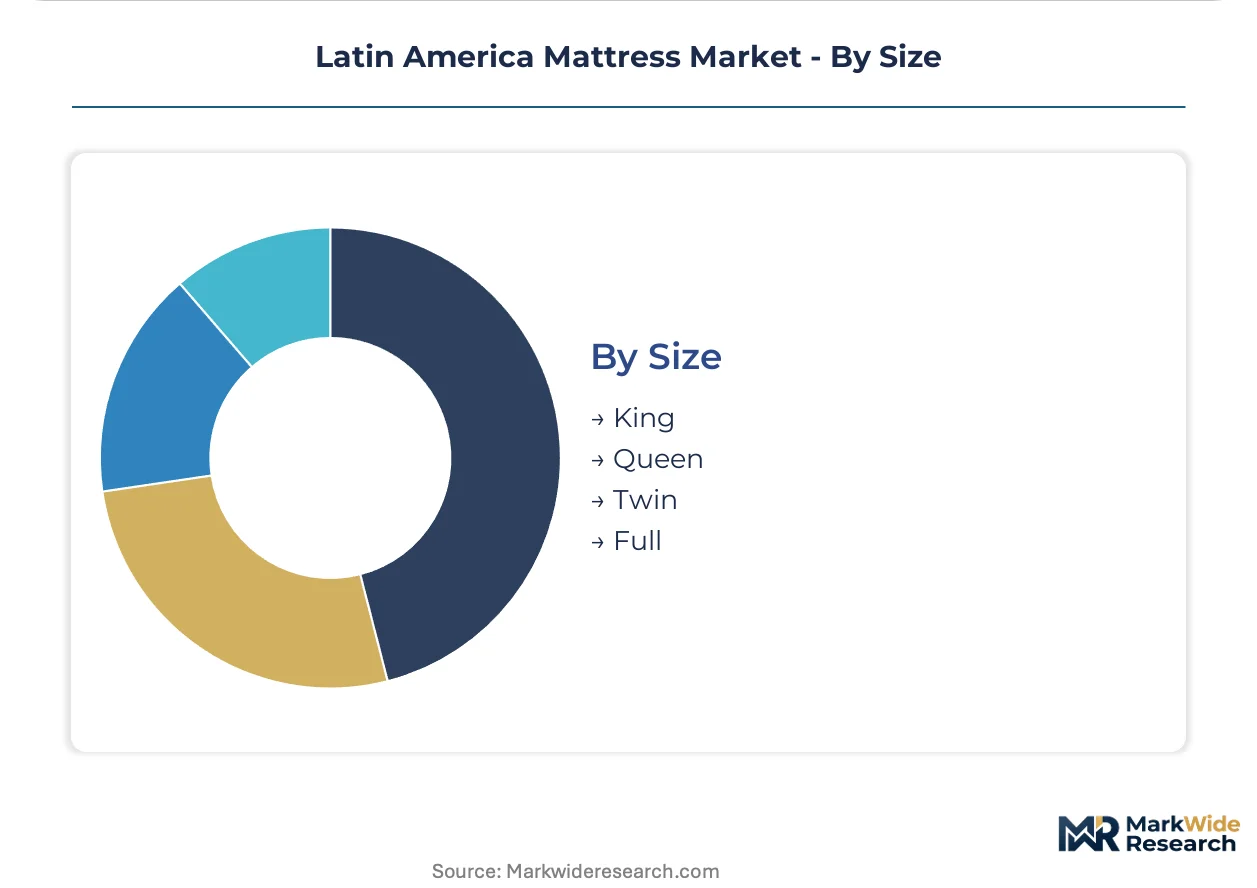
Size:
Dimensional preferences track housing stock characteristics and co-sleeping cultural norms across the region.
- Queen:The 60" × 80" standard dominates new home furnishings in Mexico's central industrial corridor and Brazil's southeastern construction boom. Master bedroom dimensions in middle-class housing developments increasingly assume queen-compatible clearances.
- King:The 76" × 80" format concentrates in luxury hospitality specifications and high-end residential developments in Buenos Aires' Puerto Madero district. Freight costs and elevator constraints limit penetration in older urban buildings.
- Twin:Single-sleeper dimensions sustain volume in children's bedrooms, dormitories, and worker housing across Peru and Ecuador. These units maximize shipping density for e-commerce fulfillment.
- Full:The 54" × 75" intermediate size retains niche demand among space-constrained couples in historic city centers where bedroom dimensions preclude queen placement.
Queen holds the dominant installed position. King is gaining share fastest among trade-up segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
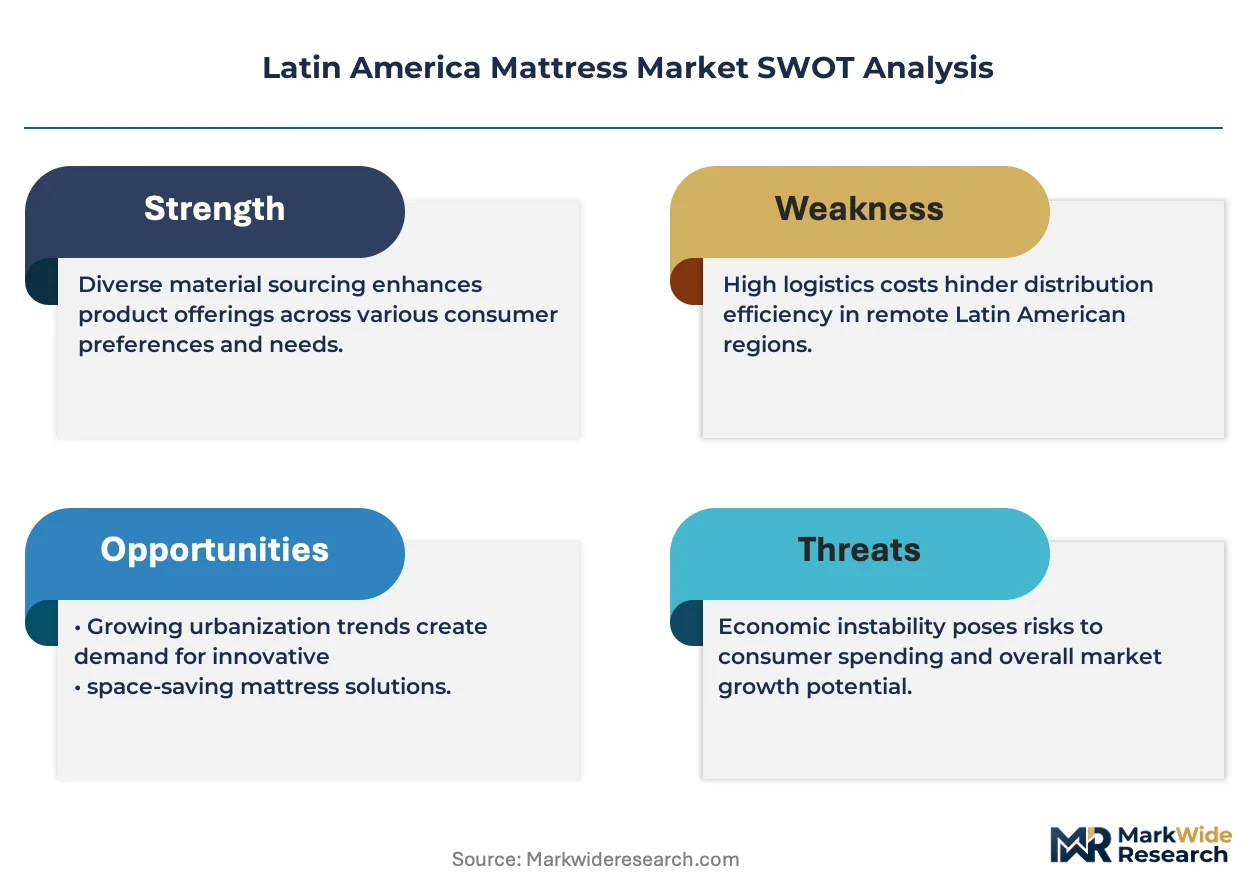
Brazil commands pricing power through INMETRO-certified domestic production while Mexico's import-dependent interior states absorb freight-cost premiums. This asymmetry shapes manufacturer location decisions and regional margin structures across the analysis window.
Brazil
São Paulo state's manufacturing belt concentrates coil-pressing and foam-pouring capacity serving both residential retail and hospitality procurement. INMETRO certification mandates for flammability resistance filter informal imports and elevate compliant domestic producers into formal distribution channels. Campinas and Sorocaba industrial parks host assembly operations supplying Brazil's Southeast construction boom.
Mexico
Mexico City's hospitality sector drives commercial-grade mattress specifications with fire-rated ticking and reinforced edge support requirements. The national standardization body enforces dimensional labeling that blocks non-compliant Asian imports from informal retail channels. Nuevo León's Monterrey metro anchors specialty store networks penetrating northern industrial corridors.
Argentina
Buenos Aires province sustains latex-preference demand among allergy-sensitive residential buyers despite import tariff pressure on natural rubber inputs. The city's furniture-as-a-service platforms compress ownership cycles among millennial apartment dwellers. Puerto Madero luxury developments specify king-format units despite freight and elevator constraints.
Colombia
Bogotá's mid-market trade-up consumers adopt hybrid constructions pairing pocketed coils with memory foam comfort layers. Medellín and Cali lack dedicated mattress retail density, creating whitespace for direct-to-consumer fulfillment and specialty store expansion. The Andean industrial corridor imports fire-barrier textiles from Asian suppliers, exposing assemblers to shipping volatility.
Chile
Santiago's metropolitan region concentrates institutional demand from extended-stay apartments and healthcare facilities prioritizing total cost of ownership. The country's national standardization body references EU-CELAC technical dialogues on chemical restrictions, forcing foam additive reformulation ahead of formal harmonization. Valparaíso port logistics enable compressed-pack e-commerce penetration into secondary markets.
Latin America Mattress Market Competitive Landscape
Multinational foam technology licensors and regional coil assemblers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: premium memory foam specialists leveraging compressed-pack logistics, mid-market hybrid producers bridging spring and foam constructions, and economy innerspring fabricators serving price-sensitive interior states. M&A activity targets distribution network consolidation, while strategic partnerships with hospitality procurement teams lock in multi-year replacement contracts.
Among premium-tier specialists, Tempur Sealy International, Inc. and Casper Sleep, Inc. occupy positions anchored by foam technology licensing and direct-to-consumer channel expertise. Serta Simmons Bedding, LLC exemplifies the hybrid-construction archetype through broad retail coverage partnerships. Zinus, Inc. represents the compressed-pack logistics model lowering last-mile costs for e-commerce fulfillment. These three companies illustrate how technology specialization, distribution scale, and supply chain innovation define competitive positioning without converging on identical capability stacks.
| Leading Market Players |
|---|
| Tempur Sealy International, Inc. |
| Colchão Inteligente |
| Dunlopillo |
| Paramount Bed Holdings Co. Ltd |
| Casper Sleep, Inc. |
| Serta Simmons Bedding, LLC |
| King Koil |
| Spring Air International |
| Zinus, Inc. |
| Others |
Supply & Pricing Matrix
Asian specialty fabric ticking and fire-barrier textile suppliers anchor margin capture upstream, concentrating pricing power with mills in China and Taiwan that feed Brazilian and Mexican assembly operations. This upstream concentration compresses working capital cycles for foam producers facing petrochemical volatility, while downstream margin pools concentrate with INMETRO-certified domestic manufacturers who filter informal imports from formal retail channels.
Pricing Analysis
The customization-premium spread separates hospitality procurement from residential retail, with hotel operators in Mexico City and São Paulo paying configured-to-order premiums for fire-rated ticking and reinforced edge support. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with INMETRO compliance commanding tier separation. Cost compression in the economy tier is intensifying because discount stores filter non-certified imports, eroding warranty-backed domestic volume. Residential buyers through online retail channels exhibit highest price sensitivity, while hospitality procurement teams show lowest sensitivity due to total cost-of-ownership contracting.
Supply Chain Analysis
Export-control regimes on advanced flame-retardant chemistry and pressure-mapping sensor arrays limit technology flows from US and EU suppliers into Brazilian foam-pouring operations. Geographic supply concentration centers on China for specialty ticking, Taiwan for fire-barrier textiles, and South Korea for viscoelastic foam additives. Raw material dependencies rest on benzene-derived TDI, natural latex from Pará state, and steel coil wire from domestic mini-mills. Single-source vulnerability runs through Asian textile suppliers exposed to shipping rate spikes. Distribution feeds from São Paulo state's manufacturing belt through specialty store networks and compressed-pack e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through INMETRO certification creates defensive moats for compliant domestic manufacturers, as laboratory approval backlogs and reformulation requirements raise switching costs for hospitality procurement teams.
For Market Incumbents: Harden certification moats by accelerating fire-barrier textile backward integration into captive weaving operations, reducing exposure to Asian shipping volatility. Deepen channel control through exclusive floor-model programs with specialty store networks in São Paulo and Nuevo León, locking out compressed-pack entrants from premium positioning. The threat of furniture-as-a-service subscription models displacing ownership among Brazilian millennials demands defensive response through trial-period matching and reverse logistics investment. For New Entrants and Emerging Players: Pursue whitespace in Colombia's underpenetrated secondary cities, where Medellín and Cali lack dedicated mattress retail density and hospitality inventory expansion lags Mexico and Brazil. The most penetrable segment is mid-market hybrid construction, where pocketed coil bases with memory foam comfort layers bridge familiar spring support with foam pressure relief. A direct-to-consumer go-to-market angle leveraging compressed-pack logistics can bypass established department store commissions and specialty store gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-tier assemblers with captive foam-pouring capacity and INMETRO laboratory relationships, as these assets compound regulatory entrenchment over the projection horizon. Acquisition target archetypes include São Paulo-state manufacturers with hospitality procurement contracts and established reverse logistics networks. The signal to watch is EU-CELAC chemical restriction harmonization timelines, which would force additive reformulation and strand non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO Certification Acceleration | Shortens approval cycles for new model launches ahead of laboratory backlog resolution. |
| Fire-Barrier Textile Backward Integration | Captures margin pools currently concentrated with Asian ticking suppliers exposed to freight spikes. |
| Compressed-Pack Logistics Expansion | Enables e-commerce penetration into Colombian secondary cities lacking specialty store density. |
| Hospitality Procurement Contract Lock-In | Secures multi-year replacement schedules with performance penalties against premature sagging. |
| Eco-Foam Pre-Certification Investment | Creates first-mover positioning ahead of EU-CELAC REACH-aligned chemical restriction harmonization. |
Research Methodology
The analysis maps innerspring, memory foam, latex, and hybrid construction segments, each validated through foam-pouring plant managers, hospitality procurement directors, specialty store network owners, and e-commerce fulfillment operators. Primary interviews with these stakeholders combined with secondary validation from INMETRO certification databases, Brazilian customs import records, Mexican national standardization body filings, and hospitality industry procurement databases. Bottom-up unit volume estimates triangulated against top-down construction spending and household formation projections across the analysis window.
The assumption-set held petrochemical input cost volatility within historical bands while varying hospitality inventory expansion rates and EU-CELAC regulatory harmonization timelines. Segmentation dimensions modeled include construction technology, distribution channel, customer type, and regional regulatory cluster. CAGRs derived from replacement cycle analysis and trade-up elasticity estimates. Industry-specific forecast inputs incorporated furniture-as-a-service subscription penetration rates and compressed-pack logistics cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer entrants or accelerated EU-CELAC chemical restriction timelines would shift outcomes. Material shifts in INMETRO laboratory capacity expansion or Mercosur-EU bilateral trade negotiation progress would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Global Mattress Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Asia-Pacific Mattress Market
Bedroom Furniture
Vietnam Mattress Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Luxury and Premium Mattress Market
Bedroom Furniture
Queen Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
Home Bedding Market
Bedroom Furniture
Malaysia Mattress Market