
 Iraq ICT Market | 2026-2036
Iraq ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq ICT Market Insights
Market Context
The capital-intensity divergence between integrated infrastructure vendors and software-centric service providers is reorganizing competitive dynamics across Iraq's ICT landscape. Huawei Technologies leverages its end-to-end telecom equipment portfolio to dominate base station deployment and fiber backbone projects. Cisco Systems anchors enterprise networking demand through channel partnerships with local system integrators. Asiacell Communications competes aggressively on mobile data pricing while extending 4G coverage into southern governorates.
Technical Definition and Segment Structure
Information and communications technology (ICT) encompasses hardware, software, and services enabling data processing, transmission, and storage across enterprise and consumer environments, with specifications ranging from sub-6 GHz wireless protocols to Tier III data center uptime standards. Cloud Computing leads technology adoption as Iraqi banks and oil firms migrate on-premise workloads to distributed infrastructure. Telecommunications anchors application spending through 5G-ready network densification, while Cybersecurity represents the fastest-growing technology segment as ransomware incidents multiply against critical infrastructure targets.
Regulatory Framework
The Communications and Media Commission governs spectrum allocation and licensing terms for mobile operators, while the Central Bank of Iraq mandates ISO 27001-aligned cybersecurity standards for financial institutions processing electronic transactions. Government Agencies dominate end-user procurement through sovereign digitization programs, yet SME access to managed services remains constrained by fragmented last-mile connectivity outside Baghdad and Basra. Stakeholders must monitor regulatory clarity on data localization requirements and foreign vendor certification timelines.
Market Dynamics
The Central Bank of Iraq's electronic payment mandates and 5G spectrum preparations by the Communications and Media Commission are reorganizing capital allocation across infrastructure and cybersecurity verticals.
Growth Catalysts
- Regulatory Mandates:The Central Bank of Iraq's ISO 27001-aligned cybersecurity standards for electronic transactions are compelling financial institutions to upgrade infrastructure. This creates immediate demand for encryption and authentication services.
- Oil Sector Digitization:Basra-based oil enterprises are migrating operational technology systems to cloud platforms. This shift requires specialized industrial IoT integration and edge computing deployment.
- 5G Spectrum Allocation:The Communications and Media Commission's preparations for 5G licensing are triggering base station densification projects in Baghdad and southern governorates.
Market Restraints
- Import Dependency:Telecom hardware and enterprise networking equipment rely heavily on supply chains originating outside the region. Currency volatility and customs processing create procurement delays.
- Power Infrastructure Gaps:Unreliable grid electricity outside Baghdad and Basra forces data center operators to invest in redundant diesel generation. This elevates operational expenditure thresholds.
- Regulatory Fragmentation:Data localization requirements remain undefined, causing foreign cloud providers to defer capital commitment until legal clarity emerges.
Strategic Opportunities
- Southern Governorate Expansion:Karbala, Najaf, and Muthanna provinces exhibit minimal managed services penetration. Local system integrators can establish first-mover advantage in enterprise support contracts.
- Cyber-Physical Convergence:Integration of operational technology security with IT networks represents unmet demand in oil and electricity infrastructure. Vendors combining SCADA protection with endpoint detection gain differentiation.
- Electronic Payment Infrastructure:Point-of-sale terminal deployment and mobile wallet integration remain underdeveloped in retail and hospitality sectors.
Industry Challenges
- Specialized Talent Scarcity:Cloud architecture and penetration testing expertise concentrates in Baghdad. Enterprises in peripheral provinces face recruitment bottlenecks and salary inflation.
- Legacy System Integration:Banking core systems built on decades-old architectures require middleware development for API connectivity. Project timelines extend due to documentation gaps and vendor attrition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq ICT Market |
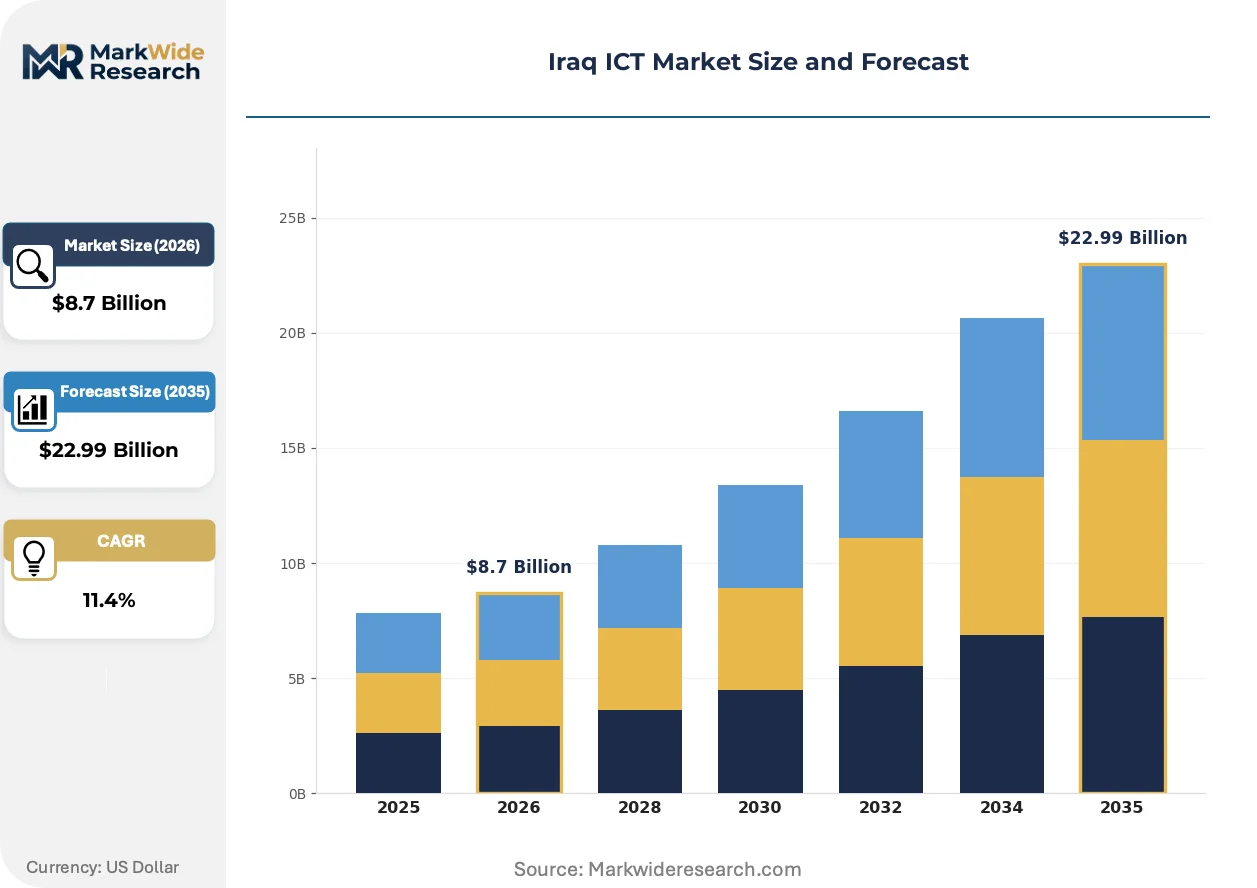
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Artificial Intelligence, IoT, Cybersecurity Application: Telecommunications, E-Government, Healthcare IT, Education Technology End User: SMEs, Large Enterprises, Government Agencies, Non-Profit Organizations Service Type: Consulting, System Integration, Managed Services, Support Services |
| Companies Covered | Huawei Technologies, Ericsson, Nokia, Microsoft, Oracle, Cisco Systems, IBM, Dell Technologies, Asiacell Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq ICT Market Trends and Innovations
Software-defined infrastructure and sovereign data requirements are compressing traditional hardware procurement cycles while elevating managed service preferences among Iraqi enterprises.
Software-defined wide area networking is supplanting MPLS-based enterprise connectivity in Iraqi banking and oil headquarters. Chief information officers in Baghdad are accelerating migration timelines from three-year to eighteen-month refresh cycles. This compression is forcing traditional telecom carriers to restructure tariff models toward bandwidth-on-demand structures.
The Communications and Media Commission's draft 5G licensing framework introduces spectrum sharing provisions and infrastructure-sharing mandates for mobile operators. These conditions reduce barriers to entry for data-centric service providers while compelling incumbents to accelerate fiber backhaul deployment. Basra-based operators are responding by consolidating tower assets through joint venture structures.
Enterprise buyers are unbundling hardware procurement from implementation and support services. Iraqi banks and oil firms now separately source equipment through international distributors while contracting local system integrators for deployment and maintenance. This disintermediation is most pronounced in Baghdad, where procurement teams have developed direct relationships with Dubai-based logistics providers.
Iraq ICT Market Segmentation
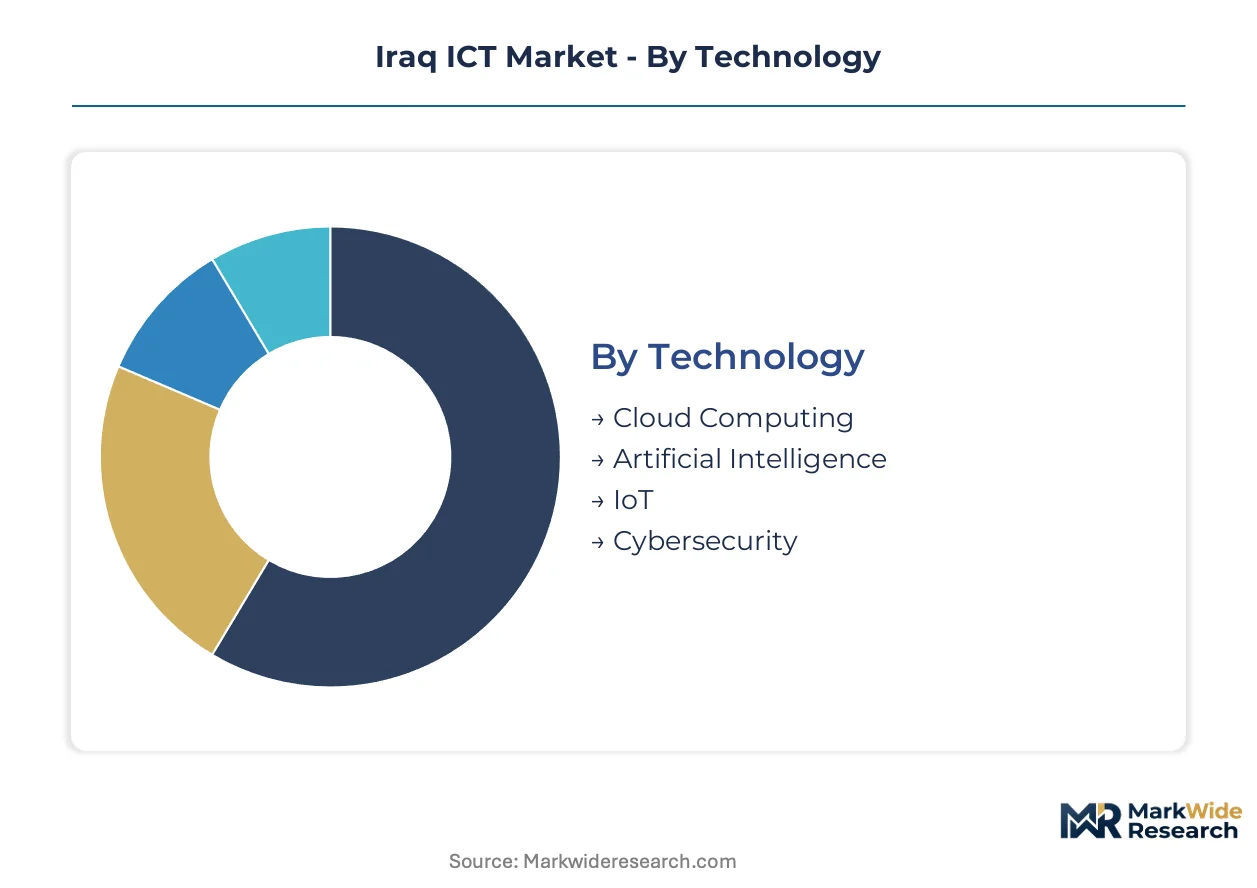
Segmentation reveals how procurement authority and technical requirements diverge across Iraqi ICT buyers. Government mandates, oil-sector digitization, and banking compliance create distinct demand profiles that vendors must navigate separately.
Technology:
Cloud Computing faces substitution pressure from hybrid on-premise deployments as data localization uncertainty persists.
- Cloud Computing:Distributed infrastructure enabling remote workload hosting and elastic resource allocation. Iraqi banks and Basra-based oil firms are migrating core systems despite regulatory ambiguity, driven by disaster recovery requirements and capital expenditure reduction goals.
- Cybersecurity:Protective technologies spanning encryption, endpoint detection, and network monitoring. The Central Bank of Iraq's ISO 27001 mandates are compelling financial institutions in Baghdad to accelerate procurement of authentication and threat intelligence services.
- Artificial Intelligence:Machine learning applications for predictive analytics and automated decision support. Limited adoption concentrates in oil-sector predictive maintenance and banking fraud detection.
- IoT:Sensor networks and connected device infrastructure for industrial monitoring. Deployment focuses on oil field automation and smart city pilots in Baghdad.
Cloud Computing retains volume leadership; Cybersecurity holds the steepest expansion curve.
Application:
Cost-tier stratification separates sovereign-funded deployments from commercially financed initiatives.
- Telecommunications:Network infrastructure and connectivity services spanning mobile and fixed-line domains. The Communications and Media Commission's 5G spectrum preparations are triggering base station densification projects in Baghdad and southern governorates.
- E-Government:Digital service delivery platforms and administrative automation systems. Procurement concentrates through sovereign digitization programs with vendors selected via Baghdad-centered tender processes.
- Healthcare IT:Electronic medical records and clinical management systems. Fragmented adoption across public hospitals and private clinics in major cities.
- Education Technology:Learning management systems and digital classroom infrastructure. Ministry of Education initiatives drive hardware deployment with limited software integration.
Telecommunications absorbs the largest capital allocation; E-Government is expanding most quickly.
End User:
Customer-type concentration creates margin divergence between price-sensitive SMEs and specification-driven government contracts.
- Government Agencies:Sovereign entities procuring through centralized tender mechanisms. Baghdad-based ministries dominate spending on infrastructure and cybersecurity with multi-year implementation timelines.
- Large Enterprises:Oil firms and banking groups with dedicated IT procurement functions. Basra-based energy companies are migrating operational technology systems to cloud platforms with specialized industrial IoT integration requirements.
- SMEs:Small and medium enterprises with constrained technical staff and budget flexibility. Managed services penetration remains minimal outside Baghdad and Basra due to last-mile connectivity gaps.
- Non-Profit Organizations:Development agencies and charitable entities with donor-dependent funding cycles. ICT spending concentrates on basic connectivity and administrative software.
Government Agencies command the procurement pipeline; Large Enterprises are gaining share fastest.
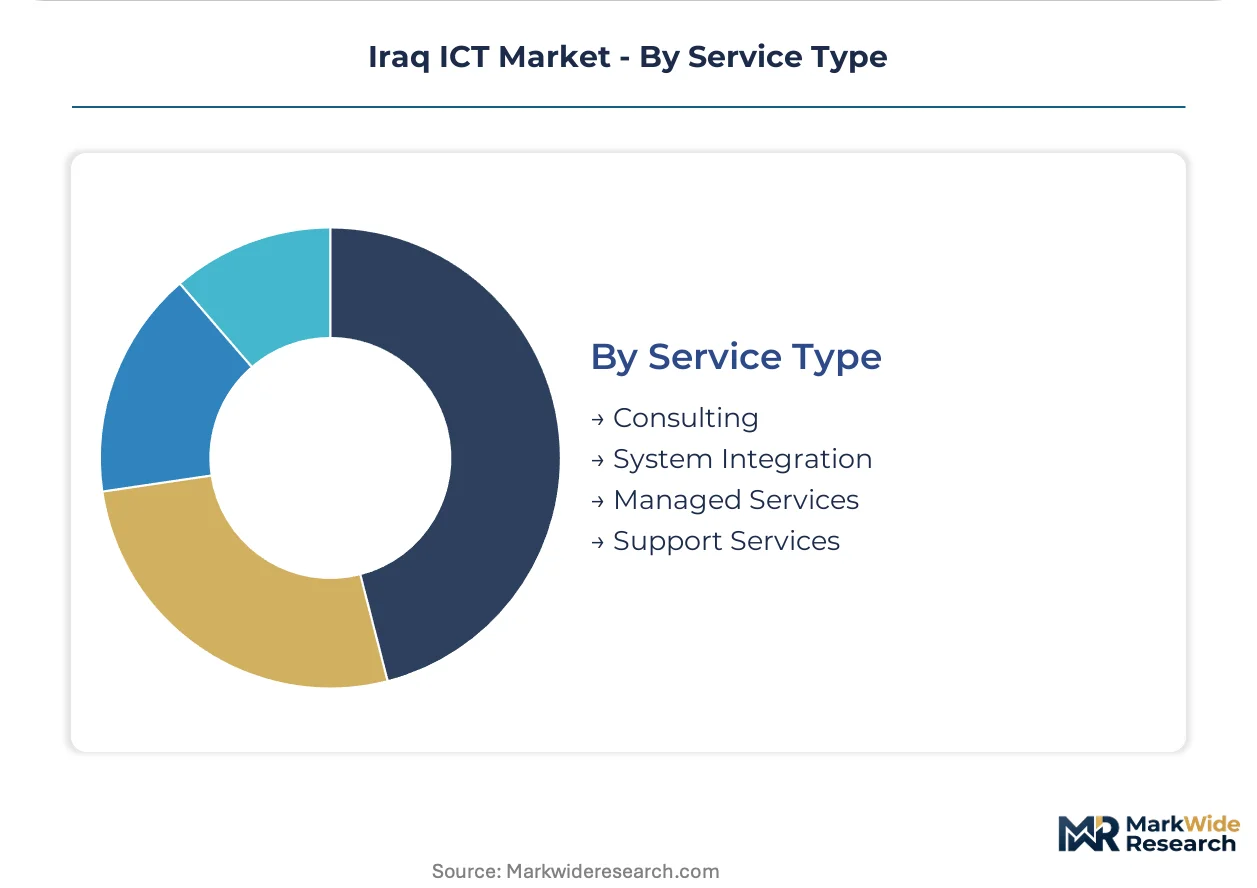
Service Type:
Supply concentration among Baghdad-based system integrators shapes delivery capabilities across service categories.
- System Integration:Hardware assembly, software configuration, and network deployment services. Local integrators in Baghdad capture implementation contracts for international equipment vendors.
- Managed Services:Ongoing infrastructure operation and maintenance under contractual arrangements. Oil firms in Basra are outsourcing data center operations to specialized providers.
- Consulting:Strategic advisory and technology roadmap development. Demand concentrates among banking groups navigating Central Bank compliance requirements.
- Support Services:Break-fix maintenance and technical helpdesk functions. Fragmented provider landscape with quality variance between Baghdad and peripheral provinces.
System Integration retains volume leadership; Managed Services holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Baghdad and Basra while southern governorates face connectivity premiums of 40-60% above capital-region benchmarks. This asymmetry is reshaping vendor deployment strategies and procurement timelines across Iraq's ICT landscape.
Baghdad Governorate
The Central Bank of Iraq's electronic payment mandates and sovereign digitization programs are driving concentrated demand for cybersecurity and cloud infrastructure. The Communications and Media Commission governs spectrum allocation from its Baghdad headquarters, streamlining licensing for capital-based operators. The Karrada and Mansour districts host the densest cluster of data centers and enterprise headquarters, with banks and government ministries executing multi-year infrastructure contracts.
Basra Governorate
Oil-sector digitization is accelerating operational technology migration to cloud platforms with specialized industrial IoT requirements. The Basra Oil Company and international energy operators are procuring edge computing and SCADA integration services under long-term frameworks. The Umm Qasr port corridor and surrounding industrial zones are attracting fiber backbone investment to support real-time field monitoring systems.
Erbil Governorate
Kurdistan Regional Government digitization initiatives are creating demand for e-government platforms and administrative automation systems. The regional Ministry of Transport and Communications oversees licensing terms distinct from federal frameworks, introducing regulatory complexity for national operators. The Ankawa district and 100 Meter Road corridor concentrate banking and commercial ICT procurement, though at lower volumes than Baghdad.
Najaf Governorate
Religious tourism infrastructure is driving smart city pilots and hospitality-sector electronic payment deployment. The Najaf Investment Commission is facilitating technology park development with fiber connectivity commitments. The Old City perimeter and Imam Ali Shrine district are seeing concentrated point-of-sale terminal rollout and mobile wallet integration trials.
Dhi Qar Governorate
Agricultural modernization programs are generating nascent demand for IoT-enabled irrigation and supply chain tracking systems. The provincial government is negotiating with federal agencies for last-mile fiber subsidies to bridge connectivity gaps with southern commercial centers. The Nasiriyah urban core represents the primary concentration of SME managed services demand outside Basra in the southern region.
Iraq ICT Market Competitive Landscape
Concentration sits with integrated infrastructure vendors possessing end-to-end telecom equipment portfolios and established channel partnerships with local system integrators. The market structure divides between hardware-centric deployers and software-focused service providers, with procurement authority increasingly unbundling equipment sourcing from implementation contracts. Three archetypes dominate: integrated global vendors with local presence, regional telecom operators expanding coverage footprints, and specialized cybersecurity providers targeting banking compliance mandates. Competitive moves center on fiber backhaul consolidation through tower joint ventures and strategic partnerships with Baghdad-based system integrators for government tender access.
Among integrated global vendors, Huawei Technologies and Cisco Systems anchor equipment supply relationships with Iraqi banks and oil enterprises, while Asiacell Communications represents the regional operator archetype competing on mobile data pricing and 4G coverage extension. These three exemplify distinct positioning strategies: the Chinese vendor leveraging end-to-end portfolio breadth, the American firm anchoring enterprise networking through channel partnerships, and the local operator pursuing subscriber growth in underserved southern governorates.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ericsson |
| Nokia |
| Microsoft |
| Oracle |
| Cisco Systems |
| IBM |
| Dell Technologies |
| Asiacell Communications |
| Others |
Pricing and Supply Chain Analysis
ISO 27001 certification requirements from the Central Bank of Iraq simultaneously gate vendor qualification for banking contracts and create price differentiation between certified and uncertified service providers. This dual function compresses margins for non-compliant operators while enabling certified Baghdad-based system integrators to command implementation premiums.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise networking deployments from standard hardware resale. Project-based pricing dominates system integration contracts, with price differentiation driven by ISO 27001 certification tier and after-sales service bundling. Cost compression in standard equipment tiers intensifies as procurement teams develop direct Dubai distributor relationships. SMEs exhibit highest price sensitivity, while oil-sector enterprises prioritize specification compliance over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites the majority of telecom hardware and enterprise networking equipment entering Iraqi ports. Supply concentrates in China, South Korea, and Taiwan for base station components, fiber optic cable, and server hardware. Single-source vulnerability around 5G-ready semiconductor components creates procurement risk for operators accelerating network densification. Distribution runs through Dubai-based logistics hubs before final-mile deployment by Baghdad system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's ICT market is recovering from import disruption cycles, with capital expenditure normalization in oil-sector digitization programs driving the current upswing.
For Market Incumbents: Compound fiber backbone coverage through tower joint ventures with southern governorate operators to preempt emerging entrant land-grab strategies. Deepen backward integration into data center power infrastructure to offset diesel generation cost inflation outside Baghdad and Basra.
For New Entrants and Emerging Players: Anchor in Karbala and Najaf provinces where managed services penetration remains minimal and local system integrator competition is sparse. Target religious tourism electronic payment infrastructure as the most penetrable segment, deploying point-of-sale terminals through hospitality channel partnerships.
For Investors and Strategic Acquirers: The Communications and Media Commission's 5G licensing framework reshapes the acquisition landscape by privileging operators with existing fiber backhaul assets. Over the medium-term horizon, prioritize Baghdad-based cybersecurity specialists with Central Bank compliance track records. Watch for spectrum auction timing as the definitive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Tower Asset Joint Venture | Consolidates fiber backhaul infrastructure across Basra and southern governorates for 5G readiness. |
| ISO 27001 Certification Investment | Unlocks Central Bank of Iraq procurement pipelines for cybersecurity and authentication services. |
| Edge Computing Deployment | Supports oil-sector operational technology migration with low-latency field monitoring capabilities. |
| System Integrator Acquisition | Secures government tender access through established Baghdad-based implementation relationships. |
| Electronic Payment Platform Launch | Captures underdeveloped retail and hospitality point-of-sale terminal demand in religious tourism corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief information officers at Baghdad banks, procurement leads at Basra oil enterprises, network engineers at mobile operators, and system integration firm principals. Secondary validation drew from Communications and Media Commission licensing disclosures, Central Bank of Iraq regulatory circulars, customs import records, and hyperscaler capex announcements. Bottom-up project pipeline enumeration was triangulated against top-down sectoral spending estimates.
Across the analysis window, the forecasting framework modeled technology adoption curves, application deployment cycles, end-user procurement authority concentration, and service type margin structures. CAGRs were derived from segment-level growth trajectory synthesis. Key inputs included 5G spectrum allocation timelines, oil-sector capital commitment patterns, and electronic payment mandate compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of regulatory clarity on data localization and stable import logistics; material deviation would warrant model refresh. Revision becomes warranted when power infrastructure reliability thresholds in southern governorates shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
ASEAN Geospatial Analytics Market
Analytics
North America Location Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
France Contact Center Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Global Clickstream Analytics Market
Analytics
Web Analytics Market
Analytics
Imagery Analytics Market
Analytics
Big Data in Automotive Market
Analytics
Brazil Geospatial Analytics Market
Analytics
Israel Geospatial Analytics Market
Analytics
Datacenter Analytics Market