
 Analytics Sandbox Market | 2026-2036
Analytics Sandbox Market Size, Share, and Industry Trends Forecast 2026-2036
Analytics Sandbox Market Outlook
Containerized compute architectures is fragmenting the traditional monolithic data platform stack into modular, API-driven sandbox environments that enterprises assemble from specialized vendors. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise-grade analytics sandboxes with native integration into Power BI and Azure ML. Databricks Inc. competes through its lakehouse architecture, which unifies batch and streaming workloads within a single sandbox runtime. Palo Alto Networks, Inc. differentiates by embedding zero-trust security primitives directly into sandbox provisioning workflows, addressing regulated industries.
An analytics sandbox is an isolated, governed computational environment that provisions temporary data processing resources, typically supporting SQL, Python, R, and Spark runtimes with configurable CPU, memory, and storage quotas, enabling data scientists to experiment with datasets without impacting production systems. Cloud-based deployment leads current adoption as organizations prioritize elastic scaling and reduced infrastructure overhead over fixed-capacity on-premise installations. Machine Learning application segments are expanding fastest, driven by demand for GPU-accelerated model training within ephemeral, cost-controlled environments. Self-Service Analytics solutions concentrate margin pools by reducing IT provisioning bottlenecks and accelerating time-to-insight for business analysts.
ISO 27001 information security management and the EU AI Act's risk-classification framework shape product standards for cross-border data experimentation, while HIPAA constrains how US healthcare organizations configure sandbox access controls for protected health information. The US Federal Risk and Authorization Management Program (FedRAMP) and Singapore's Monetary Authority of Technology Risk Management Guidelines govern cloud sandbox deployments in government and financial sectors respectively. Stakeholders must evaluate whether their sandbox architectures can adapt as regulators impose algorithmic audit requirements and data residency mandates without sacrificing computational flexibility.
Market Dynamics
Containerized compute architectures are fragmenting traditional monolithic data platforms into modular, API-driven sandbox environments that enterprises assemble from specialized vendors rather than single-stack providers.
Growth Catalysts
- Basel III capital requirements:Financial services firms in Singapore, Hong Kong, and Australia expand predictive modeling environments to stress-test portfolios under tighter regulatory scrutiny.
- GPU-accelerated training:Machine learning practitioners demand ephemeral, cost-controlled environments for model experimentation without production system risk.
- Data sovereignty maturation:Cloud-based deployment captures disproportionate demand as regional frameworks in Singapore, Hong Kong, and Australia mature.
Market Restraints
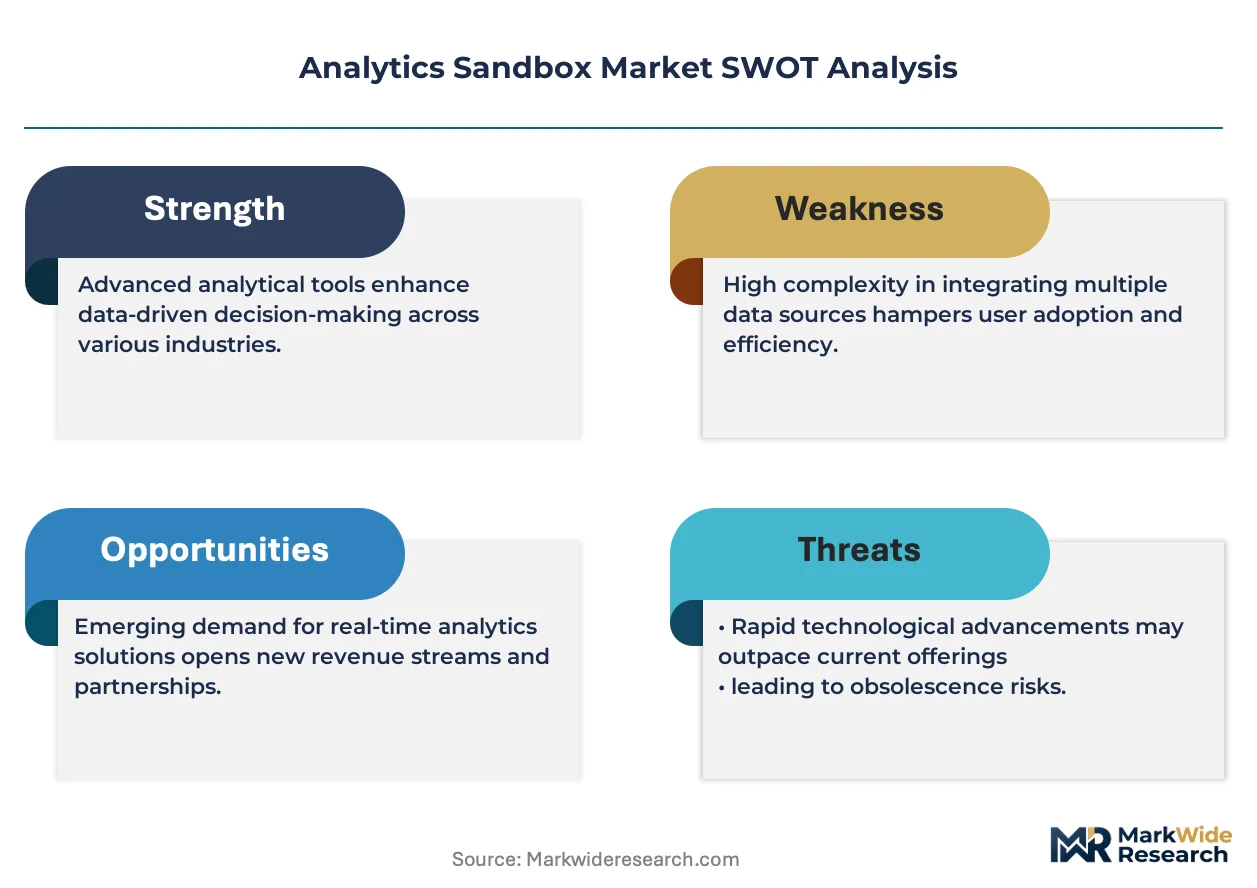
- Ephemeral storage costs:GPU-intensive workloads generate unpredictable egress charges that compress margin for self-service analytics solutions.
- Zero-trust implementation complexity:Regulated industries face extended provisioning timelines as Palo Alto Networks-style security primitives add workflow friction.
- Legacy system integration:Established enterprises maintain substantial on-premise data warehouse investments that resist cloud-native sandbox migration.
Strategic Opportunities
- FedRAMP authorization pathways:US government agencies seek compliant cloud sandbox deployments for classified and unclassified data experimentation.
- Lakehouse-SQL convergence:Databricks-style unification of batch and streaming workloads creates white space for single-runtime sandbox vendors.
- ISO 27001 certification arbitrage:Cross-border data experimentation demands spur specialized providers to anchor offerings in Singapore and Hong Kong.
Industry Challenges
- MLOps talent scarcity:Organizations struggle to staff sandbox governance roles requiring simultaneous expertise in Kubernetes orchestration and regulatory compliance.
- EU AI Act risk classification:High-risk algorithmic systems face mandatory audit trails that sandbox architectures must accommodate without sacrificing computational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytics Sandbox Market |
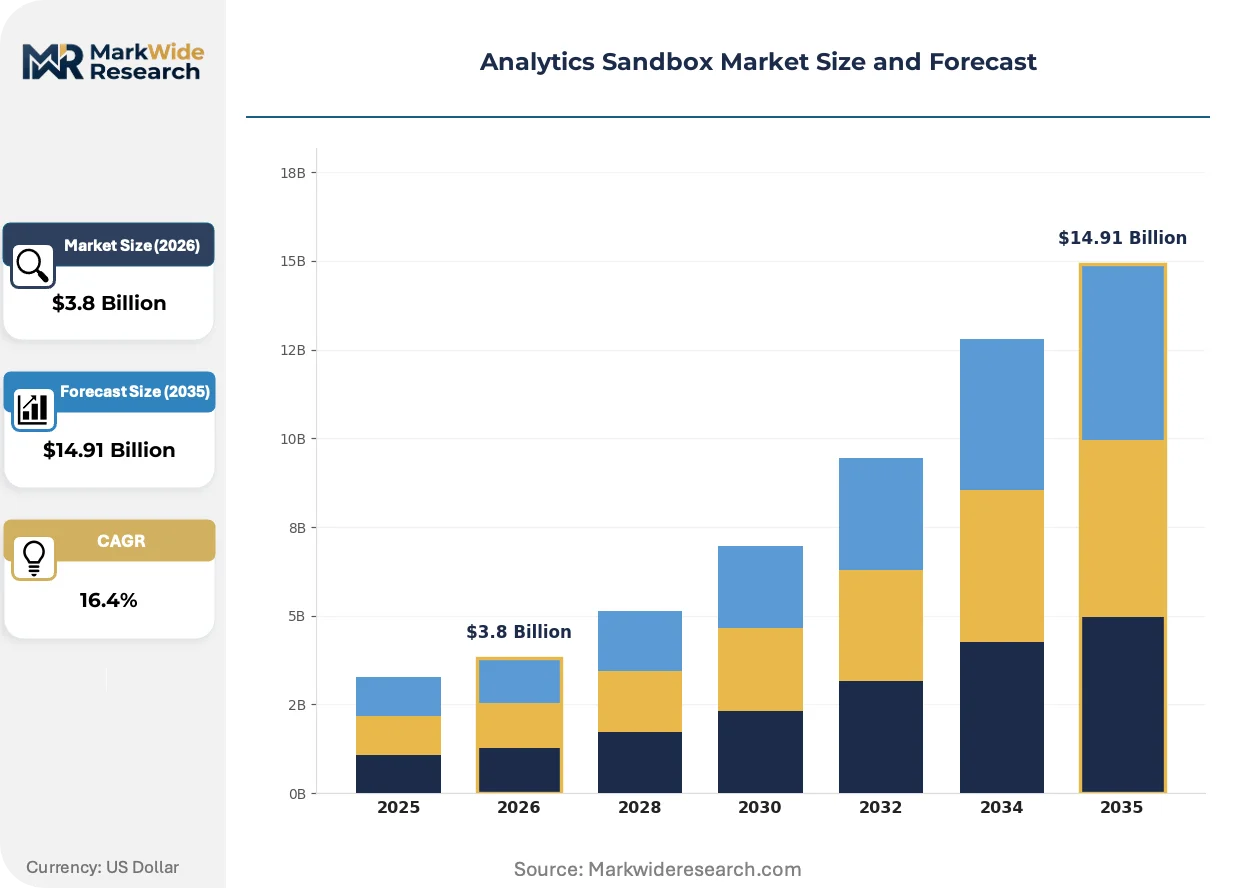
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud End User: Small Businesses, Enterprises, Academic Institutions, Government Agencies Application: Data Analysis, Predictive Modelling, Visualization, Machine Learning Solution: Self-Service Analytics, Data Discovery, Dashboarding, Reporting |
| Companies Covered | Oracle Corporation, Databricks Inc., Microsoft Corporation, Cisco Systems, Inc., Palo Alto Networks, Inc., Amazon Web Services (AWS), Alteryx, Inc., Google Cloud Platform, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytics Sandbox Market Strategic Shifts
Ephemeral compute provisioning is compressing traditional data infrastructure procurement cycles from months to minutes, forcing vendors to rearchitect around consumption-based billing and automated policy enforcement.
Serverless Spark runtimes are rendering obsolete fixed-cluster provisioning models that required capacity planning weeks in advance. Quantitative analysts at hedge funds and asset managers adopt these architectures within days of initial deployment. The shift is rendering obsolete traditional data platform vendors whose licensing models depend on predictable annual compute commitments.
The EU AI Act's risk-classification framework mandates algorithmic auditability for high-risk applications including credit scoring and insurance pricing. Sandbox providers must embed explainability tooling and lineage tracking into provisioning workflows. European financial services firms are responding by demanding ISO 27001-certified environments with pre-configured compliance guardrails.
Self-service provisioning portals are displacing ticket-based IT requests for analytics environment setup. Business analysts at retail and logistics firms now spin up Python and R sandboxes through browser interfaces without infrastructure team involvement. This pattern is most visible in Singapore and Hong Kong, where data science team autonomy ranks higher on organizational priority lists than centralized governance control.
Analytics Sandbox Market Segmentation
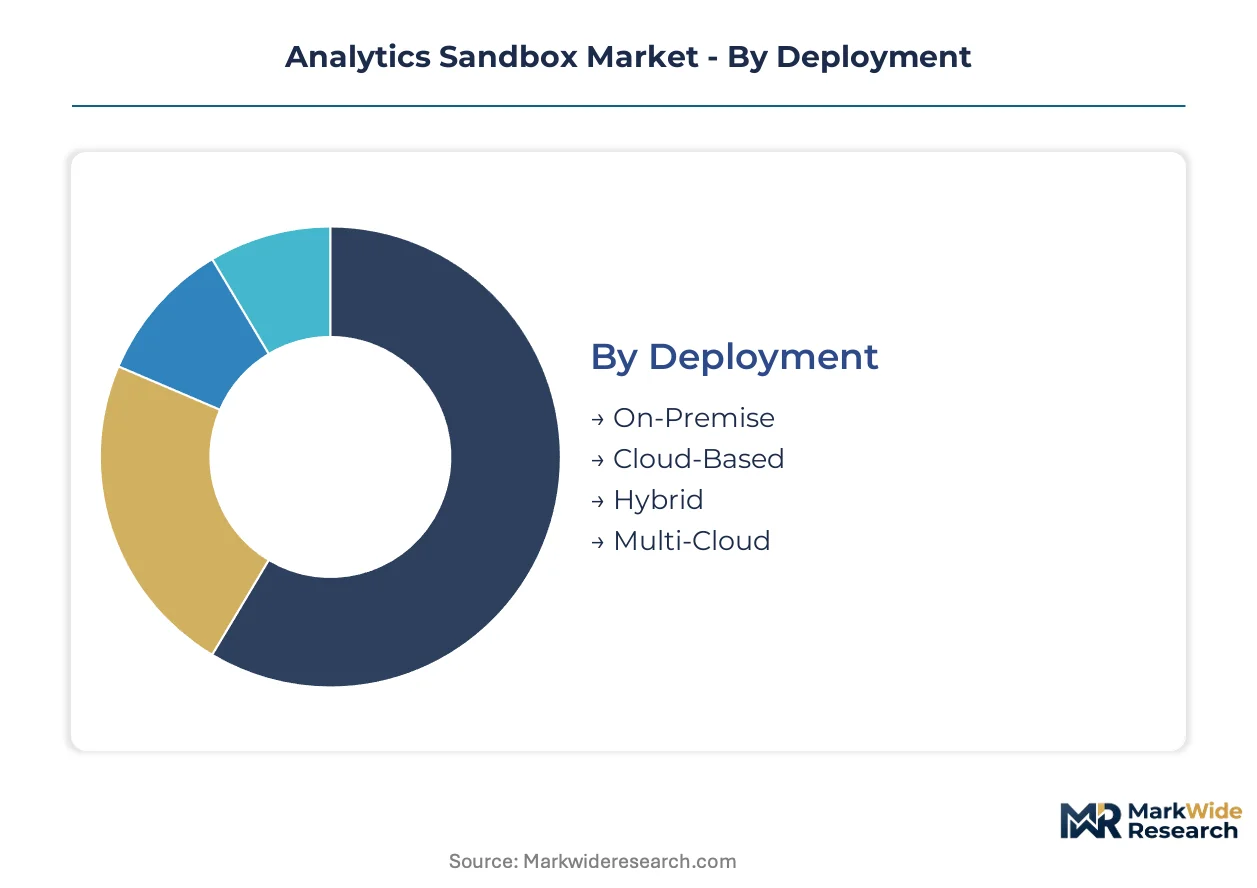
Segmentation in the analytics sandbox market reveals distinct procurement patterns across infrastructure preferences, organizational scale, and analytical sophistication. Deployment models dictate architectural trade-offs between elasticity and control. End-user categories separate volume buyers from margin-rich specialized implementations.
Deployment:
Use-case spectrum spans regulated financial institutions requiring air-gapped environments to agile startups prioritizing burst compute capacity.
- Cloud-Based:Elastic resource provisioning enables GPU-accelerated model training without capital expenditure commitment. Financial services firms in Singapore and Hong Kong favor this model under MAS and HKMA data sovereignty guidelines that now permit certified cloud configurations. The dominant share belongs to Cloud-Based, while Multi-Cloud is closing the gap fastest.
- On-Premise:Fixed-capacity installations maintain complete data custody within organizational firewalls. US healthcare providers configure these under HIPAA constraints for protected health information experimentation, accepting higher total cost of ownership for audit certainty.
- Hybrid:Split architectures reserve sensitive data processing on-premise while bursting non-critical workloads to cloud infrastructure. Australian banks adopt this pattern to satisfy APRA prudential standards without sacrificing computational flexibility.
- Multi-Cloud:Orchestration across AWS, Azure, and GCP reduces vendor lock-in and optimizes spot pricing arbitrage. Hedge funds deploy these configurations to minimize latency to exchange co-location facilities regardless of cloud provider.
Cloud configurations concentrate revenue, though hybrid architectures retain strategic importance in regulated jurisdictions.
End User:
Customer scale determines sandbox governance complexity and procurement authority centralization.
- Enterprises:Fortune 500 manufacturers provision department-specific sandboxes through centralized IT with pre-configured ISO 27001 guardrails. These deployments generate the highest per-seat revenue through premium support tiers and custom integration services.
- Small Businesses:Browser-based self-service portals from specialized vendors eliminate infrastructure team dependencies. Retail and logistics firms in Hong Kong prioritize analyst autonomy over centralized governance, accelerating adoption curves.
- Government Agencies:FedRAMP-authorized environments constrain vendor selection to pre-approved cloud service providers. US federal data science teams require classified and unclassified sandbox tiers with mandatory audit trails.
- Academic Institutions:Research universities leverage educational licensing to provide student access to Python, R, and Spark runtimes. These deployments emphasize pedagogical flexibility over production-grade security primitives.
Enterprise accounts dominate absolute revenue, while small business adoption expands most quickly through consumption-based pricing.
Application:
Functional intensity separates exploratory analytics from production-destined model development.
- Machine Learning:GPU-intensive training pipelines demand ephemeral environments with strict cost controls. Quantitative analysts at asset managers adopt serverless Spark runtimes within days of deployment, displacing fixed-cluster provisioning.
- Predictive Modelling:Stress-testing engines for Basel III capital requirements drive financial services procurement. Singaporean banks configure these sandboxes to simulate portfolio losses under regulatory scrutiny.
- Data Analysis:SQL and Python exploration of structured datasets without production system risk. Business analysts at logistics firms spin up these environments through self-service portals.
- Visualization:Dashboard prototyping and ad-hoc charting for executive presentation preparation. These lighter workloads tolerate higher latency than model training use cases.
Machine Learning commands premium pricing, though Predictive Modelling shows steepest expansion trajectory in Asia-Pacific financial centers.
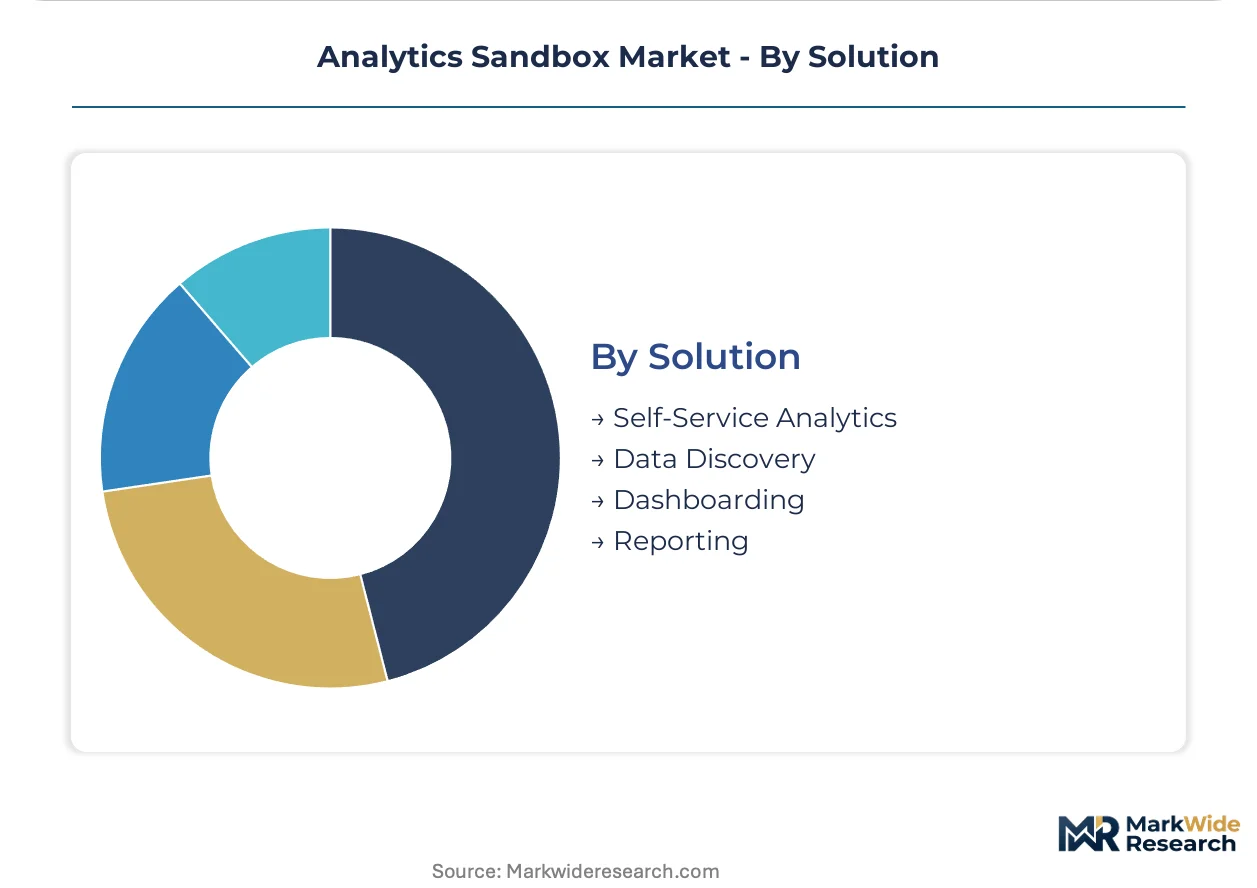
Solution:
Capability depth stratifies margin pools from basic reporting to governed self-service.
- Self-Service Analytics:Business-user provisioning without IT ticket submission accelerates time-to-insight. These solutions capture disproportionate margin by reducing infrastructure team bottlenecks.
- Data Discovery:Automated lineage tracking and metadata cataloging for regulatory audit preparation. EU AI Act compliance requirements elevate demand for these capabilities in European financial services.
- Dashboarding:Pre-built visualization templates with governance-controlled data access. These implementations emphasize standardization over analytical flexibility.
- Reporting:Scheduled distribution of static outputs to defined recipient lists. Legacy-dominated enterprises maintain substantial investments in this category despite limited growth.
Self-Service Analytics leads revenue contribution, while Data Discovery gains share fastest under tightening algorithmic accountability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports analytics sandbox expertise to Australian banks seeking compliant cloud configurations under harmonized Asia-Pacific data sovereignty frameworks.
United States
Financial services firms in New York and Chicago deploy predictive modeling environments to stress-test portfolios under SEC and Federal Reserve scrutiny. FedRAMP authorization pathways govern cloud sandbox deployments across federal agencies. The Boston-Cambridge corridor concentrates machine learning practitioner demand from quantitative hedge funds.
Singapore
Monetary Authority of Singapore guidelines permit certified cloud configurations for Basel III capital requirement testing. The city-state's data sovereignty framework matures faster than regional peers, attracting regional headquarters of global banks. Marina Bay financial district hosts concentrated demand for GPU-accelerated model training environments.
Germany
Automotive manufacturers in Stuttgart and Munich configure sandboxes for supply chain risk modeling under EU AI Act algorithmic audit requirements. BSI information security standards shape procurement specifications for cross-border data experimentation. Frankfurt's financial sector drives predictive analytics adoption for credit risk assessment.
Australia
APRA prudential standards push banks toward hybrid architectures that reserve sensitive data processing on-premise while bursting non-critical workloads to cloud infrastructure. Sydney and Melbourne concentrate fintech sandbox demand for regulatory technology solutions. The country's data residency mandates favor domestic cloud provider partnerships.
United Kingdom
FCA regulatory sandboxes for financial services innovation complement technical analytics environments in London's Square Mile. GDPR compliance requirements elevate demand for ISO 27001-certified environments with pre-configured data protection guardrails. Edinburgh's asset management cluster adopts ephemeral compute for portfolio optimization workflows.
Analytics Sandbox Market Competitive Environment
On the supply side, the industry is consolidating around cloud hyperscalers and specialized data platform vendors. Tiered competition separates infrastructure-anchored ecosystems from security-embedded specialists. Three archetypes dominate: hyperscale cloud providers with native analytics stacks, lakehouse architecture specialists unifying batch and streaming workloads, and cybersecurity-first vendors embedding zero-trust primitives. M&A activity concentrates on API-driven modularization capabilities, while strategic partnerships target cross-border compliance certification.
Within the hyperscale tier, Microsoft Corporation and Amazon Web Services anchor enterprise-grade offerings through integrated cloud ecosystems. Databricks Inc. exemplifies the lakehouse-specialist archetype with unified runtime environments. Palo Alto Networks, Inc. occupies the security-embedded position for regulated industries requiring zero-trust provisioning workflows.
| Leading Market Players |
|---|
| Oracle Corporation |
| Databricks Inc. |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Palo Alto Networks, Inc. |
| Amazon Web Services (AWS) |
| Alteryx, Inc. |
| Google Cloud Platform |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
GPU cluster concentration in Taiwan and South Korea anchors upstream compute infrastructure, directing margin capture toward cloud orchestration layers and compliance-certified managed services rather than raw hardware provisioning.
Pricing Analysis
Current-generation GPU-accelerated sandboxes command substantial premiums over CPU-only prior-generation offerings, while next-generation quantum-ready environments remain pre-commercial. Three-tier pricing structure across premium FedRAMP-certified, standard enterprise, and economy self-service levels dominates procurement. Price differentiation hinges on ISO 27001 certification tier and geographic data residency guarantees. Pricing pressure stems from hyperscaler spot-pricing arbitrage compressing margins for mid-tier vendors. Small business adopters exhibit highest price sensitivity, while regulated financial services accept premium tiers for audit certainty.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for hardware-dependent sandbox providers. Taiwan, South Korea, and the United States concentrate advanced GPU and specialized AI accelerator manufacturing. Raw material dependencies span high-bandwidth memory modules, liquid cooling systems, and sovereign cloud infrastructure partnerships. Single-source vulnerability in NVIDIA GPU supply constrains capacity scaling for training-intensive workloads. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with compliance pre-certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organizations struggle to staff sandbox governance roles requiring simultaneous Kubernetes orchestration expertise and regulatory compliance fluency, creating structural bottlenecks that constrain market expansion regardless of technology availability.
For Market Incumbents: Insulate core revenue streams by embedding zero-trust security primitives deeper into provisioning workflows before Palo Alto Networks-style specialists capture regulated industry accounts. Prioritize FedRAMP authorization investments to defend government segment position against emerging cloud-native entrants. Extend backward integration into sovereign cloud infrastructure partnerships across Singapore and Hong Kong to lock in data residency-compliant capacity. For New Entrants and Emerging Players: Build out ISO 27001-certified managed service offerings targeting European financial services under EU AI Act algorithmic audit mandates, where incumbent hyperscalers lack pre-configured compliance guardrails. Concentrate initial deployment in Australia where APRA prudential standards create hybrid architecture demand underserved by pure-cloud vendors. Position through channel partnerships with regional system integrators possessing existing banking relationships rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital is best deployed toward API-driven modularization specialists enabling enterprises to assemble sandboxes from specialized vendors rather than single-stack providers. Long-term viability favors vendors with demonstrated cross-border certification velocity spanning FedRAMP, MAS, and BSI frameworks. Monitor MAS and HKMA guideline evolution as early signal for regional cloud adoption inflection, with accelerated certification timelines indicating demand surge ahead of supply response.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Pathway | Unlocks US federal agency procurement requiring classified and unclassified data experimentation tiers. |
| Lakehouse Architecture Integration | Captures Databricks-style unification of batch and streaming workloads within single-runtime environments. |
| Zero-Trust Security Embedding | Addresses Palo Alto Networks-competitive positioning for regulated financial and healthcare sectors. |
| ISO 27001 Certification Arbitrage | Enables Singapore and Hong Kong regional headquarters capture under maturing data sovereignty frameworks. |
| Serverless Spark Runtime Launch | Displaces fixed-cluster provisioning models through ephemeral, consumption-billed compute for quantitative analysts. |
Study Parameters
A spread of perspectives from cloud infrastructure architects, regulatory compliance officers at multinational banks, data science team leads, and hyperscaler partnership managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from Databricks and Palo Alto Networks, MAS and HKMA regulatory guideline publications, and hyperscaler capex disclosure patterns. Bottom-up segment sizing triangulated against top-down market boundary checks from trade data and enterprise IT spending surveys.
Demand-supply-balance framing anchored the analytical framework across deployment models, end-user scale tiers, application intensity levels, and solution capability depths over the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by regional adoption curves and technology substitution elasticities. GPU availability constraints and FedRAMP authorization queue lengths served as industry-specific forecast inputs moderating supply-side expansion assumptions.
Practitioners should monitor MAS guideline revisions, EU AI Act implementing regulation releases, and NVIDIA supply allocation announcements for early signals of forecast deviation. Macroeconomic contraction in financial services IT spending, sovereign cloud infrastructure delays, or breakthroughs in quantum-safe encryption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Development Analytics Tools Market
Analytics
Global Telco Data Monetization Market
Analytics
Global Sentiment Analytics Software Market
Analytics
Global Wi-Fi Analytics Market
Analytics
CSP Network Analytics Market
Analytics
Global Performance Analytics Market
Analytics
Crowd Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Cyprus ICT Market
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
Investigative Analytics Market
Analytics
Workforce Analytics Market
Analytics
Global Operational Analytics Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
App Analytics Tools Market
Analytics
Big Data in Automotive Market