
 United States Geospatial Analytics Market | 2026-2036
United States Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Geospatial Analytics Market Insights
Subscription-based platform access is rebalancing how geospatial capabilities reach mid-sized engineering firms and municipal agencies. Esri sustains dominance through its ArcGIS ecosystem and deep integration with federal mapping standards. Hexagon AB leverages sensor-to-software pipelines across transportation and utility verticals. Maxar Technologies anchors high-resolution satellite imagery supply for defense and intelligence applications.
Geospatial analytics encompasses the computational processing of location-referenced data through spatial statistics, remote sensing algorithms, and geographic information systems to generate actionable intelligence for asset positioning, terrain modeling, and pattern recognition. The technology relies on coordinate reference systems, spectral band analysis, and vector-raster data fusion to transform raw positional feeds into decision-ready visualizations. Software platforms capture the dominant margin pool as recurring license revenue outpaces hardware sensor sales. Cloud Solutions represent the fastest-expanding delivery mode as agencies migrate from on-premise server farms to elastic federal-compliant architectures. Remote Sensing technology leads volume throughput given orbital and aerial imagery proliferation across agriculture and environmental monitoring applications.
The Federal Aviation Administration shapes commercial drone operations through Part 107 waivers and remote ID mandates that expand aerial data collection permissions. The National Geospatial-Intelligence Agency sets accuracy and interoperability standards that determine vendor eligibility for classified and unclassified contracts. State-level open data statutes in California, New York, and Texas further fragment procurement requirements across jurisdictions. Stakeholders must monitor evolving federal cloud security authorization timelines and state privacy restrictions on location data aggregation.
Market Dynamics
Federal cloud migration mandates are compressing procurement cycles for geospatial platforms as agencies abandon on-premise server infrastructure. The FAA's remote ID rulemaking for commercial drones is accelerating sensor network deployment across state and local jurisdictions.
Growth Catalysts
- Remote sensing infrastructure:Orbital and aerial imagery proliferation is expanding coverage for agriculture and environmental monitoring applications. Spectral band analysis capabilities are improving crop yield prediction accuracy.
- FAA Part 107 waivers:Expanded commercial drone operation permissions are multiplying aerial data collection points across metropolitan and rural zones. Flight authorization automation is reducing operational friction.
- California precision agriculture:Real-time subsurface monitoring deployments in Central Valley corridors are commanding premium platform installations. Water stress mapping is driving recurring subscription demand.
Market Restraints
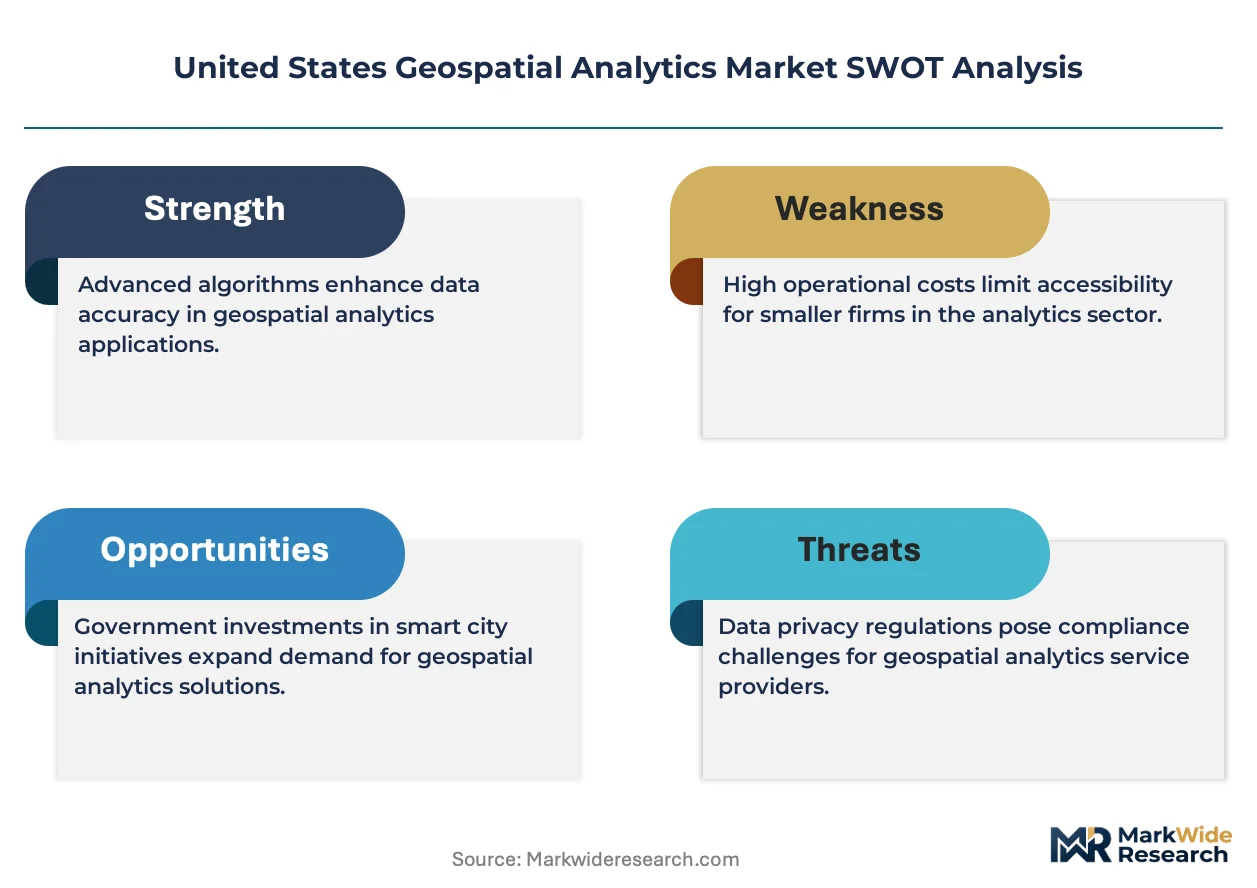
- Cloud security authorization timelines:FedRAMP compliance requirements are extending vendor onboarding cycles by 12-18 months. Federal agencies face procurement delays for unapproved architectures.
- High-resolution satellite imagery costs:Defense and intelligence-grade spectral data commands per-square-kilometer pricing that excludes municipal budgets. Commercial alternatives lack sufficient resolution for critical infrastructure assessment.
- State privacy fragmentation:California, New York, and Texas maintain divergent statutes on location data aggregation. Cross-jurisdictional platform deployment requires redundant compliance architecture.
Strategic Opportunities
- Texas energy basin monitoring:Real-time subsurface analytics for Permian and Eagle Ford operations remain underpenetrated. Methane detection and pipeline integrity applications command premium pricing.
- LiDAR-synthetic aperture radar fusion:Converging active and passive sensing technologies are enabling all-weather terrain modeling. Transportation departments are piloting fused datasets for flood prediction.
- Subscription platform access:Mid-sized engineering firms and municipal agencies are adopting recurring license models. Esri's ArcGIS ecosystem is capturing this transition through tiered service tiers.
Industry Challenges
- Geospatial data scientist scarcity:Spatial statistics and remote sensing algorithm expertise concentrates in defense contractors and federal agencies. Commercial sector recruitment competes against security-cleared compensation premiums.
- Legacy GIS integration complexity:Decades of on-premise ArcGIS deployments resist cloud-native migration. Custom toolboxes and proprietary coordinate reference systems require expensive re-engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Geospatial Analytics Market |
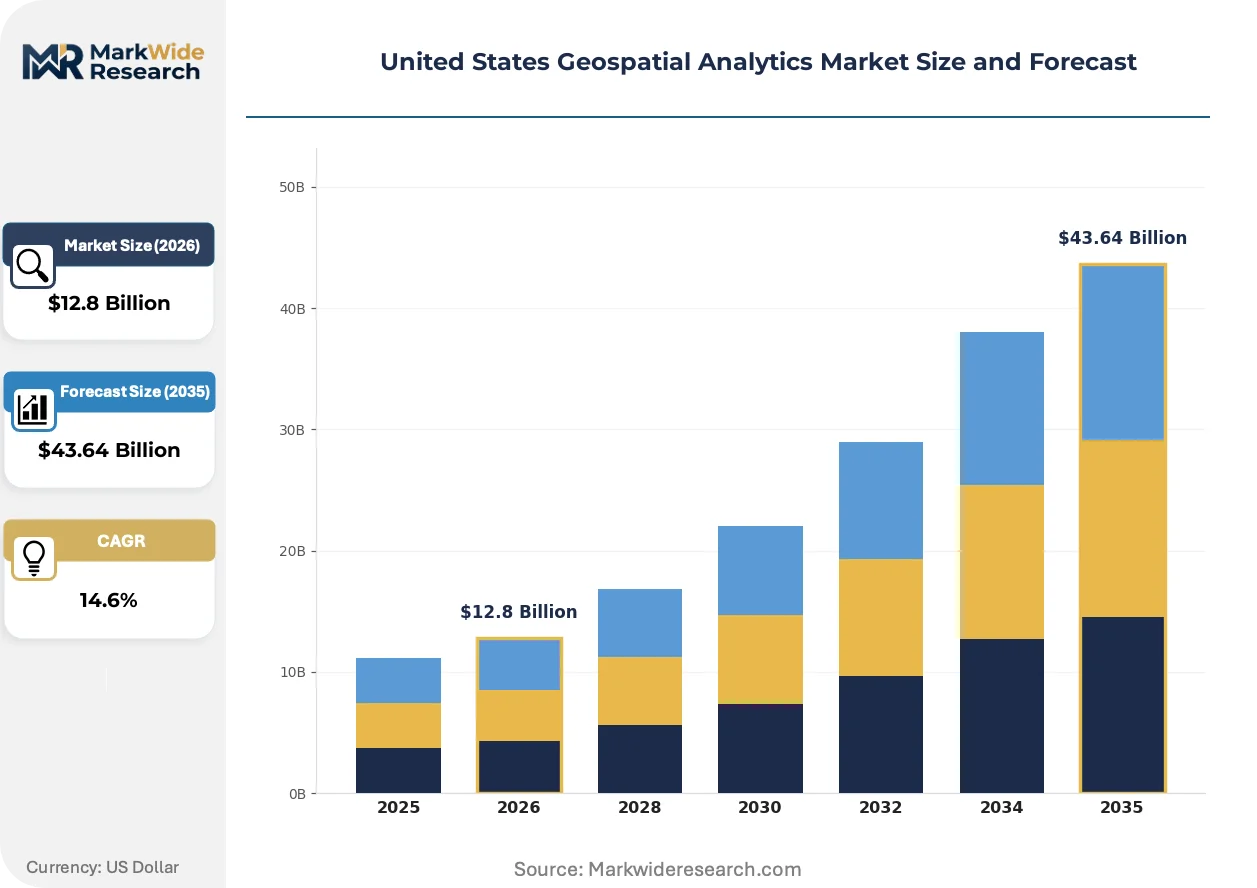
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions Technology: Remote Sensing, GIS, GPS, Satellite Imaging End User: Government, Transportation, Agriculture, Energy Application: Urban Planning, Disaster Management, Environmental Monitoring, Asset Management |
| Companies Covered | Esri, Hexagon AB, Maxar Technologies, Trimble Inc., HERE Technologies, Google LLC, Bentley Systems, Inc., Alteryx Inc., L3Harris Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Geospatial Analytics Market Trends and Innovations
Computational advances in edge processing and spectral analysis are compressing the latency between sensor capture and decision-ready intelligence. Platform vendors are repositioning around real-time rather than retrospective analytics.
Digital twin technology is converging with geospatial foundation layers to create dynamic infrastructure replicas. State departments of transportation are adopting these fused models for bridge and highway lifecycle management. The convergence is displacing static CAD-based asset registers with continuously updated spatial databases.
The FAA's remote ID mandate for commercial drones is standardizing broadcast requirements for position, altitude, and velocity data. Hardware manufacturers must embed compliant transponders or face airspace exclusion. Agricultural operators in California's Central Valley are retrofitting existing fleets to maintain spraying operation permissions.
Utility procurement departments are unbundling imagery acquisition from analytics processing. Municipal water districts now subscribe to platform APIs rather than purchasing bundled sensor-software packages. This pattern is most visible in Texas, where independent water authorities negotiate direct satellite tasking while licensing cloud-based change detection algorithms separately.
United States Geospatial Analytics Market Segmentation
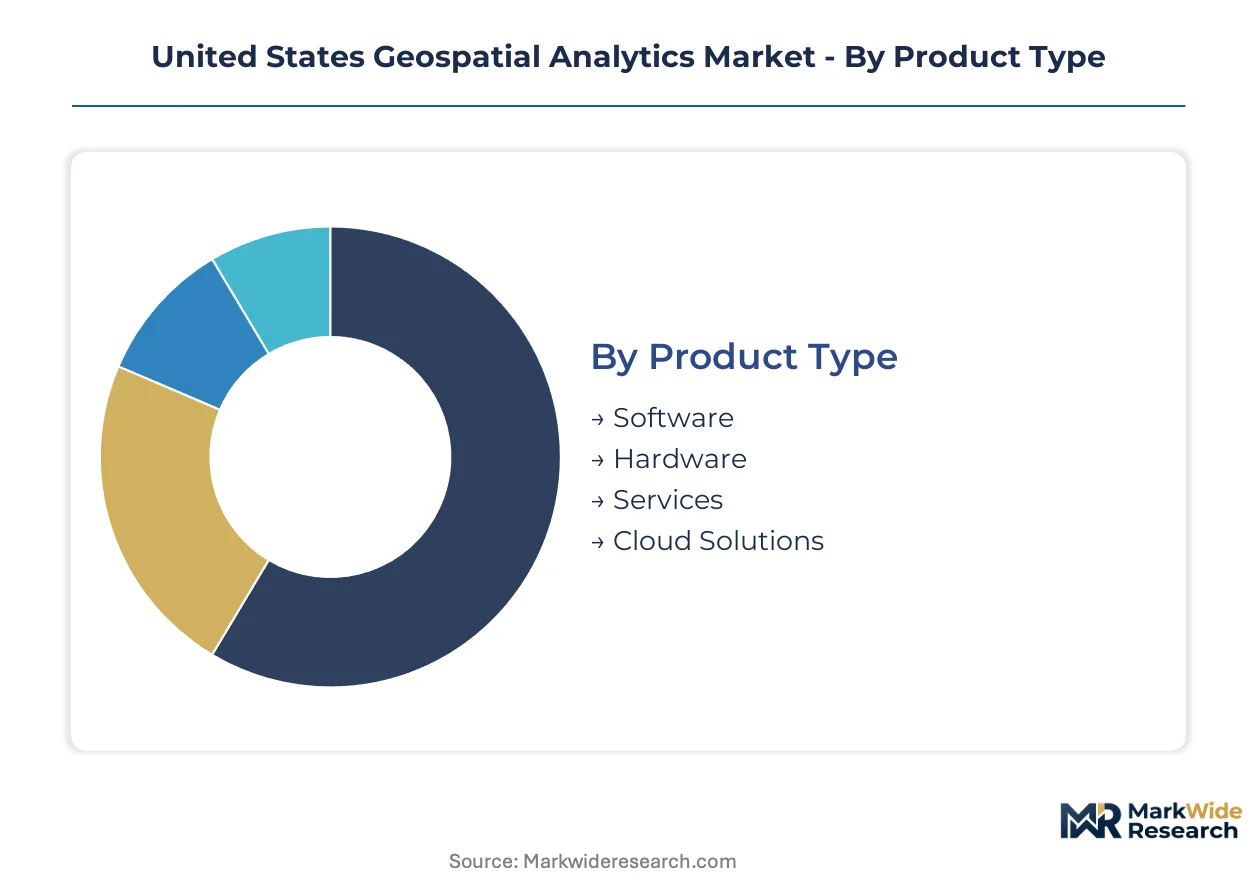
Geospatial analytics procurement splits between standalone platform purchases and embedded sensor-software bundles. Understanding where integration depth varies reveals margin concentration and vendor positioning across federal, state, and commercial deployments.
Product Type:
Standalone platforms dominate enterprise procurement while embedded configurations anchor industrial IoT deployments.
- Software:ArcGIS-compatible platforms and cloud-native analytics engines process vector-raster fusion and spatial statistics. Federal agencies in Virginia and Maryland drive recurring license demand through FedRAMP-authorized deployments. Procurement compresses as cloud migration mandates accelerate.
- Cloud Solutions:Elastic federal-compliant architectures replace on-premise server farms. California water districts and Texas energy operators subscribe to API-accessible change detection rather than owning processing infrastructure. This segment climbs fastest as municipal budgets shift from capital to operational expenditure.
- Hardware:GNSS receivers, LiDAR units, and spectral sensors capture field data.
- Services:Implementation consulting and custom tool development bridge legacy GIS migrations.
Volume placements concentrate in Software; the faster expansion belongs to Cloud Solutions.
Technology:
Passive sensing technologies saturate agriculture and environmental monitoring while active systems penetrate energy and transportation infrastructure.
- Remote Sensing:Orbital and aerial imagery platforms capture multispectral and hyperspectral data through spectral band analysis. Central Valley agricultural corridors and Gulf Coast environmental monitoring stations deploy these systems at scale. Water stress mapping and crop yield prediction anchor recurring demand.
- GIS:Coordinate reference systems and spatial databases manage asset positioning and terrain modeling. State departments of transportation in Texas and California maintain the largest installed bases. Legacy on-premise deployments resist cloud-native migration.
- GPS:Precision positioning systems enable centimeter-level asset tracking.
- Satellite Imaging:High-resolution tasking supports defense and intelligence applications.
Revenue concentrates in Remote Sensing; steepest expansion trajectory sits with GIS as cloud architectures displace server-based installations.
End User:
Federal procurement sets interoperability standards while state and commercial adoption follows funding availability and regulatory mandate timelines.
- Government:Federal agencies including the FAA, NGA, and USGS define accuracy requirements and data sharing protocols. Infrastructure resilience planning and classified intelligence applications command premium platform specifications. FedRAMP compliance timelines extend vendor onboarding cycles.
- Agriculture:California Central Valley operators deploy precision agriculture platforms for subsurface moisture monitoring and automated irrigation. FAA Part 107 waivers enable aerial spraying coordination. Real-time analytics subscriptions outpace hardware purchases.
- Transportation:State DOTs pilot digital twin integration for bridge lifecycle management.
- Energy:Permian and Eagle Ford operators monitor methane emissions and pipeline integrity.
Budget authority concentrates in Government; Agriculture gains share fastest as water stress intensifies subscription demand.
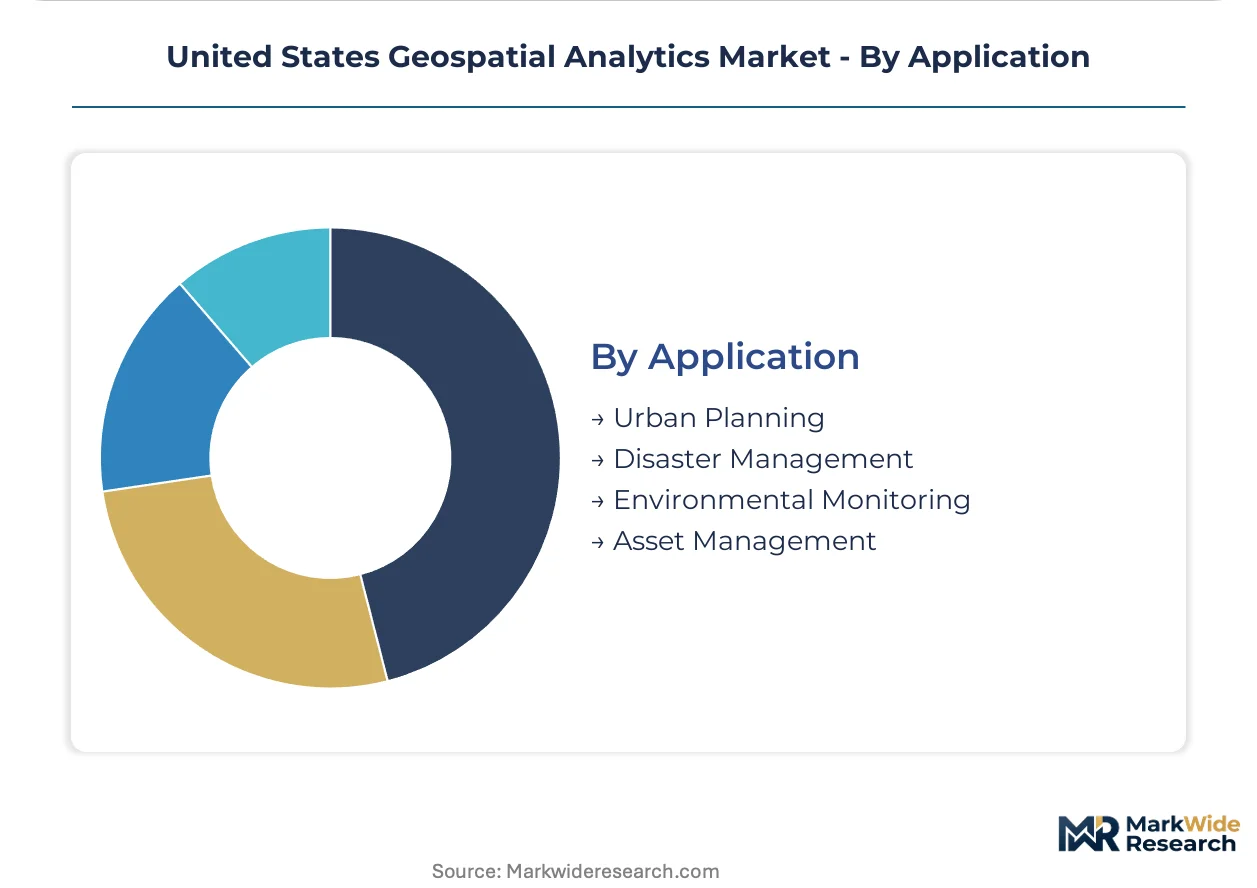
Application:
Reactive monitoring applications mature while predictive and prescriptive use cases capture incremental platform investment.
- Environmental Monitoring:Spectral analysis tracks watershed health, wildfire risk, and coastal erosion across federal land management agencies and state environmental departments. California and Florida deploy the densest sensor networks. Regulatory reporting requirements sustain recurring data collection contracts.
- Asset Management:Utility districts and transportation departments maintain spatial databases of critical infrastructure. Texas water authorities unbundle imagery acquisition from analytics processing. API-based change detection replaces bundled sensor-software procurement.
- Urban Planning:Zoning departments and real estate developers model population density and infrastructure capacity.
- Disaster Management:FEMA coordination and state emergency response teams deploy rapid damage assessment workflows.
Deployment scale concentrates in Environmental Monitoring; Asset Management expands most quickly as utility procurement unbundles hardware from software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California generates the highest platform consumption while federal procurement concentrates in the Virginia-Maryland corridor. Texas energy operators drive hardware sensor deployments. Midwest agricultural networks expand remote sensing coverage.
California
Central Valley precision agriculture operators deploy subsurface moisture monitoring for automated irrigation coordination. The state's open data statutes mandate location transparency for water district planning. Los Angeles and San Francisco Bay Area municipal agencies pilot digital twin integration for infrastructure lifecycle management.
Texas
Permian and Eagle Ford energy basins command premium methane detection and pipeline integrity analytics. State water authorities unbundle imagery acquisition from cloud-based change detection algorithms. Houston and Dallas-Fort Worth metropolitan zones concentrate utility procurement departments.
Virginia-Maryland Corridor
Federal agencies including the NGA and USGS define accuracy requirements and interoperability standards. FedRAMP compliance timelines extend vendor onboarding cycles for cloud-native platform deployment. Northern Virginia data center clusters host elastic federal-compliant architectures.
Midwest Agricultural Belt
Illinois and Iowa corn-soybean operators adopt spectral band analysis for crop yield prediction. FAA Part 107 waivers enable aerial spraying coordination across rural zones. Chicago serves as regional hub for agricultural data analytics consulting.
Pacific Northwest
Washington and Oregon environmental monitoring stations track watershed health and wildfire risk through dense sensor networks. State environmental departments sustain recurring data collection contracts for regulatory reporting. Seattle anchors commercial remote sensing algorithm development.
United States Geospatial Analytics Market Competitive Landscape
Capital-heavy satellite operators compete with asset-light software platform designers for margin capture in geospatial analytics. The vendor base concentrates around three strategic tiers: full-stack platform ecosystems, sensor-to-software pipeline specialists, and high-resolution imagery providers. Dominant competitive moves include cloud-native architecture migration and unbundled API service offerings that separate hardware acquisition from analytics processing.
Within the full-stack platform tier, Esri anchors ecosystem dominance through ArcGIS-compatible deployments. Hexagon AB and Maxar Technologies occupy positions across sensor-software integration and defense-grade imagery supply respectively. These three exemplify how vendor archetypes map to federal procurement requirements, state-level open data mandates, and commercial subscription transitions.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Maxar Technologies |
| Trimble Inc. |
| HERE Technologies |
| Google LLC |
| Bentley Systems, Inc. |
| Alteryx Inc. |
| L3Harris Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Federal procurement concentration in Virginia-Maryland corridor agencies anchors subscription-based pricing power for cloud-native geospatial platforms. FedRAMP compliance timelines extend vendor onboarding cycles, compressing price competition among authorized providers while state water authorities in Texas and California drive unbundled API service demand.
Pricing Analysis
Cost-down pressure on municipal and mid-sized engineering firm segments accelerates because cloud migration mandates shift capital expenditure to operational subscription models. Three-tier pricing structure across premium, standard, and economy levels differentiates by data resolution grade and FedRAMP certification tier. Esri's ArcGIS ecosystem commands brand premium through federal mapping standard integration. Price differentiation hinges on spectral band analysis depth and real-time processing latency. State environmental departments exhibit highest price sensitivity; defense and intelligence agencies demonstrate lowest sensitivity due to mission-critical requirements.
Supply Chain Analysis
Direct-to-federal channels handle hyperscale agency demand while API marketplaces serve unbundled municipal procurement. Satellite imagery supply concentrates in United States, Canada, and select European orbital operators. Component dependencies include spectral sensors, GNSS receivers, and edge processing units. Supply chain risk centers on single-source vulnerability for defense-grade high-resolution tasking. Distribution runs through FedRAMP-authorized cloud architectures and legacy on-premise system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedRAMP compliance timelines and cloud security authorization bottlenecks force consolidation among subscale platform vendors unable to sustain 12-18 month onboarding cycles. Market structure favors full-stack ecosystem providers with existing federal certification.
For Market Incumbents: Deploy API unbundling strategies to capture municipal procurement transitioning from bundled sensor-software packages. Esri must accelerate cloud-native migration tool development to displace legacy on-premise ArcGIS resistance. Hexagon AB should deepen sensor-to-software pipeline integration across transportation verticals. Threat vector: pure-play SaaS entrants exploiting FedRAMP authorization delays with pre-certified architectures. For New Entrants and Emerging Players: Cloud marketplace routes offer lowest-friction entry for LiDAR-SAR fusion analytics targeting state departments of transportation. Texas energy basin methane detection and Permian pipeline integrity monitoring represent most penetrable white-space. California Central Valley water stress mapping subscriptions provide recurring revenue anchor. Go-to-market angle: pre-integrated FAA Remote ID compliance modules for agricultural drone operators. For Investors and Strategic Acquirers: The window for entry favors FedRAMP-authorized platform specialists with proven federal contract vehicles. Long-term viability requires sustained R&D investment in real-time edge processing and spectral analysis algorithms. Acquisition target archetype: cloud-native analytics engines with existing NGA interoperability certification. Signal to watch: state-level open data statute harmonization reducing cross-jurisdictional compliance fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Esri's ArcGIS ecosystem deepens federal mapping standard lock-in across Virginia-Maryland procurement. |
| Strategic Partnership | Hexagon AB's sensor-to-software pipelines capture Texas DOT digital twin pilots for bridge lifecycle management. |
| Acquisition of Specialist Firm | LiDAR-SAR fusion capabilities enable all-weather terrain modeling for FEMA disaster response coordination. |
| Geographic Expansion | California Central Valley precision agriculture corridors command premium subsurface moisture monitoring deployments. |
| Product Launch | FAA Remote ID compliant transponder modules secure agricultural spraying operation permissions across metropolitan zones. |
Research Methodology
SEC filings, USGS technical documentation, and FAA regulatory dockets formed the secondary backbone for vendor positioning and federal procurement pattern analysis. Primary interviews with platform engineering directors, federal procurement officers at NGA and USGS, state DOT geospatial coordinators, and agricultural technology integration specialists validated demand segmentation. Bottom-up and top-down triangulation reconciled subscription revenue models with sensor hardware shipment data across California, Texas, and Virginia-Maryland corridors.
Bottom-up modeling aggregated individual platform deployment values across federal, state, and commercial end-user segments. Segmentation dimensions included deployment model (cloud-native versus on-premise), technology type (remote sensing, GIS, GPS, satellite imaging), end-user vertical, and application use case. CAGRs derived from elasticity-adjusted adoption curves incorporating FedRAMP authorization timeline impacts and state privacy statute fragmentation effects. Industry-specific inputs included FAA Part 107 waiver issuance rates and California water district open data mandate compliance progression.
The model holds under sustained federal cloud migration mandates and stable FAA regulatory frameworks; deviation in state privacy statute harmonization or defense budget reallocation would shift platform demand trajectories. Periodic stress-testing of base assumptions against NGA accuracy standard revisions and emerging LiDAR-SAR fusion technology cost curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Product Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Cloud-Based Predictive Analytics Platform Market
Analytics
Speech Analytics Market
Analytics
Marketing Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
App Analytics Tools Market
Analytics
Augmented Analytics Market
Analytics
North America HR Analytics Market
Analytics
TV Analytics Solutions Market
Analytics
North America Location Analytics Market
Analytics
Attribution Software Market
Analytics
Global Analytics Software Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Digital Analytics Solutions Market
Analytics
Text Analytics Market