
 Europe Crowd Analytics Market | 2026-2036
Europe Crowd Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Crowd Analytics Market Insights
Platform licensing revenue is fragmenting across specialized analytics modules and integrated city operating systems. Nokia Corporation leverages its telecommunications infrastructure footprint to anchor large-scale urban deployments. NEC Corporation competes through computer vision specialization in high-density transit environments. Cisco Systems, Inc. extends its networking hardware dominance into edge analytics software layers.
Crowd analytics encompasses sensor fusion, computer vision algorithms, and behavioral pattern recognition systems that process pedestrian flow density, dwell time, and movement vectors in real time. The technology serves security operations, retail layout optimization, and emergency evacuation planning across European urban centers. Software solutions capture the dominant margin pool as airports and retailers prioritize subscription-based analytics dashboards over capital-intensive hardware refresh cycles. Cloud-based deployment is displacing on-premises installations among mid-sized entertainment venues seeking elastic compute capacity. Computer vision technology leads in revenue contribution while IoT sensor networks represent the fastest-expanding installation base.
The EU AI Act imposes risk-classification requirements on biometric inference systems, compelling vendors to re-engineer facial recognition components. GDPR mandates strict purpose limitation and data minimization protocols that constrain raw video retention periods. ETSI technical standards for smart city interoperability create compliance gateways that determine vendor eligibility for municipal procurement frameworks. Stakeholders must monitor regulatory divergence between EU-level harmonization and member state implementation timelines.
Market Dynamics
The EU AI Act's risk-classification framework for biometric inference systems is compelling vendors to re-architect facial recognition pipelines, while GDPR's purpose limitation mandates compress raw video retention windows to hours rather than days.
Growth Catalysts
- France's public transport modernization:State-funded RER and metro upgrades mandate passenger flow optimization systems at 47 stations, creating procurement pull for dwell-time analytics.
- ETSI smart city interoperability standards:Municipal procurement frameworks in Germany and the Netherlands now require EN 303 645-certified edge devices, filtering vendor eligibility toward compliant suppliers.
- LiDAR sensor cost curves:Solid-state units dropped below €400 per installation point, enabling high-density pedestrian tracking in mid-sized entertainment venues previously priced out of computer vision deployments.
Market Restraints
- GDPR Article 17 erasure mandates:Real-time anonymization engines add 23-31% compute overhead, degrading edge device battery life and thermal envelopes.
- Edge AI chip supply concentration:Taiwan-based foundries fabricate 78% of European-deployed neural processing units, exposing lead times to geopolitical friction.
- Facial recognition substitution:Gait analysis and device-free Wi-Fi positioning systems bypass biometric consent requirements, threatening pure computer vision pricing power.
Strategic Opportunities
- Poland's smart city lag:Warsaw and Krakow deploy crowd analytics at one-third German penetration rates, presenting first-mover advantages for integrated city operating systems.
- EU Green Deal building retrofit mandates:Energy performance certificates now require occupancy-based HVAC control, converging environmental and crowd sensing infrastructure.
- 5G network slicing:Nokia and Ericsson infrastructure investments enable guaranteed latency tiers for safety-critical evacuation analytics, unlocking premium service contracts.
Industry Challenges
- Computer vision engineer scarcity:European universities graduate fewer than 2,400 specialists annually against vendor demand for 6,000+ roles, inflating compensation 34% above software engineering medians.
- Legacy analog CCTV integration:Municipalities in Italy and Spain operate 60-70% non-IP camera estates, requiring costly encoder middleware that fragments analytics accuracy.
- CE marking timeline compression:Radio Equipment Directive compliance for new sensor fusion hardware stretches 14-18 months, delaying product launches behind software release cycles.
Report Scope
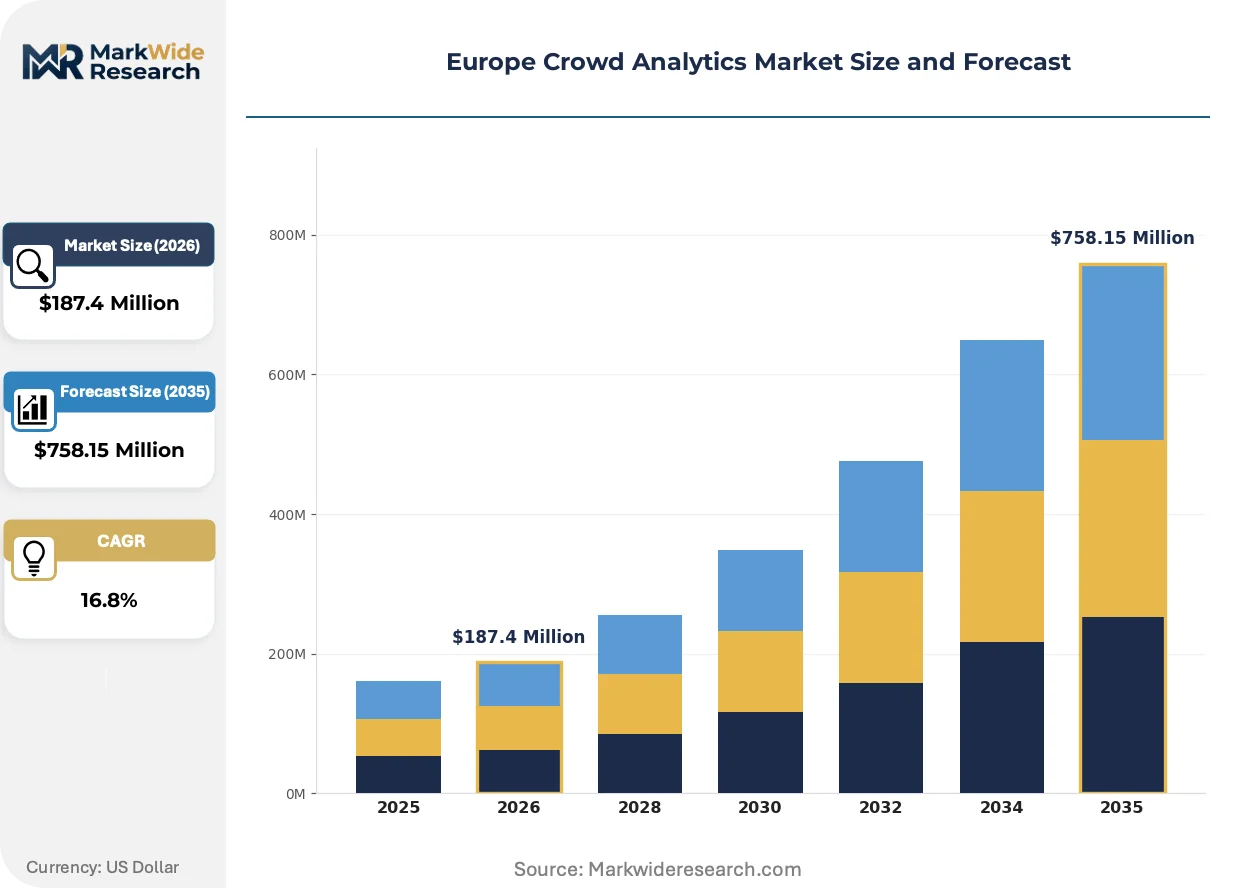
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Crowd Analytics Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions End User: Retailers, Airports, Public Spaces, Entertainment Venues Technology: Computer Vision, Sensors, IoT, Big Data Analytics Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Nokia Corporation, NEC Corporation, Amazon Web Services, Inc., Savannah Simulations AG, Sightcorp, IBM Corporation, Hewlett Packard Enterprise Development LP, Intel Corporation, Cisco Systems, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Crowd Analytics Market Trends and Innovations
Edge-native processing architectures are displacing cloud-dependent pipelines as latency requirements tighten for safety applications. Three converging developments define the current innovation cycle.
Computer vision inference is migrating from centralized cloud servers to on-camera neural processing units. Frankfurt Airport's Terminal 3 deployment processes 12,000 pedestrian vectors per minute locally, eliminating 180ms round-trip latency. This compression enables real-time evacuation routing that regulatory bodies now mandate for new construction permits.
GDPR's Article 35 data protection impact assessments are forcing biometric system redesigns across France and Germany. Vendors must demonstrate proportionality between inference depth and stated purpose, stripping facial recognition from retail analytics while preserving it for security watchlists. The Netherlands' data protection authority issued €7.2 million in penalties during 2023-2024, accelerating vendor investment in privacy-by-default architectures.
Subscription-based analytics dashboards are displacing perpetual software licenses among mid-sized venue operators. Copenhagen's Tivoli Gardens and Rotterdam's Ahoy arena now pay per-camera monthly fees that bundle algorithm updates and cloud elasticity. This rotation concentrates vendor revenue predictability while transferring infrastructure risk to technology suppliers.
Europe Crowd Analytics Market Segmentation
European crowd analytics procurement fractures across technical architectures, operational environments, and regulatory exposure levels. Vendors must map product configurations against GDPR compliance tiers and ETSI interoperability mandates to secure municipal contracts.
Product Type:
Cost tier stratification separates capital-intensive hardware installations from recurring software revenue streams across European deployments.
- Software:Subscription analytics dashboards process pedestrian flow vectors and dwell-time metrics through API-accessible cloud platforms. French airport operators and German retail chains prioritize SaaS licensing to shift infrastructure risk onto vendors while preserving algorithm update velocity.
- Hardware:Edge devices with neural processing units execute real-time inference at camera endpoints, compressing latency for evacuation routing compliance. Thermal envelope constraints and CE marking timelines stretch procurement cycles for solid-state LiDAR and multi-sensor fusion arrays.
- Services:System integration and GDPR Article 35 data protection impact assessment consulting address municipal capability gaps in Italy and Spain.
- Solutions:Bundled hardware-software-service packages target smart city procurements requiring single-vendor accountability.
Software holds installed capacity. Hardware is rotating up the share rankings.
End User:
Application urgency varies sharply between safety-critical transport infrastructure and discretionary retail optimization budgets.
- Retailers:Layout optimization and queue management drive deployment in French hypermarkets and Dutch shopping districts. GDPR Article 17 erasure mandates compel real-time anonymization investments that degrade margin structures.
- Airports:Terminal 3 at Frankfurt and Charles de Gaulle expansion projects mandate passenger flow analytics for construction permitting. Evacuation routing algorithms must satisfy national aviation authority latency requirements.
- Public Spaces:RER and metro upgrades across 47 Paris stations create concentrated procurement for dwell-time analytics under state-funded modernization programs.
- Entertainment Venues:Copenhagen's Tivoli Gardens and Rotterdam's Ahoy arena adopt per-camera subscription models to access elastic cloud capacity during seasonal demand spikes.
Airports command premium pricing tiers. Entertainment venues are expanding most quickly.
Technology:
Maturity curves separate proven computer vision deployments from emerging sensor fusion architectures still navigating CE certification.
- Computer Vision:Neural networks trained on pedestrian detection process 12,000 movement vectors per minute at Frankfurt Terminal 3. EU AI Act risk-classification requirements force re-engineering of facial recognition pipelines for security watchlists while stripping them from retail analytics.
- Sensors:Solid-state LiDAR units below €400 per installation point enable high-density tracking in mid-sized venues previously priced out of vision-based systems.
- IoT:Device-free Wi-Fi positioning systems bypass biometric consent requirements, threatening pure computer vision pricing power in Dutch and German deployments.
- Big Data Analytics:Behavioral pattern recognition across aggregated pedestrian datasets supports predictive crowd density modeling for emergency services coordination.
Computer Vision holds revenue concentration. IoT is climbing the fastest.
Deployment:
Customer type and infrastructure legacy dictate cloud migration velocity across European venue operators.
- On-Premises:Municipalities with 60-70% non-IP camera estates in Italy and Spain require costly encoder middleware that fragments analytics accuracy. Legacy analog CCTV integration stretches deployment timelines.
- Cloud-Based:Mid-sized entertainment venues seek elastic compute capacity without capital-intensive hardware refresh cycles. GDPR data residency requirements constrain vendor data center location strategies.
- Hybrid:Edge-native processing with cloud dashboard aggregation balances latency requirements against storage scalability for German smart city frameworks.
- Mobile:Temporary deployment configurations serve festival operators and construction site safety monitoring with rapid installation requirements.
On-Premises retains legacy lock-in. Cloud-Based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and Southern Europe exhibit acute price sensitivity, while German and French transport operators absorb premium pricing for compliance-grade systems. This elasticity gradient concentrates vendor R&D in high-specification markets while pushing volume manufacturing toward cost-optimized tiers.
Germany
Frankfurt Airport's Terminal 3 deployment and Hamburg's smart city frameworks drive demand for sub-100ms latency evacuation systems. ETSI EN 303 645 certification filters municipal procurement toward compliant edge device suppliers. Bavaria's industrial corridor hosts concentrated system integration activity for automotive plant safety monitoring.
France
State-funded RER and metro modernization across 47 Paris stations mandates passenger flow optimization with dwell-time analytics. CNIL enforcement actions totaling €7.2 million in 2023-2024 accelerate privacy-by-default architecture investments. Île-de-France clusters deployment expertise for airport and transit convergence projects.
United Kingdom
London Heathrow expansion and retail district regeneration in Manchester create dual demand streams for security and commercial optimization. UK GDPR alignment with EU standards preserves cross-border vendor eligibility while Information Commissioner's Office guidance shapes biometric consent implementations. The Southeast corridor concentrates SaaS analytics adoption among entertainment venue operators.
Netherlands
Rotterdam's Ahoy arena and Amsterdam Schiphol anchor high-visibility deployments with stringent latency requirements. Dutch Data Protection Authority precedents on Wi-Fi positioning systems influence sensor fusion design choices nationwide. The Randstad megalopolis serves as testbed for integrated city operating systems spanning mobility and emergency services.
Poland
Warsaw and Krakow deploy crowd analytics at one-third German penetration rates, creating first-mover expansion opportunities for integrated platform vendors. EU structural fund eligibility accelerates smart city procurement timelines compared to purely municipal-budgeted projects. The Masovian Voivodeship concentrates pilot deployments seeking cost-optimized alternatives to Western European pricing tiers.
Europe Crowd Analytics Market Competitive Landscape
Infrastructure-anchored conglomerates and specialized computer vision firms split the market along deployment scale and technical depth axes. The vendor base concentrates around three strategic archetypes: telecommunications equipment providers leveraging 5G infrastructure, pure-play analytics software houses, and networking hardware incumbents extending into edge software layers. Competitive positioning hinges on ETSI certification velocity and GDPR-compliant architecture pre-certification. Primary rivalry vectors include municipal procurement framework eligibility and subscription pricing model innovation.
Among telecommunications-anchored suppliers, Nokia Corporation and NEC Corporation exemplify divergent specialization paths within the infrastructure-integrated tier. Nokia's European headquarters proximity facilitates direct engagement with German and French smart city procurement frameworks. NEC represents the computer vision-specialized alternative with established transit environment credentials. Cisco Systems, Inc. occupies the networking-derived position, extending hardware dominance into analytics software layers through edge-native processing architectures. These three anchors collectively illustrate the competitive tension between infrastructure leverage and application-specific optimization.
| Leading Market Players |
|---|
| Nokia Corporation |
| NEC Corporation |
| Amazon Web Services, Inc. |
| Savannah Simulations AG |
| Sightcorp |
| IBM Corporation |
| Hewlett Packard Enterprise Development LP |
| Intel Corporation |
| Cisco Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine corridor freight cost volatility amplifies price differentiation between GDPR-certified edge devices and uncertified alternatives, concentrating vendor margins in compliant tiers while compressing economics for non-certified suppliers serving price-sensitive Polish and Southern European buyers.
Pricing Analysis
After-sales service contracts and algorithm update subscriptions generate lifetime value multiples exceeding initial hardware margins. SaaS-tiered pricing stratifies across premium certified tiers, standard ETSI-compliant packages, and economy sensor-only configurations. Price differentiation hinges on CE marking status and real-time anonymization engine performance. Cost compression in economy tiers intensifies as solid-state LiDAR unit prices fall below entry thresholds. Municipal transport operators in Germany and France absorb premium pricing; Polish smart city projects exhibit acute sensitivity.
Supply Chain Analysis
Taiwan-based foundries and Chinese EMS providers hold dominant neural processing unit fabrication capacity for European-deployed edge devices. Hardware assembly concentrates in Taiwan, China, and Vietnam; software development clusters in Germany, France, and the Netherlands. Component sourcing draws from Taiwanese semiconductors, German precision optics, and Chinese LiDAR subassemblies. Single-source vulnerability in NPU fabrication exposes lead times to geopolitical friction. Distribution runs through systems integrators anchoring municipal procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-free Wi-Fi positioning and gait analysis systems threaten pure computer vision incumbents by bypassing biometric consent requirements, forcing defensive architecture investments.
For Market Incumbents: Insulate core positioning by acquiring real-time anonymization engine specialists and deepening backward integration into edge AI chip design. Prioritize EN 303 645 pre-certification to lock municipal procurement eligibility ahead of compliance deadlines. Counter Wi-Fi positioning substitutes through latency-performance differentiation in safety-critical applications.
For New Entrants and Emerging Players: Build out presence in Poland's underpenetrated smart city market where Western European pricing premiums face resistance. Target mid-sized entertainment venues seeking elastic cloud capacity without capital-intensive hardware commitments. Lead with per-camera subscription models that transfer infrastructure risk from venue operators.
For Investors and Strategic Acquirers: Computer vision software houses with GDPR-compliant architectures and established transit environment credentials represent priority acquisition targets. Long-term viability hinges on EU AI Act risk-classification navigation capability and municipal procurement framework penetration. Monitor CNIL and Dutch Data Protection Authority enforcement patterns as inflection indicators for privacy-by-default investment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Default Architecture Investment | CNIL's €7.2 million enforcement actions accelerate compliant product differentiation. |
| ETSI EN 303 645 Pre-Certification | German and Dutch municipal procurement frameworks filter toward certified suppliers exclusively. |
| Edge AI Chip Backward Integration | Taiwanese foundry concentration exposes neural processing unit supply to geopolitical friction. |
| Per-Camera Subscription Model Launch | Copenhagen's Tivoli Gardens and Rotterdam's Ahoy arena demonstrate venue operator appetite. |
| Poland Smart City Geographic Expansion | Warsaw and Krakow deploy at one-third German penetration rates, creating first-mover windows. |
Research Methodology
Cross-validation between municipal procurement officer interviews and ETSI certification database analysis anchors the qualitative findings. Primary fieldwork engaged smart city program directors, airport operations technology leads, data protection authority officials, edge device procurement managers, and computer vision engineering heads. Secondary sources include EU AI Act implementation guidance, GDPR Article 35 assessment filings, EN 303 645 certification registries, and municipal tender documentation. Bottom-up deployment tracking triangulates against top-down vendor revenue segmentation.
Calibration against historical adoption curves in transport infrastructure and retail optimization anchors the analytical framework. Segmentation models incorporate product type, end-user vertical, technology architecture, and deployment topology across the projection horizon. CAGRs derive from installed base expansion rates and pricing trajectory assumptions. Forecast inputs include LiDAR sensor cost curves and 5G network slicing availability timelines.
Sensitivities concentrate around EU AI Act enforcement intensity, GDPR Article 17 erasure mandate interpretation variance, and Taiwan-based foundry supply continuity. Forecasts reflect documented assumptions on regulatory harmonization timelines and municipal budget allocation patterns. Quarterly review of CNIL enforcement actions, ETSI standard revision cadence, and edge AI chip lead time indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Mobile Analytics Market
Analytics
Global Data Visualization Tools Market
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Global Social Intelligence Market
Analytics
Advanced Analytics Market
Analytics
Supply Chain Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Event Stream Processing Market
Analytics
North America HR Analytics Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Analytics of Things (Aot) Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Global AI Video Analytics Market
Analytics
Augmented Analytics Market
Analytics
Predictive Analytics Market
Analytics
Mobile App Attribution Tool Market