
 Big Data Analytics in Manufacturing Market | 2026-2036
Big Data Analytics in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics in Manufacturing Market Analysis
Shortage of data engineers with industrial domain expertise is redrawing competitive boundaries in manufacturing analytics. IBM sustains technology leadership through its Watson IoT platform and deep vertical expertise in heavy machinery. SAP SE anchors European demand with ERP-integrated analytics that bridge operational and enterprise data layers. Microsoft competes through Azure-based industrial cloud offerings that leverage existing enterprise relationships.
Big data analytics in manufacturing encompasses the collection, processing, and interpretation of high-velocity structured and unstructured data from sensors, SCADA systems, MES platforms, and enterprise applications to optimize production outcomes, typically operating across latency requirements from sub-millisecond edge processing to batch historical analysis. Predictive analytics leads current deployment as manufacturers prioritize equipment failure prevention over retrospective reporting. Streaming analytics represents the fastest-expanding technology segment as real-time quality control and digital twin synchronization demand continuous data ingestion. Prescriptive analytics commands premium positioning where optimization engines recommend autonomous production adjustments.
Manufacturers navigating the EU AI Act face mandatory risk classification for automated decision systems, while FDA quality system regulation shapes analytics validation protocols in medical device production. ISO 22400 standards for key performance indicators in manufacturing execution systems provide interoperability frameworks that reduce integration costs. Stakeholders must evaluate whether cloud or edge deployment architectures align with emerging cross-border data sovereignty requirements before committing to platform infrastructure.
Market Dynamics
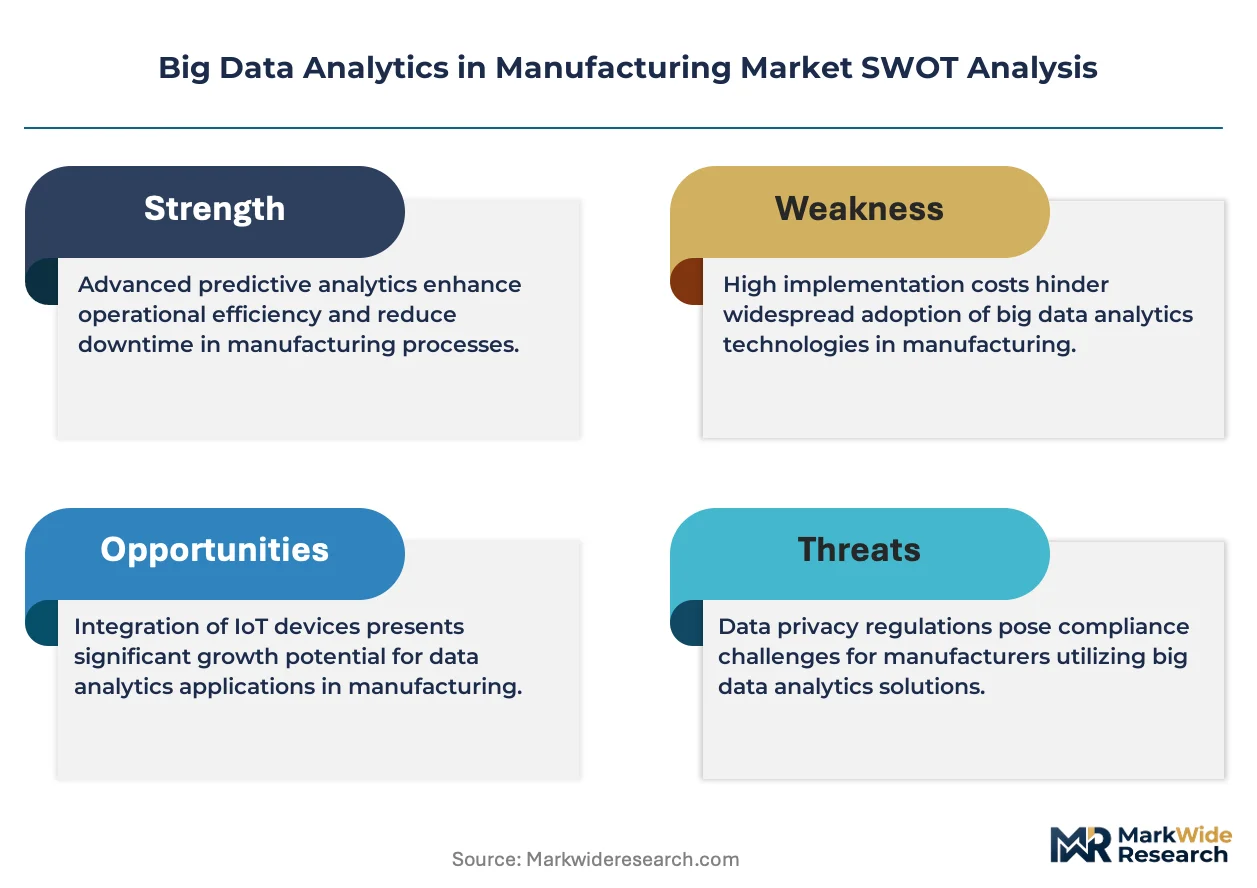
The EU AI Act's mandatory risk classification for automated decision systems is forcing manufacturers to re-architect their analytics stacks around sovereign data-processing capabilities, redrawing competitive boundaries for platform providers.
Growth Catalysts
- Predictive maintenance platforms:Automotive suppliers in Stuttgart and Munich clusters are expanding deployment to reduce unplanned downtime, anchoring Industrie 4.0 analytics adoption.
- GDPR compliance architectures:Cross-border data sovereignty requirements are accelerating demand for edge-based processing that keeps manufacturing data within national jurisdictions.
- Streaming analytics:Real-time quality control and digital twin synchronization are driving continuous data ingestion investments across heavy machinery production lines.
Market Restraints
- Data engineer scarcity:Shortage of industrial domain expertise in analytics talent pools is constraining deployment velocity for complex factory-floor implementations.
- Integration cost volatility:Legacy SCADA and MES system interoperability with modern cloud platforms requires substantial capital expenditure for protocol translation layers.
- EU regulatory friction:The AI Act's conformity assessment procedures for high-risk automated systems are extending validation timelines for prescriptive analytics deployments.
Strategic Opportunities
- Medical device analytics:FDA quality system regulation is creating validated analytics protocols that can be extended to adjacent regulated manufacturing verticals.
- Edge-cloud convergence:Hybrid architectures combining sub-millisecond edge processing with batch historical analysis are opening new deployment models for mid-tier manufacturers.
- ISO 22400 standardization:Interoperability frameworks for manufacturing execution system KPIs are reducing integration costs and accelerating platform switching.
Industry Challenges
- Legacy system entanglement:Decades-old sensor infrastructure and proprietary MES platforms resist seamless integration with modern analytics engines.
- Validation timeline compression:Medical device producers face extended FDA analytics validation protocols that delay production deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics in Manufacturing Market |
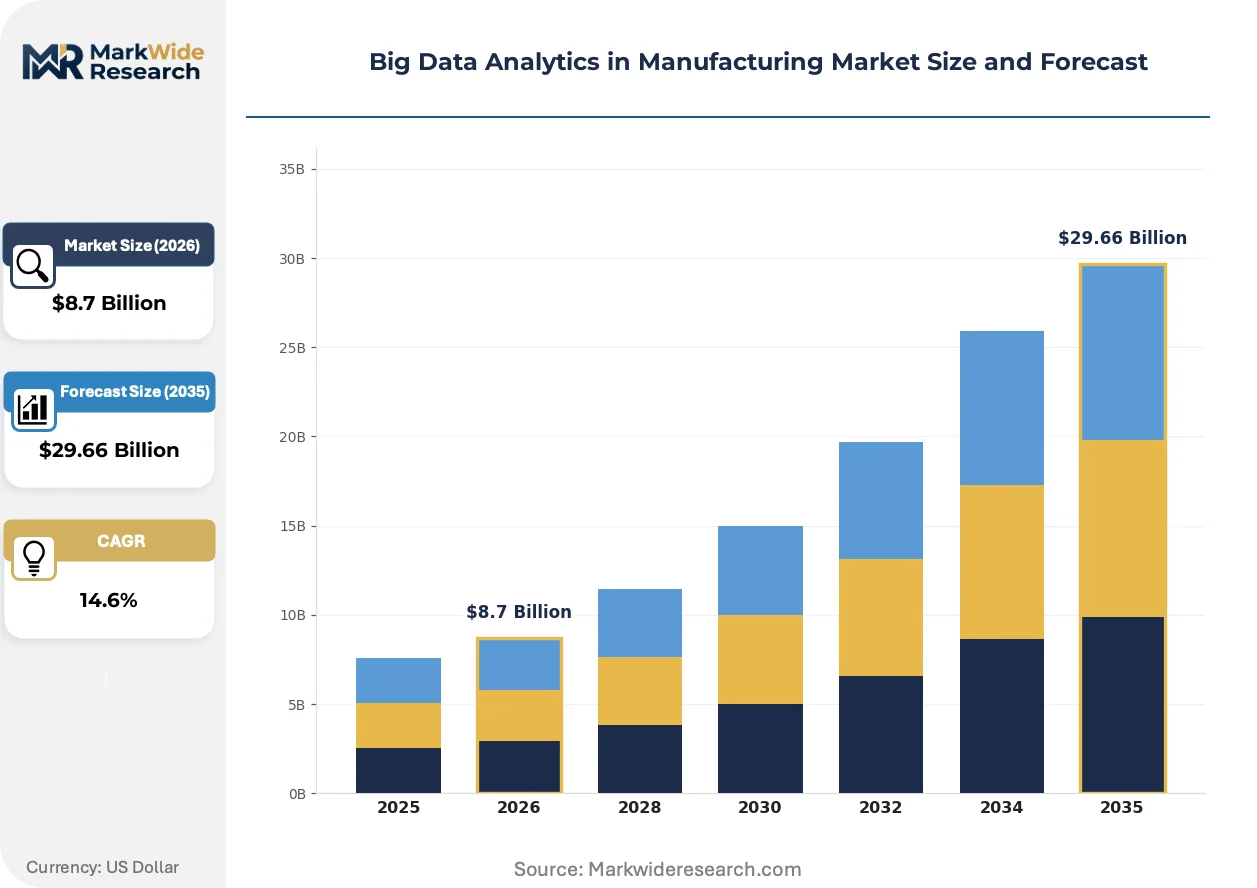
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Prescriptive Analytics, Descriptive Analytics, Streaming Analytics Technology: Machine Learning, Data Mining, Artificial Intelligence, Cloud Computing Application: Supply Chain Management, Quality Control, Predictive Maintenance, Inventory Optimization End User: Aerospace, Automotive Suppliers, Electronics, Heavy Machinery |
| Companies Covered | Altair Engineering, Oracle, IBM, TIBCO Software, SAP SE, SAS Institute, Accenture, Amazon, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics in Manufacturing Market Emerging Trajectories
Real-time synchronization between physical assets and digital representations is compressing decision latency from hours to milliseconds, restructuring how manufacturers orchestrate production flows.
Digital twin technology is decomposing traditional batch-based production planning into continuous optimization loops. Automotive and aerospace manufacturers in Germany and Japan are deploying physics-based simulations that mirror live factory conditions. This capability is compressing the feedback cycle between design iteration and shop-floor implementation.
The EU AI Act's risk-based classification system is mandating algorithmic transparency for high-risk manufacturing automation. Producers of medical devices and critical automotive components must now maintain audit trails for automated quality decisions. German Industrie 4.0 clusters are responding by embedding explainable AI modules directly into edge processing nodes.
After-sales service unbundling is fragmenting traditional equipment vendor relationships. Manufacturers in Stuttgart and Munich now procure analytics capabilities separately from machinery hardware, engaging specialized platform providers for predictive maintenance. This pattern is most visible in automotive supply chains where tier-one suppliers retain direct analytics vendor relationships.
Big Data Analytics in Manufacturing Market Segmentation
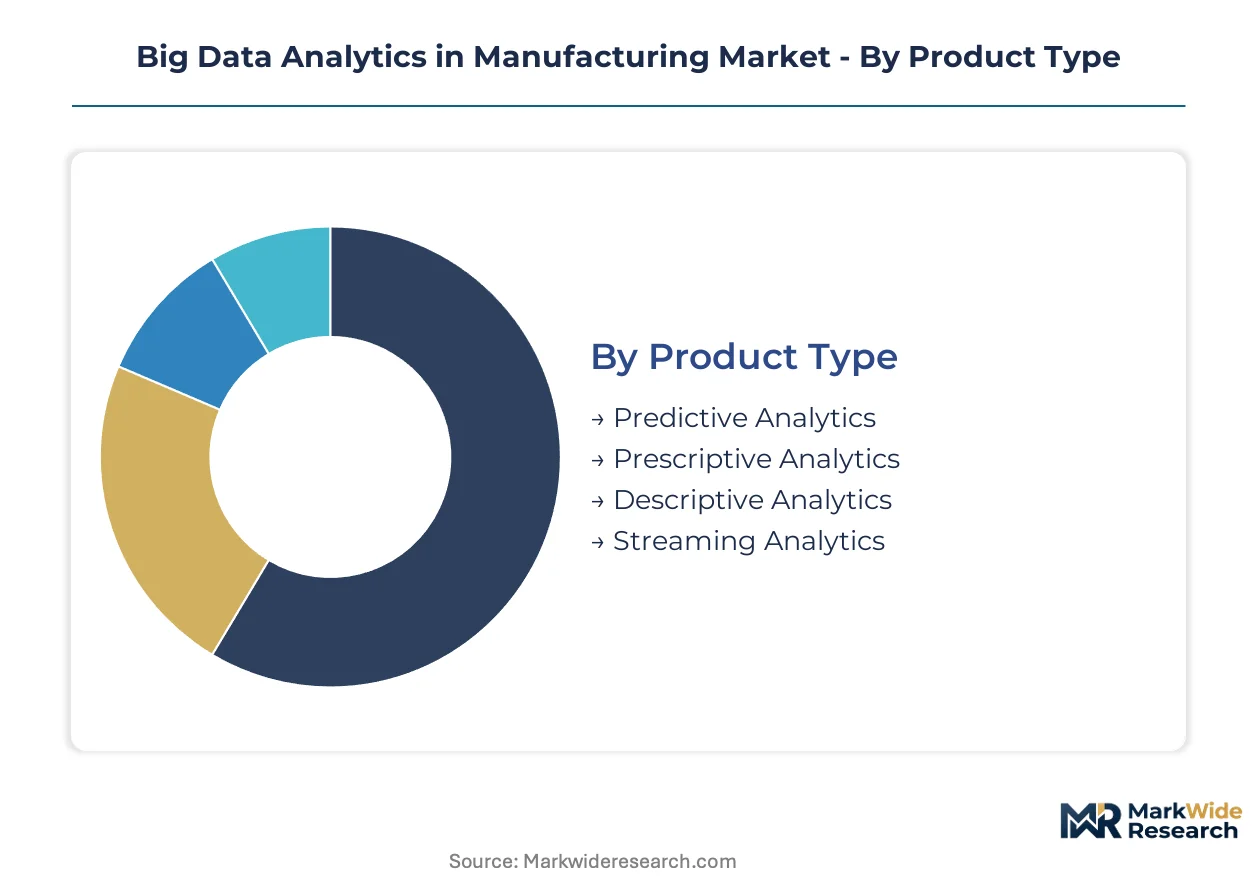
Segmentation in manufacturing analytics reflects how industrial buyers procure capabilities—through integrated platforms, point solutions, or embedded modules within existing operational systems. Channel strategy differs sharply between heavy machinery OEMs seeking edge-native deployments and automotive suppliers favoring cloud-integrated ERP extensions.
Product Type:
Channel mix varies by analytics maturity: predictive and descriptive platforms flow through established industrial software vendors, while streaming and prescriptive solutions increasingly route through specialized edge-computing distributors and systems integrators.
- Predictive Analytics:Algorithms process historical sensor data and SCADA logs to forecast equipment failures before operational impact. Demand concentrates among automotive suppliers in Stuttgart and Munich clusters, driven by unplanned downtime reduction mandates from OEM customers. Deployment typically integrates with existing MES platforms rather than standalone procurement.
- Streaming Analytics:Continuous ingestion pipelines process sub-millisecond data streams from production lines for real-time quality intervention and digital twin synchronization. Heavy machinery manufacturers in Germany and Japan anchor adoption, compelled by ISO 22400 KPI standardization requirements and the EU AI Act's audit trail mandates for automated decisions.
- Prescriptive Analytics:Optimization engines recommend autonomous production adjustments based on multi-variable constraint modeling. Medical device producers under FDA quality system regulation represent the most demanding validation segment.
- Descriptive Analytics:Retrospective dashboards and reporting tools summarize historical production performance. Mid-tier electronics manufacturers represent the volume base, prioritizing cost-effective visibility over predictive capabilities.
Predictive analytics dominates installed base. Streaming analytics is where expansion concentrates.
Technology:
Technology selection tracks infrastructure legacy and data sovereignty requirements, with cloud-native architectures facing friction against edge-preferred deployments in regulated European manufacturing.
- Machine Learning:Supervised and unsupervised learning models identify patterns in heterogeneous manufacturing data sources. Automotive suppliers deploy ML for defect classification in computer vision quality systems, constrained by the EU AI Act's risk classification requirements for high-risk automated decision systems.
- Artificial Intelligence:Broader cognitive capabilities including natural language processing for maintenance documentation and generative design optimization. Aerospace manufacturers leverage AI for generative design-to-manufacturing feedback loops, though validation protocols under EASA and FAA regulations extend deployment timelines.
- Data Mining:Pattern extraction from historical production databases to identify root causes of quality deviations. Electronics manufacturers with mature data lakes represent the primary adoption segment.
- Cloud Computing:Scalable compute and storage resources for batch historical analysis and model training. GDPR cross-border data transfer restrictions are redirecting demand toward sovereign cloud architectures and hybrid edge-cloud deployments.
Machine learning anchors current revenue. Artificial intelligence is climbing the fastest as explainable AI modules address regulatory transparency mandates.
Application:
Application prioritization reflects manufacturing vertical economics: asset-intensive sectors weight predictive maintenance highest, while discrete manufacturers emphasize quality control and inventory velocity.
- Predictive Maintenance:Condition-based monitoring and failure forecasting for critical production equipment. Heavy machinery OEMs and automotive suppliers represent parallel demand centers, with the former seeking aftermarket service revenue and the latter pursuing uptime guarantees.
- Quality Control:Real-time defect detection and process parameter optimization. Electronics manufacturers deploy computer vision and sensor fusion for microelectronics inspection, where streaming analytics integration is becoming standard.
- Supply Chain Management:Demand forecasting, supplier risk monitoring, and logistics optimization. Aerospace tier-one suppliers leverage analytics for multi-tier supplier visibility under AS9100 quality management requirements.
- Inventory Optimization:Dynamic safety stock positioning and material requirements planning enhancement. Automotive just-in-sequence production models drive demand for real-time inventory synchronization with upstream suppliers.
Quality control holds the broadest cross-vertical penetration. Predictive maintenance is gaining share fastest as equipment connectivity infrastructure matures.
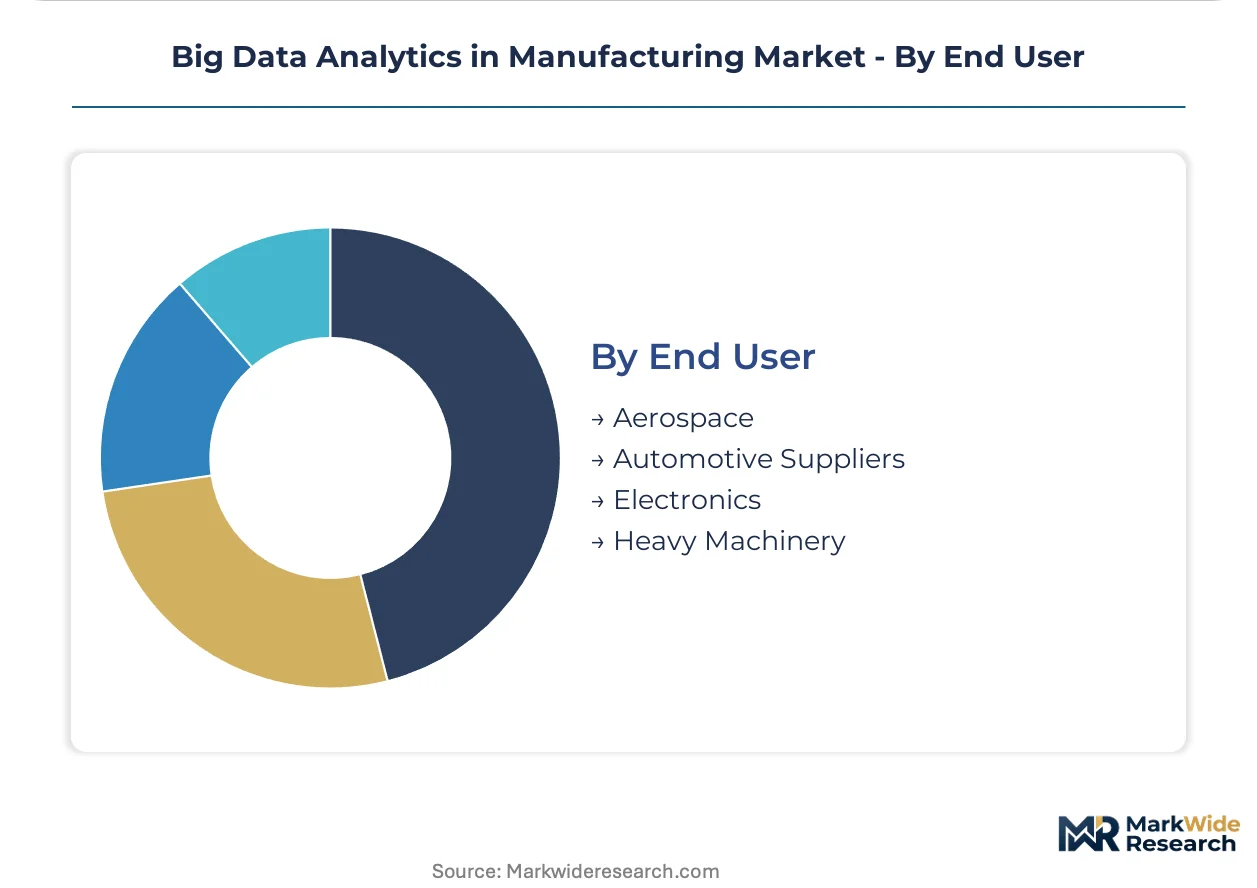
End User:
End-user segmentation reveals divergent procurement patterns: automotive and electronics manufacturers favor platform consolidation through ERP-integrated analytics, while aerospace and heavy machinery retain specialized vendor relationships for safety-critical applications.
- Automotive Suppliers:Tier-one and tier-two component manufacturers serving OEM assembly networks. Stuttgart and Munich Industrie 4.0 clusters anchor European deployment, with predictive maintenance and quality analytics representing the priority investment categories.
- Heavy Machinery:Construction, mining, and agricultural equipment manufacturers. After-sales service unbundling is fragmenting traditional vendor relationships, with machinery OEMs procuring analytics capabilities separately from hardware platforms.
- Aerospace:Commercial and defense aircraft component manufacturers. EASA and FAA regulatory frameworks impose stringent validation requirements on analytics-driven quality decisions, extending procurement cycles but creating durable supplier relationships.
- Electronics:Semiconductor, consumer electronics, and industrial electronics producers. High-mix, low-volume production environments drive demand for flexible quality control and rapid changeover optimization.
Automotive suppliers represent the largest addressable base. Heavy machinery is where vendor relationship restructuring is creating the most supplier switching opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA and BSI anchor European regulatory frameworks for industrial data sovereignty, while the EU AI Act establishes continent-wide algorithmic transparency mandates that reshape deployment architectures across manufacturing hubs.
Germany
Automotive suppliers in Stuttgart and Munich clusters drive predictive maintenance platform demand to satisfy OEM uptime requirements. BSI technical guidelines for industrial cybersecurity complement GDPR data localization rules. Baden-Württemberg's Industrie 4.0 innovation labs anchor real-time quality analytics deployment for tier-one component manufacturers.
United States
Heavy machinery OEMs and aerospace manufacturers prioritize FDA-validated analytics protocols for medical device and critical component production. NIST cybersecurity frameworks shape edge-computing procurement standards for defense-adjacent manufacturing. Michigan's automotive corridor and Washington state's aerospace cluster concentrate streaming analytics investments for supply chain synchronization.
China
MIIT smart manufacturing initiatives accelerate digital twin deployment across Yangtze River Delta electronics producers. GB standards for industrial data interoperability reduce integration friction between legacy MES platforms and cloud analytics. Shenzhen and Suzhou manufacturing hubs anchor computer vision quality control system rollouts for consumer electronics assembly.
Japan
METI's Society 5.0 roadmap funds physics-based simulation platforms for automotive and precision machinery sectors. JIS standards for manufacturing execution system KPIs provide interoperability baselines for analytics integration. Nagoya's Chubu industrial corridor and Osaka's Kansai manufacturing belt concentrate prescriptive analytics adoption for autonomous production adjustment.
South Korea
MFDS quality system regulations extend validation requirements to analytics-driven pharmaceutical and medical device manufacturing. Government smart factory subsidies compress deployment timelines for mid-tier electronics producers. Seoul Capital Area and Busan-Ulsan industrial zones anchor machine learning defect classification investments in semiconductor and display panel fabrication.
Big Data Analytics in Manufacturing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in manufacturing analytics, with ERP-embedded platforms and cloud-native industrial suites occupying distinct competitive spaces. The upper tier consolidates around enterprise software incumbents with deep operational data layer integration, while specialists concentrate on edge-native streaming and physics-based simulation capabilities. Two strategic archetypes dominate: vertical-integrated platform providers bundling hardware-software-analytics stacks, and modular specialists selling point solutions through systems integrator channels. Competitive moves center on M&A targeting industrial IoT connectivity assets and strategic partnerships bridging OT-IT data translation layers.
Within the integrated platform tier, SAP SE and Microsoft exemplify contrasting geographic anchoring and deployment philosophies, while IBM occupies a distinct position emphasizing heavy machinery vertical expertise. Oracle and Amazon represent cloud-native challengers competing through scalable compute infrastructure and existing enterprise relationships. Altair Engineering and TIBCO Software sit within the specialist tier, with SAS Institute and Accenture occupying hybrid consulting-technology positions that blur traditional vendor boundaries.
| Leading Market Players |
|---|
| Altair Engineering |
| Oracle |
| IBM |
| TIBCO Software |
| SAP SE |
| SAS Institute |
| Accenture |
| Amazon |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity assessment procedures gate both supplier qualification and price differentiation simultaneously, as high-risk automated system certifications separate premium-validated analytics modules from standard descriptive dashboards. Stuttgart automotive suppliers pay substantial premiums for FDA-equivalent validation protocols, while mid-tier electronics manufacturers in Shenzhen select unvalidated cloud-native alternatives to compress procurement costs.
Pricing Analysis
German Industrie 4.0 clusters command 40-60% price premiums over comparable US deployments for identical predictive maintenance platforms, reflecting embedded compliance engineering for BSI cybersecurity guidelines and GDPR data localization. Pricing stratifies across premium, standard, and economy tiers based on validation depth and edge-processing latency guarantees. Cost compression in the standard tier is intensifying because hyperscaler cloud offerings are commoditizing descriptive analytics. Automotive tier-one suppliers exhibit lowest price sensitivity due to OEM-mandated uptime guarantees, while mid-tier electronics manufacturers in high-mix environments prioritize per-seat SaaS economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are inflating inbound logistics costs for edge-computing hardware components, compressing margins for systems integrators deploying factory-floor analytics. Supply concentrates in Germany, the United States, and China, with industrial software development anchored in Stuttgart, Seattle, and Shenzhen clusters. Raw material dependencies span silicon wafers for edge processors, rare earth elements for sensor magnetics, and specialized memory modules for real-time streaming pipelines. Single-source vulnerability in EUV lithography equipment for advanced semiconductor fabrication creates chokepoint exposure. Distribution runs through specialized industrial IoT systems integrators rather than direct vendor relationships, particularly for automotive and aerospace verticals requiring embedded compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of data engineers possessing both industrial domain expertise and machine learning implementation skills is constraining deployment velocity and redrawing competitive boundaries around talent acquisition and retention capabilities.
For Market Incumbents: Shield installed base relationships through embedded compliance modules that preempt EU AI Act audit requirements, while acquiring specialist edge-computing firms to close latency gaps against cloud-native challengers. Vertical integration into industrial IoT sensor manufacturing secures supply chain priority during semiconductor allocation cycles. Certification investment in FDA-validated analytics protocols for medical device verticals creates switching costs that protect premium pricing tiers. For New Entrants and Emerging Players: After-sales service unbundling in heavy machinery OEM relationships exposes a service-layer gap where incumbents under-serve predictive maintenance analytics as standalone offerings. Target automotive tier-two suppliers in Baden-Württemberg seeking independent platform relationships outside consolidated ERP-integrated procurement channels. Go-to-market leverage rests on ISO 22400 KPI standardization expertise that accelerates MES integration timelines for mid-tier manufacturers. For Investors and Strategic Acquirers: EU AI Act high-risk system classification reshapes the acquisition landscape toward edge-native platforms with embedded explainable AI capabilities and sovereign data-processing architectures. Long-term viability centers on hybrid deployment models spanning sub-millisecond edge processing with cloud-based model training. Acquisition target archetype: specialist streaming analytics firms with physics-based simulation IP and established relationships in German Industrie 4.0 clusters. Signal to watch: FDA validation protocol extensions into adjacent regulated manufacturing verticals as precedent for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Development | Sub-millisecond processing capabilities satisfy EU AI Act audit mandates for automotive suppliers in Stuttgart. |
| Regulatory Validation Investment | FDA quality system protocols open medical device manufacturing to prescriptive analytics premium positioning. |
| Industrial IoT Acquisition | Sensor connectivity assets bridge OT-IT data translation layers for legacy SCADA integration. |
| Sovereign Cloud Partnership | GDPR-compliant architectures capture cross-border data sovereignty requirements in German manufacturing. |
| Explainable AI Module Integration | Algorithmic transparency features address EASA and FAA mandates for aerospace quality decisions. |
Methodological Framework
A spread of perspectives from plant engineers, maintenance directors, OEM procurement teams, and industrial software integration specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from industrial software vendors, MIIT smart manufacturing initiative disclosures, and BSI technical guideline publications. Bottom-up triangulation against top-down macroeconomic indicators anchored volume and value estimates.
Segmentation dimensions modeled span analytics type, deployment architecture, manufacturing vertical, and geographic regulatory cluster across the projection horizon. CAGRs derive from installation base expansion rates, replacement cycle analysis, and technology substitution curves for streaming versus batch processing modalities. Industry-specific inputs include Industrie 4.0 adoption velocity in German automotive corridors and FDA validation timeline compression for medical device analytics.
Underlying assumptions cover sustained EU AI Act implementation timelines, with deviation risk concentrated in cross-border data sovereignty enforcement heterogeneity and semiconductor supply normalization trajectories. Recalibration cycles align with material shifts in regulatory compliance deadlines and hyperscaler industrial cloud capex commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Business Intelligence and Analytics Software Market
Analytics
US Predictive Analytics Market
Analytics
APAC Location Analytics Market
Analytics
IoT Analytics Market
Analytics
Business Analytics Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Global People and HR Analytics Software Market
Analytics
Customer Journey Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
APAC Operational Intelligence Market
Analytics
Global Development Analytics Tools Market
Analytics
Weather Data Services Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Content Analytics Software Market
Analytics
Israel Geospatial Analytics Market