
 Patent Analytics Market | 2026-2036
Patent Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Patent Analytics Market Intelligence
Multi-source procurement of patent analytics is broadening as enterprises diversify beyond single-vendor dependencies. Patsnap leverages its integrated platform spanning search, analysis, and collaboration tools to anchor enterprise relationships across Asia-Pacific markets. Clarivate Derwent Innovation sustains its position through deep backfile coverage and curated patent family structures that differentiate legacy offerings. LexisNexis IP competes on legal workflow integration, extending its reach into law firm and corporate counsel segments.
Patent analytics encompasses the systematic extraction, visualization, and interpretation of bibliographic, legal, and technical data from patent documents to support strategic decision-making, typically processing millions of records through structured databases with semantic indexing and citation network mapping. The primary commercial purpose centers on reducing uncertainty in R&D investment, litigation risk, and licensing negotiations by transforming raw patent data into actionable intelligence. Competitive intelligence and portfolio management solutions lead current revenue pools, while technology scouting and legal analytics represent faster-growing segments as enterprises seek earlier-stage signals and proactive dispute prevention. Machine learning and natural language processing dominate technology investment, though graph analytics is gaining traction for mapping inventor mobility and technology convergence patterns.
ISO standards for intellectual property management, USPTO examination guidelines, and EPO patentability criteria collectively shape product development priorities and client compliance requirements across vendor roadmaps. The USPTO's ongoing artificial intelligence initiatives and the EU's unitary patent system create dual regulatory tailwinds that expand addressable use cases for cross-jurisdictional portfolio tools. Stakeholders must monitor how generative AI capabilities reshape prior art search accuracy standards and whether regulatory bodies establish formal validation frameworks for algorithmic patent analysis outputs.
Market Dynamics
Machine learning integration into patent search workflows is compressing prior art analysis timelines from weeks to hours, forcing incumbent vendors to re-architect legacy semantic indexing engines or cede enterprise accounts to AI-native competitors.
Growth Catalysts
- USPTO examination backlog:The United States Patent and Trademark Office's persistent application backlog creates sustained demand for predictive analytics that forecast examiner behavior and prosecution outcomes. Pharmaceutical firms deploy these tools to accelerate drug patent timelines.
- Pharmaceutical R&D intensity:Biotechnology and pharmaceutical companies face mounting pressure to derisk billion-dollar molecule investments through freedom-to-operate landscaping before clinical trials commence.
- Graph analytics:Network mapping of inventor mobility and technology convergence patterns enables earlier identification of disruptive competitors and acquisition targets.
Market Restraints
- Data licensing costs:Commercial patent databases require expensive recurring subscriptions to national patent office feeds, creating margin pressure for mid-tier analytics vendors.
- Technical debt in legacy platforms:Established providers built on decades-old document processing architectures struggle to integrate transformer-based language models without complete infrastructure rebuilds.
- Regulatory fragmentation:Divergent patentability standards between the USPTO, EPO, and JPO force vendors to maintain jurisdiction-specific rule engines that multiply development overhead.
Strategic Opportunities
- EU unitary patent system:The European Union's unified patent framework creates demand for cross-jurisdictional portfolio management tools that streamline validation and enforcement across member states.
- Technology scouting services:Early-stage signal detection represents faster-growing revenue pools as enterprises seek competitive intelligence before patent publication lags.
- Generative AI validation frameworks:Regulatory bodies will likely establish formal standards for algorithmic patent analysis outputs, creating first-mover advantage for vendors with compliant audit trails.
Industry Challenges
- Computational linguistics talent scarcity:The intersection of patent law expertise and natural language processing engineering remains shallow, constraining product development velocity.
- Legacy system integration friction:Enterprise legal departments operate entrenched matter management platforms that resist API-based connectivity with modern analytics suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patent Analytics Market |
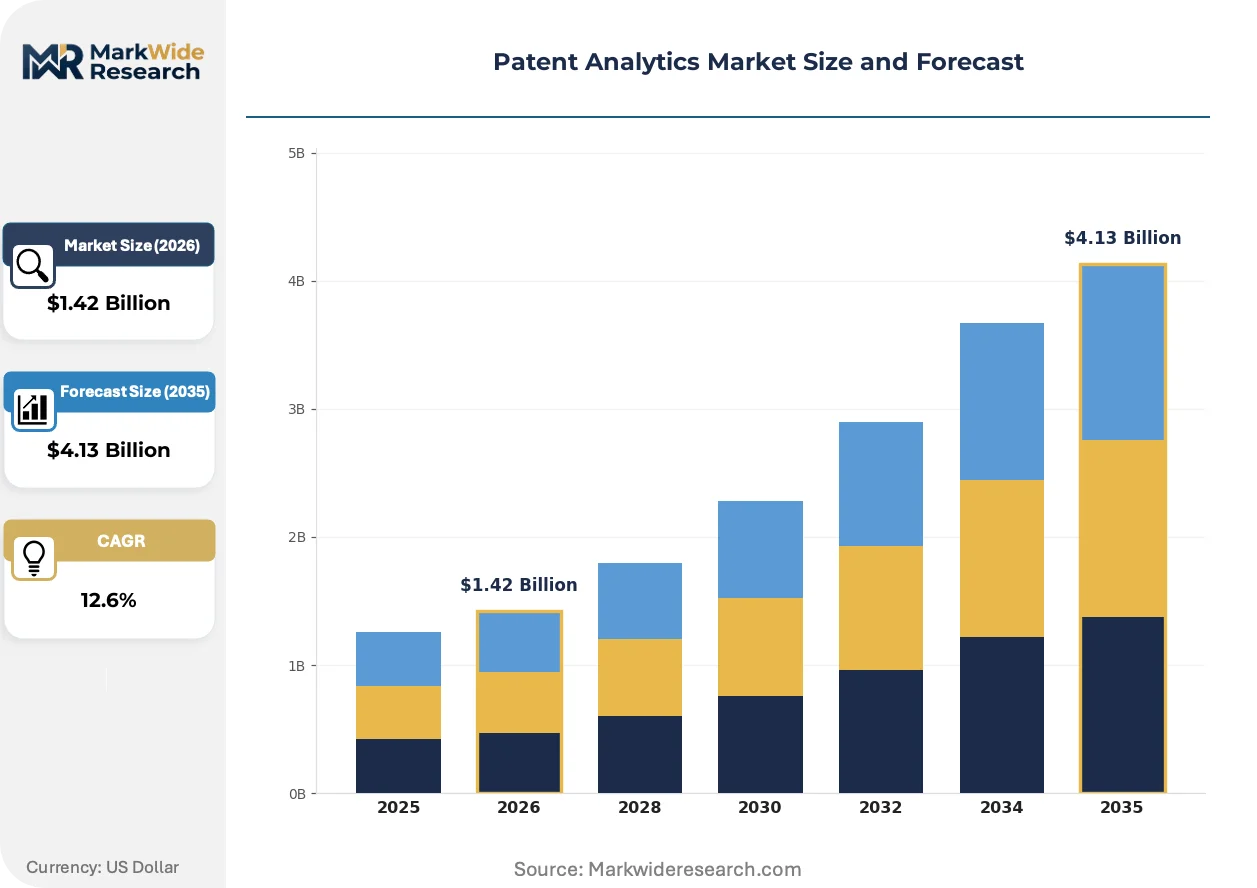
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Competitive Intelligence, Portfolio Management, Patent Search, Patent Valuation, Technology Scouting, Legal Analytics Technology: Machine Learning, Natural Language Processing, Data Mining, Semantic Analysis, Predictive Analytics, Graph Analytics Application: R&D Optimization, IP Risk Management, Market Trend Analysis, Licensing & Monetization, Compliance Monitoring, Innovation Benchmarking End User Industry: Pharmaceuticals & Biotechnology, Information Technology & Software, Manufacturing & Engineering, Consumer Electronics, Energy & Utilities, Aerospace & Defense |
| Companies Covered | Relecura, PatentSight, Patsnap, The Lens, Cypris, Clarivate Derwent Innovation, LexisNexis IP, Google Patents, Questel Orbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patent Analytics Market Strategic Shifts & Innovations
Natural language processing architectures are displacing Boolean search as the dominant retrieval paradigm, while citation network visualization tools embed directly into R&D collaboration platforms.
Transformer-based semantic search is expanding into technical due diligence workflows. Private equity firms and corporate development teams now deploy these engines to screen acquisition targets for latent IP risks. The compression of manual review time is reshaping how deal timelines are structured.
The USPTO's artificial intelligence initiatives are accelerating examiner training tool deployment. These programs generate structured feedback datasets that improve automated classification accuracy. Vendors serving prosecution analytics must align product roadmaps with these evolving examination standards.
Enterprise buyers are consolidating vendor relationships around integrated platforms. Procurement teams now prioritize unified search, analysis, and collaboration tools over point solutions. This preference shift concentrates contract value with providers offering end-to-end workflow coverage.
Patent Analytics Market Segmentation
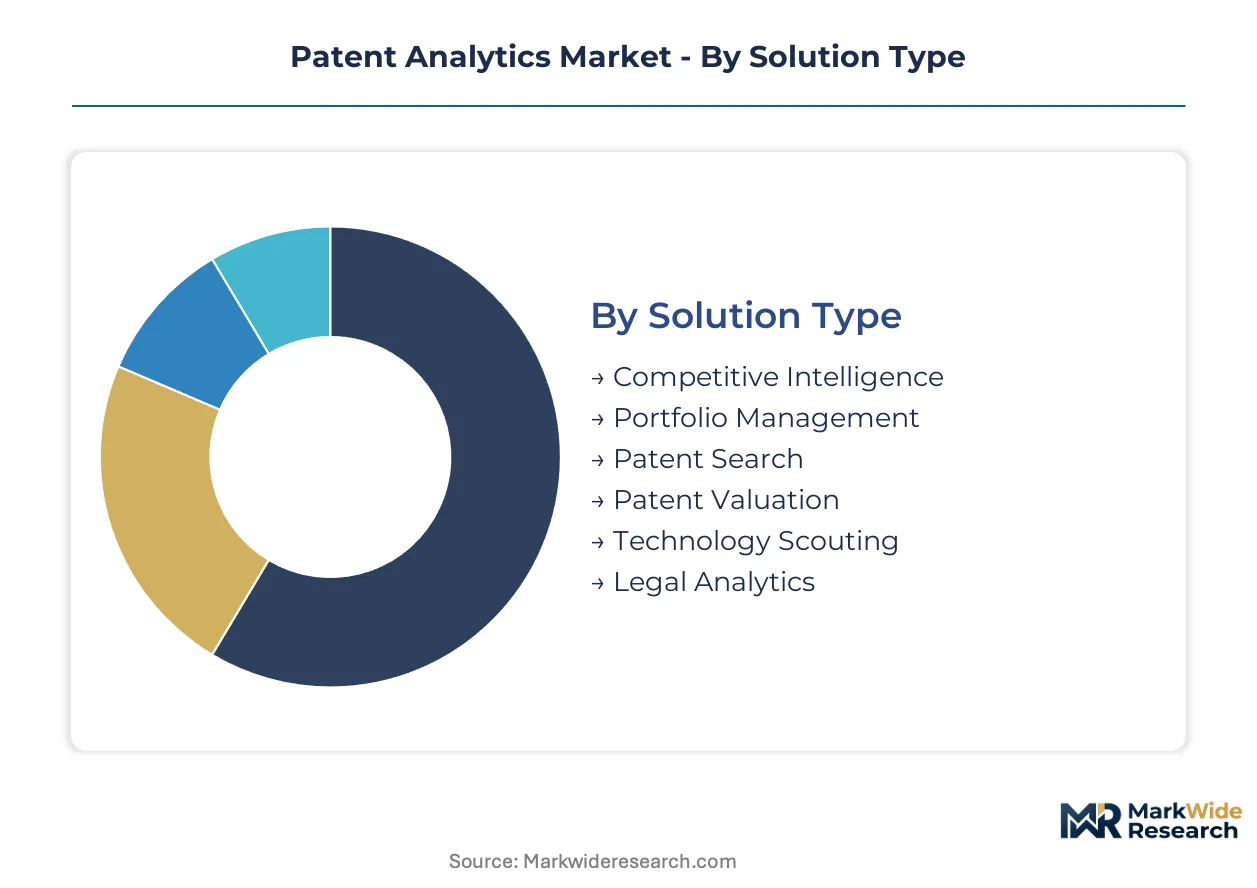
Segmentation reveals how capital deployment varies across patent analytics workflows. Pharmaceutical firms prioritize portfolio management platforms requiring substantial infrastructure investment, while mid-market adopters favor modular search tools with lower entry costs.
Solution Type:
Capital intensity peaks in integrated platforms demanding multi-year implementation cycles and dedicated client success teams.
- Competitive Intelligence:Systems tracking competitor filing patterns, technology migrations, and prosecution strategies through automated alert engines. Demand concentrates among Fortune 500 manufacturers seeking early warning of disruptive entrants; budget cycles align with annual strategic planning processes.
- Portfolio Management:Enterprise-grade platforms consolidating global patent families, annuity decisions, and maintenance fee optimization across thousands of assets. Pharmaceutical and biotechnology firms absorb the bulk of installed capacity due to molecule-specific IP hedging requirements; deployment timelines stretch 12-18 months with seven-figure commitments.
- Patent Search:Boolean and semantic retrieval tools for prior art examination and freedom-to-operate landscaping. Law firms and R&D departments represent primary demand clusters.
- Patent Valuation:Models integrating citation metrics, claim breadth scoring, and comparable licensing transactions for M&A and litigation support. Private equity due diligence teams drive adoption.
- Technology Scouting:Early-stage signal detection identifying emerging inventors and convergence patterns before patent publication. Corporate venture arms and innovation labs deploy these tools.
- Legal Analytics:Litigation outcome prediction, judge behavior modeling, and damages estimation for IP disputes. Am Law 100 firms anchor demand.
Portfolio management absorbs the bulk of installed capacity; technology scouting is expanding most quickly.
Technology:
Engineering talent costs and compute infrastructure requirements create steep barriers for transformer-based architectures.
- Machine Learning:Supervised classification models trained on examiner behavior datasets and prosecution outcome histories. The USPTO's AI training initiatives generate structured feedback loops improving prediction accuracy; vendors must align roadmaps with evolving examination standards.
- Natural Language Processing:Transformer architectures replacing Boolean retrieval with semantic embedding spaces capturing technical concept relationships. R&D teams at information technology and software companies compress prior art review timelines from weeks to hours; implementation demands specialized computational linguists scarce in legal technology labor markets.
- Data Mining:Pattern extraction across citation networks, inventor trajectories, and technology co-occurrence matrices.
- Semantic Analysis:Ontology-driven indexing mapping patent claims to standardized technology taxonomies.
- Predictive Analytics:Monte Carlo simulations forecasting patent grant probabilities and maintenance fee optimization paths.
- Graph Analytics:Network visualization of technology convergence and inventor mobility patterns. Aerospace and defense contractors leverage these tools for supply chain IP risk mapping.
Natural language processing claims the deepest R&D investment; graph analytics shows the steepest expansion trajectory among emerging capabilities.
Application:
Workflow integration complexity determines implementation cost tiers across use cases.
- R&D Optimization:Freedom-to-operate landscaping and white-space analysis guiding molecule and component design decisions. Biotechnology firms deploy these tools before Phase I trials to derisk billion-dollar development programs; integration with electronic laboratory notebooks multiplies deployment scope.
- IP Risk Management:Infringement monitoring, opposition tracking, and litigation early-warning systems. Consumer electronics manufacturers with dense patent thickets sustain continuous monitoring programs; semiconductor and telecommunications sectors show highest alert frequency.
- Market Trend Analysis:Technology lifecycle mapping and adoption curve forecasting from filing velocity patterns.
- Licensing & Monetization:Essentiality determination, royalty rate benchmarking, and negotiation support for patent pools.
- Compliance Monitoring:Standard-essential patent disclosure tracking and FRAND obligation management.
- Innovation Benchmarking:R&D productivity metrics comparing patent output to peer organizations.
R&D optimization commands the largest implementation budgets; IP risk management is climbing the fastest as litigation frequency rises.
End User Industry:
Regulatory intensity and R&D spend ratios shape procurement sophistication across verticals.
- Pharmaceuticals & Biotechnology:Patent term extension strategies, Hatch-Waxman litigation preparation, and biosimilar defense analytics. FDA approval timelines create compressed prosecution windows demanding predictive examiner tools; freedom-to-operate studies precede every major clinical investment.
- Information Technology & Software:Open-source compliance, API patent landscaping, and cloud infrastructure IP hedging. Continuous release cycles require automated monitoring of competitor filings in the United States, China, and Europe; engineering teams integrate analytics directly into CI/CD pipelines.
- Manufacturing & Engineering:Process patent protection and supply chain IP risk mapping.
- Consumer Electronics:Standard-essential patent portfolios and cross-licensing negotiation support.
- Energy & Utilities:Clean technology patenting and carbon capture IP strategy.
- Aerospace & Defense:Export control classification and government contract IP allocation.
Pharmaceuticals and biotechnology absorb the bulk of installed capacity; information technology and software is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patent data infrastructure concentrates where R&D expenditure and intellectual property litigation intersect most densely. Silicon Valley patent prosecution volumes and Frankfurt chemical patent filings anchor continental demand patterns.
United States
Pharmaceutical freedom-to-operate studies and USPTO examination backlog mitigation drive enterprise procurement. The USPTO's AI training initiatives generate structured feedback datasets that improve automated classification accuracy. Boston biotechnology clusters deploy predictive analytics to compress patent prosecution timelines before FDA submission windows.
Germany
Automotive component patent landscaping and chemical process protection absorb substantial analytics capacity. EPO unitary patent framework implementation creates demand for cross-jurisdictional portfolio management. Munich industrial engineering corridors integrate citation network tools into R&D collaboration platforms for supplier IP risk mapping.
China
Semiconductor patent thickets and standard-essential patent disclosure tracking accelerate vendor penetration. MIIT patent quality initiatives and SAMR enforcement guidelines reshape compliance requirements. Shenzhen hardware manufacturing ecosystems deploy semantic search to monitor competitor filings across United States, European, and domestic registries.
Japan
Materials science patent families and robotics IP hedging sustain platform subscriptions. METI intellectual property strategy roadmaps emphasize prior art search automation for university technology transfer offices. Osaka pharmaceutical corridors license analytics suites to manage Hatch-Waxman litigation preparation and biosimilar defense portfolios.
United Kingdom
Financial services patent analytics and life sciences licensing negotiation tools gain traction among corporate counsel. IPO examination practice harmonization with EPO standards influences product development priorities. Cambridge biotechnology clusters integrate predictive examiner behavior models to optimize prosecution strategy before European validation phases.
Patent Analytics Market Key Industry Players
Platform consolidation dominates the current landscape as procurement teams prioritize unified workflow coverage over point solutions. The vendor base organizes around three archetypes: integrated platform providers spanning search through collaboration, specialized legal workflow integrators, and open-access academic infrastructure operators. M&A activity concentrates on semantic search engine acquisitions and geographic expansion into Asia-Pacific enterprise accounts. Strategic partnerships between analytics vendors and national patent offices reshape data feed exclusivity arrangements.
Within the integrated platform tier, Patsnap and Clarivate Derwent Innovation occupy positions anchored by multi-year enterprise implementations and dedicated client success structures. LexisNexis IP sits within the legal workflow integration archetype, extending reach into law firm and corporate counsel segments where matter management platform connectivity determines procurement outcomes. Relecura represents the emerging capability vector, exemplifying how graph analytics and inventor mobility mapping gain traction among aerospace and defense contractors for supply chain IP risk assessment.
| Leading Market Players |
|---|
| Relecura |
| PatentSight |
| Patsnap |
| The Lens |
| Cypris |
| Clarivate Derwent Innovation |
| LexisNexis IP |
| Google Patents |
| Questel Orbit |
| Others |
Cost & Logistics Intelligence
Enterprise procurement consolidation around unified platforms forces vendors to absorb data licensing costs while maintaining service tiers, compressing margins for mid-tier providers unable to match integrated suite investments.
Pricing Analysis
Warranty and service bundling separates enterprise contracts from modular offerings, with dedicated client success teams and custom implementation support anchoring premium tiers while self-service search tools occupy economy positioning. Pricing stratifies across premium, standard, and economy tiers differentiated by API access depth, historical backfile coverage, and machine learning feature activation. Cost compression in the mid-market intensifies as pharmaceutical buyers consolidate vendor relationships and demand volume discounts for multi-year portfolio management commitments. Law firms and corporate counsel segments show highest price sensitivity due to matter management platform integration friction, while biotechnology firms absorb premium pricing for predictive examiner analytics.
Supply Chain Analysis
Data feed refurbishment and remanufacturing flows concentrate where national patent offices release structured bibliographic datasets for commercial licensing, with the United States, European Patent Office jurisdictions, and China anchoring primary supply nodes. Raw material dependencies include USPTO examination records, EPO register entries, and CNIPA publication feeds, supplemented by proprietary family linking algorithms and semantic indexing engines. Single-source vulnerability runs through exclusive data partnerships with national registries, creating renewal risk for vendors lacking diversified feed arrangements. Distribution runs through direct enterprise sales teams for integrated platforms and channel partners serving mid-market law firm segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation accelerates as machine learning integration demands render legacy architectures obsolete, forcing vendors without transformer-based capabilities toward acquisition or exit.
For Market Incumbents: Deploy graph analytics capabilities to defend enterprise relationships against AI-native competitors targeting supply chain IP risk assessment segments. Incumbents must re-architect semantic indexing engines or cede pharmaceutical accounts to challengers offering compressed prior art analysis timelines. Backward integration into proprietary training datasets from USPTO examiner feedback loops creates differentiation moats unavailable to data-dependent entrants. For New Entrants and Emerging Players: The EU unitary patent system opens a window for cross-jurisdictional portfolio tools targeting validation and enforcement workflows across member states. White-space exists in technology scouting services for corporate venture arms seeking pre-publication inventor mobility signals, and in generative AI validation frameworks awaiting regulatory standardization. Go-to-market positioning should emphasize API-first architecture enabling direct integration with entrenched matter management platforms resisting incumbent connectivity overtures. For Investors and Strategic Acquirers: Re-rating potential sits with specialized semantic search engine developers given pharmaceutical R&D intensity demanding freedom-to-operate automation. Long-term viability favors vendors with compliant audit trails for algorithmic patent analysis outputs as regulatory bodies formalize validation standards. Monitor USPTO artificial intelligence training initiative disclosures for inflection signals on examiner behavior model accuracy improvements that reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies search, analysis, and collaboration workflows reducing enterprise vendor fragmentation. |
| Acquisition of Specialist Firm | Secures transformer-based semantic search engines absent from legacy document processing architectures. |
| Strategic Partnership | Aligns product roadmaps with USPTO AI training initiatives generating structured feedback datasets. |
| Geographic Expansion | Captures Asia-Pacific enterprise accounts where Patsnap anchors relationships through localized implementation. |
| Product Launch | Deploys graph analytics for inventor mobility mapping targeting aerospace supply chain IP risk assessment. |
Research Approach
Multi-period observation of patent prosecution timelines, examiner behavior datasets, and vendor platform roadmaps anchored the trend analysis, supplemented by interviews with intellectual property directors, patent prosecution attorneys, R&D portfolio managers, and legal technology procurement officers. Secondary validation drew from USPTO patent examination statistics, EPO annual reports, WIPO IP statistics databases, and vendor SEC disclosures where available. Bottom-up triangulation across solution type, technology, application, and end user industry segments converged with top-down market sizing from national patent office filing volumes and enterprise software expenditure patterns.
Segment-weighting applied differential growth assumptions across competitive intelligence, portfolio management, patent search, and technology scouting workflows, with technology dimensions spanning machine learning, natural language processing, and graph analytics capabilities. CAGRs were derived from regression analysis of historical adoption curves and forward projection of R&D optimization and IP risk management application penetration. Forecast inputs incorporated pharmaceutical R&D pipeline valuations and USPTO examination backlog trajectory assumptions.
Caveats apply where USPTO examination guideline revisions, EPO unitary patent system implementation delays, or generative AI regulatory standardization timelines could materially shift the outlook. Practitioners should monitor USPTO artificial intelligence initiative progress and EU unitary patent validation uptake rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Big Data Analytics in BFSI Market
Analytics
HR Analytics Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Video Analytics Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
CSP Network Analytics Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Italy ICT Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Global Enterprise Performance Management Market
Analytics
Global Healthcare Cloud Based Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Asia-Pacific HR Analytics Market