
 Europe Data Monetization Market | 2026-2036
Europe Data Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Monetization Market Analytics
Platform licensing revenue from raw data resale is tilting toward enriched analytics and predictive model subscriptions. SAP SE leverages its S/4HANA installed base to embed data monetization tools directly into enterprise ERP workflows. Microsoft Corporation anchors its position through Azure Purview and Fabric integrations that unify governance with commercialization. Snowflake competes by extending its Data Cloud marketplace model across European financial services and healthcare verticals.
Data monetization encompasses the conversion of enterprise information assets into measurable economic value through direct sale, licensing, or derivative service offerings, typically requiring metadata tagging, quality scoring, and access-control protocols to ensure tradability. Its primary purpose is to transform dormant or underutilized data reservoirs into recurring revenue streams or operational cost offsets. Analytics and data brokerage services capture the deepest margin pools, as buyers prioritize actionable intelligence over unprocessed feeds. AI-powered enrichment within cloud computing deployments represents the fastest-expanding technology layer, while blockchain-based provenance tracking remains nascent but strategically significant for cross-border data transactions.
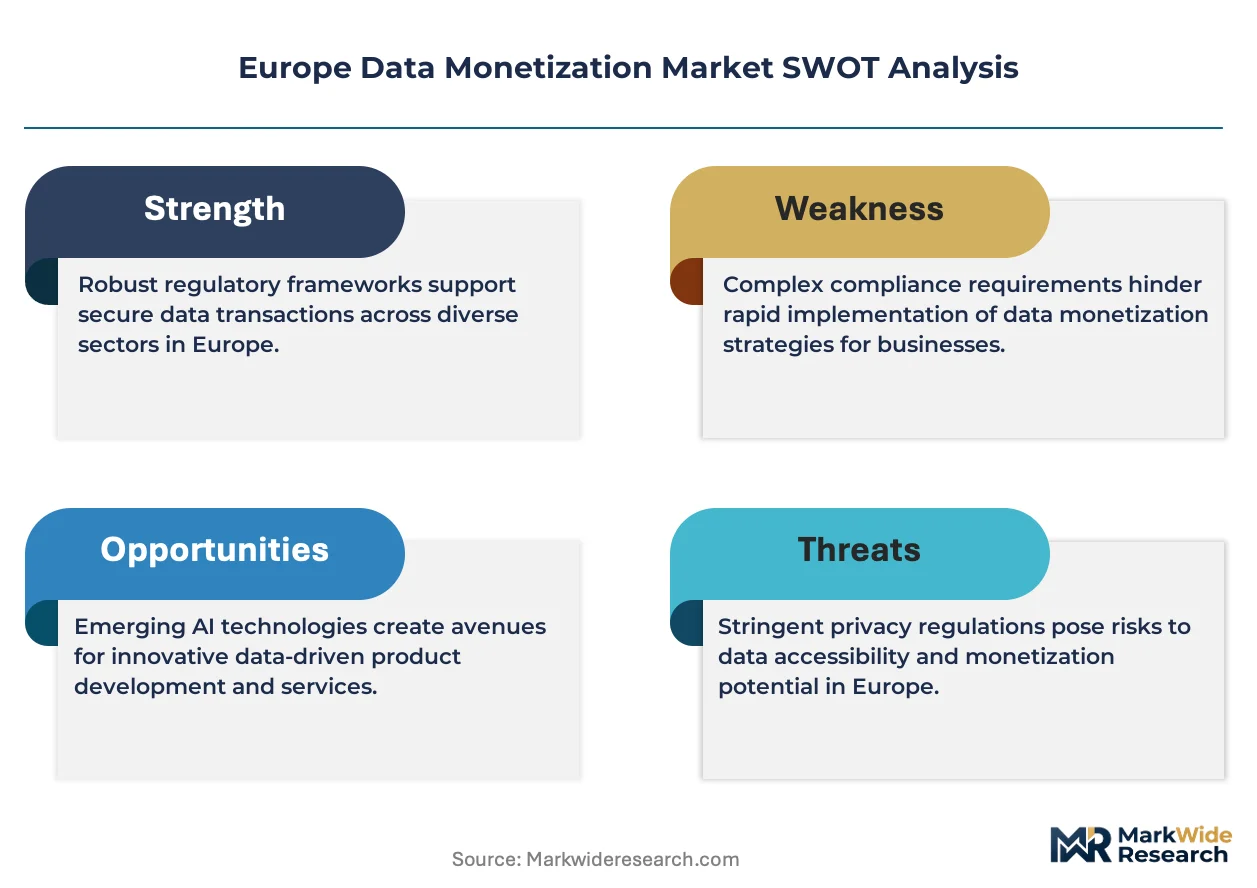
The EU AI Act, GDPR, and the Data Governance Act collectively mandate explainability, consent documentation, and fair-value attribution for monetized datasets, effectively raising compliance costs while creating barriers to informal data trading. EMA guidelines on real-world evidence and the European Health Data Space initiative further channel pharmaceutical and clinical data monetization through approved trust frameworks. Stakeholders must evaluate whether to build captive data marketplaces or participate in emerging sectoral data spaces governed by European standardization bodies.
Market Dynamics
GDPR and the EU AI Act are compressing informal data trading while elevating governed exchange architectures, forcing enterprises to rebuild monetization stacks around consent documentation and explainability requirements rather than raw extraction velocity.
Growth Catalysts
- EMA Real-World Evidence Framework:Pharmaceutical sponsors across Germany and France now monetize longitudinal patient datasets through approved trust frameworks, accelerating clinical data commercialization.
- Cloud-Native Data Exchanges:Financial services institutions in the Netherlands are deploying sectoral data spaces that standardize API-driven subscription models for enriched analytics.
- Synthetic Data Generation:Privacy-preserving augmentation techniques are unlocking monetization of sensitive healthcare and banking records without direct personal data exposure.
Market Restraints
- Compliance Cost Escalation:GDPR Article 30 documentation and EU AI Act conformity assessments impose fixed overhead that disadvantages mid-market data holders.
- Cross-Border Fragmentation:Divergent national implementations of the Data Governance Act create friction for pan-European dataset licensing.
- Quality Scoring Bottlenecks:Absence of unified metadata standards forces bilateral negotiation of data fitness metrics, elongating sales cycles.
Strategic Opportunities
- European Health Data Space:The 2025-2030 implementation timeline creates first-mover advantage for certified health data intermediaries in secondary use markets.
- AI-Model-as-Product:Predictive model subscriptions trained on proprietary datasets command premium pricing over raw data feeds in UK insurance verticals.
- Blockchain Provenance Layer:Immutable lineage tracking is emerging as a contractual requirement for cross-border transactions between Nordic and Benelux exchanges.
Industry Challenges
- Data Engineering Talent Scarcity:Shortage of professionals fluent in both privacy engineering and commercial product development constrains marketplace buildouts.
- Legacy ERP Integration:SAP and Oracle environments require custom middleware to expose governed data APIs without disrupting operational workflows.
- Consent Lifecycle Management:Dynamic withdrawal rights under GDPR force continuous monitoring of downstream usage rights, complicating recurring revenue models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Monetization Market |
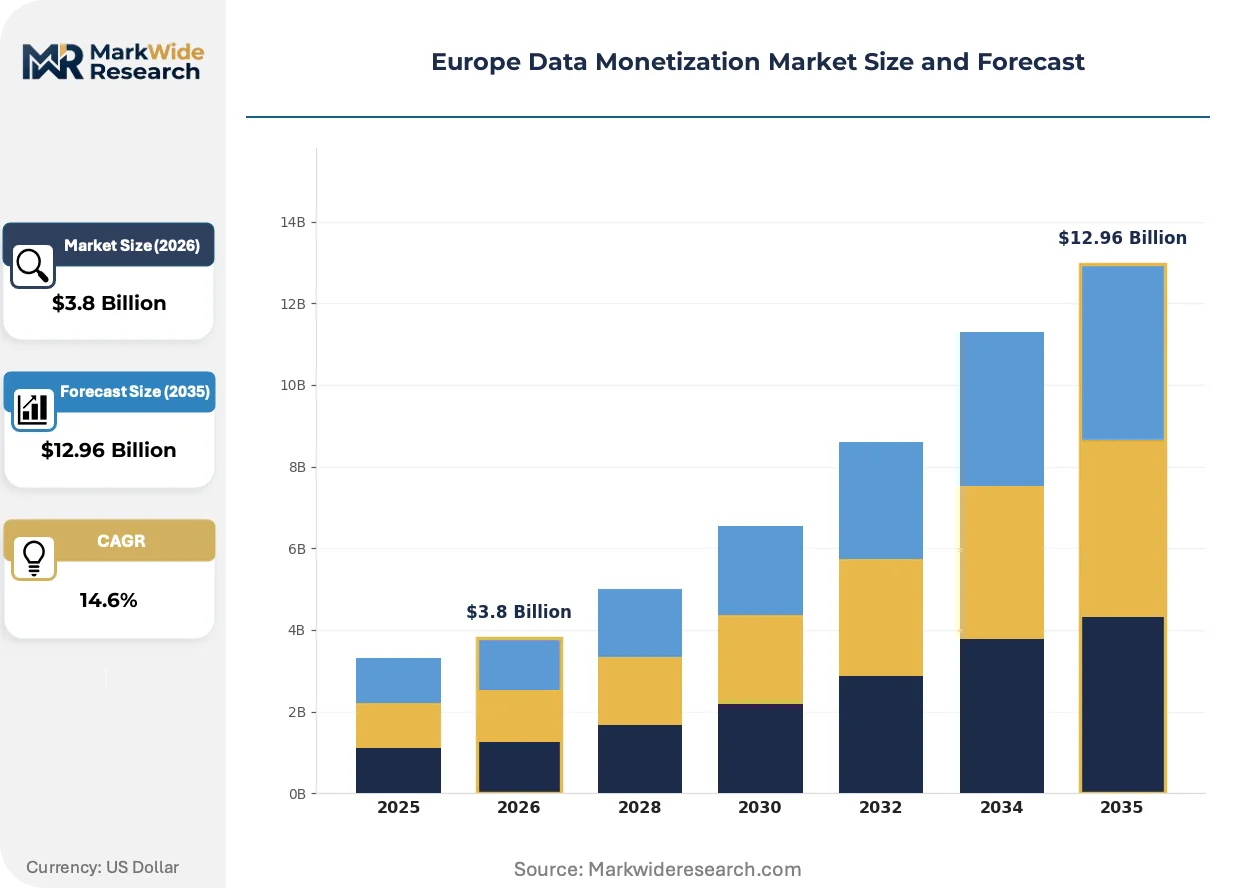
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Advertising, Analytics, Market Research, Asset Management Service Type: Data Brokerage, Consulting, Licensing, Integration Technology: Blockchain, AI, Cloud Computing, IoT Customer Type: Enterprises, Startups, Government Agencies, Nonprofits |
| Companies Covered | Accenture, IBM Corporation, SAP SE, Microsoft Corporation, Google (Alphabet Inc.), Salesforce, Oracle Corporation, Infosys, Snowflake, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Monetization Market Evolving Landscape
Federated analytics architectures are displacing centralized data lakes as the dominant technical paradigm, enabling computation-at-source that satisfies sovereignty requirements while preserving commercial utility.
Confidential computing enclaves are digitizing sensitive dataset collaboration by allowing joint analysis without exposing raw records to counterparties. Pharmaceutical consortiums in Switzerland and Belgium are deploying Intel SGX and AMD SEV infrastructure for multi-party clinical research. This architecture is digitizing trust formation between competitive data holders who previously refused direct sharing.
The EU AI Act's risk-classification system is mandating algorithmic impact assessments for high-stakes automated decision-making systems. Financial services deployers in France and Germany must now document training data provenance and bias testing protocols before commercial deployment. Credit scoring and insurance pricing models face the steepest compliance retrofit requirements.
Buyers are consolidating procurement around subscription-based intelligence platforms rather than per-dataset licensing. Procurement teams at continental retailers and logistics operators now demand predictive outputs with embedded model refresh guarantees. This preference shift is most visible in the UK and Netherlands, where cloud marketplaces have normalized SaaS-style consumption for external data assets.
Europe Data Monetization Market Segmentation
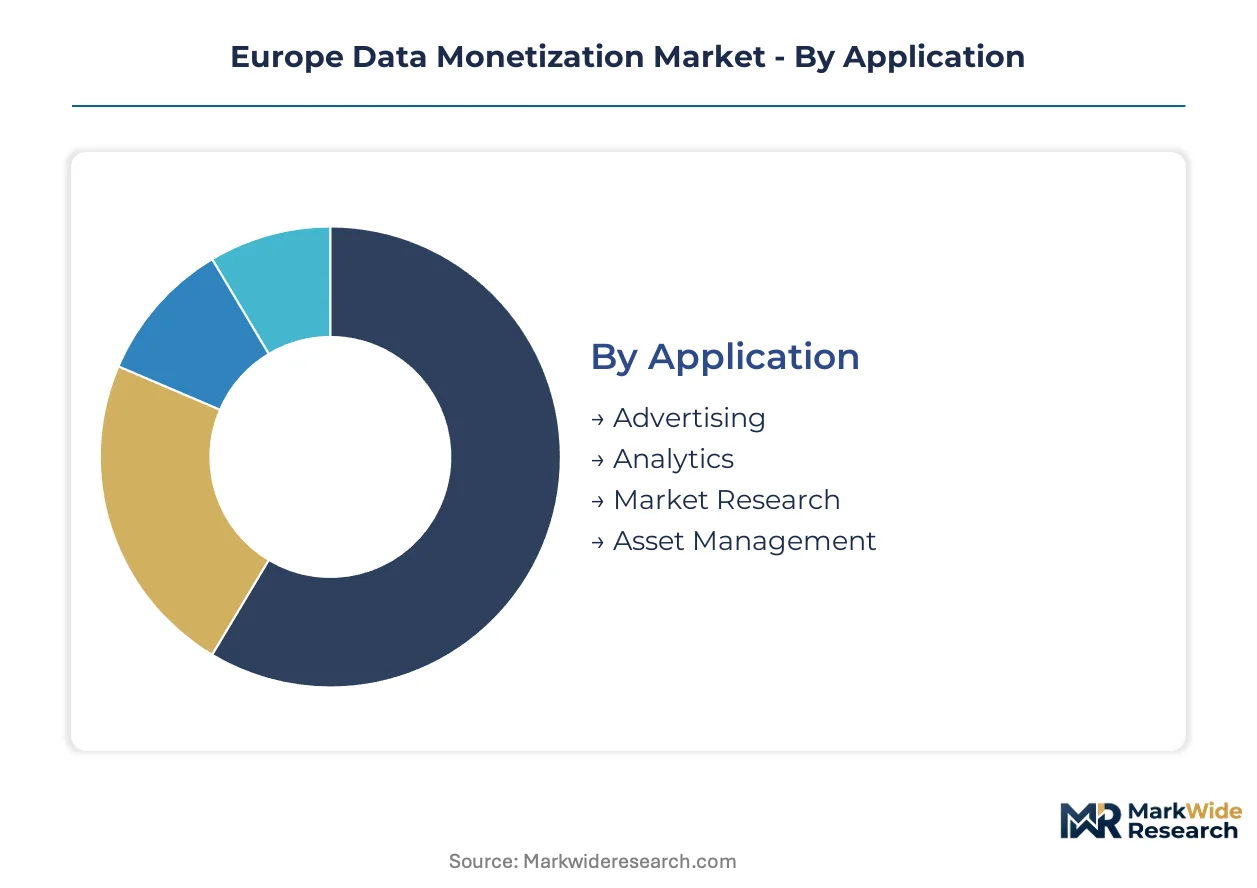
Segmentation reveals how value capture concentrates across distinct commercialization modes in Europe's regulated data economy. Application focus and service delivery models determine margin structure, while technology choice and customer profile shape compliance burden and contract scalability.
Application:
End-use orientation determines whether monetization yields one-time licensing fees or recurring subscription revenue.
- Advertising:Audience segmentation and behavioral targeting datasets generate per-impression or per-campaign licensing. Demand concentrates among retail media networks in the United Kingdom and Netherlands, where retail data clean rooms monetize first-party purchase signals without third-party cookie dependency.
- Analytics:Predictive intelligence subscriptions command premium pricing over raw data feeds. Financial services institutions across Germany and France prioritize credit risk and fraud detection models trained on proprietary transaction histories, driven by EU AI Act explainability mandates that favor documented training data provenance.
- Market Research:Syndicated consumer panels and sentiment tracking services support product development cycles.
- Asset Management:Alternative data feeds for investment decision-making include satellite imagery and supply chain tracking.
Analytics commands the established base. The steepest expansion runs through advertising as retail media networks scale.
Service Type:
Delivery mechanism dictates working capital intensity and customer acquisition economics.
- Data Brokerage:Intermediary platforms match data sellers with buyers, handling quality verification and rights clearance. Cloud-native exchanges in the Netherlands standardize API-driven subscription models, reducing bilateral negotiation overhead that previously elongated sales cycles.
- Consulting:Advisory services span data strategy, valuation methodology, and marketplace architecture. GDPR Article 30 documentation and EU AI Act conformity assessments create sustained demand for privacy engineering expertise, particularly among mid-market data holders lacking internal compliance capacity.
- Licensing:Direct contractual grants of data usage rights with defined scope and duration.
- Integration:Technical implementation services embed monetization capabilities into operational systems.
Consulting anchors near-term revenue. Data brokerage is climbing the fastest as platform economics mature.
Technology:
Infrastructure choice shapes sovereignty compliance and multi-party collaboration feasibility.
- AI:Machine learning pipelines for enrichment, anonymization, and predictive model generation. Pharmaceutical sponsors leverage synthetic data generation to unlock monetization of sensitive patient records without direct personal data exposure, satisfying EMA real-world evidence frameworks.
- Cloud Computing:Scalable storage and compute resources support marketplace operations. Financial services deployers in France and Germany rely on governed cloud architectures to satisfy EU AI Act documentation requirements for high-stakes automated decision-making systems.
- Blockchain:Distributed ledger infrastructure for provenance tracking and smart contract execution.
- IoT:Sensor-derived operational data from connected industrial and consumer devices.
Cloud computing holds the installed base. AI is gaining share fastest through enrichment service premiums.
Customer Type:
Buyer sophistication and procurement scale determine contract structure and pricing power.
- Enterprises:Large organizations with captive data assets seeking external commercialization. Internal data marketplaces at German and French financial institutions expand to monetize proprietary datasets through governed exchange architectures, driven by GDPR compliance requirements that elevate formal trading over informal sharing.
- Government Agencies:Public sector bodies releasing open data or procuring external intelligence. The European Health Data Space initiative channels pharmaceutical and clinical data monetization through approved trust frameworks, creating certified intermediary opportunities.
- Startups:Emerging ventures accessing external data to train models or validate hypotheses.
- Nonprofits:Research and advocacy organizations utilizing subsidized or donated data access.
Enterprises dominate contract value. Government agencies are expanding most quickly through sectoral data space mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across European data monetization demand. Financial services buyers in London and Amsterdam accept premium pricing for governed analytics subscriptions. German industrial buyers resist per-dataset licensing fees, preferring bundled integration services that spread costs across operational budgets.
United Kingdom
Retail media networks and insurance underwriters drive subscription demand for predictive intelligence platforms. The UK Information Commissioner's Office enforces GDPR consent documentation that elevates formal data exchange over informal trading. London's financial district hosts cloud-native data exchanges normalizing API-driven procurement for credit risk models.
Germany
Automotive OEMs and industrial conglomerates monetize sensor-derived operational data through captive marketplaces. The Federal Financial Supervisory Authority (BaFin) mandates explainability documentation for AI-driven pricing models, compressing deployment timelines. Munich and Frankfurt clusters concentrate compliance engineering talent serving cross-border dataset licensing.
France
Pharmaceutical sponsors leverage synthetic data generation to commercialize longitudinal patient records under EMA real-world evidence frameworks. The French National Commission on Informatics and Liberty (CNIL) audits consent lifecycle management for recurring revenue models. Paris hosts health data intermediaries positioning for European Health Data Space certification.
Netherlands
Banking consortia deploy sectoral data spaces standardizing API subscription models for fraud detection analytics. The Dutch Data Protection Authority enforces GDPR Article 30 documentation that disadvantages mid-market data holders lacking internal compliance capacity. Amsterdam's fintech corridor anchors cloud marketplace development for enriched financial intelligence.
Switzerland
Pharmaceutical consortiums deploy confidential computing enclaves for multi-party clinical research without raw record exposure. Swissmedic guidelines align with EMA frameworks for real-world evidence monetization. Basel and Geneva clusters concentrate infrastructure for immutable lineage tracking in cross-border transactions.
Europe Data Monetization Market Competitive Landscape
Cloud-native platforms and legacy ERP-embedded tools split the market between subscription marketplaces and workflow-integrated monetization stacks. Consolidation pressure concentrates around governance-unified commercialization suites. Three archetypes dominate: hyperscale cloud providers with native data governance, enterprise software vendors leveraging installed base distribution, and independent data cloud specialists. Competitive moves center on federated analytics partnerships and synthetic data generation acquisitions that satisfy privacy regulations without degrading dataset utility.
Within the cloud-provider tier, Microsoft Corporation and Google exemplify hyperscale positioning through governance-integrated marketplace infrastructure. SAP SE anchors the ERP-embedded archetype, leveraging S/4HANA distribution to embed monetization tools directly into operational workflows. Snowflake occupies a position among independent data cloud specialists extending marketplace models across regulated verticals. These three represent divergent bets on whether buyers prefer native governance suites, workflow-embedded procurement, or specialized data cloud architectures.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Google (Alphabet Inc.) |
| Salesforce |
| Oracle Corporation |
| Infosys |
| Snowflake |
| Others |
Value Network & Pricing Analysis
Amsterdam's fintech corridor anchors cloud marketplace infrastructure that feeds downstream pricing power for governed analytics subscriptions. Capacity concentration among Dutch banking consortia standardizes API-driven procurement models, compressing bilateral negotiation overhead that previously elongated sales cycles across European financial services.
Pricing Analysis
Subscription renewals and model refresh guarantees drive lifetime value capture across European data monetization. Three-tier pricing structure across premium, standard, and economy levels stratifies by governance certification depth and synthetic data generation capabilities. Cost compression in mid-market data brokerage intensifies because GDPR Article 30 documentation imposes fixed overhead that disadvantages smaller holders. Retail media networks in the United Kingdom exhibit least price sensitivity, while German industrial conglomerates resist per-dataset licensing in favor of bundled integration services.
Supply Chain Analysis
Regulatory fragmentation between EU member states on Data Governance Act implementation dominates supply chain risk assessment. Data engineering talent concentrates in Germany, France, and the Netherlands, with Zurich and Geneva clusters anchoring confidential computing infrastructure for pharmaceutical applications. Raw dataset provisioning draws from SAP S/4HANA installations, Snowflake Data Cloud deployments, and Azure Purview governance layers. Single-source vulnerability persists around privacy engineering expertise fluent in both GDPR compliance and commercial product development. Distribution runs through cloud-native exchanges and ERP-embedded procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's data monetization market functions as a service-attach opportunity where predictive model subscriptions and compliance consulting expand faster than raw data resale. Recurring revenue layers around synthetic data generation and federated analytics deployment outpace one-time licensing growth.
For Market Incumbents: Harden governance-unified commercialization suites against hyperscale cloud provider encroachment by embedding monetization tools deeper into operational workflows. Acquire synthetic data generation capabilities to satisfy EMA real-world evidence frameworks without degrading dataset utility. Channel control through certified health data intermediary status offers defensive positioning as the European Health Data Space mandates tighten. For New Entrants and Emerging Players: Establish a beachhead in mid-market data brokerage where GDPR documentation burdens disadvantage incumbent holders lacking internal compliance capacity. White-space concentrates in pharmaceutical synthetic data services and cross-border provenance tracking for Nordic-Benelux transactions. Go-to-market leverage rests on federated analytics partnerships that satisfy sovereignty requirements without centralized infrastructure investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent data cloud specialists with vertical-specific governance certifications over horizontal platform plays. Long-term viability across the analysis window hinges on recurring revenue attachment rates rather than transactional marketplace volume. Acquisition target archetype: privacy engineering boutiques with EMA or BaFin compliance track records. Signal to watch is certification velocity for European Health Data Space intermediary status.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Data Generation Acquisition | Unlocks monetization of sensitive healthcare records under GDPR without direct personal data exposure. |
| Federated Analytics Partnership | Enables computation-at-source that satisfies EU data sovereignty requirements while preserving commercial utility. |
| Confidential Computing Infrastructure Deployment | Digitizes trust formation between competitive pharmaceutical holders through Intel SGX and AMD SEV enclaves. |
| European Health Data Space Certification | Creates first-mover advantage in secondary use markets for clinical data intermediaries under EMA guidelines. |
| API-Driven Marketplace Standardization | Reduces bilateral negotiation friction in Dutch banking consortia through sectoral data space architectures. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. Conversations with data platform engineers, privacy compliance officers, healthcare informatics directors, and financial services procurement leads informed demand-side dynamics. Secondary sources include EMA real-world evidence submissions, GDPR enforcement actions by national DPAs, cloud provider capex disclosures, and sectoral data space technical specifications. Bottom-up segment sizing triangulates against top-down market envelope calculations.
Calibration against historical adoption curves for cloud marketplace procurement and synthetic data generation deployment shapes the projection framework. Segmentation dimensions span application type, service delivery model, technology infrastructure, and customer sophistication tier across the modeling period. CAGRs derive from fitted growth curves applied to disclosed platform transaction volumes and compliance consulting contract values. Forecast inputs incorporate EU AI Act implementation timelines and European Health Data Space certification velocity.
Sensitivities concentrate around regulatory enforcement intensity and cross-border data flow permissibility. Forecasts reflect assumptions about consent lifecycle management technology maturation and federated analytics commercial adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Italy Geospatial Analytics Market
Analytics
Predictive Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Spain Geospatial Analytics Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Global Systems of Insight Market
Analytics
Construction Data Analytics Software Market
Analytics
Online Analytical Processing Market
Analytics
App Analytics Market
Analytics
Drone Analytics Software Market
Analytics
Service Analytics Market
Analytics
Retail Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Imagery Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market