
 Mercaptopropionic Acid Market | 2026-2036
Mercaptopropionic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Mercaptopropionic Acid Market Foresight
Specialty grade formulation revenue is rewriting margin distribution across the Mercaptopropionic Acid value chain, pulling returns upstream from commodity blending toward controlled-purity synthesis. BASF SE leverages its Ludwigshafen integrated site to sustain captive mercaptan output for polymer additive streams. Bruno Bock Chemische Fabrik GmbH & Co. KG anchors European supply through dedicated thiol chemistry expertise and custom specification capability.
Mercaptopropionic acid is an organosulfur compound with the formula HSCH₂CH₂COOH, featuring a thiol group that enables metal chelation, polymer crosslinking, and surface modification reactions across pH-tolerant conditions. Its primary commercial purpose centers on serving as a molecular bridge in adhesive curing systems and as a chain transfer agent in controlled radical polymerization. High Purity output commands premium positioning due to pharmaceutical and electronics end-use qualification requirements, while Industrial Grade volumes dominate tonnage flows into coating agent applications. Polymer Additives represents the fastest-growing application dimension as sulfur-functionalized demand from automotive lightweighting and construction sealant sectors intensifies.
EPA oversight of thiol compound emissions shapes manufacturing site permitting and wastewater handling protocols for US-based producers, while REACH registration requirements in Europe mandate extensive toxicological dossiers for mercaptan imports above one-tonne thresholds. China's MEE enforces GB standard compliance for volatile organic compound releases from thiol production facilities, creating divergent compliance cost structures across major supply regions. Stakeholders must monitor regulatory harmonization pressures between OECD chemical hazard classifications and emerging national thiol-specific limits that could fragment market access conditions.
Market Dynamics
Sulfur-functionalized polymer demand from automotive lightweighting programs is compressing specification cycles for mercaptopropionic acid suppliers, forcing qualification timelines that favor integrated thiol chemistry operations over merchant traders.
Growth Catalysts
- REACH registration thresholds:One-tonne import mandates in Europe filter out non-compliant traders, consolidating volume with dossier-holding producers capable of supporting downstream polymer additive certification.
- Construction sealant sulfur demand:Building envelope regulations in Germany and the United States specify crosslinking efficiency standards that mercaptopropionic acid satisfies through thiol-ene reaction pathways.
- Captive mercaptan synthesis:Ludwigshafen and Shanghai chemical parks maintain backward-integrated thiol production, securing supply continuity for pharmaceutical and electronics-grade qualification programs.
Market Restraints
- Propylene sulfide feedstock volatility:Mercaptopropionic acid production depends on propylene sulfide availability, with pricing swings tracking olefin market conditions and refinery sulfur recovery rates.
- Thiol odor handling infrastructure:EPA wastewater protocols and MEE volatile organic compound standards impose capital-intensive scrubbing and containment systems that raise fixed cost barriers for new entrants.
- Cysteamine substitution in metal chelation:Pharmaceutical formulators increasingly specify cysteamine derivatives for certain chelation applications, displacing mercaptopropionic acid in parenteral drug intermediate segments.
Strategic Opportunities
- India specialty chemical expansion:PLI scheme incentives for active pharmaceutical ingredient manufacturing create demand for high-purity thiol intermediates in Mumbai-Pune and Hyderabad chemical corridors.
- Bioconjugation application emergence:Antibody-drug conjugate programs require thiol-reactive linkers, opening qualification pathways for pharmaceutical-grade mercaptopropionic acid in controlled-purity synthesis.
- MEE dual carbon compliance:China's carbon intensity targets favor sulfur-recovery-integrated thiol production, advantaging producers with co-located refinery sulfur streams over standalone operations.
Industry Challenges
- Thiol chemistry talent scarcity:Organosulfur synthesis expertise concentrates among retiring specialists in European and Japanese chemical clusters, constraining technical service capacity for new market entrants.
- Pharmaceutical-grade certification timelines:DMF filing and ICH Q7 compliance for high-purity mercaptopropionic acid extends eighteen to thirty-six months, compressing returns on specification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mercaptopropionic Acid Market |
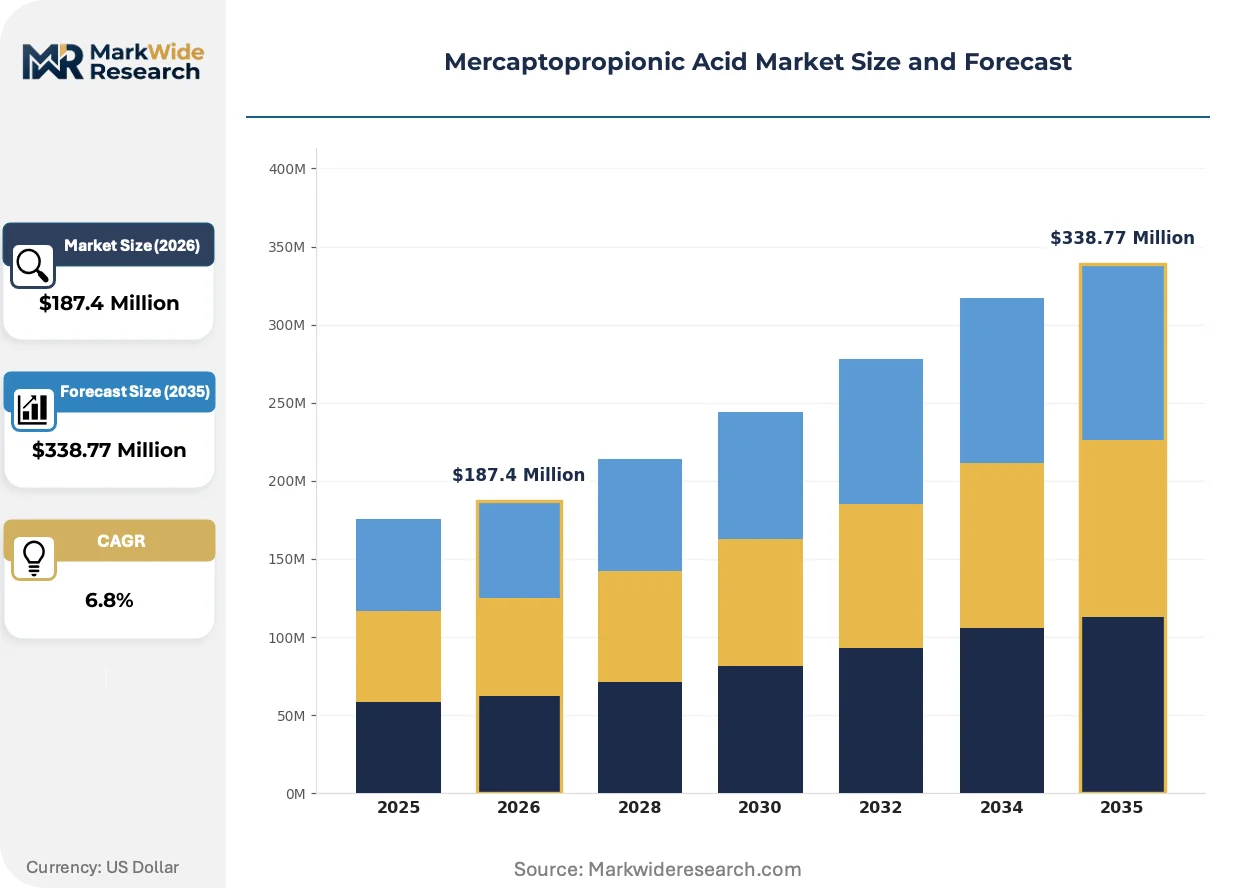
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High Purity, Specialty Grade, Industrial Grade Application: Adhesives, Coating Agents, Polymer Additives, Intermediate Chemicals End User: Pharmaceuticals, Agriculture, Cosmetics, Electronics Packaging Type: Drums, Jerricans, Bags, Tanks |
| Companies Covered | BASF SE, Arkema Group, Bruno Bock Chemische Fabrik GmbH & Co. KG, Evonik Industries AG, Merck KGaA, Chevron Phillips Chemical Company LLC, Lanxess AG, Thermo Fisher Scientific Inc., Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mercaptopropionic Acid Market Shifts & Advancements
Process intensification and regulatory data harmonization are restructuring how mercaptopropionic acid producers compete, with specification-grade synthesis displacing commodity blending as the primary value capture mechanism.
Continuous flow thiolation technology is hybridizing batch mercaptan production into modular, temperature-controlled reactor sequences. Polymer additive manufacturers in Germany and the United States are qualifying flow-sourced material for adhesive curing systems that demand sub-ppm metal content. This process architecture compresses impurity profiles while reducing solvent inventory, enabling just-in-time supply contracts that displace traditional bulk shipment models.
REACH Annex VIII extended one-tonne data requirements now mandate reproductive toxicity studies for thiol imports into European Union member states. The industrial consequence elevates registration costs above six figures for new market entrants, filtering supply toward established dossier holders. Pharmaceutical and electronics-grade segments respond by consolidating purchase agreements with registrants possessing completed toxicological packages, marginalizing non-compliant traders.
Specification-driven procurement now dominates polymer additive purchasing, with automotive tier-one suppliers requiring Certificate of Analysis alignment to OEM crosslinking protocols. Direct contracting between mercaptopropionic acid synthesizers and adhesive formulators is replacing distributor-mediated spot purchases in Stuttgart and Detroit supply corridors. This channel compression is most visible in automotive sealant applications where lightweighting programs demand lot-to-lot consistency in sulfur content.
Mercaptopropionic Acid Market Segmentation
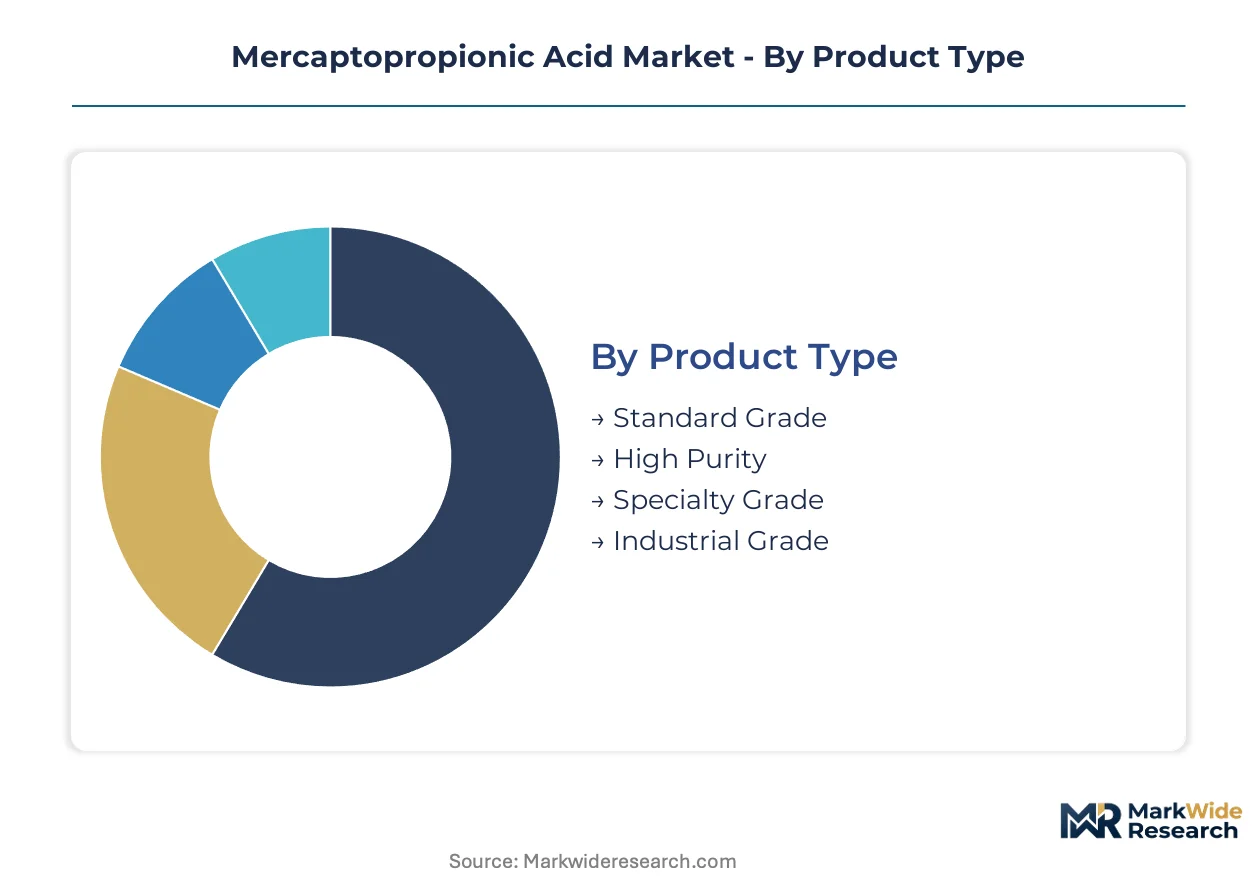
Segmentation in mercaptopropionic acid markets reveals how sulfur-functionalized chemistry splits across radically different service intensity requirements. Pharmaceutical-grade supply chains demand eighteen-to-thirty-six-month qualification timelines, while industrial coating applications operate on spot purchasing cycles with minimal technical support.
Product Type:
After-sales-service intensity escalates dramatically as purity tiers climb, with specialty grade requiring dedicated regulatory dossier maintenance and batch-specific Certificate of Analysis alignment that commodity grades never demand.
- High Purity:Sub-ppm metal content specifications serve antibody-drug conjugate linkers and semiconductor surface modification protocols. Pharmaceutical formulators in Germany and the United States consolidate purchase agreements with dossier-holding producers capable of supporting DMF filing and ICH Q7 compliance. REACH Annex VIII reproductive toxicity studies and EPA wastewater handling protocols compress supplier pools to integrated thiol chemistry operations.
- Specialty Grade:Controlled-purity synthesis with custom specification capability anchors European supply through dedicated thiol chemistry expertise. Polymer additive manufacturers in automotive lightweighting programs demand lot-to-lot consistency in sulfur content, forcing direct contracting between synthesizers and adhesive formulators that displaces distributor-mediated spot purchases.
- Standard Grade:General-purpose mercaptan output serves commodity blending applications with minimal regulatory burden.
- Industrial Grade:Volume-dominant tonnage flows into coating agent applications where specification tolerance permits broader supplier qualification.
By volume, Industrial Grade leads. By growth pace, Specialty Grade is climbing the fastest.
Application:
Margin capture potential varies threefold across these application dimensions, with polymer crosslinking chemistry commanding premium positioning over commodity adhesive curing.
- Polymer Additives:Sulfur-functionalized demand from automotive lightweighting and construction sealant sectors intensifies specification cycles. Building envelope regulations in Germany and the United States specify crosslinking efficiency standards that mercaptopropionic acid satisfies through thiol-ene reaction pathways. Stuttgart and Detroit supply corridors exhibit channel compression as tier-one suppliers require Certificate of Analysis alignment to OEM protocols.
- Adhesives:Curing system applications leverage thiol-ene click chemistry for rapid, pH-tolerant bonding across industrial assembly operations. Continuous flow thiolation technology enables just-in-time supply contracts that displace traditional bulk shipment models for adhesive formulators qualifying sub-ppm metal content material.
- Coating Agents:Surface modification reactions exploit metal chelation properties for corrosion-resistant industrial finishes.
- Intermediate Chemicals:Molecular bridge functionality supports downstream active pharmaceutical ingredient synthesis with variable purity requirements.
By volume, Adhesives leads. By expansion trajectory, Polymer Additives is gaining share fastest.
End User:
Customer procurement sophistication creates sharp segmentation boundaries, with electronics and pharmaceutical buyers demanding captive synthesis relationships that agricultural and cosmetic formulators rarely require.
- Pharmaceuticals:Parenteral drug intermediate segments face displacement pressure from cysteamine derivatives in certain metal chelation applications, though antibody-drug conjugate programs open qualification pathways for pharmaceutical-grade mercaptopropionic acid. DMF filing timelines extend eighteen to thirty-six months, compressing returns on specification investments.
- Electronics:Semiconductor surface modification and printed circuit board fabrication demand sub-ppm metal content with full toxicological dossiers. Ludwigshafen and Shanghai chemical parks maintain backward-integrated thiol production securing supply continuity for qualification programs.
- Agriculture:Crop protection intermediate applications operate through distributor channels with lower regulatory barriers than pharmaceutical supply chains.
- Cosmetics:Personal care formulation demand concentrates in sulfur-functionalized hair and skin conditioning agents with moderate purity requirements.
By volume, Pharmaceuticals leads. By service intensity, Electronics is ahead.
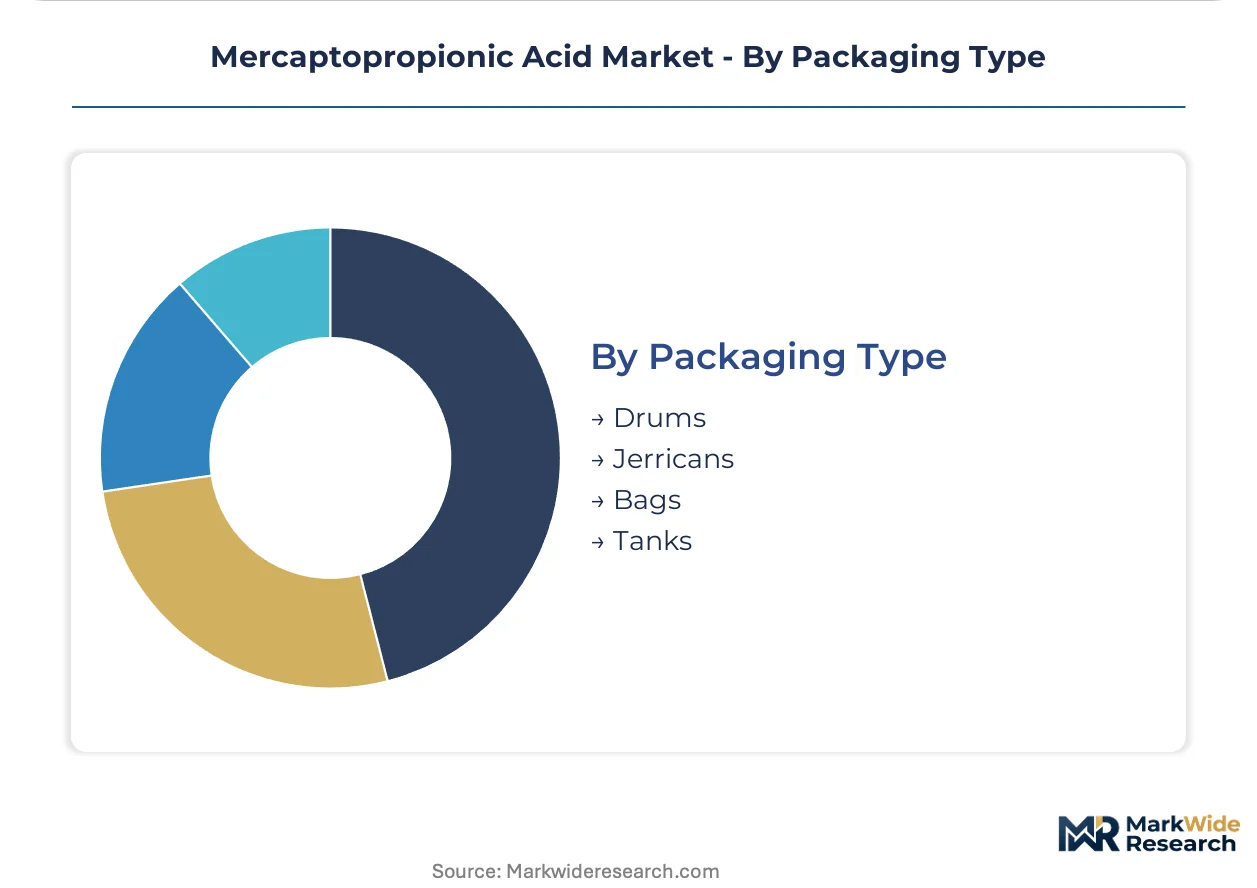
Packaging Type:
Logistics configuration directly reflects end-use contamination sensitivity, with high-purity segments rejecting multi-use container formats that industrial grades accept.
- Drums:Standard bulk handling for industrial-grade coating agents and intermediate chemical shipments with established cleaning protocols.
- Jerricans:Mid-volume containment serves adhesive formulators requiring portability between production lines.
- Bags:Powder handling configurations support solid-phase mercaptopropionic acid derivatives in agricultural intermediate applications.
- Tanks:Dedicated tanker shipments dominate high-purity pharmaceutical and electronics-grade supply chains where cross-contamination risks mandate single-use logistics.
By volume, Drums leads. By compliance stringency, Tanks is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with automotive and construction sectors in Germany and the United States driving polymer additive specifications while pharmaceutical and electronics clusters in China and Switzerland concentrate high-purity demand.
United States
Automotive lightweighting programs in Detroit and construction sealant specifications in Texas drive polymer additive consumption. EPA wastewater protocols and thiol emission standards tighten manufacturing site permitting, raising fixed cost barriers. The Gulf Coast chemical corridor hosts integrated thiol operations serving pharmaceutical qualification programs.
Germany
Building envelope regulations specify crosslinking efficiency standards for construction sealants, while automotive tier-one suppliers in Stuttgart demand lot-to-lot sulfur consistency. REACH Annex VIII reproductive toxicity studies filter supply toward dossier-holding producers. The Ludwigshafen chemical park maintains backward-integrated mercaptan synthesis for captive polymer additive streams.
China
Electronics-grade demand concentrates in the Yangtze River Delta for semiconductor surface modification applications. MEE GB standards enforce volatile organic compound releases from thiol production facilities, while dual carbon targets favor sulfur-recovery-integrated operations. Shanghai chemical parks secure supply continuity for high-purity qualification programs.
Switzerland
Pharmaceutical formulators in Basel specify sub-ppm metal content for antibody-drug conjugate linker applications. Swissmedic oversight of active pharmaceutical ingredient intermediates extends qualification timelines. The Basel-Leverkusen corridor maintains specialized thiol chemistry expertise for custom specification synthesis.
India
PLI scheme incentives for active pharmaceutical ingredient manufacturing create demand for high-purity thiol intermediates. CDSCO filing requirements compress supplier pools to integrated operations. The Mumbai-Pune and Hyderabad chemical corridors concentrate specialty chemical expansion for pharmaceutical-grade mercaptopropionic acid.
Mercaptopropionic Acid Market Competitive Landscape
Capability concentration sits with integrated thiol chemistry specialists; scale advantage sits with diversified chemical conglomerates with captive mercaptan output. The market structures around three tiers: backward-integrated majors with Ludwigshafen-type chemical park operations, dedicated thiol chemistry specialists with custom specification capability, and merchant traders facing REACH registration barriers. Dominant competitive moves include captive synthesis investments and direct contracting with automotive tier-one suppliers.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG occupy positions defined by captive mercaptan production at major European chemical parks. Among dedicated thiol chemistry specialists, Bruno Bock Chemische Fabrik GmbH & Co. KG exemplifies the custom specification capability that anchors European supply for pharmaceutical and electronics-grade segments.
| Leading Market Players |
|---|
| BASF SE |
| Arkema Group |
| Bruno Bock Chemische Fabrik GmbH & Co. KG |
| Evonik Industries AG |
| Merck KGaA |
| Chevron Phillips Chemical Company LLC |
| Lanxess AG |
| Thermo Fisher Scientific Inc. |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
Ludwigshafen chemical park capacity dynamics translate directly into downstream pricing power for specialty-grade mercaptopropionic acid, with integrated thiol synthesis operations commanding premium positioning over merchant traders facing REACH registration barriers. Propylene sulfide feedstock volatility and EPA wastewater compliance costs compress margins at industrial-grade tiers while pharmaceutical qualification timelines extend returns on specification investments.
Pricing Analysis
Long-term offtake agreements dominate high-purity pharmaceutical and electronics-grade procurement, locking in eighteen-to-thirty-six-month supply continuity with dossier-holding producers capable of supporting DMF filing and ICH Q7 compliance. Spot purchasing persists in industrial coating applications where specification tolerance permits broader supplier qualification. Three-tier pricing structure across high-purity, specialty, and industrial levels reflects certification burden divergence, with REACH Annex VIII reproductive toxicity studies filtering volume toward registrants. Cost compression in industrial-grade tiers intensifies because propylene sulfide availability tracks olefin market swings. Adhesive formulators exhibit highest price sensitivity due to distributor-mediated spot purchase legacy, while pharmaceutical buyers prioritize supply security over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for European electronics-grade buyers sourcing from Yangtze River Delta producers. Geographic supply concentration centers on Germany, China, and the United States, with Ludwigshafen and Shanghai chemical parks anchoring backward-integrated thiol production. Raw material dependencies rest on propylene sulfide, refinery sulfur recovery streams, and hydrogen sulfide feedstocks. Single-source vulnerability concentrates in pharmaceutical-grade segments where DMF filing timelines compress supplier pools to integrated operations. Distribution runs through direct contracting between synthesizers and automotive tier-one suppliers in Stuttgart and Detroit corridors, displacing traditional distributor channels for polymer additive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive tier-one suppliers and pharmaceutical formulators as direct contracting consolidates purchase agreements with dossier-holding producers, marginalizing non-compliant traders and distributor-mediated spot purchases.
For Market Incumbents: Harden regulatory dossier maintenance capabilities against REACH Annex VIII extended data requirements and EPA wastewater protocol tightening. Invest in captive mercaptan synthesis capacity at Ludwigshafen-type chemical parks to secure supply continuity for pharmaceutical qualification programs. Deepen backward integration into propylene sulfide feedstocks to buffer margin compression from olefin market volatility. For New Entrants and Emerging Players: India specialty chemical expansion in Mumbai-Pune and Hyderabad corridors offers the most penetrable white-space target, with PLI scheme incentives creating demand for high-purity thiol intermediates. Bioconjugation application emergence in antibody-drug conjugate programs opens qualification pathways for pharmaceutical-grade mercaptopropionic acid with lower incumbent lock-in. Pursue continuous flow thiolation technology partnerships to compress impurity profiles and enable just-in-time supply contracts. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical-consolidation play because REACH registration thresholds and pharmaceutical-grade certification timelines erect structural barriers that favor scale. Acquisition target archetype: dedicated thiol chemistry specialists with custom specification capability and completed toxicological packages. Watch for MEE dual carbon compliance enforcement in China as an inflection indicator advantaging sulfur-recovery-integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Sulfide | Captive feedstock supply buffers margin compression from olefin market volatility. |
| Continuous Flow Thiolation Technology Deployment | Modular reactor sequences compress impurity profiles for pharmaceutical qualification. |
| REACH Annex VIII Dossier Completion | Reproductive toxicity studies filter supply toward established registrants in European markets. |
| Direct Contracting with Automotive Tier-One Suppliers | Channel compression displaces distributor-mediated spot purchases in Stuttgart and Detroit. |
| India PLI Scheme Capacity Expansion | Mumbai-Pune and Hyderabad corridors concentrate specialty chemical growth for API intermediates. |
Research Methodology
Desk research of customs and trade data, SEC and European chemical industry association filings, and regulatory dossier databases preceded structured interviews with plant managers at integrated thiol operations, procurement leads at downstream polymer additive manufacturers, distribution channel partners, and technical R&D directors specializing in organosulfur synthesis. Primary fieldwork combined with secondary validation through ECHA registration databases, EPA emission compliance records, and MEE GB standard filings. Bottom-up volume modeling and top-down value triangulation anchored forecast construction.
Assumptions held fixed include REACH registration threshold enforcement at one-tonne import mandates, EPA wastewater protocol stability, and MEE dual carbon target trajectory; varied assumptions included propylene sulfide feedstock pricing elasticity and pharmaceutical qualification timeline compression. Segmentation dimensions modeled across grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from volume trajectory analysis against specification-grade demand intensification. Forecast inputs incorporated automotive lightweighting program sulfur-content specifications and construction sealant crosslinking efficiency standards.
Macroeconomic conditions sit as an overlay; deviation in olefin market cycles, refinery sulfur recovery rates, or carbon pricing enforcement would shift the trajectory for industrial-grade and high-purity segments respectively. Forecasts reflect documented assumptions with continuous validation against operating reality as the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Crotonic Acid Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Alanine Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
1,3-Dichloroacetone Market