
 CRISPR Genomic Cure Market | 2026-2036
CRISPR Genomic Cure Market Size, Share, and Industry Trends Forecast 2026-2036
CRISPR Genomic Cure Market Outlook
Buyer concentration across pharmaceutical firms and large biotechnology companies is rebalancing as hospital systems and specialized gene-therapy centers build in-house editing capabilities. CRISPR Therapeutics leverages its allogeneic CAR-T platform to sustain manufacturing advantages across hematology indications. Intellia Therapeutics anchors its position through lipid nanoparticle delivery systems for in vivo liver-directed editing. Editas Medicine differentiates via engineered Cas variants optimized for ocular and neurological targets.
CRISPR genomic cure denotes therapeutic applications of clustered regularly interspaced short palindromic repeat systems to correct disease-causing mutations through precise DNA cleavage and repair mechanisms, typically employing guide RNA-directed Cas nucleases with editing efficiencies measured by indel rates and homology-directed repair frequencies. Its primary commercial purpose centers on permanent correction of monogenic diseases and engineered cellular immunotherapies. Services and reagents capture dominant margin pools as pharmaceutical outsourcing of GMP-grade guide RNA synthesis and analytical validation expands faster than instrument placements. Cancer therapy applications lead absolute spending while genetic disorders represent the most advanced clinical-stage pipeline with near-term revenue conversion.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme compress regulatory timelines for CRISPR-based treatments, directly shaping market access speed and development capital allocation. The country's national pharmaceutical regulator in Japan and PMDA's sakigake framework create parallel accelerated pathways that fragment global launch sequencing. Stakeholders must monitor evolving germline editing prohibitions versus somatic therapy distinctions across jurisdictions to anticipate reimbursement and ethical boundary constraints.
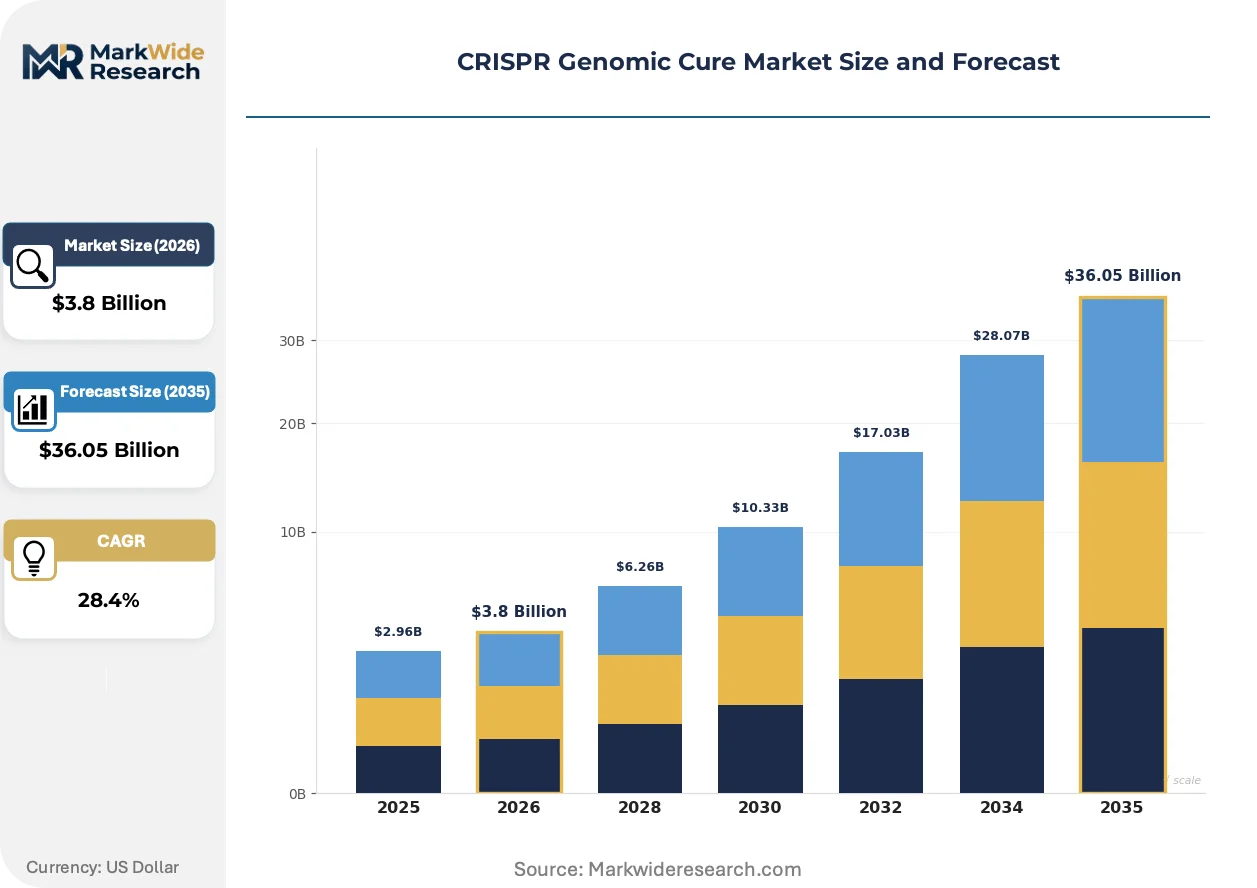
Market Dynamics
Accelerated FDA and EMA approval pathways compress development timelines from discovery to commercialization, forcing capital reallocation toward manufacturing scale-up and analytical validation infrastructure.
Growth Catalysts
- Regenerative Medicine Advanced Therapy (RMAT) Designation:FDA's RMAT pathway grants expedited review and enhanced FDA engagement for CRISPR-based treatments targeting serious conditions, reducing regulatory uncertainty and accelerating investment timelines.
- Lipid Nanoparticle Delivery Maturation:Advances in liver-targeted LNP formulations enable in vivo editing without ex vivo cell manipulation, expanding addressable patient populations beyond hematologic disorders.
- Boston-San Francisco Biotech Cluster Density:Concentrated talent pools and specialized CDMO infrastructure in these hubs reduce time-to-clinic for emerging CRISPR platforms.
Market Restraints
- GMP-Grade Guide RNA Supply Concentration:Synthesis capacity for clinical-grade sgRNA concentrates among three specialized CDMOs in the United States and Switzerland, creating single-source vulnerability.
- Allogeneic Cell Donor Matching Complexity:HLA matching requirements for off-the-shelf CAR-T products limit donor pool scalability and increase manufacturing failure rates.
- Germline Editing Prohibitions:Distinguishing somatic therapeutic applications from heritable modifications creates jurisdictional fragmentation in reimbursement policy across national regulators.
Strategic Opportunities
- Japan Sakigake Framework:PMDA's priority review system offers first-in-world approval potential for CRISPR therapies, enabling premium pricing before US and EU market entry.
- In Vivo Neurological Editing:Engineered AAV variants crossing the blood-brain barrier open treatment for Huntington's disease and ALS without invasive delivery.
- Hospital In-House Editing Capabilities:Academic medical centers building point-of-care manufacturing for autologous therapies bypass traditional pharmaceutical distribution channels.
Industry Challenges
- Cell Processing Technician Shortage:GMP-compliant cleanroom operations for ex vivo editing require specialized training programs that outpace workforce supply in Germany and the United States.
- Analytical Validation Standardization:Absence of harmonized assays for off-target detection across FDA, EMA, and PMDA submissions forces redundant qualification studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CRISPR Genomic Cure Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.05 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Services Technology: Base Editing, Gene Knockout, Gene Editing, RNA Targeting Application: Cancer Therapy, Genetic Disorders, Infectious Diseases, Research End User: Academic Institutions, Biotechnology Companies, Pharmaceutical Firms, Hospitals |
| Companies Covered | CRISPR Therapeutics, Intellia Therapeutics, Editas Medicine, Beam Therapeutics, Merck KGaA, Thermo Fisher Scientific, GenScript, Caribou Biosciences, Vertex Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CRISPR Genomic Cure Market Strategic Shifts
Base editing and prime editing platforms are displacing conventional CRISPR-Cas9 across precision-critical applications, while regulatory frameworks race to accommodate novel nuclease architectures.
Prime editing is converging with high-fidelity reverse transcriptase variants to enable single-nucleotide corrections without double-strand breaks. Large pharmaceutical buyers are prioritizing these platforms for dominant inheritance disorders where indel tolerance is minimal. This convergence is compressing the viable differentiation window for first-generation Cas9-dependent pipelines.
EMA's priority medicines (PRIME) scheme now mandates real-world evidence generation protocols at Phase II, reshaping clinical trial design for gene-editing therapies. Sponsors must integrate patient registry infrastructure earlier, increasing upfront program costs. Hematology indications face the steepest compliance burden due to long-term follow-up requirements for mosaicism monitoring.
Hospital systems are consolidating procurement authority for gene therapies into centralized pharmacy and therapeutics committees, displacing traditional physician-driven purchasing. This concentration demands outcome-based contracting frameworks that tie reimbursement to durable response markers. The United States exhibits the most advanced committee structures, with Mass General Brigham and UCSF Health establishing dedicated gene therapy value assessment boards.
CRISPR Genomic Cure Market Segmentation
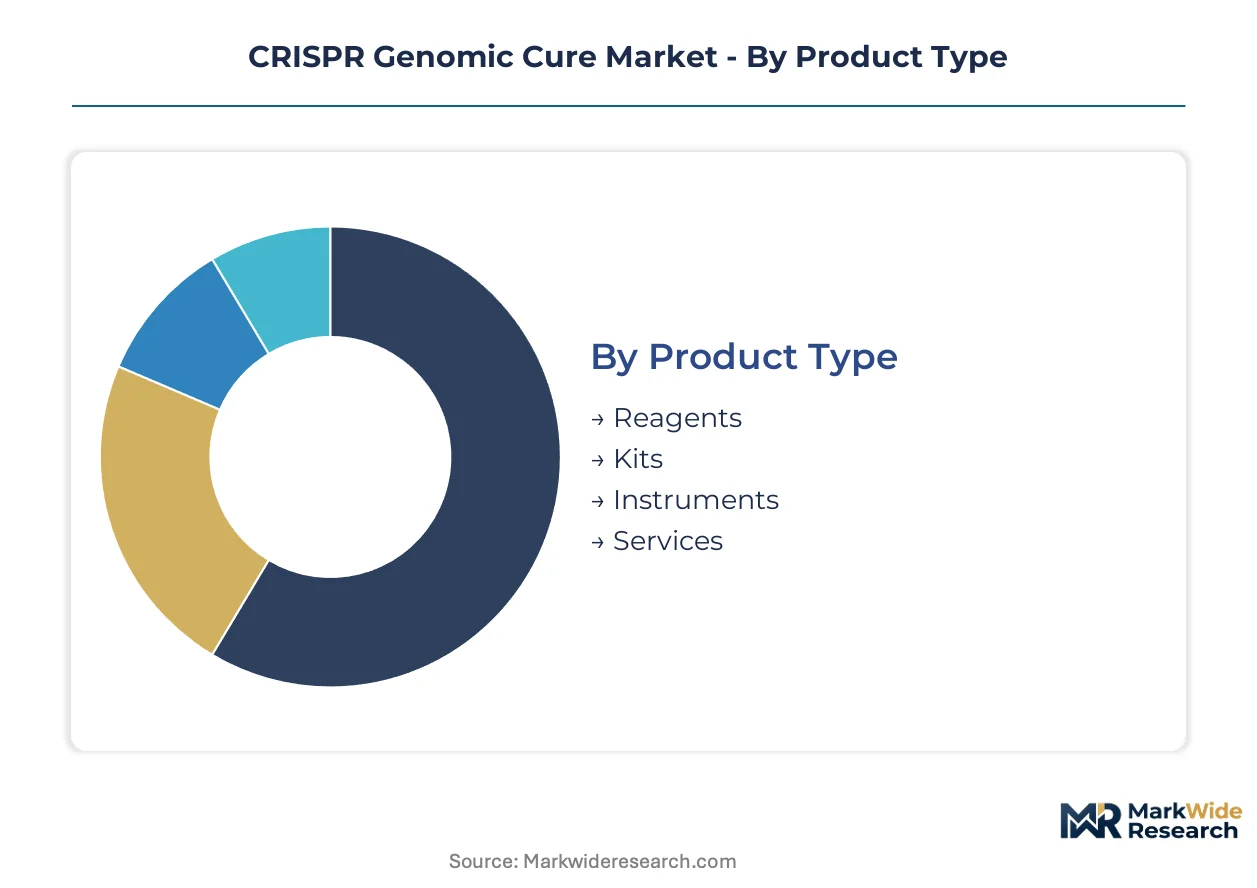
CRISPR genomic cure segmentation reflects divergent commercial models across research tools, therapeutic development, and clinical deployment. Each category carries distinct margin structures, regulatory pathways, and customer procurement behaviors that shape vendor strategy.
Product Type:
Standalone consumables dominate transactional purchasing patterns while integrated instrument-service bundles anchor long-term vendor relationships.
- Reagents:GMP-grade guide RNA synthesis and Cas nuclease formulations command premium pricing due to batch-to-batch consistency requirements. Demand clusters in Boston and Basel manufacturing hubs where CDMOs serve both pharmaceutical sponsors and academic centers.
- Services:Contract manufacturing of patient-specific cell therapies and regulatory-compliant analytical validation generate recurring revenue streams. Hospital systems in the United States are building in-house capabilities that bypass traditional outsourcing relationships.
- Kits:Pre-validated editing reagent combinations reduce protocol development time for research laboratories.
- Instruments:Electroporation systems and cell processing platforms require substantial capital commitment and specialized training.
Volume placements concentrate in Services; the faster expansion belongs to Reagents.
Technology:
Precision thresholds determine platform selection across therapeutic versus research applications, with error tolerance dictating architecture choices.
- Base Editing:Cytosine and adenine deaminase variants enable single-nucleotide conversions without double-strand break formation. Pharmaceutical pipelines in Cambridge, Massachusetts prioritize this architecture for dominant inheritance disorders where indel tolerance is minimal.
- Gene Editing:Conventional CRISPR-Cas9 systems with homology-directed repair remain the workhorse for ex vivo cell engineering. Clinical-stage programs for sickle cell disease and beta-thalassemia rely on this established platform.
- Gene Knockout:Non-homologous end joining pathways achieve rapid loss-of-function for research screening and certain therapeutic targets.
- RNA Targeting:Cas13 and related systems offer transient modulation without permanent genomic alteration.
Gene Editing captures current therapeutic investment; Base Editing is climbing the fastest toward commercialization.
Application:
Regulatory maturity and reimbursement infrastructure create divergent timelines across disease categories despite comparable technical feasibility.
- Cancer Therapy:Allogeneic and autologous CAR-T products represent the largest absolute spending category with established manufacturing infrastructure. FDA's RMAT designation has compressed development timelines for hematologic malignancies.
- Genetic Disorders:Sickle cell disease and beta-thalassemia programs are furthest along the clinical-to-commercial pathway. Vertex Pharmaceuticals and CRISPR Therapeutics have secured regulatory approvals in the United States and United Kingdom.
- Infectious Diseases:Prophylactic and curative approaches target viral reservoirs including HIV and hepatitis B.
- Research:Functional genomics and target validation support pharmaceutical discovery pipelines.
Genetic Disorders anchor near-term revenue conversion; Cancer Therapy maintains the steepest expansion trajectory.
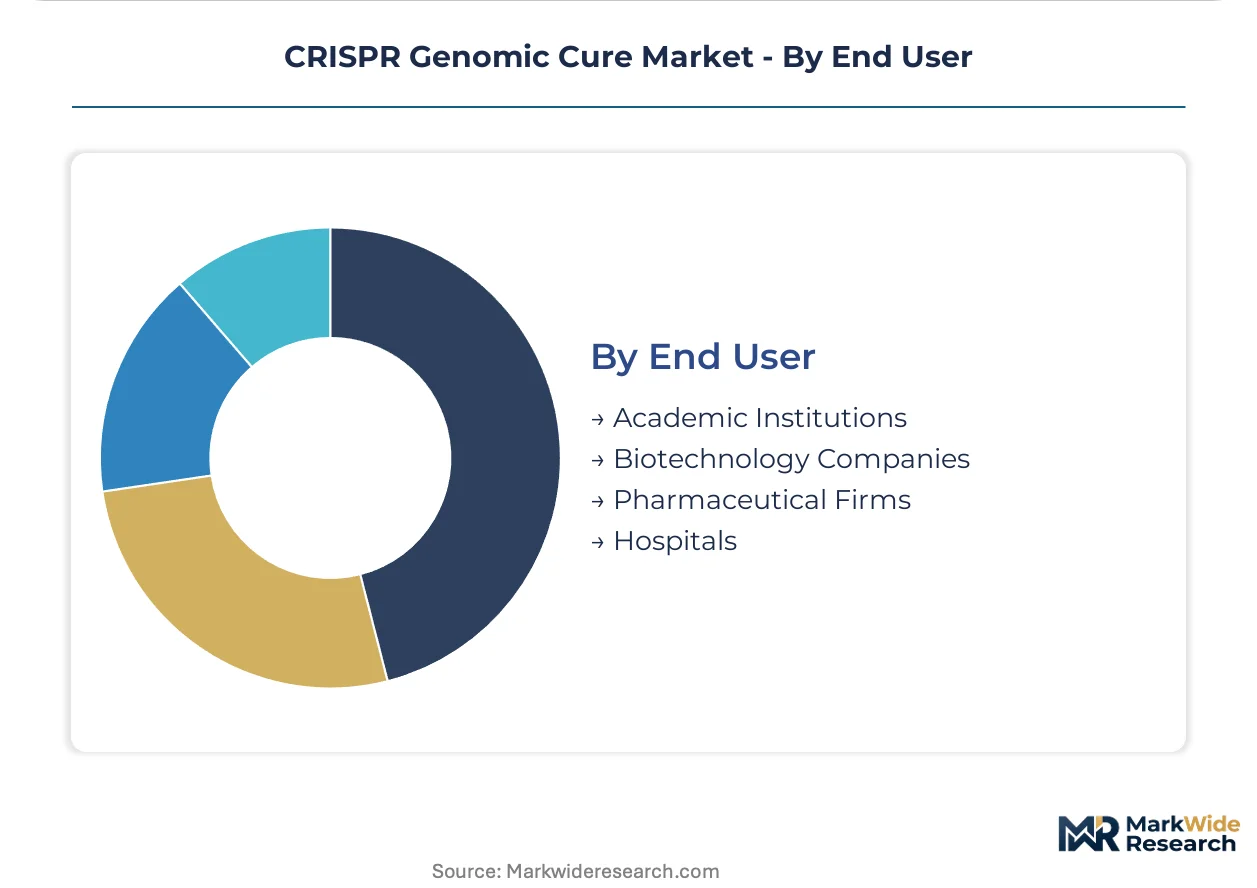
End User:
Procurement authority is consolidating from individual investigators toward centralized pharmacy and therapeutics committees with outcome-based contracting mandates.
- Pharmaceutical Firms:Internal platform development and strategic biotechnology acquisitions dominate capital allocation. Large sponsors prioritize in-house manufacturing capabilities to secure supply chain control over GMP-grade reagents.
- Hospitals:Academic medical centers are building point-of-care manufacturing for autologous therapies. Mass General Brigham and UCSF Health have established dedicated gene therapy value assessment boards.
- Biotechnology Companies:Venture-backed specialists compete on delivery technology and engineered nuclease variants.
- Academic Institutions:Research funding from NIH and equivalent bodies sustains foundational science and training pipelines.
Pharmaceutical Firms command the largest contract values; Hospitals are gaining share fastest through vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized CDMO capacity for GMP-grade guide RNA synthesis concentrates in Basel, Switzerland and the Greater Boston corridor, anchoring supply-side geography for CRISPR therapeutic manufacturing.
United States
FDA's RMAT designation and clustered biotech talent in Cambridge and San Francisco compress development timelines for sickle cell therapies. The NIH accelerates funding through the Somatic Cell Genome Editing program. Vertex Pharmaceuticals and CRISPR Therapeutics have secured commercial approvals, establishing manufacturing precedent.
Switzerland
Specialized CDMO infrastructure in Basel serves global pharmaceutical sponsors requiring clinical-grade sgRNA synthesis. Swissmedic maintains accelerated pathways for advanced therapy medicinal products. Lonza and specialized synthesis providers anchor European supply chain resilience for gene-editing reagents.
United Kingdom
The MHRA's Innovative Licensing and Access Pathway enables rapid conditional approval for CRISPR-based treatments. NHS England's specialized commissioning framework governs reimbursement for high-cost gene therapies. London and Oxford academic centers concentrate early-phase clinical trial capacity.
Japan
PMDA's sakigake framework offers priority review status for first-in-world CRISPR approvals, enabling premium pricing ahead of US and EU entry. METI coordinates national genome editing strategy through the Japan Agency for Medical Research and Development. Tokyo and Osaka medical centers build point-of-care manufacturing capabilities.
Germany
EMA centralized procedures through Frankfurt anchor regulatory submissions for EU-wide market access. The country's national pharmaceutical regulator enforces GMP standards for ex vivo cell processing facilities. Heidelberg and Munich academic hospitals pioneer autologous therapy manufacturing, though technician shortages constrain cleanroom operations.
CRISPR Genomic Cure Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue next-generation editing platforms and in vivo delivery systems. The vendor base stratifies across three tiers: integrated pharmaceutical sponsors with captive manufacturing, specialized biotechnology platforms competing on nuclease engineering, and service-oriented CDMOs capturing margin from GMP-grade reagent supply. Two dominant competitive moves are reshaping positioning: strategic partnerships between platform developers and large pharmaceutical buyers, and backward integration by hospital systems into point-of-care cell processing.
Among platform-specialist developers, CRISPR Therapeutics, Intellia Therapeutics, and Editas Medicine exemplify the biotechnology archetype competing on engineered delivery systems and disease-specific applications. These entities occupy positions defined by their geographic clustering in Cambridge, Massachusetts and their representation of distinct technical approaches to therapeutic gene editing. Beam Therapeutics and Caribou Biosciences sit within the emerging platform tier, representing base editing and next-generation nuclease architectures respectively.
| Leading Market Players |
|---|
| CRISPR Therapeutics |
| Intellia Therapeutics |
| Editas Medicine |
| Beam Therapeutics |
| Merck KGaA |
| Thermo Fisher Scientific |
| GenScript |
| Caribou Biosciences |
| Vertex Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
GMP-grade certification tiers bifurcate the CRISPR genomic cure market into premium-priced clinical-grade reagents and commoditized research-use formulations, with FDA and EMA batch-validation requirements concentrating margin capture among Swiss and Boston-based CDMOs while hospital systems and pharmaceutical sponsors face divergent total-cost-of-ownership calculations based on analytical validation bundling.
Pricing Analysis
Warranty and post-delivery analytical support bundling separates premium GMP-grade guide RNA contracts from unbundled research-grade transactions. Three-tier pricing structure across premium, standard, and economy levels reflects batch-to-batch consistency guarantees, FDA master file cross-referencing, and endotoxin testing depth. Pricing pressure stems from hospital systems building in-house synthesis capabilities that bypass traditional pharmaceutical outsourcing premiums. Academic medical centers exhibit highest price sensitivity due to grant-funded procurement constraints, while large pharmaceutical sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized CDMOs in Switzerland and the United States for clinical-grade sgRNA synthesis, with Lonza and Basel-area providers anchoring European resilience. Raw material dependencies span phosphoramidite chemistries, high-purity solvents, and engineered Cas nuclease cell banks. Tariff exposure on Chinese-sourced precursor chemicals compounds logistics chokepoints at Boston and Basel manufacturing hubs. Distribution runs through pharmaceutical sponsor direct procurement and hospital system centralized pharmacy committees with outcome-based contracting mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA's regenerative medicine advanced therapy designation creates a barrier-to-entry moat for platform developers with established regulatory navigation capabilities and validated manufacturing infrastructure.
For Market Incumbents: Anticipate base editing and prime editing platforms displacing conventional Cas9-dependent pipelines by accelerating investment in engineered nuclease patent estates and lipid nanoparticle delivery manufacturing scale-up. CDMO consolidation threatens margin capture for reagent suppliers without captive GMP-grade synthesis capacity. Backward integration into point-of-care cell processing equipment secures hospital system channel control against emerging platform competitors. For New Entrants and Emerging Players: Hospital pharmacy and therapeutics committees represent the most penetrable channel archetype given their nascent gene therapy value assessment infrastructure and outcome-based contracting appetite. Japan's sakigake framework offers first-in-world approval positioning ahead of FDA and EMA timelines. Target academic medical centers building autologous manufacturing capabilities with modular electroporation system offerings that reduce cleanroom technician dependency. For Investors and Strategic Acquirers: Re-rating potential sits with base editing platform developers given EMA's priority medicines scheme mandating real-world evidence infrastructure at Phase II, which favors sponsors with integrated patient registry capabilities. Long-term viability across the analysis window hinges on germline editing prohibition durability versus somatic therapy reimbursement clarity. Watch for PMDA sakigake approvals as inflection signals for premium pricing precedents.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMO capacity expansion in Basel reduces single-source vulnerability for pharmaceutical sponsors. |
| Regulatory Approval Pathway | FDA RMAT designation compresses timelines for sickle cell and beta-thalassemia programs. |
| Licensing Agreement | Platform developers secure lipid nanoparticle delivery access through university technology transfer. |
| Pipeline Diversification | In vivo neurological editing targets Huntington's disease through engineered AAV variants. |
| Clinical Trial Advancement | Real-world evidence protocols at Phase II reshape hematology indication trial design under EMA PRIME. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA 510(k) submissions, EMA advanced therapy medicinal product designations, ClinicalTrials.gov entries, and formulary databases provided validation layers. Bottom-up modeling of reagent demand and top-down pharmaceutical R&D allocation triangulated market sizing.
Segment-level granularity modeled technology platforms, application indications, and end-user procurement behaviors with regional regulatory cluster differentiation across the analysis window. CAGRs derived from therapeutic pipeline progression rates, approval pathway compression factors, and manufacturing capacity expansion curves. Inputs included CDMO utilization rates, hospital system vertical integration announcements, and germline editing policy evolution signals.
Caveats apply where germline editing prohibition reversals, GMP-grade technician shortage resolution, or allogeneic CAR-T manufacturing failure rate improvements could materially shift the outlook. Forecasts reflect assumptions on regulatory pathway stability and reimbursement infrastructure development pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Microbial Gene Editing Services Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
US Gene Editing Market