
 Knockout Mice Model Market | 2026-2036
Knockout Mice Model Market Size, Share, and Industry Trends Forecast 2026-2036
Knockout Mice Model Market Outlook
North American breeding capacity is fragmenting as specialized facilities compete for precision-genetics contracts. Charles River Laboratories leverages its integrated discovery-services footprint to anchor large-pharma relationships across multiple therapeutic areas. Taconic Biosciences differentiates through gnotobiotic capabilities and controlled-flora model supply, while The Jackson Laboratory sustains nonprofit leadership in strain distribution and genomic-data stewardship.
Knockout mice models are laboratory rodents with targeted gene deletions achieved through CRISPR-Cas9, homologous recombination, or transposon-mediated mutagenesis, typically maintained on defined genetic backgrounds with documented allele sequences for experimental reproducibility. Pharmaceutical companies and contract research organizations represent the dominant end-user categories, with conditional knockouts capturing premium pricing due to tissue-specific induction requirements and temporal control complexity. Global knockouts retain volume leadership in early-target-validation workflows where constitutive gene deletion suffices.
FDA guidelines on animal-model qualification for drug development, alongside USDA Animal Welfare Act enforcement and AAALAC accreditation standards, collectively determine facility eligibility and strain-validation protocols for commercial suppliers. The NIH Office of Laboratory Animal Welfare imposes additional protocol-review requirements on federally funded research using genetically modified rodents. Stakeholders must monitor evolving gene-editing patent landscapes and emerging EPA frameworks for genetically engineered organism containment as these will reshape licensing costs and facility-permitting timelines.
Market Dynamics
The Knockout Mice Model Market faces intensifying pressure from CRISPR-Cas9 patent expirations and the subsequent commoditization of gene-editing services, which compresses pricing power while simultaneously expanding addressable model diversity for contract research organizations.
Growth Catalysts
- NIH Model Repository Funding:Sustained federal investment in centralized strain archives reduces duplication costs and accelerates preclinical validation timelines for academic researchers.
- FDA Animal Rule Pathway:Mandatory biologics development requirements for validated knockout strains create procurement pull-through from pharmaceutical sponsors.
- Conditional Knockout Sophistication:Tissue-specific induction capabilities command premium positioning in oncology and neuroscience therapeutic pipelines.
Market Restraints
- Patent Licensing Burden:Residual CRISPR intellectual property claims from Broad Institute and UC Berkeley impose per-model royalty stacking.
- Genetic Background Standardization:C57BL/6 substrain drift between vendors compromises cross-study reproducibility and triggers validation rework.
- Biosecurity Containment Costs:USDA Animal Welfare Act facility requirements escalate capital intensity for gnotobiotic breeding operations.
Strategic Opportunities
- Humanized Immune System Models:Patient-derived xenograft integration with knockout backgrounds opens immuno-oncology contract research segments.
- AAALAC Accreditation Arbitrage:Pre-certified facility networks in lower-cost US states capture price-sensitive academic volume without quality compromise.
- AI-Driven Phenotype Prediction:Machine learning convergence with genomic databases reduces breeding cycles for novel target validation.
Industry Challenges
- Veterinary Pathology Specialist Scarcity:Board-certified laboratory animal diagnosticians command compensation premiums that strain facility operating models.
- Allele Sequence Documentation Gaps:Incomplete genomic characterization from legacy embryonic stem cell lines forces expensive re-derivation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knockout Mice Model Market |
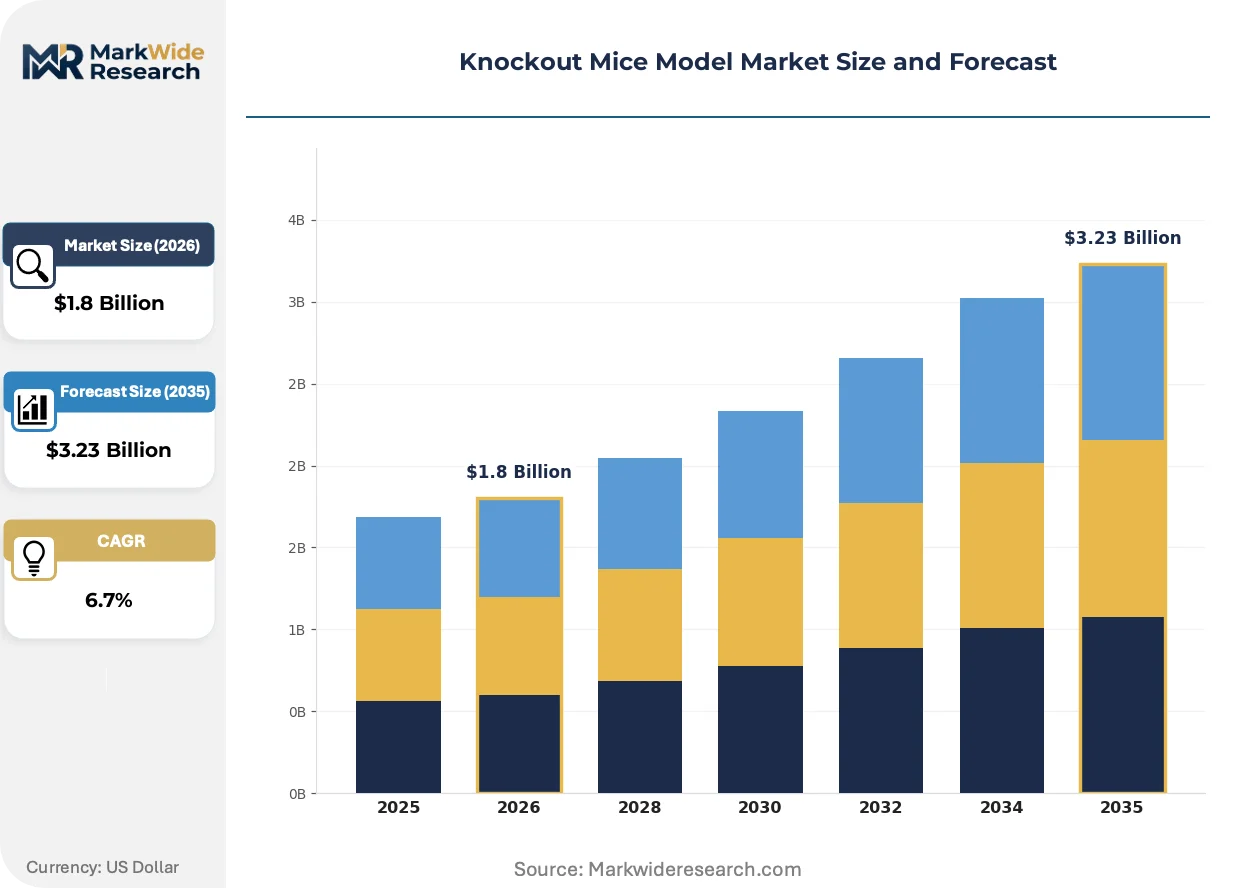
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conditional Knockouts, Global Knockouts, Transgenic Models, Humanized Mice Application: Cancer Research, Cardiovascular Studies, Neurological Disorders, Immunology Research End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations Delivery Mode: Direct Supply, Online Platforms, Research Collaborations, Institutional Purchases |
| Companies Covered | Charles River Laboratories, Cyagen Biosciences, Envigo, genOway, Taconic Biosciences, The Jackson Laboratory, Ozgene Pty Ltd, Trans Genic Inc, Ingenious Targeting Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knockout Mice Model Market Strategic Shifts
Gene-editing toolkits are fragmenting across multiple nuclease platforms, forcing suppliers to build modular service architectures rather than single-technology dependencies. This diversification reshapes competitive moats toward phenotyping depth and data stewardship rather than editing efficiency alone.
Base editing technology is migrating from proof-of-concept publications into commercial service catalogs. Large-pharma target validation teams now specify C-to-T or A-to-G conversions for precise missense modeling without double-strand break complications. The shift compresses demand for conventional knock-in workflows and rewards vendors with dual CRISPR-base editing capabilities.
EMA's revised guideline on non-clinical biodistribution studies for gene therapy vectors tightens animal model qualification requirements. Sponsors must now demonstrate tissue tropism in immunocompetent knockout backgrounds rather than standard wild-type strains. European contract research organizations are responding by expanding dedicated gene therapy model breeding capacity ahead of anticipated regulatory submission volume.
Consortium-based procurement consortia now aggregate demand from mid-tier biotech clusters. These pooled purchasing arrangements displace traditional one-to-one supplier relationships and extract volume-based pricing concessions. The phenomenon concentrates in Boston-Cambridge and Research Triangle Park, where shared facility infrastructure reduces per-study model acquisition costs.
Knockout Mice Model Market Segmentation
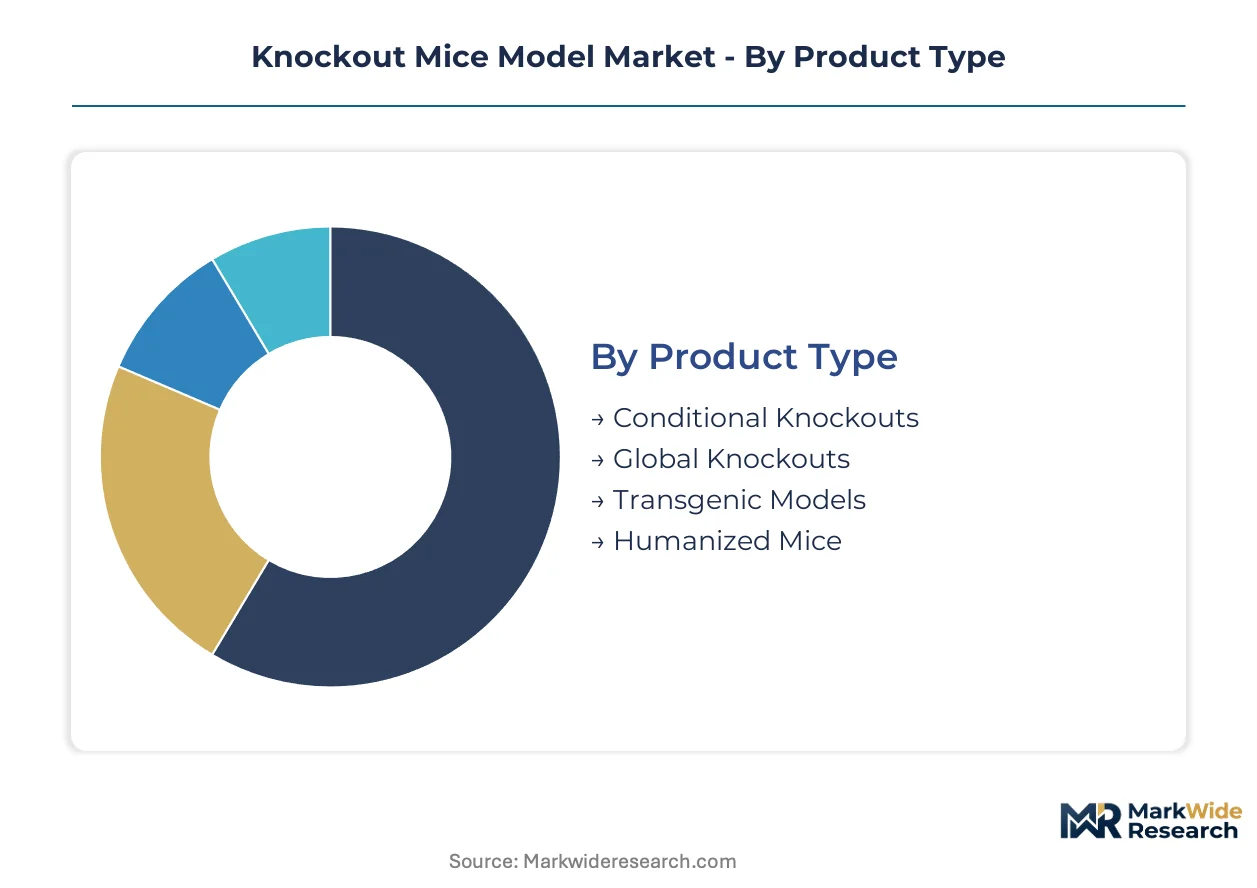
Segmentation in the knockout mice model market reflects how gene-editing complexity, therapeutic application urgency, and procurement channel preferences stratify pricing power across supplier portfolios. Understanding these divisions clarifies where conditional knockouts command premiums versus where global knockouts drive volume throughput.
Product Type:
Cost tier differentiation separates constitutive deletion models from precision-engineered conditional systems requiring Cre-LoxP infrastructure investment.
- Conditional Knockouts:Cre-LoxP recombination systems enable tissue-specific gene deletion with temporal control via tamoxifen-inducible promoters. Oncology and neuroscience therapeutic pipelines in the United States concentrate demand here, driven by FDA Animal Rule pathway requirements for validated tissue-restricted phenotypes.
- Global Knockouts:Constitutive gene deletion across all tissues serves early target validation where phenotypic severity is acceptable. Academic institutions in Germany and Japan leverage these for mechanistic studies where cost efficiency outweighs spatial precision needs.
- Transgenic Models:Random or targeted transgene insertion supports gain-of-function studies and reporter line development.
- Humanized Mice:Human gene knock-in or immune system engraftment enables preclinical validation of biologics targeting human-specific epitopes.
Global knockouts hold installed capacity. Conditional knockouts are rotating up the share rankings.
Application:
Volume concentration tracks pharmaceutical pipeline priorities, with immuno-oncology and rare disease targets reshaping model specification requirements.
- Cancer Research:Tumor suppressor knockouts and oncogene activation models form the backbone of immuno-oncology combination therapy studies. Contract research organizations in the United Kingdom and South Korea expand dedicated breeding capacity for patient-derived xenograft integration.
- Neurological Disorders:Conditional deletion in neural lineages supports Alzheimer's and Parkinson's target validation where developmental lethality prevents global knockout approaches. Academic consortia in Switzerland and the Netherlands drive procurement for longitudinal behavioral phenotyping studies.
- Cardiovascular Studies:Atherosclerosis and hypertension models utilize ApoE and LDLR knockout backgrounds for statin and PCSK9 inhibitor validation.
- Immunology Research:Cytokine and immune checkpoint knockouts enable autoimmune disease mechanism studies and biologics safety assessment.
Cancer research maintains the steepest expansion trajectory. Neurological disorders are climbing the fastest in procurement priority.
End User:
Customer type determines contract structure, with large-pharma annual master agreements contrasting against academic spot purchasing through NIH-funded repositories.
- Pharmaceutical Companies:Multi-year supply agreements with defined genetic background specifications dominate spending, particularly for IND-enabling toxicology studies. FDA qualification requirements for biologics development mandate validated strain documentation that only accredited suppliers provide.
- Contract Research Organizations:Centralized procurement for sponsor studies creates demand for rapid model availability with expedited health monitoring documentation. CROs in Massachusetts and North Carolina aggregate volume through consortium arrangements.
- Academic Institutions:NIH repository access and shared facility infrastructure reduce per-study costs for mechanistic research.
- Biotechnology Firms:Virtual development models outsource breeding entirely, prioritizing speed over captive colony investment.
Pharmaceutical companies hold installed capacity. Contract research organizations are rotating up the share rankings.
Delivery Mode:
Supply channel configuration reflects institutional purchasing maturity and biosecurity containment requirements for gnotobiotic shipments.
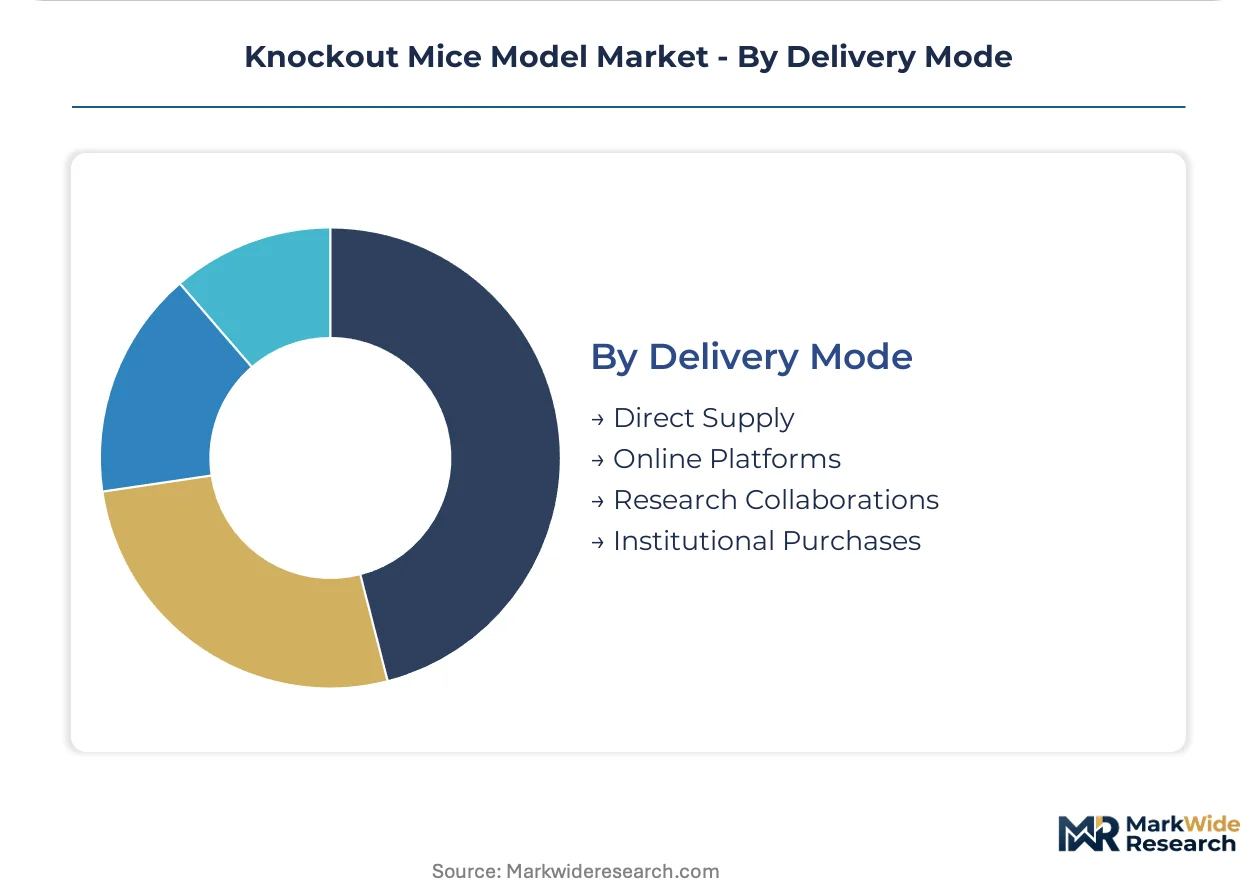
- Direct Supply:Breeding facilities ship live animals or cryopreserved embryos with health certificates and allele sequence documentation. Large-pharma sites in New Jersey and California maintain dedicated receiving quarantine infrastructure.
- Institutional Purchases:Universities leverage centralized procurement offices and shared animal facility budgets to aggregate demand across multiple principal investigators.
- Research Collaborations:Material transfer agreements govern strain exchange between academic labs with reciprocal breeding obligations.
- Online Platforms:Repository databases enable strain discovery and ordering through curated genomic search interfaces.
Direct supply holds installed capacity. Institutional purchases are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys knockout mice predominantly for FDA-mandated biologics qualification, while Germany and Japan prioritize mechanistic academic research with less regulatory-driven procurement. This consumption-mix differential shapes facility investment patterns and breeding specialization across major markets.
United States
NIH repository funding and the FDA Animal Rule pathway drive concentrated demand from pharmaceutical sponsors and contract research organizations. The NIH Office of Laboratory Animal Welfare imposes protocol-review requirements on federally funded research using genetically modified rodents. The Boston-Cambridge cluster anchors commercial breeding capacity, with consortium-based procurement arrangements extracting volume-based pricing concessions from suppliers.
Germany
Academic institutions leverage knockout mice for longitudinal behavioral phenotyping studies in neurological disorder research. EMA guidelines on non-clinical biodistribution studies for gene therapy vectors tighten model qualification requirements across European contract research organizations. The Heidelberg-Mannheim biotech corridor expands dedicated gene therapy model breeding capacity ahead of anticipated regulatory submission volume.
United Kingdom
Contract research organizations expand breeding capacity for patient-derived xenograft integration with immuno-oncology pipelines. The country's national pharmaceutical regulator aligns with EMA frameworks for genetically engineered organism containment and facility permitting. The Cambridge-Oxford arc concentrates specialist phenotyping services and genomic data stewardship operations.
Japan
Academic consortia drive procurement for mechanistic studies where cost efficiency outweighs spatial precision requirements. METI standards influence domestic facility accreditation and quality management systems for genetically modified rodent suppliers. The Kanto region around Tokyo maintains centralized model repositories serving national research institutes.
Switzerland
Academic consortia in Basel and Zurich prioritize conditional knockout models for longitudinal neurodegenerative disease studies. Swissmedic requirements for preclinical study documentation shape supplier validation protocols and strain characterization standards. The Basel biotech cluster integrates phenotyping depth with pharmaceutical sponsor relationships across multiple therapeutic areas.
Knockout Mice Model Market Competitive Environment
Capability concentration sits with specialized breeding facilities possessing gnotobiotic infrastructure and genomic data stewardship competencies; scale advantage sits with integrated discovery-services organizations anchoring multi-year pharmaceutical contracts. The market structure reflects a tiered competitive field where nonprofit repositories, commercial breeders, and contract research subsidiaries occupy distinct positioning. Three archetypes dominate: integrated pharmaceutical service providers, precision-genetics specialists with controlled-flora capabilities, and nonprofit strain distribution centers. Dominant competitive moves include strategic partnerships for rapid model availability and portfolio diversification into humanized immune system platforms.
Within the integrated service tier, Charles River Laboratories exemplifies scale-driven positioning through its discovery-services footprint anchoring large-pharma relationships. Taconic Biosciences occupies a specialist position, representing the precision-genetics archetype with differentiated gnotobiotic capabilities. The Jackson Laboratory anchors nonprofit leadership, exemplifying strain distribution and genomic-data stewardship competencies that sustain centralized repository functions.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Cyagen Biosciences |
| Envigo |
| genOway |
| Taconic Biosciences |
| The Jackson Laboratory |
| Ozgene Pty Ltd |
| Trans Genic Inc |
| Ingenious Targeting Laboratory |
| Others |
Value Chain & Pricing Dynamics
Concentrated breeding capacity in the United States and Germany funnels margin pools toward facilities with AAALAC accreditation and gnotobiotic infrastructure, while CRISPR-Cas9 commoditization erodes pricing power at the service tier.
Pricing Analysis
Long-term master service agreements anchor pharmaceutical procurement, with conditional knockout models commanding premium positioning over constitutive deletion strains due to Cre-LoxP infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates AAALAC-accredited gnotobiotic supply from conventional specific-pathogen-free tiers and repository-sourced academic volume. Cost compression in standard-grade global knockouts is intensifying because CRISPR patent expirations democratize editing capabilities. Academic institutions exhibit highest price sensitivity, while large-pharma toxicology programs prioritize validation documentation over unit cost.
Supply Chain Analysis
Extended payment terms from pharmaceutical sponsors strain working capital for specialized breeding facilities, driving supply-chain finance facility adoption among mid-tier contract research organizations. Live animal and cryopreserved embryo supply concentrates in the United States, Germany, and the United Kingdom, with germplasm import dependencies creating biosecurity documentation burdens. Breeding operations draw from CRISPR reagent suppliers, pathogen-free feed producers, and veterinary diagnostic laboratories. Single-source vulnerability sits with C57BL/6 substrain repositories where genetic drift compromises cross-study reproducibility. Distribution runs through direct facility-to-facility shipment with health certificate documentation, supplemented by NIH-funded repository databases for academic strain discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary pathology specialist scarcity and gnotobiotic infrastructure gaps constrain capacity expansion, creating asymmetric returns for facilities that resolve these bottlenecks through targeted capability investment.
For Market Incumbents: Insulate margin pools by securing captive supply of pathogen-free feed production and expanding gnotobiotic breeding capacity in lower-cost US states to capture price-sensitive academic volume without quality compromise. Patent licensing burden from residual CRISPR intellectual property claims threatens service-tier profitability, making backward integration into in-house nuclease toolkit development a priority lever for differentiation. For New Entrants and Emerging Players: Build out humanized immune system model capabilities for immuno-oncology contract research, where patient-derived xenograft integration with knockout backgrounds remains underpenetrated relative to therapeutic pipeline demand. The most penetrable white space sits with AI-driven phenotype prediction services that reduce breeding cycles for novel target validation. A go-to-market angle anchored in rapid model availability with expedited health monitoring documentation displaces incumbent relationships in mid-tier biotech clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organizations possessing AAALAC-accredited facility networks but lacking phenotyping depth or genomic data stewardship competencies. Long-term viability across the analysis window hinges on regulatory qualification moats rather than editing efficiency alone, favoring targets with FDA-validated strain documentation. The signal to watch is EMA enforcement of revised gene therapy vector biodistribution guidelines, which would accelerate demand for immunocompetent knockout breeding capacity.| Strategic Initiative | Industry Significance |
|---|---|
| AAALAC Accreditation Expansion | Pre-certified facility networks capture price-sensitive academic volume without quality compromise. |
| Humanized Immune System Model Development | Patient-derived xenograft integration opens immuno-oncology contract research segments. |
| AI-Driven Phenotype Prediction Investment | Machine learning convergence with genomic databases reduces breeding cycles for target validation. |
| Gnotobiotic Breeding Capacity Addition | Controlled-flora model supply differentiates positioning in precision-genetics contracts. |
| Base Editing Service Catalog Expansion | C-to-T and A-to-G conversion capabilities capture large-pharma missense modeling demand. |
Study Parameters
Desk research of FDA Animal Rule pathway documentation, NIH repository funding disclosures, and EMA gene therapy guideline revisions preceded structured interviews with pharmaceutical development executives, contract research organization procurement leads, academic facility directors, and veterinary pathologists specializing in laboratory animal diagnostics. Secondary validation drew from SEC filings of publicly traded breeding services providers, AAALAC accreditation databases, and patent landscape analyses from Broad Institute and UC Berkeley CRISPR intellectual property records. Bottom-up strain-level demand modeling and top-down therapeutic pipeline segmentation were triangulated against repository shipment data.
Assumptions held NIH funding levels and FDA biologics qualification requirements stable across the modeling period, with CRISPR patent expiration timelines and EMA enforcement intensity treated as scenario variables. Segmentation dimensions included product type complexity tier, therapeutic application urgency, end-user procurement maturity, and regional regulatory cluster. CAGRs were derived from installed capacity analysis and anticipated pipeline conversion rates. Forecast inputs incorporated gene therapy vector development timelines and immuno-oncology combination therapy study initiation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by nonprofit repositories or technology licensing shifts by CRISPR patent holders would shift outcomes. Macroeconomic pressure on pharmaceutical R&D budgets, regulatory deviation from current Animal Rule enforcement, or breakthrough base editing platform adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Brazil Gene Editing Market