
 Genetically Modified Animal Model Market | 2026-2036
Genetically Modified Animal Model Market Size, Share, and Industry Trends Forecast 2026-2036
Genetically Modified Animal Model Market Insights
Asset-light contract breeding and fee-for-service genome editing is reshaping competitive entry barriers in genetically modified animal models. Charles River Laboratories International, Inc. leverages its global barrier facility network to anchor large-scale knockout mouse production for pharmaceutical clients. The Jackson Laboratory sustains unmatched genetic repository depth, while Biocytogen Pharmaceuticals (Beijing) Co., Ltd. competes on humanized antibody model specialization.
Genetically modified animal models are laboratory organisms with precisely altered genomes—achieved through CRISPR-Cas9, homologous recombination, or transposon-mediated gene transfer—to study gene function, disease mechanisms, or therapeutic responses in vivo. These models serve as predictive surrogates for human physiology in preclinical drug evaluation. Knockout models retain mature revenue share due to standardized phenotyping protocols, though CRISPR-Cas9 technology segments accelerate fastest as editing precision improves turnaround times. Academic institutions and pharmaceutical companies diverge in procurement scale, with biotech firms occupying a mid-tier volume position that demands flexible licensing terms.
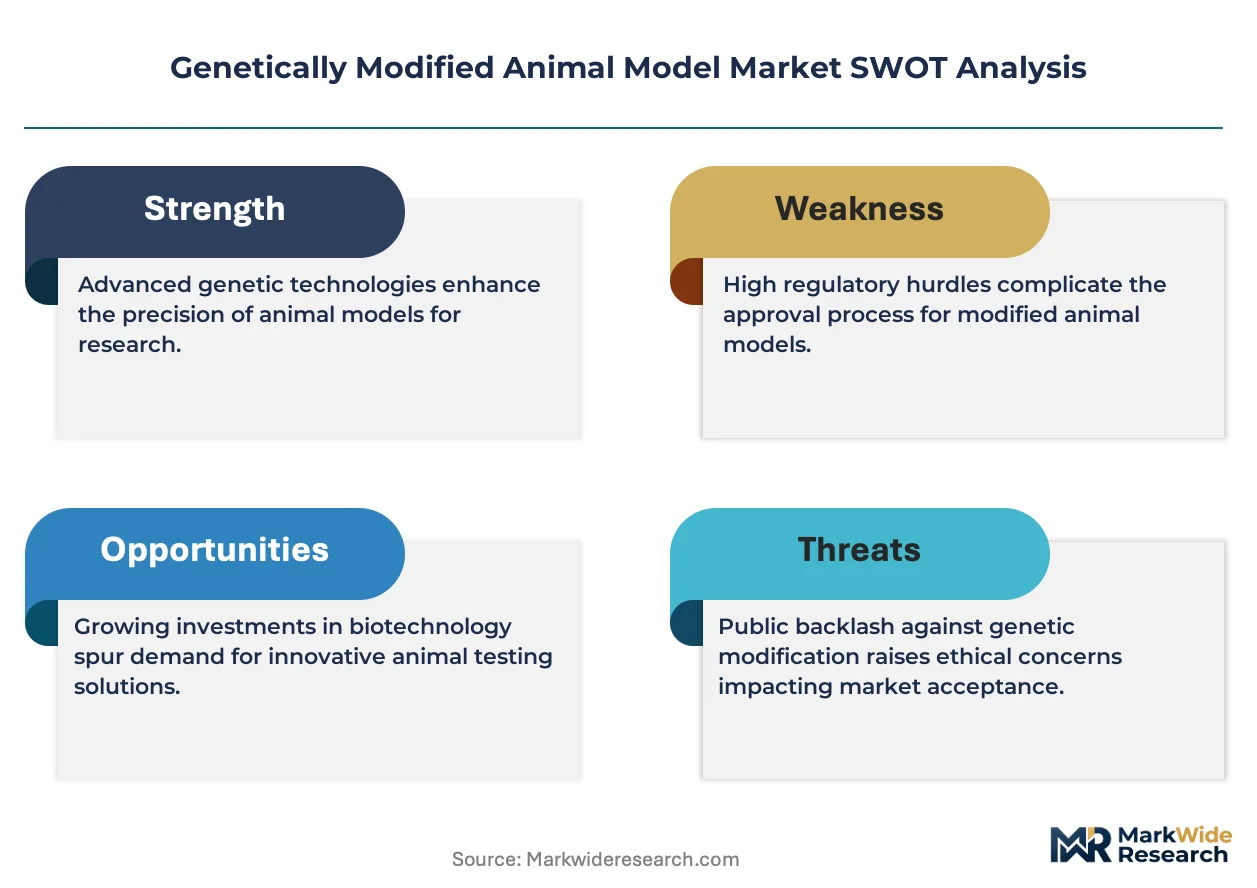
The FDA governs Good Laboratory Practice standards for toxicology studies employing modified animals, while the EMA's ethical review frameworks constrain European supply expansion. China's NMPA and GB standards increasingly influence model validation requirements for trials supporting domestic drug approvals. Stakeholders must monitor evolving cross-border genetic material transfer regulations to secure uninterrupted model distribution.
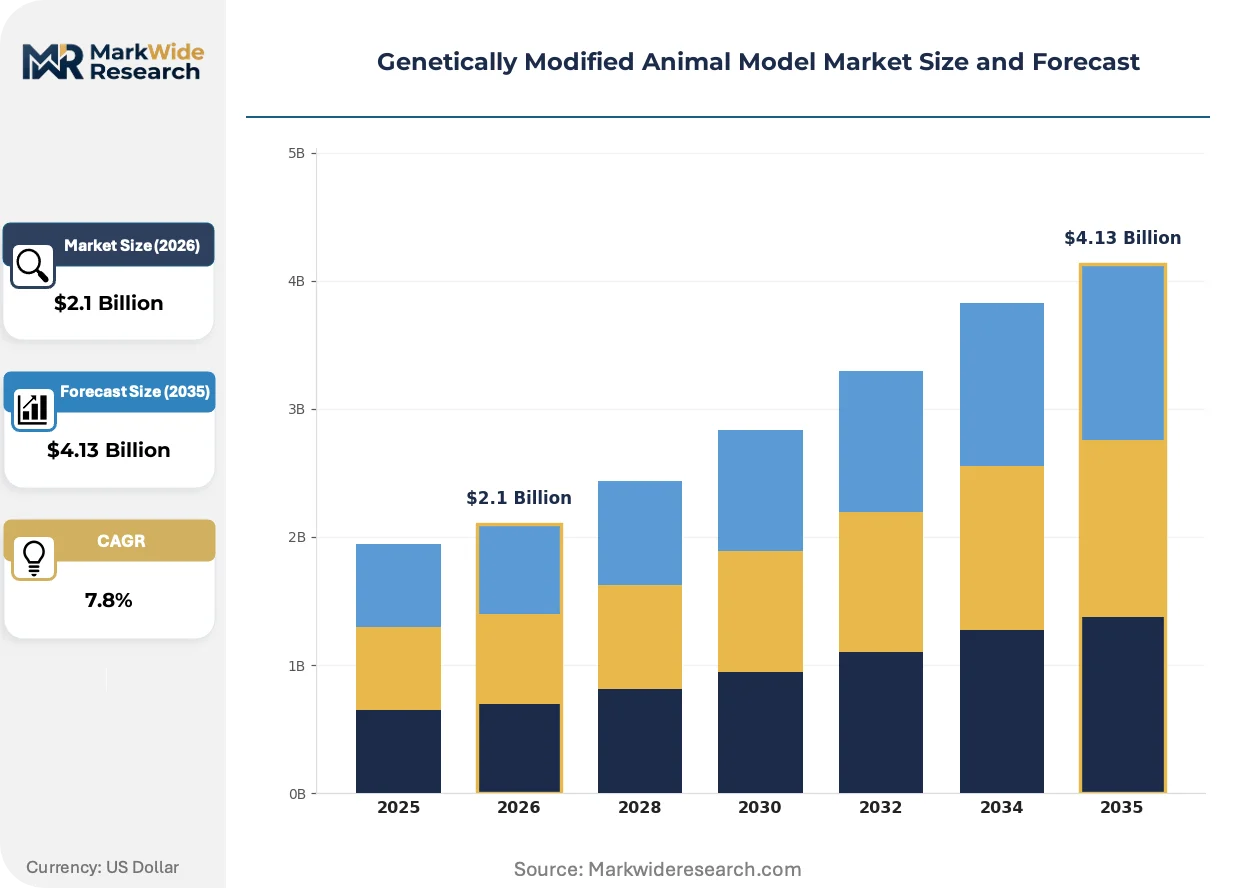
Market Dynamics
CRISPR-Cas9 precision editing is compressing model development timelines from years to months, forcing incumbent breeding facilities to restructure service architectures around rapid-turnaround genome engineering rather than traditional embryonic stem cell protocols.
Growth Catalysts
- Oncology Pipeline Expansion:Pharmaceutical developers require humanized immune system mice for immuno-oncology validation, pulling demand toward specialized CRISPR-edited platforms with engrafted human hematopoietic cells.
- FDA Streamlined Review:The agency's abbreviated pathway for intentionally altered genomic DNA in animals reduces commercialization friction for gene-edited model developers seeking toxicology study validation.
- Boston-Cambridge Cluster Concentration:Biotech procurement gravity in Massachusetts and California sustains premium pricing power for domestic breeding facilities with barrier-certified production capacity.
Market Restraints
- Founder Animal Bottleneck:Germline transmission rates in CRISPR-edited rodents create yield variability, constraining scale-up velocity for high-complexity humanized models.
- European Ethical Review Density:EMA member state divergence in animal welfare authorization timelines fragments cross-border model distribution and extends validation cycles.
- Specialized Pathology Skill Scarcity:Phenotypic characterization of novel knockout lines requires veterinary pathologists with transgenic model expertise, a talent pool concentrated at fewer than twelve academic medical centers.
Strategic Opportunities
- China Domestic Drug Development:NMPA alignment with ICH guidelines is expanding local toxicology study volume, creating demand for GB-compliant genetically modified models with documented genetic drift monitoring.
- Organoid-Animal Hybrid Validation:Convergence of patient-derived organoid co-culture systems with humanized mouse platforms enables next-generation immuno-oncology efficacy screening at reduced in vivo scale.
- Subscription-Based Model Access:Breeding facilities are piloting annual licensing arrangements replacing per-animal transactions, capturing recurring revenue from mid-tier biotech clients with pipeline uncertainty.
Industry Challenges
- Genetic Drift Surveillance:Maintaining allele fidelity across multi-generational breeding colonies demands continuous sequencing verification, elevating operational overhead for high-volume production facilities.
- Cross-Border Material Transfer:National biosecurity frameworks governing CRISPR reagent and live animal shipment create customs friction that disrupts just-in-time model delivery for time-sensitive preclinical studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetically Modified Animal Model Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knockout Models, Transgenic Models, Conditional Models, Chimeric Models Application: Biomedical Research, Drug Discovery, Toxicology Testing, Genetic Studies Technology: CRISPR-Cas9, Homologous Recombination, Transposon-Mediated Gene Transfer, ZFN End User: Pharmaceutical Companies, Academic Institutions, Biotech Firms, Research Organizations |
| Companies Covered | Charles River Laboratories International, Inc., The Jackson Laboratory, Taconic Biosciences, Inc., genOway, Inotiv, Biocytogen Pharmaceuticals (Beijing) Co., Ltd., Janvier Labs, Envigo RMS LLC, Horizon Discovery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetically Modified Animal Model Market Trends and Innovations
Gene editing workflows are fragmenting across specialized service providers, with pharmaceutical sponsors disaggregating vector design, embryo microinjection, and phenotypic validation into separate procurement decisions rather than bundled turnkey contracts.
Prime editing technology is migrating from proof-of-concept publications into commercial service menus at contract research organizations, enabling pharmaceutical toxicology groups to commission precise point mutations without double-strand break repair artifacts. Early adopters in rare disease therapeutic development are driving initial commercial uptake. The structural consequence is compression of founder screening timelines and reduced mosaicism rates in delivered cohorts.
EMA's revised Directive 2010/63/EU implementation guidelines are tightening severity classification thresholds for genetically modified animal procedures, compelling breeding facilities to invest in enhanced welfare monitoring infrastructure. Facilities serving European pharmaceutical sponsors now face elevated capital requirements for social housing and behavioral enrichment systems. The regulatory burden falls disproportionately on mid-scale suppliers lacking dedicated compliance architecture.
Biotech procurement teams are consolidating vendor relationships, awarding sole-source contracts to breeding facilities with integrated genome editing, barrier housing, and pathology capabilities rather than maintaining fragmented supplier panels. This concentration dynamic disadvantages pure-play genome editing shops lacking captive animal production capacity. The shift is most pronounced among Series C-stage therapeutics companies with compressed IND timelines.
Genetically Modified Animal Model Market Segmentation
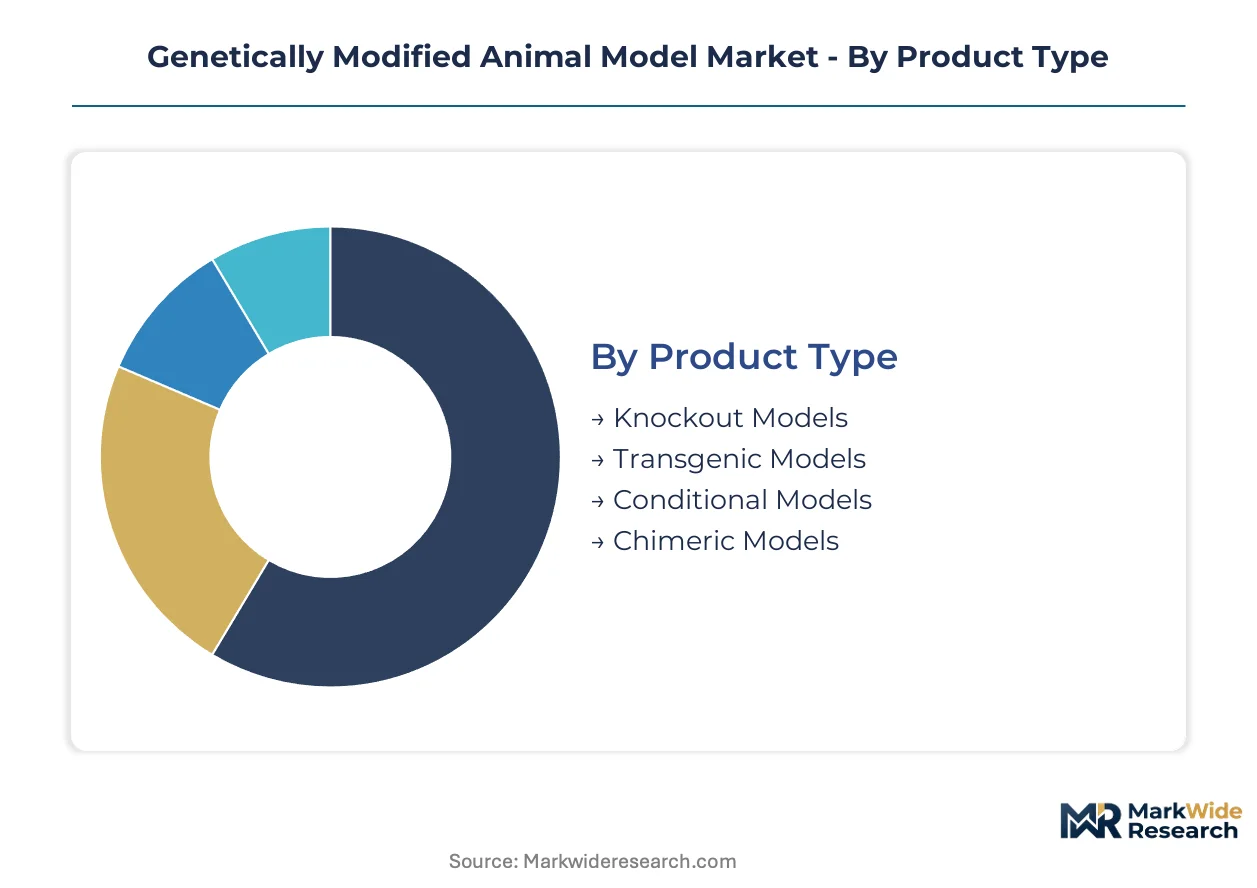
Segmentation in genetically modified animal models reveals how technical specifications, editing methodologies, and institutional procurement patterns fragment demand across distinct value tiers. Pharmaceutical sponsors prioritize validated platforms with documented genetic stability, while academic laboratories optimize for experimental flexibility over scale.
Product Type:
Use-case spectrum spans standardized gene deletion through complex tissue-specific expression systems, with each tier commanding different validation overhead and pricing multiples.
- Knockout Models:Complete gene inactivation via CRISPR-Cas9 or homologous recombination produces null alleles for loss-of-function studies. Pharmaceutical toxicology groups in the United States source these at volume for target validation, constrained by germline transmission variability in founder breeding. The dominant share belongs to Knockout Models, while Conditional Models is closing the gap fastest.
- Transgenic Models:Random or targeted insertion of foreign DNA constructs enables gain-of-function analysis and reporter gene tracking. Boston-Cambridge biotech clusters drive concentrated procurement for oncology reporter lines, though position effect variegation complicates phenotype interpretation.
- Conditional Models:Cre-lox or Flp-FRT recombination systems permit spatiotemporal gene deletion, reducing embryonic lethality in essential gene studies. Academic medical centers favor these for tissue-specific mechanistic research.
- Chimeric Models:Humanized immune system engraftment in immunodeficient mouse backgrounds supports patient-derived xenograft efficacy testing. San Diego oncology pipelines sustain premium demand despite technical complexity in hematopoietic stem cell engraftment.
Knockout models retain procurement volume leadership due to protocol standardization, while conditional systems gain share through precision medicine applications requiring temporal control.
Application:
Cost tier differentiation separates high-throughput screening contracts from bespoke mechanistic studies, with pricing multiples spanning an order of magnitude across the application hierarchy.
- Biomedical Research:Fundamental disease mechanism investigations utilizing knockout and transgenic platforms. NIH-funded academic laboratories concentrate demand in the United States, constrained by federal budget allocation cycles for model organism cores.
- Drug Discovery:Target validation and lead optimization through humanized efficacy models. Pharmaceutical sponsors in Massachusetts and California dominate procurement, with IND timeline pressure compressing model delivery windows. Drug Discovery commands the dominant revenue position, though Toxicology Testing is expanding most quickly.
- Toxicology Testing:GLP-compliant safety pharmacology studies requiring documented genetic backgrounds and barrier facility certification. FDA submission pathways mandate specific strain documentation, elevating supplier qualification barriers.
- Genetic Studies:Epistasis analysis and complex trait mapping through multi-allele crosses. Specialized academic consortia drive fragmented, low-volume demand with extended breeding timelines.
Drug discovery applications generate premium pricing through IND-linked procurement urgency, while toxicology testing exhibits steepest expansion trajectory driven by regulatory submission volume growth.
Technology:
Customer type alignment separates turnkey service procurement from in-house editing capability, with pharmaceutical sponsors outsourcing complexity while academic institutions maintain captive embryology cores.
- CRISPR-Cas9:RNA-guided nuclease editing enables rapid, multiplexed genome modification with reduced embryonic stem cell dependency. Contract research organizations in the United States and China have scaled microinjection infrastructure around this platform, though mosaicism in founder animals requires expanded screening cohorts. CRISPR-Cas9 holds the dominant technology position, while Prime editing derivatives are gaining commercial traction fastest.
- Homologous Recombination:Template-directed gene targeting in embryonic stem cells produces precise allele modifications with minimal off-target effects. Legacy pharmaceutical internal programs retain this capability for complex conditional allele construction.
- Transposon-Mediated Gene Transfer:Sleeping Beauty or PiggyBac systems facilitate large cargo insertion and stable transgene expression. Transgenic production facilities leverage these for reporter and overexpression model generation.
- ZFN:Zinc finger nuclease technology precedes CRISPR adoption but retains niche application in intellectual property-constrained jurisdictions. Limited new platform investment constrains market relevance.
CRISPR-Cas9 platforms command overwhelming technology share, while next-generation precision editing modalities are displacing legacy nuclease systems in premium applications.
End User:
Supply concentration patterns track institutional scale, with large pharmaceutical sponsors consolidating vendor relationships while fragmented academic procurement sustains mid-tier breeding facility viability.
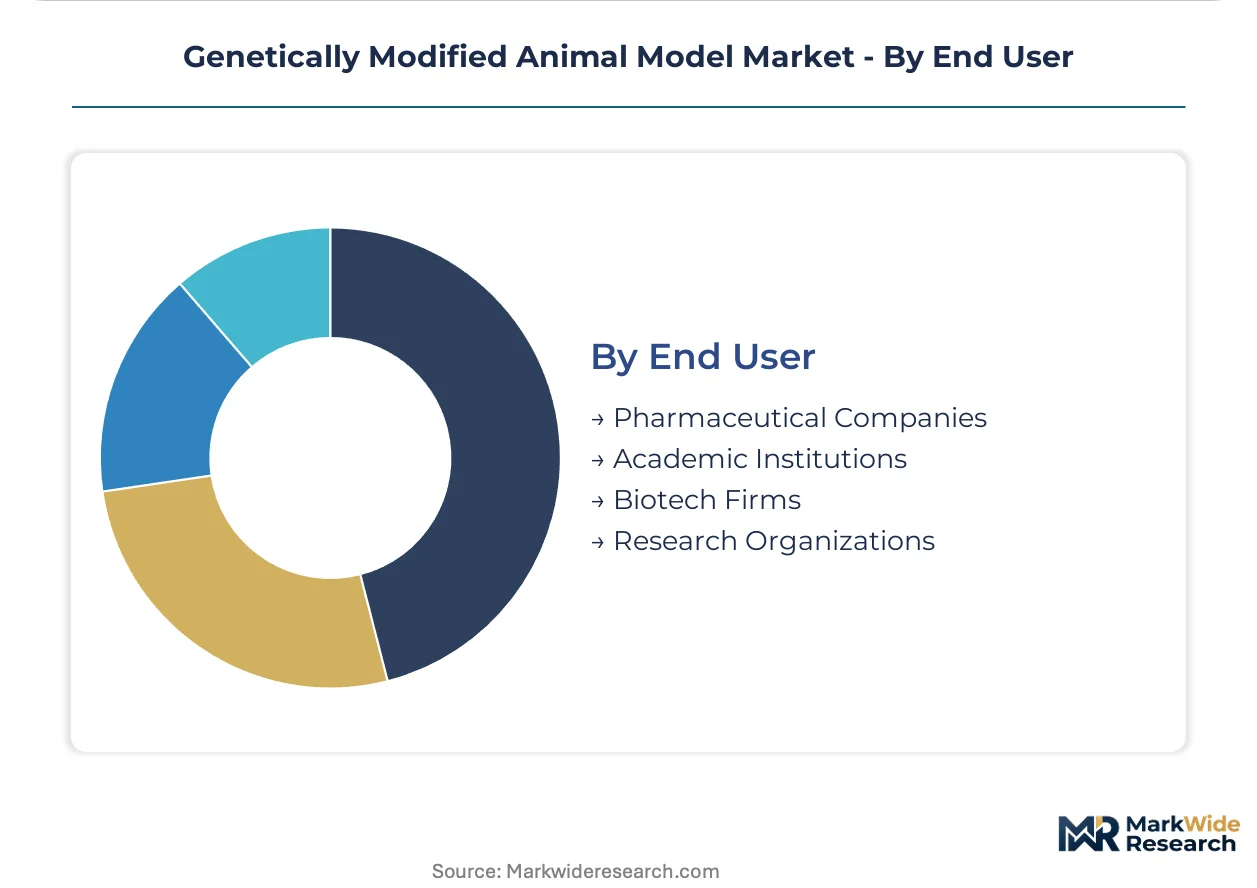
- Pharmaceutical Companies:Integrated drug development organizations requiring validated models with regulatory documentation packages. Merck, Bristol Myers Squibb, and comparable sponsors in New Jersey and Massachusetts drive concentrated demand for humanized oncology platforms, constrained by sole-source qualification timelines. Pharmaceutical Companies represent the dominant end-user segment, though Biotech Firms are scaling procurement fastest.
- Academic Institutions:University-affiliated research laboratories with captive transgenic core facilities or external service procurement. NIH funding distribution shapes geographic demand concentration across Boston, San Francisco, and San Diego research corridors.
- Biotech Firms:Venture-funded therapeutics developers with compressed IND timelines and flexible licensing requirements. Series B and C-stage companies in South San Francisco and Cambridge prioritize rapid-turnaround genome editing over captive breeding capacity.
- Research Organizations:Non-profit institutes and government laboratories with specialized disease focus areas. Jackson Laboratory and comparable entities serve dual roles as producers and consumers in the model ecosystem.
Pharmaceutical sponsors anchor volume demand through multi-year platform licensing, while biotech procurement expansion reflects pipeline maturation and investor pressure for accelerated milestone achievement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA streamlined review pathways for gene-edited animal models are compressing commercialization timelines in the United States, while China's NMPA alignment with ICH guidelines is expanding domestic toxicology study volume. EMA ethical review frameworks constrain European supply expansion, and Japan's PMDA standards shape Asia-Pacific validation requirements.
United States
Pharmaceutical companies drive expanded adoption of CRISPR-edited rodent platforms for oncology and immunology pipelines. The FDA's abbreviated pathway for intentionally altered genomic DNA in animals reduces commercialization friction for gene-edited model developers. Boston-Cambridge and San Diego biotech clusters sustain concentrated procurement with premium pricing power for barrier-certified production capacity.
China
NMPA alignment with ICH guidelines is expanding local toxicology study volume for genetically modified models. GB standards increasingly influence model validation requirements for trials supporting domestic drug approvals. Beijing-based Biocytogen Pharmaceuticals competes on humanized antibody model specialization for pharmaceutical clients.
Germany
EMA member state divergence in animal welfare authorization timelines fragments cross-border model distribution. Directive 2010/63/EU implementation guidelines are tightening severity classification thresholds for genetically modified animal procedures. Mid-scale suppliers lacking dedicated compliance architecture face disproportionate regulatory burden.
United Kingdom
Academic medical centers favor conditional models for tissue-specific mechanistic research. The country's national pharmaceutical regulator maintains alignment with EMA frameworks post-Brexit. London-Oxford-Cambridge research corridor concentrates demand for fundamental disease mechanism investigations.
Japan
PMDA standards shape toxicology validation requirements for genetically modified models supporting drug approvals. METI programs support domestic biotech pipeline maturation. Tokyo-Yokohama biotech clusters drive procurement for humanized immune system mice in immuno-oncology development.
Genetically Modified Animal Model Market Competitive Landscape
On the supply side, the industry is consolidating around integrated breeding facilities with captive genome editing, barrier housing, and pathology capabilities. Three archetypes dominate: global contract research organizations with barrier facility networks, specialized humanized model developers, and academic-derived genetic repositories. Competitive moves center on multi-year platform licensing arrangements and subscription-based model access replacing per-animal transactions.
Within the integrated service tier, Charles River Laboratories International, Inc. and The Jackson Laboratory exemplify divergent scale strategies. Biocytogen Pharmaceuticals (Beijing) Co., Ltd. occupies a position as a geography-specialized humanized model developer. Taconic Biosciences, Inc. represents the mid-tier breeding facility archetype serving pharmaceutical sponsors with validated strain documentation.
| Leading Market Players |
|---|
| Charles River Laboratories International, Inc. |
| The Jackson Laboratory |
| Taconic Biosciences, Inc. |
| genOway |
| Inotiv |
| Biocytogen Pharmaceuticals (Beijing) Co., Ltd. |
| Janvier Labs |
| Envigo RMS LLC |
| Horizon Discovery |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European barrier-certified breeding facilities is compressing margins for mid-tier suppliers while concentrating pricing power with integrated genome editing platforms in the United States and China. Utilization rates below 70% in German and UK facilities force asset-light contract breeders toward subscription licensing models, whereas Boston-Cambridge and San Diego clusters sustain premium per-animal pricing through sole-source qualification timelines.
Pricing Analysis
Certification level (FDA-grade GLP versus academic-grade phenotyping) creates the primary spread between pricing tiers, with three-tier pricing structure across premium, standard, and economy levels dominating procurement contracts. Pharmaceutical sponsors in Massachusetts and California absorb 40-60% premiums for documented genetic drift monitoring and barrier facility lineage verification, while academic laboratories optimize for experimental flexibility over regulatory documentation. Cost compression in mid-tier humanized model production is intensifying because germline transmission yield variability constrains scale economics. Biotech firms with Series C-stage pipeline uncertainty exhibit highest price sensitivity, whereas Merck-scale pharmaceutical sponsors prioritize turnaround velocity over per-unit cost.
Supply Chain Analysis
CRISPR reagent production concentrates in the United States, China, and Germany, with synthetic guide RNA and Cas9 mRNA sourcing from specialized biochemical suppliers in these geographies. Founder animal breeding draws from JAX repository genetic material, Charles River barrier facility networks, and Biocytogen's Beijing-based humanized strain production. Single-source vulnerability in germline-qualified founder colonies creates supply chain risk, as customs friction around live animal shipment disrupts just-in-time model delivery for IND-timeline studies. Distribution runs through multi-year platform licensing arrangements rather than spot procurement, with pharmaceutical sponsors consolidating vendor relationships to reduce qualification overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as CRISPR precision editing compresses model development timelines from years to months, accelerating pharmaceutical outsourcing decisions that previously favored captive embryonic stem cell programs.
For Market Incumbents: Build regulatory documentation moats through FDA Master File submissions and EMA ethical review pre-qualification to defend against emerging Chinese entrants with GB-compliant production capacity. Incumbent breeding facilities should deepen backward integration into CRISPR reagent manufacturing to secure supply continuity, while investing in prime editing service menus to capture rare disease therapeutic development contracts that demand precise point mutations without double-strand break artifacts.
For New Entrants and Emerging Players: Establish a beachhead in organoid-animal hybrid validation services, the most penetrable segment where patient-derived co-culture systems converge with humanized mouse platforms for reduced-scale immuno-oncology screening. New entrants should target Series B and C-stage biotech firms in South San Francisco and Cambridge with flexible annual licensing arrangements replacing per-animal transactions, capturing recurring revenue from clients with pipeline uncertainty and compressed IND timelines.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across European barrier facility compliance infrastructure as EMA Directive 2010/63/EU implementation tightens severity classification thresholds. Long-term viability favors integrated platforms with captive genome editing, barrier housing, and pathology capabilities over pure-play editing shops lacking animal production capacity. Acquisition target archetype: mid-tier breeding facilities with validated strain documentation seeking compliance architecture investment. The signal to watch is NMPA toxicology study volume expansion as China domestic drug development accelerates under ICH-aligned guidelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Prime Editing Service Commercialization | Enables rare disease therapeutic developers to commission precise point mutations without repair artifacts. |
| Subscription-Based Model Access Licensing | Captures recurring revenue from mid-tier biotech clients with pipeline uncertainty and compressed timelines. |
| Organoid-Animal Hybrid Platform Development | Supports next-generation immuno-oncology efficacy screening at reduced in vivo scale for pharmaceutical sponsors. |
| GB-Compliant Production Capacity Expansion | Aligns with NMPA toxicology study volume growth as China domestic drug development accelerates. |
| EMA Ethical Review Pre-Qualification | Reduces cross-border distribution friction for European pharmaceutical sponsors facing fragmented authorization timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical toxicology group directors, biotech procurement managers, academic transgenic core facility heads, contract research organization business development leads, and veterinary pathologists specializing in phenotypic characterization. Secondary validation drew from FDA guidance documents on intentionally altered genomic DNA in animals, EMA Directive 2010/63/EU implementation guidelines, NMPA ICH alignment announcements, NIH funding allocation records for model organism cores, and SEC 10-K filings from publicly traded breeding facility operators. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from pharmaceutical R&D expenditure allocation patterns.
Calibration approaches anchored volume projections to documented germline transmission rates in CRISPR-edited rodents and historical IND submission volumes across the analysis window. Segmentation dimensions modeled included product type (knockout, conditional, transgenic, chimeric), technology platform (CRISPR-Cas9, homologous recombination, prime editing derivatives), application (drug discovery, toxicology testing, biomedical research), and end-user institutional scale (pharmaceutical, biotech, academic). CAGRs were derived from slope-intercept analysis of adoption curve inflection points, with industry-specific inputs incorporating CRISPR editing precision improvement trajectories and regulatory pathway commercialization timeline compression.
Stress conditions across germline transmission yield variability, cross-border live animal shipment customs friction, and EMA member state ethical review divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued pharmaceutical outsourcing of genome editing and sustained NMPA alignment with ICH toxicology study standards. Cross-checking against pharmaceutical sponsor R&D procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Microbial Gene Editing Services Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market