
 China Gene Editing Market | 2026-2036
China Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
China Gene Editing Market Insights
Chinese biotech clusters is restructuring around CRISPR therapeutic manufacturing, with Beijing and Shanghai hubs expanding GMP-compliant plasmid and viral vector capacity. EdiGene leverages allogeneic CAR-T pipelines to anchor hematology indications. HuidaGene sustains one of China's largest proprietary guide RNA libraries. Yoltech Therapeutics specializes in base editing platforms for inherited retinal diseases.
Gene editing encompasses programmable nuclease systems—CRISPR-Cas9, TALEN, ZFN, and RNAi—that introduce site-specific DNA modifications with precision down to single-base resolution, primarily serving therapeutic development and agricultural trait engineering. CRISPR dominates technology adoption due to lower cost and multiplexing capability, while TALEN retains share in regulatory-sensitive therapeutic contexts requiring reduced off-target profiles. Gene therapy represents the fastest-expanding application segment, though biomedical research still captures the largest absolute spending pool from academic institutes and pharmaceutical sponsors.
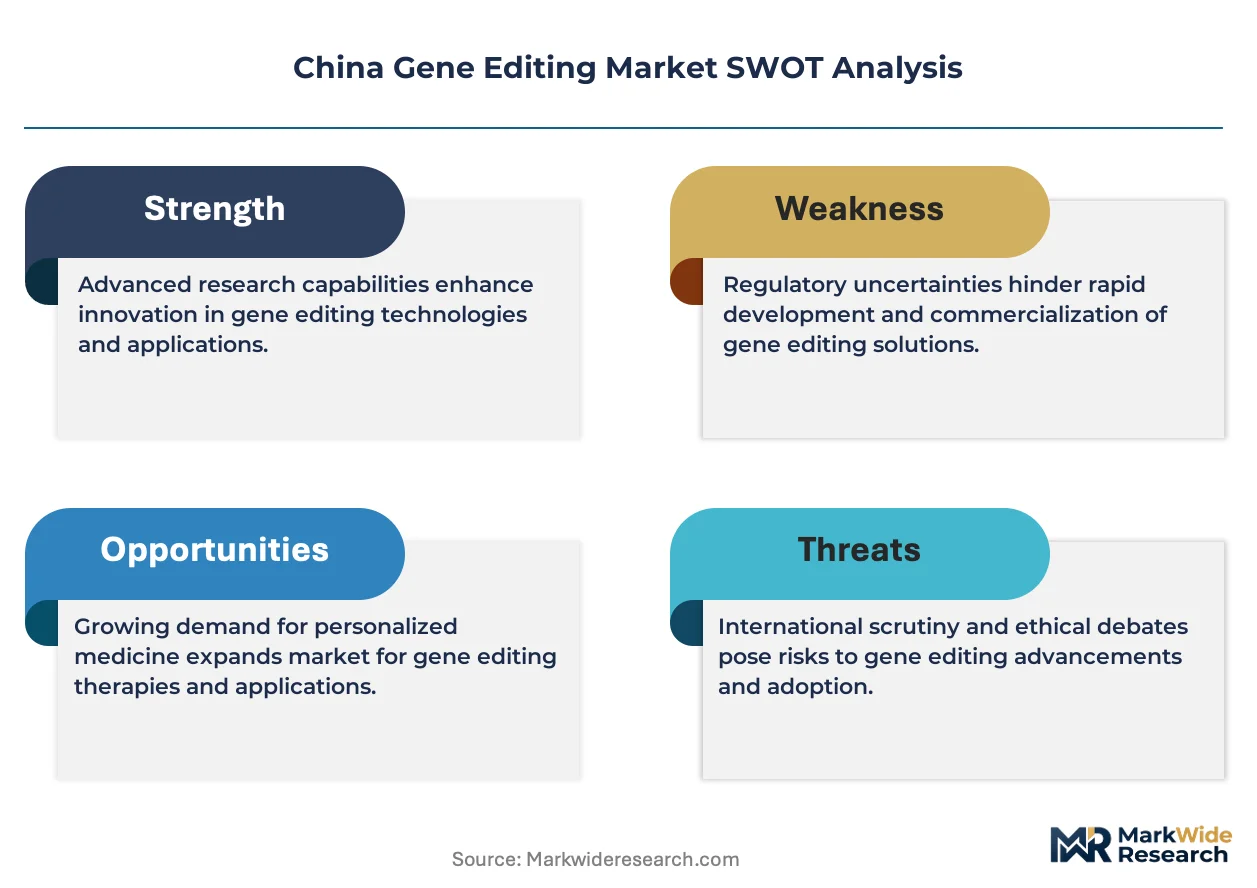
NMPA's technical guidelines for gene therapy products, MIIT's biosecurity protocols for genetic resource management, and GB standards for laboratory biosafety collectively shape clinical trial pacing and manufacturing compliance requirements in China. SAMR's oversight of gene-edited agricultural products creates parallel commercialization pathways distinct from therapeutic regulation. Stakeholders must track how NMPA's accelerated approval pathways for breakthrough therapies interact with provincial reimbursement negotiations to determine viable launch sequencing.
Market Dynamics
NMPA's accelerated approval pathways for breakthrough gene therapies are compressing clinical trial timelines from years to months, forcing contract manufacturers in Beijing and Shanghai to expand viral vector capacity ahead of confirmed demand.
Growth Catalysts
- NMPA Breakthrough Therapy Designation:The regulator's fast-track pathway for serious conditions with unmet medical needs is slashing review periods. Hematology and oncology pipelines receive priority status.
- CRISPR-Cas9 Multiplexing:Simultaneous editing of multiple genomic loci is reducing therapeutic development costs. Research institutes in Shanghai are deploying this for complex polygenic diseases.
- Rare Disease Patient Pools:China's expanded newborn screening programs are identifying larger addressable populations for inherited retinal and hematologic conditions.
Market Restraints
- Plasmid Supply Concentration:GMP-grade plasmid DNA production clusters in three coastal provinces. Any biosafety incident triggers nationwide vector manufacturing delays.
- Off-Target Liability:CRISPR's double-strand break mechanism creates chromosomal translocation risks that TALEN platforms mitigate. Therapeutic developers face higher insurance burdens.
- Reimbursement Negotiation Friction:Provincial health security bureaus lack actuarial models for one-time curative therapies. Payment structures assume chronic administration.
Strategic Opportunities
- Base Editing in Guangdong:Cytosine and adenine base editors enable precise C-to-T or A-to-G conversions without double-strand breaks. Inherited retinal disease programs in Shenzhen are piloting this.
- Allogeneic CAR-T Manufacturing:Off-the-shelf cell therapies eliminate patient-specific logistics. Beijing biotech parks are building dedicated cleanroom suites for this transition.
- SAMR Agricultural Pathway:Gene-edited crops face lower regulatory burdens than transgenic products. Trait developers can commercialize drought-resistant rice variants faster than therapeutic timelines.
Industry Challenges
- Guide RNA Design Talent Scarcity:Computational biology expertise for minimizing off-target effects concentrates in top-tier institutes. Mid-tier CROs struggle to hire qualified bioinformaticians.
- Vector Manufacturing Capex Burden:Suspension bioreactor facilities for AAV production require nine-figure RMB investments. Smaller developers outsource to CDMOs with limited capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Gene Editing Market |
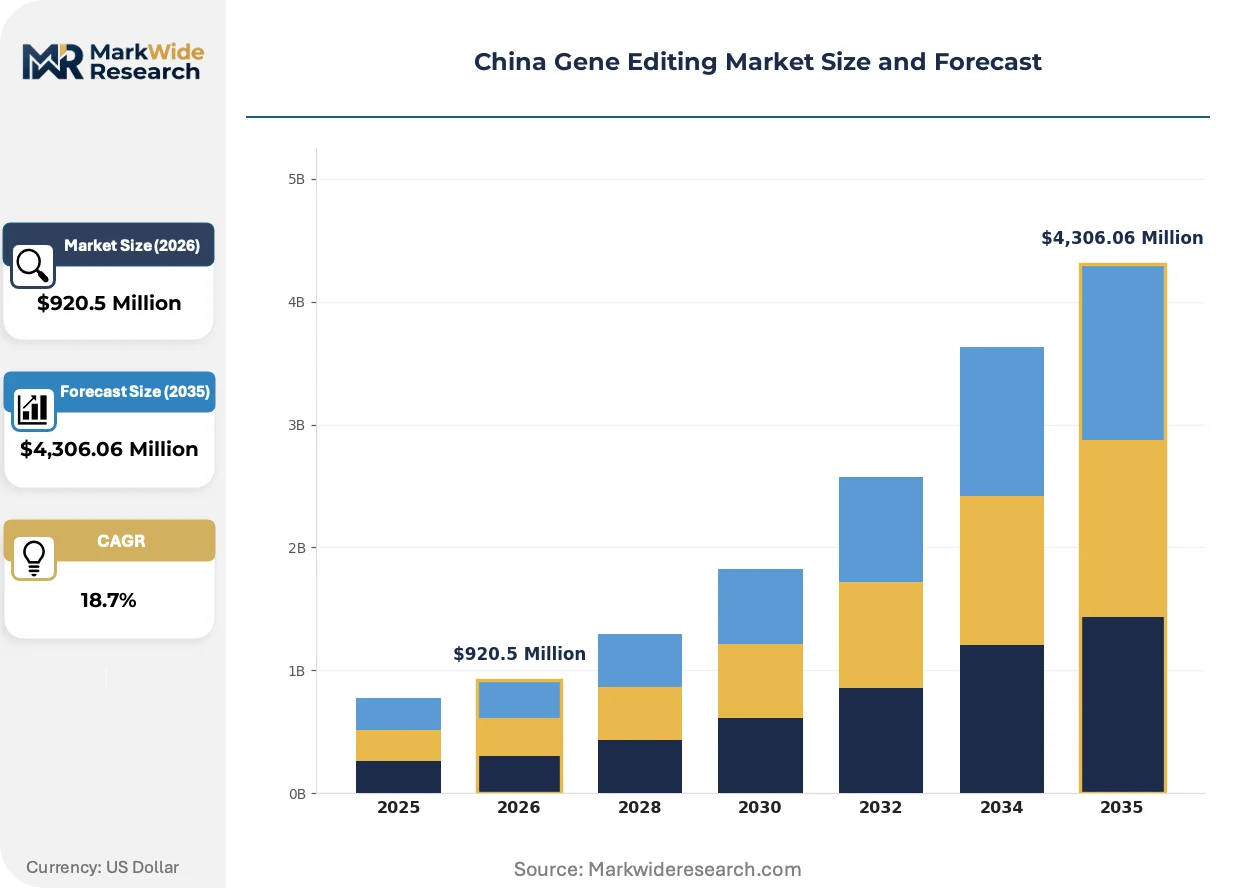
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $4,306.06 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CRISPR, TALEN, ZFN, RNAi Application: Biomedical Research, Agriculture, Gene Therapy, Industrial Biotechnology Delivery Method: Viral Vectors, Electroporation, Microinjection, Liposome-mediated End User: Academic Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | EdiGene, HuidaGene, Yoltech Therapeutics, Neurophth, GeneCradle, Shandong BellaGen Biotechnology, Wuhan HumanWell, NorthLand, Shanghai Vitalgen Biopharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Gene Editing Market Trends and Innovations
Gene editing platforms are converging with synthetic biology and AI-driven target identification, creating modular therapeutic architectures that separate disease targeting from delivery mechanism optimization.
Prime editing is absorbing the most technically demanding correction applications previously reserved for donor template-based homology-directed repair. Shanghai-based therapeutic developers are adopting prime editors for single-base substitutions in hematopoietic stem cells. The technology is absorbing market share from early CRISPR-Cas9 programs by eliminating double-strand break risks entirely.
MIIT's biosecurity protocols for human genetic resource management now mandate pre-export approval for all collaborative sequencing and editing data. Foreign pharmaceutical sponsors must establish data localization infrastructure within China before initiating multicenter trials. Beijing and Shanghai institutes are restructuring partnership agreements to comply with cross-border transfer restrictions.
Hospital procurement committees are consolidating gene therapy purchasing through provincial centralized tendering platforms. Third-party medical insurance administrators are designing single-payment models for curative interventions. Guangdong and Jiangsu provinces are piloting outcome-based reimbursement where therapeutic efficacy determines final payment amounts.
China Gene Editing Market Segmentation
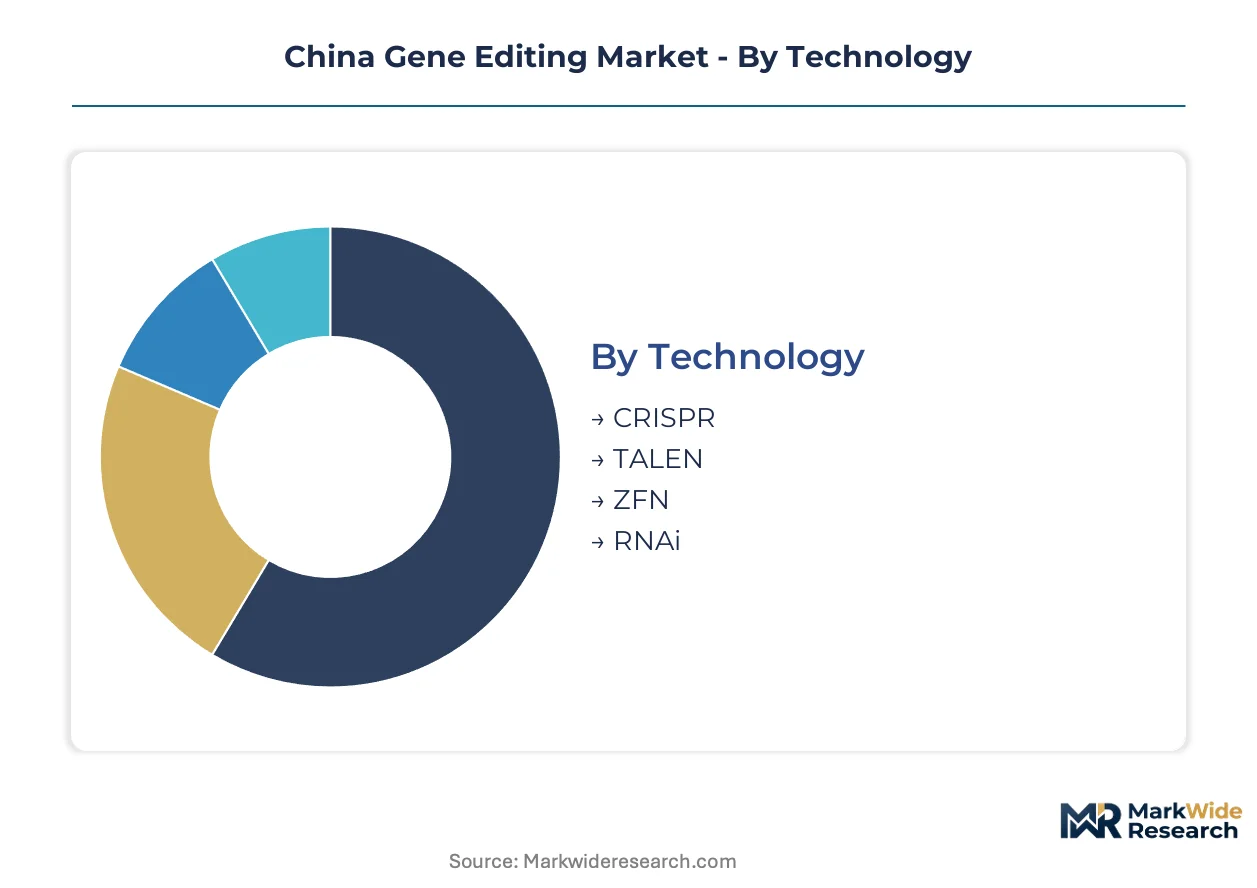
Segmentation in China's gene editing market reveals how technology platforms, delivery systems, and customer types concentrate investment and regulatory attention. Each dimension carries distinct supply chain implications for plasmid sourcing, vector manufacturing capacity, and clinical trial infrastructure.
Technology:
Supply concentration in CRISPR guide RNA synthesis has created three dominant domestic vendors serving Shanghai and Beijing therapeutic developers.
- CRISPR:Programmable nuclease systems using Cas9 and variants enable multiplexed genomic editing with reduced cost per target. Shanghai biomedical institutes deploy this for polygenic disease programs targeting oncology indications. NMPA's breakthrough therapy designations are compressing timelines for CRISPR-based hematology pipelines.
- TALEN:Transcription activator-like effector nucleases offer reduced off-target profiles through protein-DNA recognition. Beijing gene therapy developers favor TALEN for regulatory-sensitive therapeutic contexts requiring precise chromosomal integration. Higher manufacturing complexity limits vendor options.
- ZFN:Zinc finger nucleases represent earlier-generation platforms with established IP landscapes. Legacy therapeutic programs in Guangdong maintain ZFN pipelines for inherited retinal applications.
- RNAi:RNA interference enables transient gene silencing without permanent genomic modification. Agricultural trait developers leverage RNAi for pest-resistant crop varieties under SAMR's lower-burden regulatory pathway.
CRISPR absorbs the bulk of installed capacity; base editing derivatives within the CRISPR family are expanding most quickly.
Application:
Cost tier separation distinguishes capital-intensive gene therapy manufacturing from research-scale reagent consumption.
- Gene Therapy:Curative interventions using ex vivo and in vivo editing command premium pricing structures. Beijing and Shanghai biotech parks are building dedicated GMP facilities for viral vector production serving oncology and rare disease portfolios. Provincial reimbursement pilots in Guangdong and Jiangsu are testing outcome-based payment models.
- Biomedical Research:Academic and pharmaceutical-sponsored discovery programs constitute the largest absolute spending pool. Shanghai institutes drive demand for high-throughput screening platforms and proprietary guide RNA libraries.
- Agriculture:Gene-edited crop traits face streamlined SAMR approval compared to transgenic products. Drought-resistant rice variants from Hainan breeding centers are reaching commercialization faster than therapeutic timelines.
- Industrial Biotechnology:Microbial strain optimization for enzyme production and biofuel applications. Shandong fermentation facilities are adopting CRISPR-based chassis engineering.
Biomedical Research captures the largest absolute expenditure base; Gene Therapy is climbing the fastest as NMPA accelerates breakthrough designations.
Delivery Method:
Volume concentration in viral vector manufacturing has forced Beijing and Shanghai CDMOs to expand suspension bioreactor capacity ahead of confirmed pipeline demand.
- Viral Vectors:Adeno-associated virus and lentiviral systems dominate in vivo and ex vivo therapeutic delivery. AAV serotype selection determines tissue tropism for inherited retinal and hematologic programs. Three coastal provinces concentrate GMP plasmid supply feeding vector production.
- Electroporation:Physical membrane permeabilization enables non-viral delivery of ribonucleoprotein complexes. Allogeneic CAR-T developers in Beijing favor electroporation for manufacturing scalability.
- Microinjection:Precision delivery into embryos and oocytes for agricultural trait engineering. Hainan and Guangdong breeding centers maintain specialized facilities.
- Liposome-mediated:Lipid nanoparticle formulations for mRNA and sgRNA cargo. Emerging applications in base editing delivery for liver-targeted programs.
Viral Vectors absorb the bulk of manufacturing capex; Electroporation is gaining share fastest as allogeneic cell therapy scales.
End User:
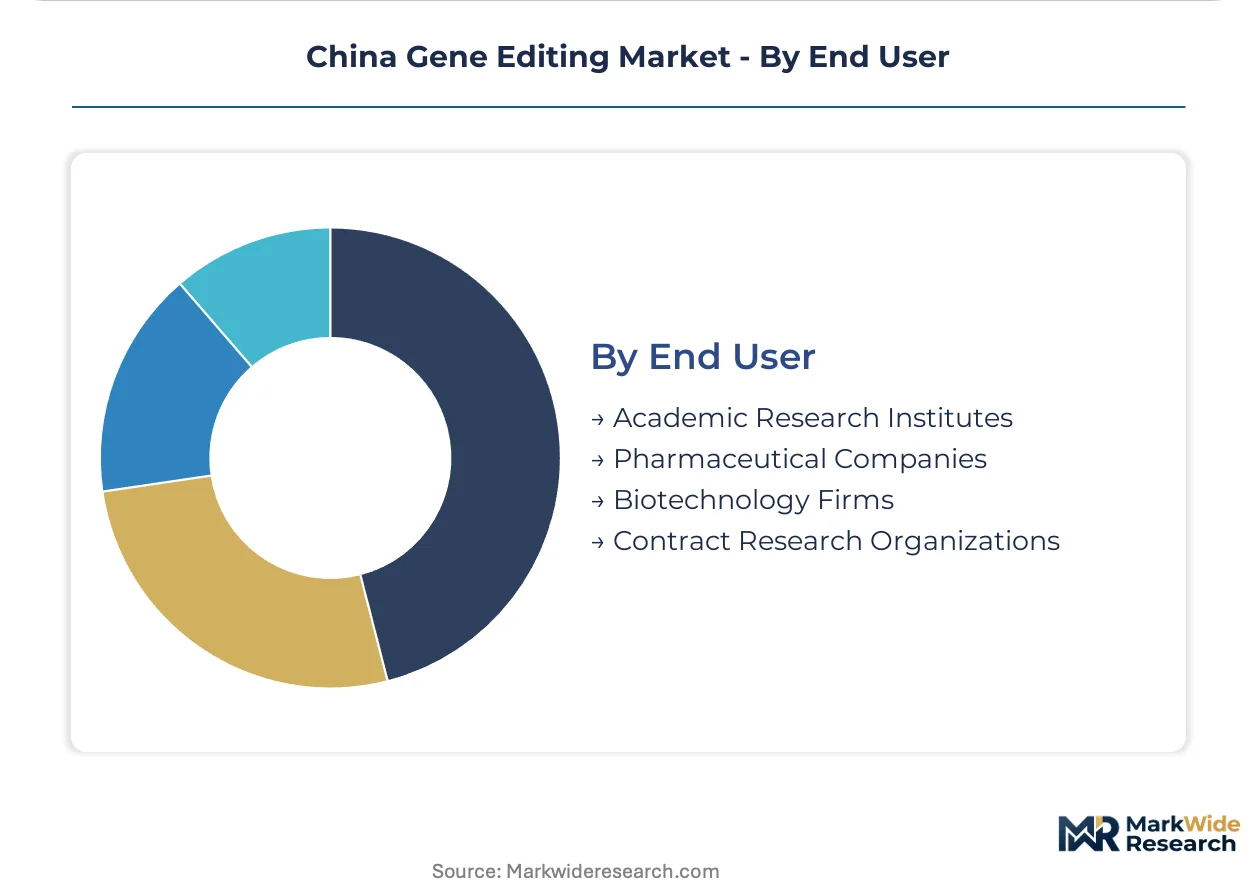
Customer type determines procurement patterns, with pharmaceutical sponsors consolidating purchasing through centralized tendering platforms while academic institutes maintain fragmented reagent sourcing.
- Pharmaceutical Companies:Sponsored therapeutic pipelines drive demand for integrated CMC development and regulatory submission support. Multinational firms must establish data localization infrastructure per MIIT biosecurity protocols before initiating multicenter trials.
- Academic Research Institutes:Discovery-focused spending from CAS and university-affiliated centers in Shanghai and Beijing. Federal funding cycles create predictable reagent demand patterns.
- Biotechnology Firms:Venture-backed developers in Suzhou and Shenzhen biotech parks. These entities outsource vector manufacturing to CDMOs with limited capacity.
- Contract Research Organizations:Mid-tier CROs in Chengdu and Wuhan struggle to hire qualified bioinformaticians for guide RNA design. Computational biology expertise concentrates in top-tier institutes.
Academic Research Institutes absorb the bulk of historical spending; Pharmaceutical Companies are expanding procurement fastest as NMPA accelerates commercial pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasmid DNA feedstock production clusters along China's eastern seaboard, anchoring the gene editing supply chain in three coastal provinces where GMP-grade manufacturing infrastructure concentrates. Beijing and Shanghai biotech parks command viral vector capacity expansion, while provincial reimbursement pilots in southern China test outcome-based payment models for curative therapies.
Beijing-Tianjin-Hebei
Hematology and oncology pipelines drive therapeutic demand in this northern cluster. NMPA's breakthrough therapy designation compresses review timelines for serious conditions with unmet medical needs. Beijing biotech parks are building dedicated cleanroom suites for allogeneic CAR-T manufacturing as off-the-shelf cell therapies scale.
Yangtze River Delta
Shanghai biomedical institutes deploy CRISPR-Cas9 multiplexing for complex polygenic disease programs targeting cancer indications. MIIT's biosecurity protocols mandate pre-export approval for collaborative sequencing and editing data, forcing foreign sponsors to establish data localization infrastructure. Suzhou biotech parks host venture-backed developers outsourcing vector manufacturing to capacity-constrained CDMOs.
Pearl River Delta
Base editing platforms for inherited retinal diseases concentrate in Shenzhen pilot programs. Guangdong province is testing outcome-based reimbursement where therapeutic efficacy determines final payment amounts. Provincial centralized tendering platforms consolidate hospital procurement committee purchasing for gene therapy products.
Sichuan-Chongqing
Chengdu-based contract research organizations struggle to hire qualified bioinformaticians for guide RNA design, as computational biology expertise concentrates in top-tier institutes. The country's national pharmaceutical regulator accelerates clinical trial approvals through evolving gene therapy guidelines. Mid-tier CROs in this western hub compete for talent against coastal salary premiums.
Shandong Peninsula
Industrial biotechnology applications for microbial strain optimization drive CRISPR-based chassis engineering adoption. Fermentation facilities adopt gene editing for enzyme production and biofuel applications. GMP plasmid supply from this northern province feeds viral vector manufacturing clusters in Beijing and Shanghai.
China Gene Editing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated editing modalities and regional manufacturing partnerships. The vendor base stratifies across three maturity levels: multinational-backed platforms with integrated CMC capabilities, domestic biotechs with proprietary guide libraries, and research-spinout ventures commercializing institutional IP. Three strategic archetypes dominate: CRISPR therapeutic developers, base editing specialists, and agricultural trait engineers. Competitive moves center on CDMO capacity pre-commitments and provincial reimbursement pilot partnerships.
Within the therapeutic development tier, EdiGene, HuidaGene, and Yoltech Therapeutics exemplify distinct platform strategies. EdiGene represents the allogeneic cell therapy archetype with hematology-focused pipelines. HuidaGene occupies a position anchored by proprietary guide RNA library scale. Yoltech Therapeutics exemplifies precision editing specialization for inherited disease applications. These Beijing and Shanghai-based entities compete for viral vector manufacturing slots at capacity-constrained CDMOs while navigating NMPA's evolving technical guidelines.
| Leading Market Players |
|---|
| EdiGene |
| HuidaGene |
| Yoltech Therapeutics |
| Neurophth |
| GeneCradle |
| Shandong BellaGen Biotechnology |
| Wuhan HumanWell |
| NorthLand |
| Shanghai Vitalgen Biopharma |
| Others |
Pricing and Supply Chain Analysis
Bioinformatician talent pools in Beijing and Shanghai command salary premiums that propagate through service pricing, widening spreads between premium-tier CRISPR therapeutic developers and mid-tier CROs competing on cost.
Pricing Analysis
Warranty and validation service bundling separates GMP-grade viral vector contracts from research-scale reagent purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales technical support depth. Cost compression in standard-tier plasmid sourcing intensifies because CDMOs compete for limited suspension bioreactor slots. Academic research institutes exhibit highest price sensitivity; pharmaceutical sponsors prioritize regulatory submission support over unit cost.
Supply Chain Analysis
Logistics costs for temperature-controlled AAV shipment from Shandong fermentation facilities to Beijing and Shanghai biotech parks add 15-20% to landed vector costs. GMP plasmid DNA production draws from Shandong, Jiangsu, and Zhejiang coastal provinces. Critical inputs include Cas9 mRNA, synthetic guide RNA, and GMP-grade plasmid backbones. Single-source vulnerability concentrates in AAV serotype-specific packaging cell lines. Distribution runs through provincial centralized tendering platforms consolidating hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral vector manufacturing capacity constraints prop pricing power for GMP-compliant CDMOs, insulating premium-tier service providers from cost-based competition.
For Market Incumbents: Anticipate prime editing platforms displacing early CRISPR-Cas9 programs by eliminating double-strand break liabilities. Defensive consolidation should prioritize backward integration into proprietary guide RNA libraries to lock in HuidaGene-scale content advantages. Capacity addition in Suzhou biotech parks addresses emerging allogeneic CAR-T demand before foreign entrants establish data localization infrastructure per MIIT protocols.
For New Entrants and Emerging Players: Contract research organizations in Chengdu and Wuhan represent the most penetrable channel partner type for computational biology outsourcing partnerships. White-space targets include base editing delivery for liver-targeted programs and agricultural trait engineering under SAMR's streamlined pathway. Go-to-market positioning should emphasize outcome-based reimbursement pilot participation in Guangdong and Jiangsu provinces.
For Investors and Strategic Acquirers: Re-rating potential sits with base editing specialists given NMPA breakthrough therapy designation acceleration for inherited retinal disease programs. Long-term viability favors platforms with integrated CMC capabilities spanning viral vector and electroporation manufacturing modalities. Signal to watch: provincial health security bureau actuarial model adoption for one-time curative therapy payment structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Suspension bioreactor expansion in Beijing biotech parks secures AAV capacity for hematology pipelines. |
| Regulatory Approval Pathway | NMPA breakthrough therapy designation compresses review timelines for serious unmet medical needs. |
| Backward Integration | In-house plasmid production mitigates biosafety incident risks concentrated in three coastal provinces. |
| Strategic Partnership | CDMO capacity pre-commitments lock in viral vector slots ahead of confirmed pipeline demand. |
| Pipeline Diversification | Prime editing adoption eliminates double-strand break risks in hematopoietic stem cell programs. |
Research Methodology
Document review covered NMPA technical guidelines, MIIT biosecurity protocols, and SAMR agricultural product standards, complemented by interviews with gene therapy development executives, regulatory affairs leads, CDMO operations managers, and hospital procurement committee members. Secondary validation drew from ClinicalTrials.gov filings, patent databases, and provincial health security bureau tendering records. Bottom-up therapeutic pipeline enumeration and top-down market sizing triangulated volume estimates.
Segment-level outputs across technology platform, delivery method, application, and end-user dimensions were generated through the projection horizon. CAGRs were derived from patent filing trajectories, clinical trial initiation rates, and capacity expansion announcements. Industry-specific inputs included NMPA breakthrough therapy designation velocity and provincial reimbursement pilot adoption curves.
Several conditions sit outside the modeled scope, including unannounced regulatory guideline revisions, biosafety incidents disrupting plasmid supply, and foreign sponsor data localization compliance delays. Forecasts reflect documented assumptions about NMPA review timeline compression and CDMO capacity buildout schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
CRISPR Gene Editing Market
Gene Editing & CRISPR
France Gene Editing Market