
 Cloning and Mutagenesis Market | 2026-2036
Cloning and Mutagenesis Market Size, Share, and Industry Trends Forecast 2026-2036
Cloning and Mutagenesis Market Analysis
Modular kit configurations is broadening buyer choice across the Cloning and Mutagenesis Market. Thermo Fisher Scientific leverages its end-to-end reagent portfolio to anchor large pharmaceutical accounts. Agilent Technologies differentiates through specialized vector design services for agricultural biotechnology clients. Takara Bio competes on manufacturing scale in enzyme and reagent production for Asian research institutes.
Cloning and mutagenesis encompasses the directed replication and deliberate alteration of DNA sequences using site-specific nucleases, polymerases, and ligase enzymes operating at precise temperature-cycling parameters, primarily to engineer organisms or validate gene function for therapeutic and agricultural outcomes. Kits and reagents command the largest revenue share due to recurring consumable demand across high-throughput workflows. CRISPR technology leads technology adoption with the fastest expansion trajectory, while gene therapy applications concentrate margin pools through premium pricing tied to clinical-grade validation standards.
FDA oversight of gene therapy products and NIH guidelines on recombinant DNA research shape product development pathways and facility certification requirements in the United States. EMA's ATMP framework and REACH chemical safety standards govern market access across European member states. Stakeholders must monitor evolving regulatory divergence between jurisdictions to align manufacturing investments with compliant distribution channels.

Market Dynamics
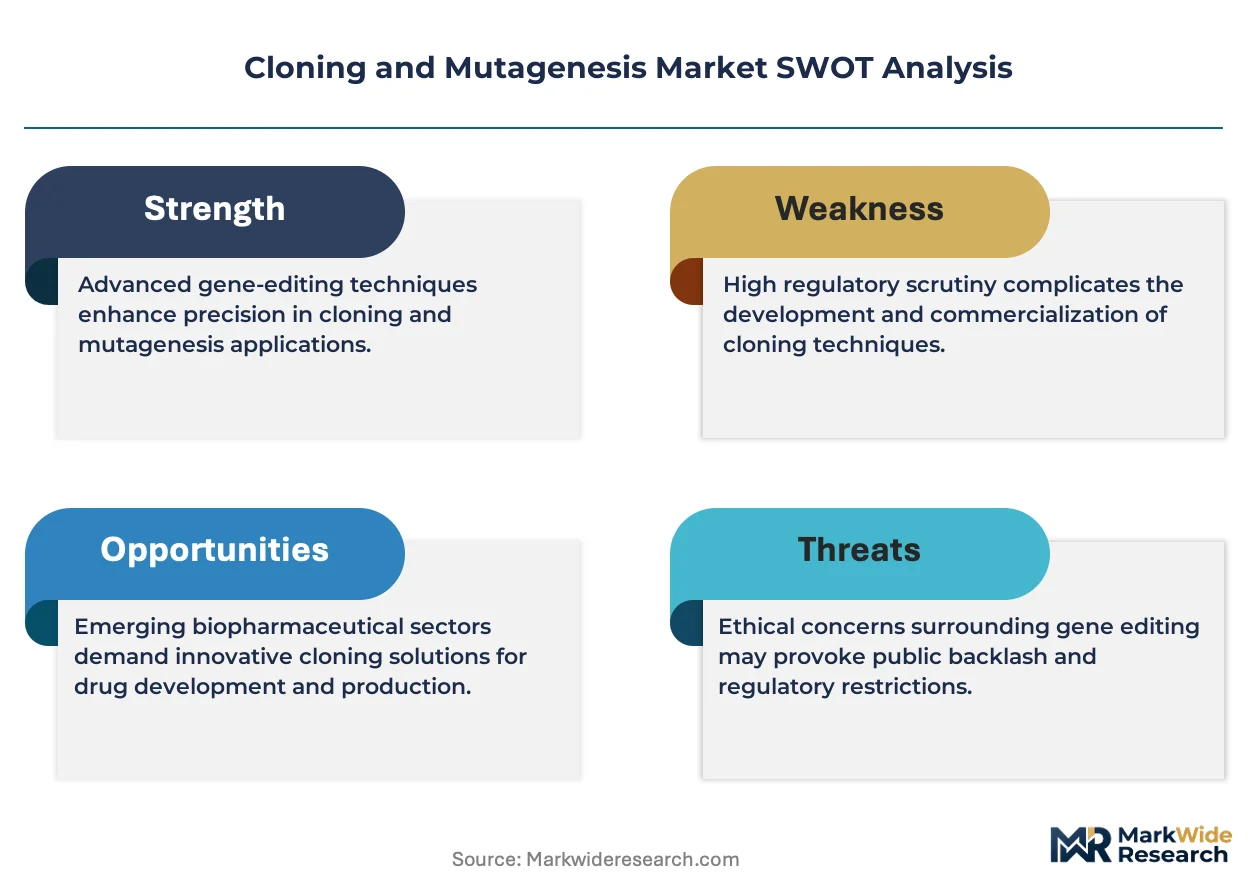
CRISPR technology maturation is compressing development timelines and forcing kit suppliers to reconfigure reagent portfolios around programmable nuclease workflows rather than legacy restriction enzyme systems.
Growth Catalysts
- Gene therapy pipeline expansion:Pharmaceutical developers are scaling viral vector manufacturing capacity, driving recurring demand for high-fidelity cloning reagents and sequence verification services.
- FDA gene editing guidance:The agency's 2024 recommendations on IND-enabling studies for genome-editing products have clarified validation requirements, accelerating sponsor investment in compliant mutagenesis workflows.
- NIH funding intensity:The National Institutes of Health has sustained recombinant DNA research allocations, concentrating grant-supported demand in Boston and San Francisco biotech clusters.
Market Restraints
- Specialized enzyme input costs:High-purity polymerases and site-specific nucleases require fermentation-grade manufacturing capacity concentrated among limited contract suppliers.
- European regulatory friction:EMA's ATMP framework imposes extended certification timelines for clinical-grade reagents, delaying market entry for novel kit configurations.
- Technical limitation in multiplex editing:Off-target effects in complex genomic loci constrain application scope for agricultural trait stacking programs.
Strategic Opportunities
- Underpenetrated cell therapy segment:Allogeneic CAR-T developers in South Korea and Japan require scalable mutagenesis platforms for donor cell engineering.
- Regulatory tailwind from EU Green Deal:Agricultural biotechnology incentives in Germany and France are accelerating CRISPR-based crop trait development.
- Technology convergence of AI and protein engineering:Machine learning-guided nuclease design is reducing optimization cycles for novel genome-editing tools.
Industry Challenges
- Specialized technician scarcity:CRISPR guide RNA design and high-complexity vector assembly require molecular biology expertise that outpaces training program output.
- GMP facility certification timelines:Clinical-grade reagent production demands ISO 13485 and FDA facility inspections that extend 18-24 months.
- IP licensing complexity:Broad Institute and University of California patent estates create royalty stacking burdens for commercial kit developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloning and Mutagenesis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmids, Vectors, Reagents, Kits Technology: CRISPR, RNA Interference, Transposon, ZFN Application: Gene Therapy, Agricultural Biotechnology, Functional Genomics, Drug Development End User: Academic Research, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Takara Bio, Merck KGaA, Bio-Rad Laboratories, New England Biolabs, Qiagen N.V., GenScript, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloning and Mutagenesis Market Emerging Trajectories
Workflow automation and artificial intelligence are restructuring how research institutions and pharmaceutical developers design, execute, and validate genetic modification experiments at scale.
CRISPR-Cas12 and Cas13 systems are modularizing the genome-editing toolkit beyond the original Cas9 architecture. Agricultural biotechnology developers in the Netherlands and plant science institutes in Australia are adopting these variants for multiplexed trait engineering. The technology is modularizing supplier revenue models from single-product sales toward configurable platform licensing.
EMA's 2023 revision to the ATMP classification guideline has redefined which gene-editing products trigger centralized marketing authorization procedures. Manufacturers of clinical-grade mutagenesis reagents must now submit manufacturing process descriptions earlier in development. European contract research organizations are responding by building dedicated ATMP-compliant vector production suites.
Consolidated procurement through group purchasing organizations is displacing direct kit sales to individual principal investigators. Large academic medical centers in Texas and North Carolina are negotiating enterprise reagent agreements that bundle cloning, mutagenesis, and sequencing workflows. This pattern is most visible in United States research institutions with centralized core facility budgets exceeding $50 million annually.
Cloning and Mutagenesis Market Segmentation
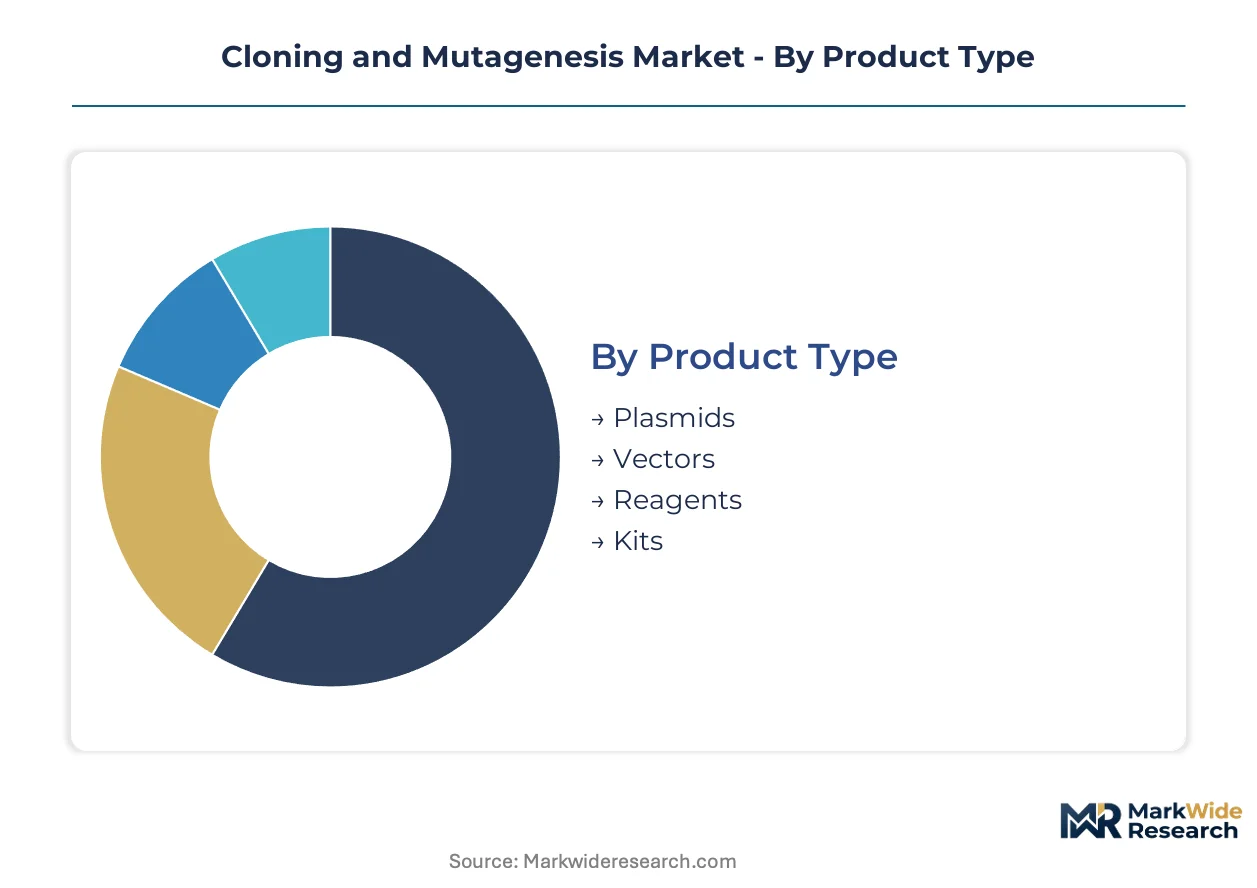
Segmentation in cloning and mutagenesis reflects how technology maturity, regulatory validation requirements, and end-use economics fragment purchasing behavior across reagent formats, editing platforms, and customer workflows.
Product Type:
Kit configurations dominate procurement patterns as laboratories consolidate vendor relationships around validated workflow bundles rather than discrete reagent sourcing.
- Kits:Pre-configured reagent combinations with protocol documentation reduce experimental variability for high-throughput screening operations. Pharmaceutical developers in Boston and San Francisco biotech clusters prioritize GMP-compliant kit formats for IND-enabling studies.
- Reagents:Individual enzyme and buffer sales persist among academic core facilities with established protocol libraries. NIH-funded institutions in Maryland and Massachusetts sustain demand for polymerases, ligases, and competent cells through centralized procurement.
- Vectors:Viral and non-viral delivery vehicles for therapeutic gene transfer require specialized manufacturing under FDA gene therapy guidance.
- Plasmids:Circular DNA constructs for bacterial propagation and transient expression remain foundational for molecular biology training programs.
Kits lead on scale; reagents lead on momentum as modular procurement displaces bundled purchasing in budget-constrained research environments.
Technology:
Programmable nuclease architectures are displacing legacy enzyme systems as CRISPR maturation compresses design-to-experiment timelines.
- CRISPR:Cas9, Cas12, and Cas13 systems enable targeted double-strand breaks with RNA-programmable specificity. Agricultural biotechnology developers in the Netherlands and plant science institutes in Australia adopt Cas12 variants for multiplexed trait engineering.
- ZFN:Zinc finger nucleases retain utility in therapeutic contexts requiring smaller protein payloads than CRISPR complexes. ZFN-based HIV therapeutics from Sangamo Therapeutics demonstrate clinical validation for genome editing in human trials.
- Transposon:Sleeping Beauty and piggyBac systems integrate large DNA cargoes without double-strand break repair dependencies.
- RNA Interference:Short hairpin and small interfering RNA constructs suppress gene expression without permanent genomic modification.
CRISPR commands installed base; ZFN retains defensible niches in payload-constrained delivery applications.
Application:
Clinical-grade validation requirements create pricing stratification between therapeutic and research-use-only segments.
- Gene Therapy:Viral vector manufacturing for in vivo and ex vivo treatments demands sequence-verified cloning reagents under FDA oversight. Allogeneic CAR-T developers in South Korea and Japan require scalable mutagenesis platforms for donor cell engineering.
- Drug Development:Target validation and lead optimization workflows consume high-fidelity mutagenesis reagents for mechanism-of-action studies. Large pharmaceutical accounts anchor volume through enterprise reagent agreements.
- Agricultural Biotechnology:CRISPR-based crop trait development accelerates under EU Green Deal incentives in Germany and France.
- Functional Genomics:Gene knockout and activation libraries support systematic pathway mapping in academic research settings.
Gene Therapy concentrates margin pools; Agricultural Biotechnology expands most quickly as regulatory frameworks clarify for gene-edited crops.
End User:
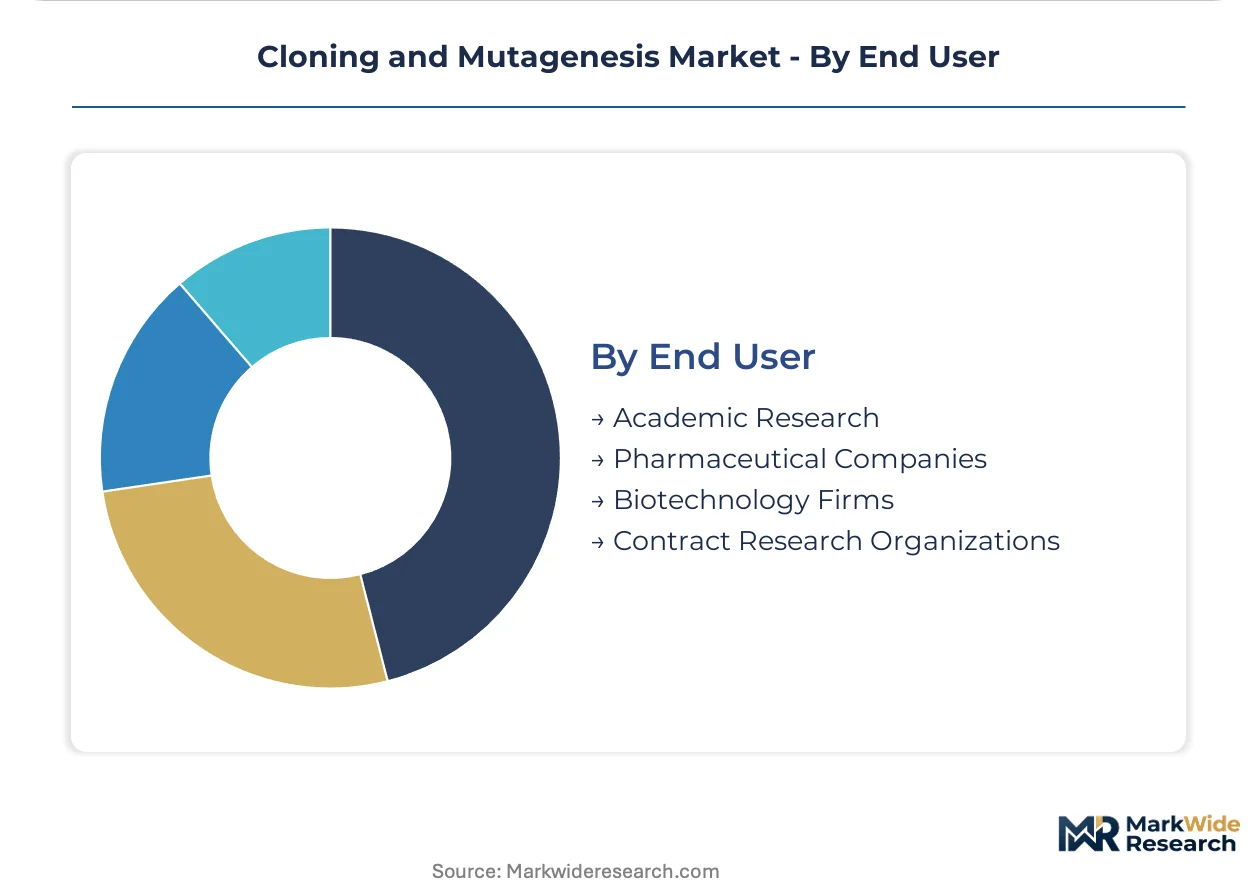
Procurement centralization through group purchasing organizations is restructuring how reagent suppliers engage customer segments.
- Pharmaceutical Companies:Gene therapy pipeline expansion drives recurring demand for clinical-grade reagents and vector production services. Enterprise agreements with Thermo Fisher Scientific and Agilent Technologies bundle cloning, mutagenesis, and sequencing workflows.
- Academic Research:NIH funding intensity concentrates grant-supported demand in Boston and San Francisco biotech clusters. Core facility budgets exceeding $50 million annually enable consolidated procurement negotiations.
- Biotechnology Firms:Venture-backed developers prioritize speed-to-data over cost optimization in reagent selection.
- Contract Research Organizations:ATMP-compliant vector production suites in European contract research organizations respond to EMA classification guideline revisions.
Pharmaceutical Companies lead on contract value; Academic Research leads on transaction volume through grant-funded principal investigator demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant DNA research originated in United States academic laboratories during the 1970s, establishing institutional frameworks that now concentrate commercial demand in clustered biotech hubs. NIH funding mechanisms and FDA regulatory pathways have since anchored global investment gravity for cloning and mutagenesis technologies.
United States
Pharmaceutical gene therapy pipelines and NIH recombinant DNA research allocations drive sustained kit demand. FDA gene editing guidance issued in 2024 clarified IND-enabling study requirements for genome-editing products. Boston and San Francisco biotech clusters concentrate venture-backed developers scaling viral vector manufacturing capacity.
Germany
Agricultural biotechnology incentives under the EU Green Deal accelerate CRISPR-based crop trait development programs. EMA's ATMP framework governs clinical-grade reagent certification timelines for gene therapy applications. Heidelberg and Munich research institutes anchor demand for high-fidelity mutagenesis workflows in academic settings.
China
NMPA oversight of gene therapy products and expanding domestic pharmaceutical R&D budgets stimulate reagent procurement. National biosecurity regulations shape import pathways for specialized enzymes and competent cells. Shanghai and Beijing biotech parks host contract research organizations building CRISPR service capabilities.
Japan
PMDA guidelines on regenerative medicine products create compliance requirements for clinical-grade cloning reagents. METI funding for cellular agriculture research extends mutagenesis applications beyond therapeutic contexts. Osaka and Tokyo academic medical centers sustain demand for viral vector production suites.
United Kingdom
MHRA post-Brexit regulatory autonomy enables differentiated approval pathways for gene-editing therapeutics. UK Research and Innovation funding concentrates functional genomics research in Cambridge and Oxford clusters. London-based contract manufacturers invest in ATMP-compliant vector production infrastructure.
Cloning and Mutagenesis Market Vendor Landscape
The competitive structure tilts toward diversified life science conglomerates with end-to-end reagent portfolios. Thermo Fisher Scientific and Merck KGaA anchor large pharmaceutical accounts through bundled workflow agreements. Three archetypes dominate: integrated platform suppliers, specialized enzyme manufacturers, and regional service providers. Capacity expansion in GMP-grade reagent production and strategic technology licensing for CRISPR patent estates constitute the primary competitive moves.
Among integrated platform suppliers, Thermo Fisher Scientific represents the archetype of end-to-end workflow consolidation. Agilent Technologies occupies a position within specialized analytical and design service tiers. Takara Bio exemplifies manufacturing-scale competitiveness in enzyme production for Asian research markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Takara Bio |
| Merck KGaA |
| Bio-Rad Laboratories |
| New England Biolabs |
| Qiagen N.V. |
| GenScript |
| Illumina |
| Others |
Supply Flow & Price Mechanics
Clinical-grade certification tiers bifurcate the Cloning and Mutagenesis Market into premium GMP-compliant reagents and research-use-only consumables, with FDA and EMA validation requirements driving both pricing premiums and supply chain specialization around audited manufacturing facilities. This divergence concentrates margin capture among enzyme manufacturers with captive fermentation capacity while forcing budget-constrained academic buyers toward modular kit configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs reagent procurement, with GMP-grade polymerases commanding substantial premiums over research-grade equivalents due to ISO 13485 certification and FDA facility inspection requirements. Price differentiation rests on validation documentation depth and endotoxin testing rigor rather than raw enzyme activity alone. Cost compression in the standard tier intensifies as group purchasing organizations consolidate academic procurement in the United States. Biotechnology firms with venture funding exhibit lowest price sensitivity; NIH-funded core facilities face greatest budget pressure.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive reagents remain minimal given single-use consumable formats, though vector production suites in contract research organizations increasingly handle client-specific plasmid returns for modification cycles. Manufacturing concentrates in the United States, Germany, and Japan, with high-purity polymerases drawing from fermentation-grade capacity anchored in these jurisdictions. Supply chain risk centers on single-source dependency for site-specific nucleases produced through proprietary strain development. Distribution runs through direct sales forces for pharmaceutical accounts and authorized distributors for academic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloning and Mutagenesis Market functions as a geographic-arbitrage opportunity where EMA's extended ATMP certification timelines in Europe contrast with FDA's clarified 2024 gene editing guidance, creating cost and speed differentials for reagent suppliers willing to navigate regulatory divergence.
For Market Incumbents: Deepen backward integration into fermentation-grade enzyme production to defend margin position against emerging Asian manufacturers scaling competent cell output. Prioritize GMP facility certification investments in the United States to capture pharmaceutical gene therapy pipeline expansion. Lock in exclusive licensing terms with Broad Institute and University of California patent estates before royalty stacking intensifies. For New Entrants and Emerging Players: E-commerce direct-to-laboratory platforms offer the lowest-friction route into budget-constrained academic segments bypassing established distributor relationships. Target agricultural biotechnology developers in the Netherlands and Australia with Cas12 variant kits for multiplexed crop trait engineering. Lead with transparent pricing and rapid guide RNA design turnaround to differentiate from incumbent bundled workflows. For Investors and Strategic Acquirers: Consolidation pressure builds where CRISPR patent licensing complexity creates insurmountable royalty burdens for standalone kit developers lacking platform breadth. Long-term viability favors integrated suppliers with end-to-end reagent portfolios spanning cloning, mutagenesis, and downstream sequencing validation. Monitor FDA gene therapy approval velocity and corresponding viral vector manufacturing capacity announcements as inflection indicators for clinical-grade reagent demand.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Certification | FDA inspections for clinical-grade reagent production unlock pharmaceutical gene therapy accounts. |
| CRISPR Patent Licensing Agreement | Access to Broad Institute and UC estates reduces royalty stacking for commercial kit portfolios. |
| Workflow Automation Partnership | Integration with liquid handling platforms anchors high-throughput screening operations in Boston clusters. |
| Regional Manufacturing Scale-Up | Captive fermentation capacity in Germany shortens EMA ATMP-compliant reagent delivery timelines. |
| Agricultural Biotechnology Service Launch | EU Green Deal incentives in France accelerate CRISPR-based crop trait development programs. |
Methodological Framework
Multiple input streams — executive interviews with gene therapy developers, regulatory affairs specialists at FDA and EMA, and procurement managers at NIH-funded core facilities — were reconciled against secondary validation from FDA guidance documents, EMA ATMP classification guidelines, ClinicalTrials.gov gene therapy entries, and SEC filings from listed life science suppliers. Bottom-up demand modeling across kit configurations, reagent categories, and vector formats was triangulated with top-down market sizing from pharmaceutical R&D expenditure patterns.
Data-stream reconciliation produced volume and value outputs across the projection horizon through segmented modeling by product type, technology platform, application area, and end-user archetype. CAGRs were derived from fitted growth curves anchored to NIH funding trajectories, gene therapy pipeline expansion rates, and CRISPR technology adoption curves. Industry-specific forecast inputs included viral vector manufacturing capacity buildouts and EMA regulatory timeline revisions.
The model assumes a particular technology adoption path; alternative pathways for base-editing or prime-editing systems would alter the outlook for Cas9-dependent reagent demand. Forecasts reflect assumptions around sustained NIH recombinant DNA allocations and FDA gene therapy approval velocity. Practitioners should monitor EMA ATMP framework evolution and CRISPR patent litigation outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
CRISPR Gene Editing Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market