
 Asia-Pacific Food Colorants Market | 2026-2036
Asia-Pacific Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Colorants Market Outlook
Premium natural-grade certification is redrawing competitive boundaries across the Asia-Pacific food colorants landscape. Givaudan SA leverages its integrated botanical extraction network to supply carmine-free formulations for dairy applications. Sensient Technologies Corporation anchors its position through proprietary microencapsulation technology that stabilizes beet-derived pigments in heat-processed beverages. Roha Dyechem competes on cost-optimized synthetic blends while building backward integration into turmeric and paprika farming clusters in southern India.
Food colorants comprise chromatic additives—natural extracts, synthetic azo compounds, mineral-based pigments, and nature-identical molecules—delivered in liquid, powder, gel, or paste matrices to achieve visual uniformity, shelf appeal, and brand recognition in processed foods. Natural colorants, particularly anthocyanin and curcumin variants, command expanding volume share as beverage manufacturers reformulate to meet clean-label requirements across China and Southeast Asia. Synthetic colorants retain structural dominance in bakery and snack segments where thermal stability and cost predictability outweigh label transparency concerns, though margin pools are migrating toward certified organic liquid concentrates for dairy applications.
FSSAI labeling mandates in India, China's SAMR enforcement of GB standards for natural food additives, and Japan's positive list system under the Ministry of Health, Labour and Welfare collectively elevate compliance costs while accelerating substitution toward plant-derived alternatives. The EU Green Deal's extraterritorial influence on ASEAN export-oriented processors further tightens permissible synthetic dye thresholds for cross-border trade. Stakeholders must monitor regulatory divergence between national permissible limits and harmonized Codex Alimentarius frameworks to anticipate reformulation cycles and raw material sourcing pivots.
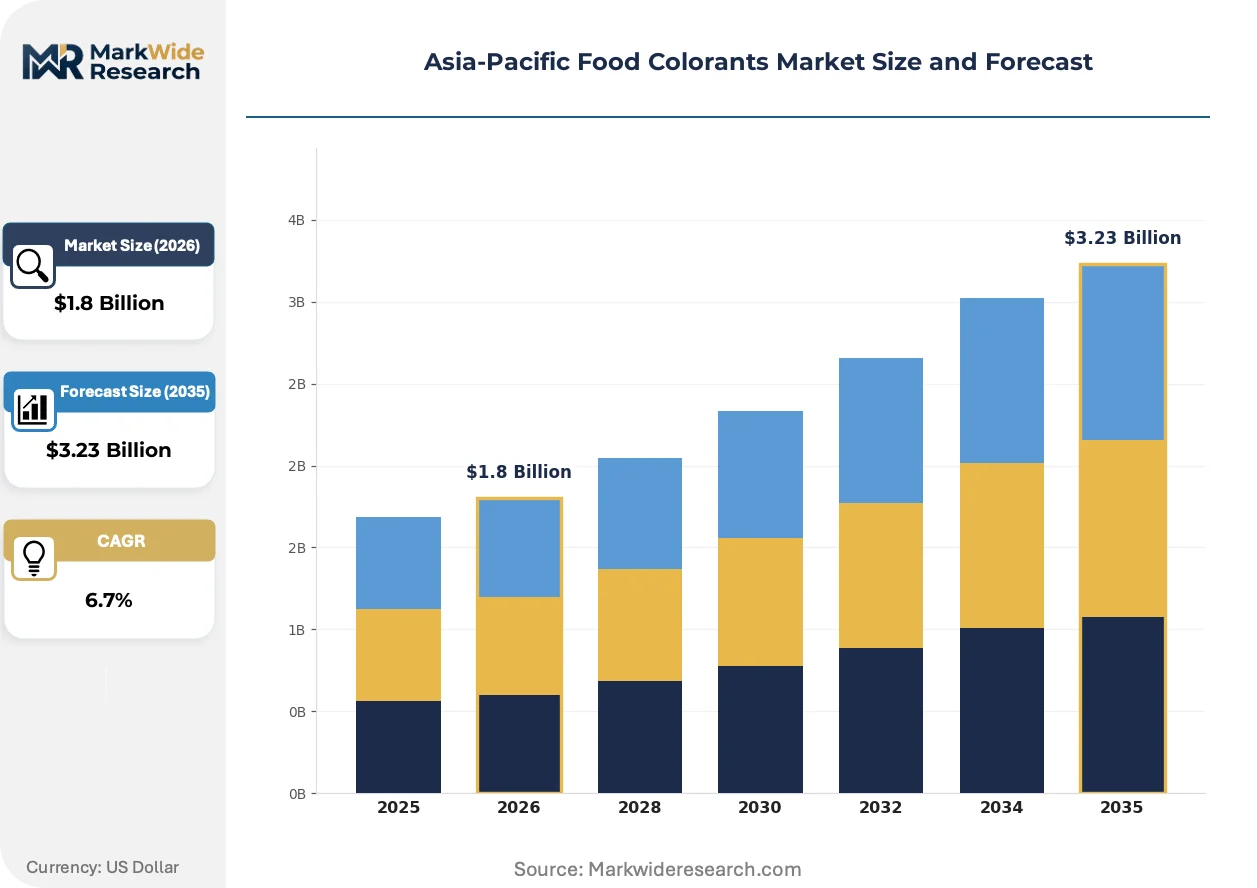
Market Dynamics
Clean-label reformulation mandates across China, India, and Southeast Asia are compressing synthetic azo dye procurement while expanding backward integration into turmeric and anthocyanin farming clusters.
Growth Catalysts
- China's GB standards:SAMR enforcement of natural additive classifications is forcing beverage manufacturers to reformulate with plant-derived pigments.
- Halal certification expansion:Indonesia's confectionery sector is absorbing certified natural colorants at accelerating volume to meet export compliance.
- Microencapsulation advances:Heat-stable beet and curcumin formulations are unlocking dairy applications previously blocked by thermal degradation.
Market Restraints
- Input cost volatility:Climate-sensitive harvests of paprika and turmeric in southern India create raw material price instability.
- Supply concentration risk:Carmine extraction depends on cochineal farming clusters concentrated in Peru and the Canary Islands.
- Regulatory friction:Divergence between FSSAI labeling mandates and Codex Alimentarius permissible limits complicates cross-border formulation.
Strategic Opportunities
- Vietnam's underpenetrated processing sector:Beverage contract manufacturers lack certified natural colorant suppliers, creating first-mover whitespace.
- EU Green Deal tailwind:Extraterritorial compliance requirements for ASEAN exporters are accelerating organic certification adoption.
- E-commerce channel emergence:Direct procurement platforms are disintermediating traditional distributor networks for mid-scale food processors.
Industry Challenges
- Certification timeline compression:FSSAI and SAMR parallel approval tracks demand simultaneous documentation in multiple jurisdictions.
- Capex intensity for extraction infrastructure:Supercritical CO2 and ethanol extraction systems require significant capital deployment for GMP compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Colorants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Inorganic Application: Beverages, Dairy Products, Bakery, Snacks Form: Liquid, Powder, Gel, Paste End User: Food Manufacturers, Restaurants, Retailers, Catering |
| Companies Covered | Givaudan SA, Archer Daniels Midland Company, Sensient Technologies Corporation, Roha Dyechem, Koninklijke DSM N.V., Döhler, Chr. Hansen Holding A/S, Synthite Industries, Kalsec Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Colorants Market Strategic Shifts
Formulation science and procurement infrastructure are undergoing parallel transformation as thermal stability requirements clash with clean-label imperatives across dairy and beverage segments.
Microencapsulation technology is fragmenting the traditional trade-off between natural origin and processing resilience. Encapsulated beet and curcumin variants now survive UHT treatment and retort processing. Japanese dairy processors and Chinese RTD tea manufacturers are adopting these stabilized formats at accelerating rates. The technology is fragmenting incumbent supplier relationships by enabling smaller botanical extractors to compete on performance parity.
India's FSSAI labeling mandates and China's SAMR enforcement of GB standards are compressing permissible synthetic dye thresholds. Beverage manufacturers face simultaneous compliance deadlines across both jurisdictions. The regulatory pressure is forcing dual-track reformulation strategies that prioritize anthocyanin and carotenoid alternatives in export-oriented production lines.
Direct procurement from farming cooperatives is displacing traditional distributor intermediation. Large-scale beverage manufacturers in Maharashtra and Gujarat are establishing captive supply agreements with turmeric and paprika clusters. This channel shift concentrates volume with integrated processors while squeezing margin pools for regional trading houses dependent on spot-market sourcing.
Asia-Pacific Food Colorants Market Segmentation
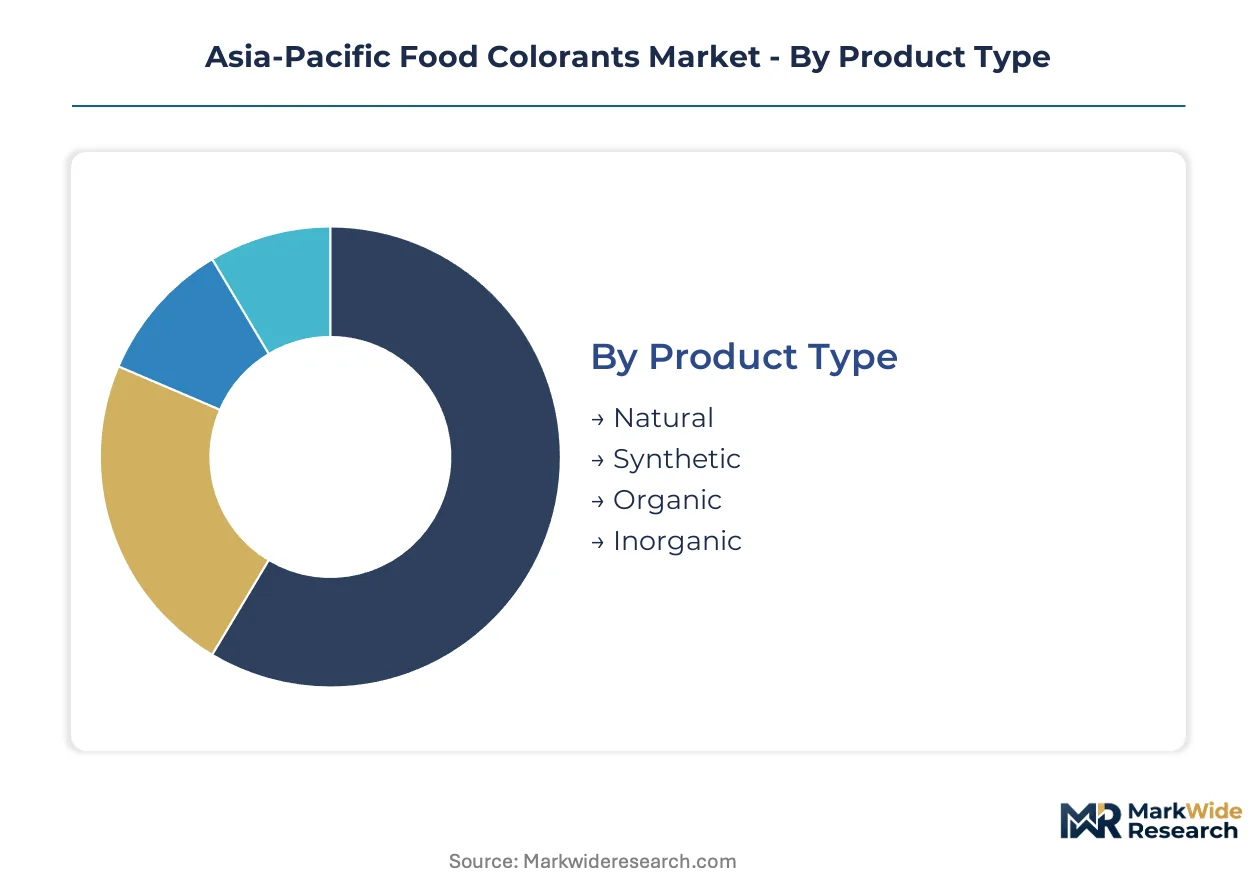
Segmentation in the Asia-Pacific food colorants market reveals divergent procurement patterns across clean-label reformulation cycles. Channel preferences vary sharply between multinational beverage manufacturers seeking certified natural grades and cost-sensitive snack producers maintaining synthetic portfolios.
Product Type:
Natural colorants flow predominantly through direct procurement agreements with farming cooperatives, while synthetic variants still dominate traditional distributor networks serving bakery and confectionery segments.
- Natural:Anthocyanin and curcumin extracts command premium positioning in China's GB-compliant beverage sector. Maharashtra-Gujarat food processors are establishing captive supply agreements with turmeric clusters to secure volume commitments for FSSAI-mandated reformulations.
- Synthetic:Azo dye compounds retain structural presence in heat-processed snacks where thermal stability requirements exceed natural pigment performance. Cost predictability anchors procurement for Indonesia's halal-certified confectionery exporters balancing export compliance with domestic price sensitivity.
- Organic:Certified organic grades absorb expanding margin pools in Japan's dairy applications.
- Inorganic:Mineral-based pigments concentrate in specialty candy coatings and decorative bakery finishes.
Natural dominates installed base value. Synthetic is where expansion concentrates in cost-optimized segments.
Application:
Margin tiering separates premium reformulation budgets in beverages from efficiency-driven procurement in mass-market snacks.
- Beverages:RTD tea and functional drink manufacturers across China's eastern manufacturing corridor are absorbing microencapsulated beet and curcumin variants at accelerating rates. SAMR enforcement of natural additive classifications is compressing permissible synthetic thresholds and forcing dual-track supply qualification.
- Dairy Products:UHT milk and yogurt processors require heat-stable formulations previously blocked by thermal degradation of plant-derived pigments. Japanese dairy manufacturers are adopting stabilized natural grades to meet Ministry of Health, Labour and Welfare positive list requirements.
- Bakery:Synthetic retention remains highest here due to Maillard reaction compatibility and cost floors.
- Snacks:Fried and extruded products prioritize synthetic azo dyes for color consistency under high-temperature processing.
Beverages command the steepest expansion trajectory. Dairy is where technical innovation unlocks previously blocked natural substitution.
Form:
Volume concentration favors liquid concentrates for beverage integration, while powder formats retain logistics advantages in cross-border bakery supply chains.
- Liquid:Concentrated natural extracts integrate directly into automated dosing systems at China's RTD tea bottling facilities. Standardized viscosity specifications reduce batch-to-batch variation in high-speed production environments.
- Powder:Spray-dried variants dominate interregional trade between India's extraction clusters and Southeast Asian confectionery processors. Shelf stability and reduced shipping weights favor powder in Indonesia's archipelago distribution challenges.
- Gel:Viscous formats concentrate in artisan bakery and decorative applications requiring precise manual dosing.
- Paste:High-solid content pastes serve niche marzipan and fondant specialty manufacturers.
Liquid leads volume throughput. Powder is where supply chain resilience concentrates for island nation distribution.
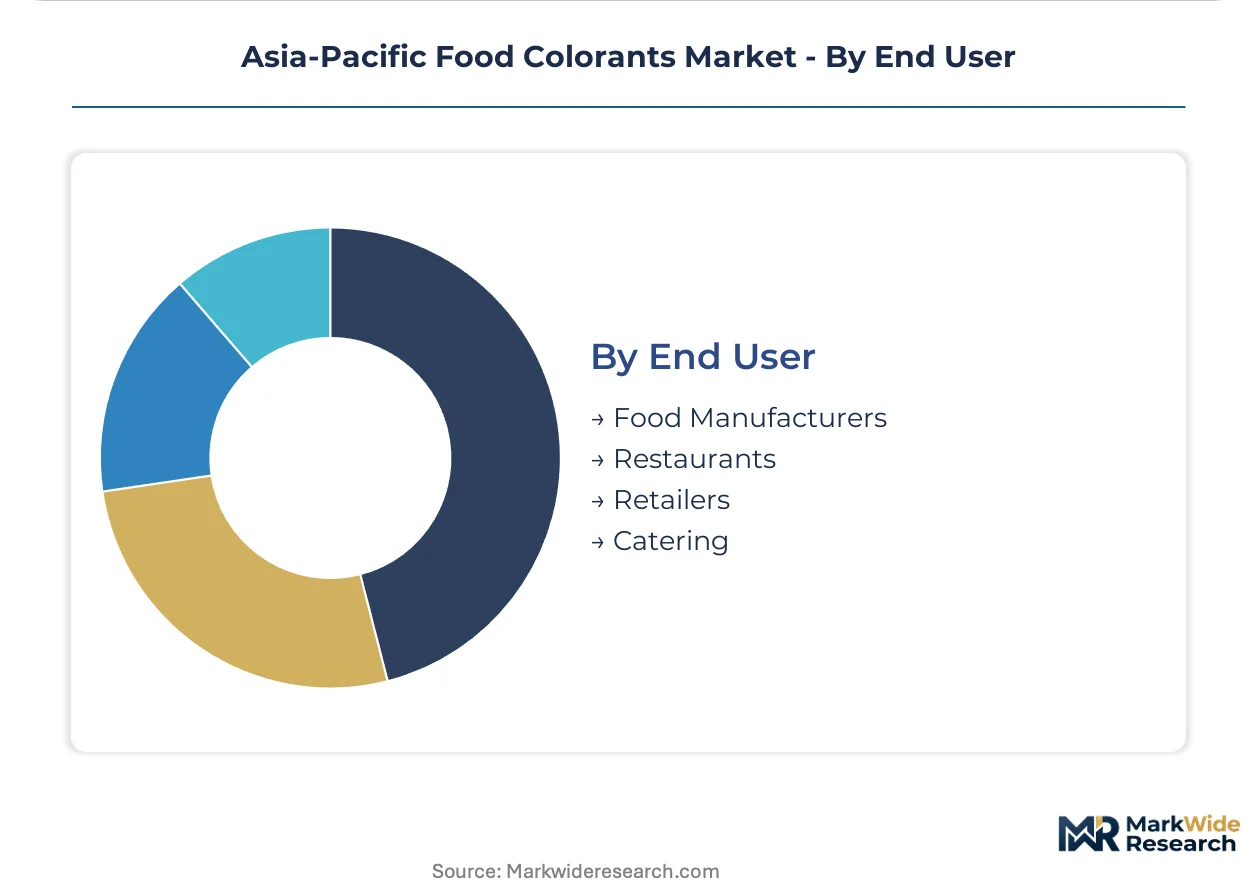
End User:
Customer type stratifies between integrated manufacturers with backward control and fragmented foodservice operators dependent on distributor intermediation.
- Food Manufacturers:Large-scale processors in China's eastern corridor and India's Maharashtra-Gujarat belt are disintermediating traditional trading houses through direct farming cooperative agreements. E-commerce procurement platforms are accelerating this channel shift for mid-scale manufacturers.
- Restaurants:Chain operators face divergent compliance requirements across FSSAI and SAMR jurisdictions, complicating centralized procurement for pan-Asian brands.
- Retailers:Private-label packaged food divisions are mandating clean-label specifications that cascade pressure upstream to ingredient suppliers.
- Catering:Institutional foodservice concentrates demand for cost-optimized synthetic blends in high-volume meal preparation.
Food Manufacturers dominate procurement volume. Retailers are where specification pressure concentrates for upstream reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material extraction clusters in southern India and Peru concentrate upstream supply, while formulation demand clusters along China's eastern seaboard and Indonesia's Java corridor. SAMR enforcement timelines and FSSAI labeling mandates are compressing procurement cycles across manufacturing hubs.
China
RTD tea and functional beverage manufacturers in the Yangtze River Delta absorb microencapsulated natural pigments at accelerating rates. SAMR's GB standards enforcement is compressing permissible synthetic dye thresholds ahead of compliance deadlines. Shanghai and Hangzhou processing corridors are qualifying dual-source supply agreements with anthocyanin extractors to mitigate reformulation risk.
India
Maharashtra-Gujarat food processors are establishing captive turmeric and paprika supply agreements with farming cooperatives in southern India. FSSAI's stricter artificial additive labeling mandates are forcing synthetic-to-natural conversion across export-oriented production lines. Mumbai-Ahmedabad manufacturing clusters are absorbing heat-stable curcumin formulations for dairy applications previously blocked by thermal degradation.
Indonesia
Halal-certified confectionery exporters in Java are absorbing certified natural colorants to meet EU Green Deal extraterritorial compliance requirements. The country's national food and drug regulator is tightening permissible additive thresholds for cross-border trade. Surabaya and Jakarta processing hubs are qualifying beet-derived pigments for heat-processed candy applications.
Japan
UHT milk and yogurt processors require stabilized natural grades to meet Ministry of Health, Labour and Welfare positive list requirements. METI-aligned quality certifications are elevating procurement standards for imported botanical extracts. Kansai dairy manufacturers are adopting microencapsulated carotenoid formulations for shelf-stable beverage applications.
Vietnam
Beverage contract manufacturers lack certified natural colorant suppliers, creating first-mover whitespace for qualified entrants. The country's national standards body is harmonizing permissible additive limits with ASEAN frameworks. Ho Chi Minh City processing corridors are absorbing spray-dried anthocyanin powders for RTD tea export production.
Asia-Pacific Food Colorants Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific food colorants landscape. Integrated botanical extractors with proprietary stabilization technology command premium positioning in beverage and dairy reformulation cycles. Cost-optimized synthetic blenders retain structural presence in heat-processed snack segments where thermal stability outweighs label transparency. Competitive moves concentrate on backward integration into farming clusters and microencapsulation licensing agreements.
Within the integrated technology tier, Givaudan SA and Sensient Technologies Corporation exemplify archetypes pursuing formulation science differentiation. Roha Dyechem occupies a position representing cost-optimized natural-synthetic hybrid strategies. These three anchors illustrate the strategic divergence between premium-grade certification pursuit and volume-scale procurement efficiency across regional procurement networks.
| Leading Market Players |
|---|
| Givaudan SA |
| Archer Daniels Midland Company |
| Sensient Technologies Corporation |
| Roha Dyechem |
| Koninklijke DSM N.V. |
| Döhler |
| Chr. Hansen Holding A/S |
| Synthite Industries |
| Kalsec Inc |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for anthocyanin concentrates expose buyers to harvest volatility while concentrating pricing power with integrated extractors holding captive farming agreements. SAMR compliance deadlines and FSSAI labeling mandates compress procurement timelines, forcing beverage manufacturers to absorb premium natural-grade markups or risk reformulation delays.
Pricing Analysis
China's GB standards dictate the pricing tier structure across the Asia-Pacific food colorants landscape. Three-tier pricing structure across premium natural-certified, standard food-grade, and economy synthetic levels separates procurement budgets by application thermal requirements. Price differentiation rests on organic certification status and microencapsulation technology licensing. Cost compression in standard natural grades is intensifying because Maharashtra-Gujarat processors are establishing direct farming cooperative agreements. Snack manufacturers remain most price-sensitive due to thin margins on heat-processed products, while Japanese dairy processors show least sensitivity given METI-aligned quality mandates.
Supply Chain Analysis
Sixty-day lead times for spray-dried curcumin powders from southern India expose Indonesian confectionery exporters to monsoon-driven supply interruptions. Raw material extraction concentrates in India's turmeric and paprika farming clusters, Peru's cochineal cultivation zones, and China's beet processing corridors. Downstream formulation draws from beet-derived pigments, anthocyanin concentrates, and carotenoid suspensions. Single-source vulnerability runs through Peru-Canary Islands carmine supply. Distribution runs through direct procurement agreements with farming cooperatives for large-scale beverage manufacturers, while regional trading houses serve fragmented foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between FSSAI and SAMR compliance tracks creates specialist opportunities for certification-nimble suppliers serving dual-jurisdiction exporters. Clean-label reformulation timelines compress procurement cycles, rewarding agile entrants with qualified natural-grade inventories.
For Market Incumbents: Shield margin pools in dairy applications by locking microencapsulation licensing agreements with Japanese and Chinese processors ahead of competitor qualification. Deepen backward integration into southern India turmeric clusters to secure volume commitments from Maharashtra-Gujarat food manufacturers facing FSSAI mandates. Accelerate organic certification timelines for beet-derived pigments to capture EU Green Deal tailwinds among ASEAN exporters. For New Entrants and Emerging Players: FSSAI-SAMR parallel approval fast-tracks offer qualification arbitrage for specialist extractors targeting Vietnam's underpenetrated beverage contract manufacturing sector. Vietnam's processing corridor lacks certified natural colorant suppliers, creating first-mover whitespace for qualified entrants with heat-stable anthocyanin formulations. Direct e-commerce procurement platforms disintermediate traditional distributor networks, enabling mid-scale manufacturers to bypass incumbent trading house relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because clean-label mandates are structurally permanent across China, India, and Southeast Asia. Acquisition targets should concentrate on integrated botanical extractors with proprietary stabilization technology and captive farming agreements. Watch for SAMR enforcement acceleration as the inflection indicator signaling reformulation cycle compression and premium natural-grade demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Clusters | Maharashtra-Gujarat processors secure captive turmeric supply against FSSAI-mandated reformulation deadlines. |
| Microencapsulation Technology Licensing | Japanese dairy manufacturers adopt heat-stable curcumin for UHT applications previously blocked by thermal degradation. |
| Dual-Jurisdiction Certification Investment | Specialist extractors capture Vietnam whitespace by qualifying simultaneous FSSAI-SAMR approval tracks. |
| Direct E-Commerce Procurement Platform | Mid-scale Chinese RTD tea bottlers disintermediate traditional distributor networks for anthocyanin concentrates. |
| Organic Certification Acceleration | Indonesian halal-certified confectionery exporters meet EU Green Deal extraterritorial compliance requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs filings, FSSAI additive registration databases, SAMR GB standard enforcement records, and ASEAN harmonization protocols. Primary interviews engaged procurement directors at Chinese beverage manufacturers, FSSAI compliance officers at Indian food processors, halal certification auditors at Indonesian confectionery exporters, and extraction technology specialists at southern India botanical processors. Secondary validation drew from trade flow data, regulatory filing repositories, and agricultural harvest statistics. Bottom-up volume modeling triangulated against top-down value estimates across natural, synthetic, and organic grade tiers.
Segmentation dimensions modeled include product type, application thermal requirements, form factor logistics, and end-user procurement channel. CAGRs were derived from regression analysis of historical procurement volumes against regulatory enforcement timelines. Forecast inputs incorporated climate sensitivity coefficients for paprika and turmeric harvests, microencapsulation adoption curves in dairy processing, and halal certification penetration rates across ASEAN export corridors. Outputs reflect assumptions across the analysis window without year-specific anchoring.
Decision-makers should treat outputs as directional under sustained regulatory enforcement intensity and stable agricultural yield patterns; material deviation in SAMR or FSSAI implementation timelines would warrant model refresh. Climate-induced harvest disruption or synthetic dye threshold relaxation represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Lemon Extract Market