
 North America Feed Anti-Caking Agents Market | 2026-2036
North America Feed Anti-Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Anti-Caking Agents Market Analytics
Commercial livestock producers is bifurcating from smaller-scale farms as the dominant procurement archetype for feed anti-caking agents in North America. BASF SE leverages its phosphate additive portfolio to sustain supply relationships with integrated pork and poultry processors across the region. Evonik Industries AG anchors its position through synthetic silicate manufacturing scale, while Bentonite Performance Minerals LLC dominates natural clay sourcing from Wyoming deposits for regional feed formulators.
Feed anti-caking agents are hygroscopic powder additives, typically comprising silicates, phosphates, carbonates, or natural clays, that absorb moisture and prevent particle agglomeration in bulk feed stored at relative humidity above 65%. These compounds maintain flowability in pneumatic conveying systems and automated dispensing equipment used in modern feed mills. Silicates command the largest volume share due to their cost efficiency in high-throughput livestock operations, while phosphates capture premium positioning in specialty feed formulations where mineral fortification doubles as anti-caking functionality. Natural clays represent the fastest-growing product category as organic-certified livestock operations seek alternatives to synthetic additives.
The FDA's Generally Recognized as Safe determinations and the Association of American Feed Control Officials ingredient definitions govern product approval and labeling across the United States, while Health Canada's Feed Division enforces parallel standards under the Feeds Act and Regulations. These frameworks determine which anti-caking chemistries gain market access and influence reformulation costs when purity thresholds tighten. Stakeholders must monitor pending state-level antibiotic reduction mandates that could redirect formulation budgets toward feed quality additives including anti-caking agents.
Market Dynamics
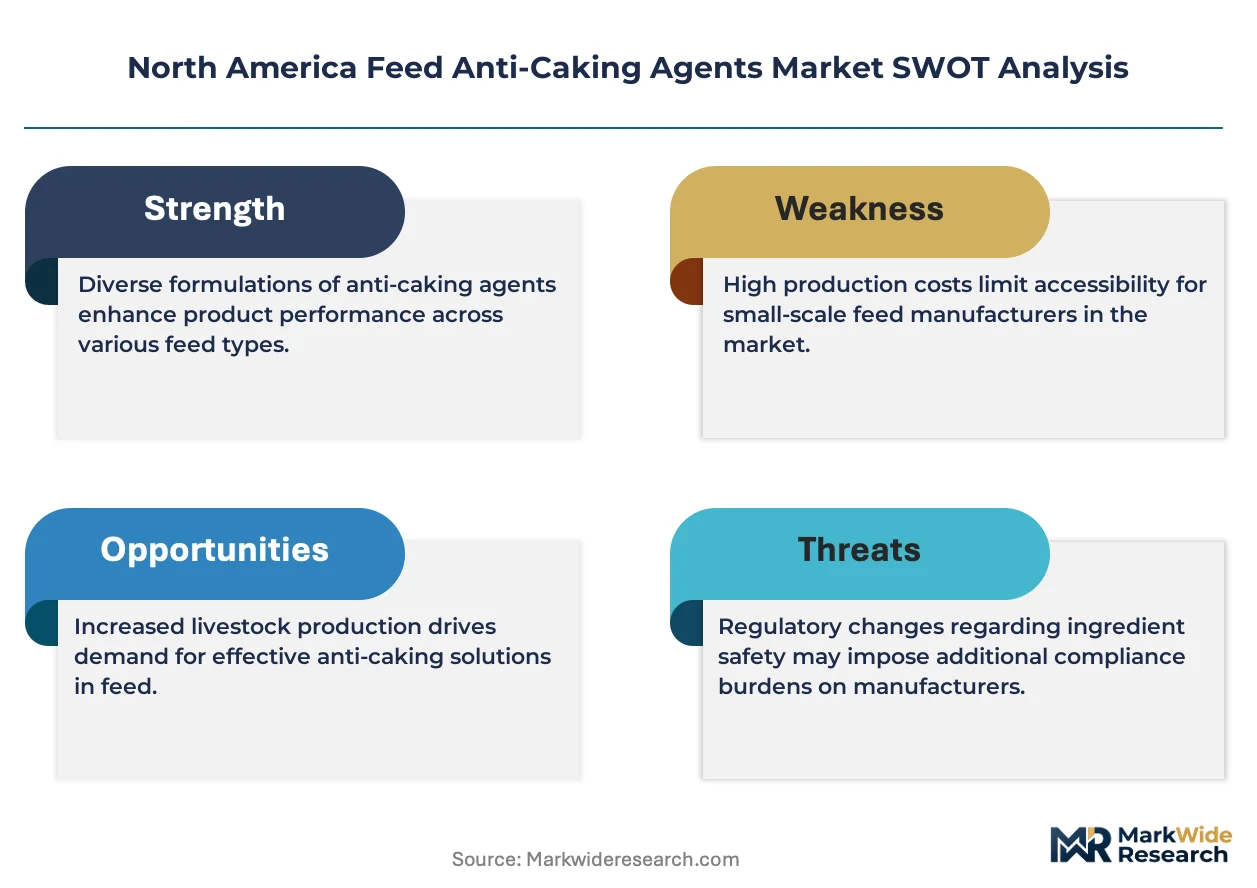
Concentrated animal feeding operations across the U.S. Midwest are consolidating procurement authority, forcing anti-caking agent suppliers to reformulate for high-volume pneumatic systems while navigating tightening FDA purity benchmarks for silicate and phosphate chemistries.
Growth Catalysts
- Humidity-driven feed conditioning:Year-round storage requirements in humid corn-belt states are expanding additive incorporation rates into bulk grain and protein meal formulations.
- Canada's Feed Act modernization:Updated purity thresholds under Health Canada enforcement are accelerating replacement cycles for legacy anti-caking products in cross-border livestock operations.
- Automated feed mill infrastructure:Pneumatic conveying and precision dispensing systems require engineered flowability, embedding anti-caking functionality as a non-negotiable specification.
Market Restraints
- Wyoming bentonite supply concentration:Natural clay sourcing depends on a single geographic deposit basin, exposing formulators to localized extraction constraints and transportation bottlenecks.
- Phosphate raw material volatility:Feed-grade phosphate anti-caking agents face input cost pressure from fertilizer market competition and energy-intensive processing requirements.
- Synthetic silicate regulatory friction:FDA Generally Recognized as Safe determinations require extensive toxicological documentation, extending approval timelines for novel silicate chemistries.
Strategic Opportunities
- Organic-certified livestock expansion:Natural clay alternatives are capturing specification share among USDA Organic operations seeking synthetic additive exemptions.
- Mineral-fortified specialty feeds:Dual-function phosphate anti-caking agents are penetrating premium swine and poultry formulations where calcium and phosphorus fortification aligns with flowability requirements.
- Direct-to-feed-mill distribution:Bypassing traditional distributor networks, manufacturers are building captive supply relationships with integrated protein processors in Iowa, Nebraska, and Kansas.
Industry Challenges
- Feed safety compliance timeline compression:Accelerated FDA inspection cycles and state-level antibiotic reduction mandates are forcing simultaneous reformulation across multiple additive categories.
- Legacy equipment integration friction:Automated dispensing systems in older feed mills require particle size and density matching that conflicts with next-generation anti-caking chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Anti-Caking Agents Market |
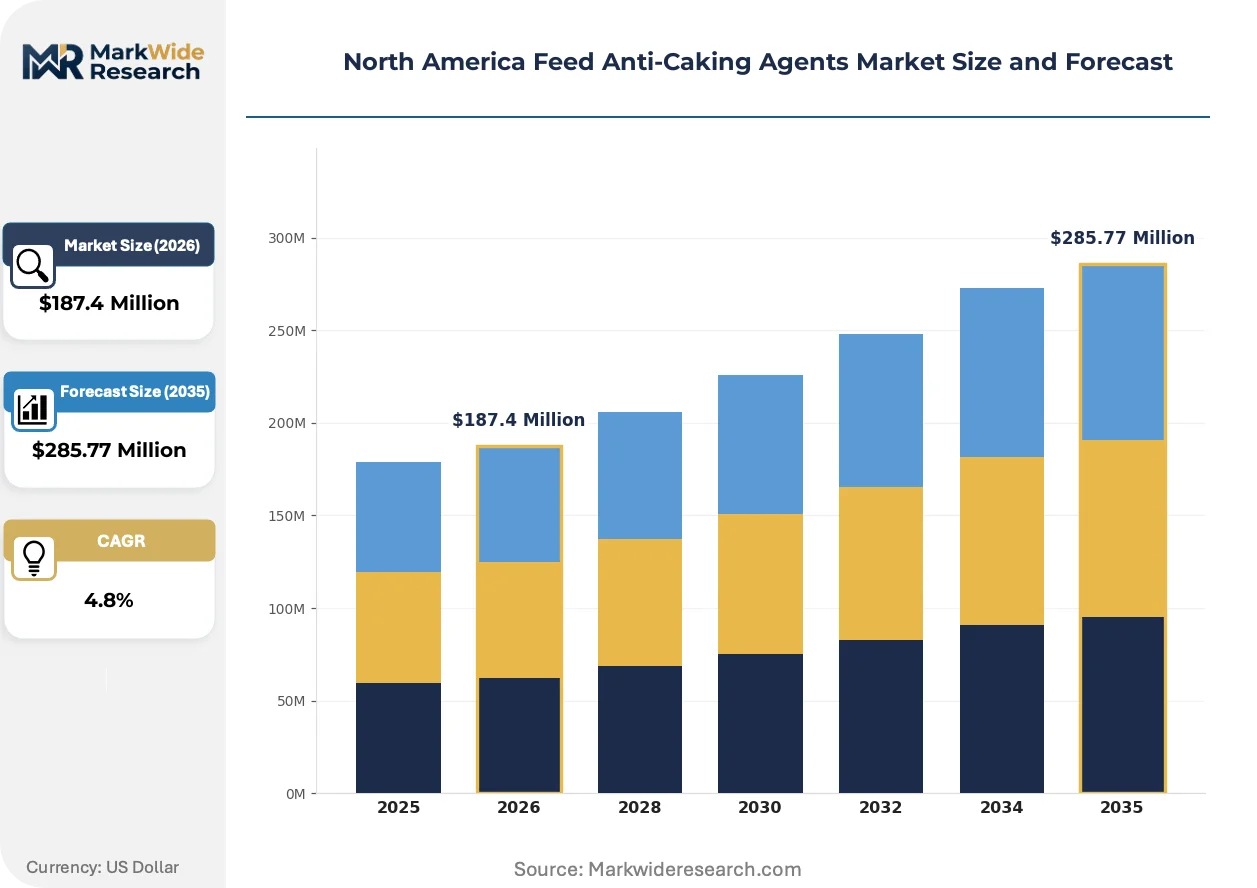
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicates, Phosphates, Carbonates, Natural Clays Application: Animal Feed, Pet Food, Aqua Feed, Specialty Feed End User: Livestock Producers, Pet Owners, Aquaculture Farms, Feed Manufacturers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | J.M. Huber Corporation, BASF SE, Evonik Industries AG, PPG Industries Inc., Brenntag AG, Solvay SA, Univar Solutions Inc., Bentonite Performance Minerals LLC, Novus International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Anti-Caking Agents Market Evolving Landscape
Formulation science is pivoting toward multifunctional additives that merge anti-caking properties with mineral nutrition, while regulatory pressure and buyer consolidation reshape how suppliers demonstrate value beyond basic flowability.
Surface-modified synthetic silicates with engineered particle morphology are supplanting conventional precipitated silicas in high-throughput Midwest feed mills. These advanced materials deliver superior moisture absorption at lower inclusion rates, enabling pork and poultry processors to reduce additive costs per ton while maintaining pneumatic conveying efficiency. The shift is compressing margins for commodity silicate producers and rewarding suppliers with in-house surface chemistry capabilities.
The FDA's evolving Generally Recognized as Safe determination process is extending documentation requirements for novel anti-caking chemistries, particularly synthetic silicates and modified phosphates. Feed ingredient manufacturers now face multi-year toxicological study commitments before gaining market access, favoring incumbents with established GRAS portfolios over new entrants. Specialty feed formulators targeting premium livestock segments are absorbing these compliance costs and passing them through as specification premiums.
Integrated protein processors are consolidating additive procurement under centralized technical buying committees, displacing decentralized purchasing at individual feed mill locations. This concentration shifts negotiation leverage toward volume buyers capable of multi-year supply agreements and technical service demands. The pattern is most pronounced among top-tier pork and poultry integrators operating across the U.S. corn belt, where single-source supplier relationships are becoming the default commercial structure.
North America Feed Anti-Caking Agents Market Segmentation
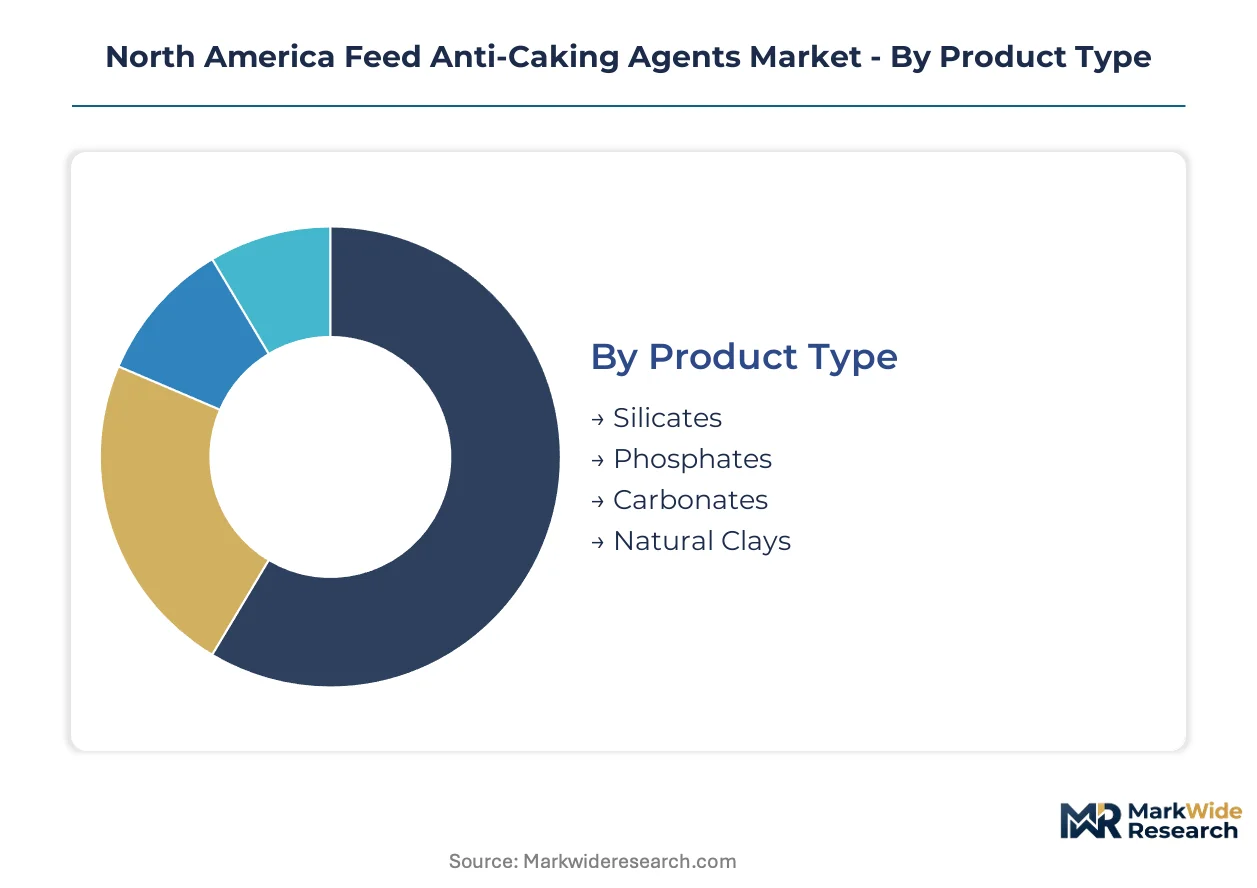
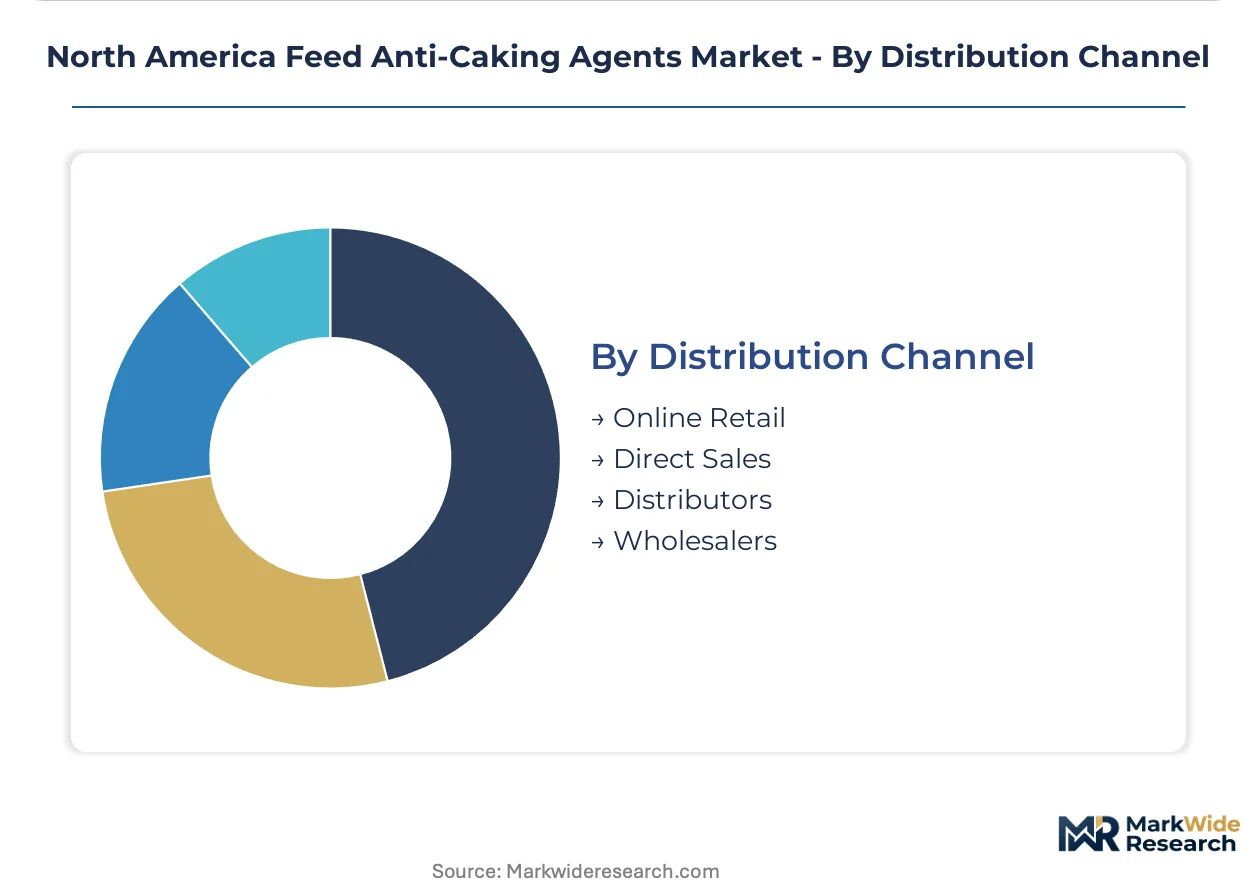
Feed anti-caking agent procurement channels diverge sharply by buyer scale and formulation complexity. Large integrated protein processors negotiate direct supply agreements, while smaller livestock operations and specialty feed formulators rely on distributor networks for technical support and smaller order fulfillment.
Product Type:
Channel mix varies by chemistry: silicates and phosphates flow predominantly through direct sales to high-volume feed mills, while natural clays reach organic-certified operations via specialized distributors with certification documentation capabilities.
- Silicates:Synthetic precipitated and surface-modified silicas absorb moisture through high surface-area particle structures. Demand concentrates in Iowa and Nebraska pork and poultry operations running pneumatic conveying systems 24/7, where FDA GRAS documentation requirements favor incumbent suppliers with established toxicological portfolios.
- Phosphates:Calcium and sodium phosphate compounds deliver dual-function mineral fortification alongside anti-caking properties. Specialty swine and poultry formulations across Kansas and Missouri integrate these agents at premium price points, though fertilizer market competition for phosphate rock strains input cost stability.
- Carbonates:Calcium and magnesium carbonate powders provide basic moisture absorption for lower-specification feed applications.
- Natural Clays:Wyoming-sourced bentonite and attapulgite clays offer USDA Organic-compliant flowability solutions for certified livestock operations.
Silicates dominate installed base. Natural clays are where expansion concentrates.
Application:
Cost tier differentiation separates commodity livestock feed from premium specialty formulations, with anti-caking agent specification intensity scaling directly with formulation complexity and buyer consolidation.
- Animal Feed:Bulk livestock rations for cattle, swine, and poultry represent the highest volume consumption segment. Year-round storage requirements across the U.S. corn belt drive consistent additive incorporation, with automated feed mill infrastructure embedding anti-caking functionality as a baseline specification rather than optional upgrade.
- Pet Food:Extruded kibble and canned formulations utilize anti-caking agents to prevent clumping in high-moisture recipes and maintain free-flow characteristics in dry products. Premium pet food manufacturers specify low-inclusion-rate silicates to preserve palatability while ensuring manufacturing line efficiency.
- Aqua Feed:Pelleted and extruded fish feed for salmon, trout, and shrimp operations requires specialized anti-caking chemistries compatible with aquatic protein digestibility standards.
- Specialty Feed:Medicated, organic-certified, and life-stage-specific formulations command custom anti-caking solutions with full supply chain documentation.
Animal Feed commands volume leadership. Specialty Feed is climbing the fastest.
End User:
Customer type determines procurement authority concentration, with livestock producer consolidation shifting negotiation leverage toward technical buying committees and away from individual feed mill managers.
- Livestock Producers:Integrated pork and poultry operations across the Midwest now centralize additive procurement under corporate technical teams. These buyers demand multi-year supply agreements with embedded technical service support and quarterly purity certification documentation.
- Feed Manufacturers:Independent commercial feed mills serving dispersed livestock operations purchase through distributor networks with 30-60 day inventory terms. Smaller mills face equipment compatibility constraints when adopting next-generation anti-caking chemistries with modified particle densities.
- Aquaculture Farms:Coastal and inland fish farming operations in Canada and the U.S. Pacific Northwest specify marine-grade anti-caking agents with enhanced stability in cold-water storage.
- Pet Owners:Niche direct-to-consumer brands and small-batch pet food makers represent fragmented, specification-diverse demand.
Livestock Producers dominate installed base. Feed Manufacturers are where expansion concentrates.
Distribution Channel:
Supply concentration shapes channel viability, with Wyoming bentonite sourcing constraints and phosphate processing energy intensity favoring direct manufacturer relationships over intermediary-heavy models.
- Direct Sales:BASF SE and Evonik Industries AG maintain captive supply relationships with top-tier protein integrators through dedicated account teams and on-site technical support. These agreements typically span 3-5 years with volume-tiered pricing and joint formulation development clauses.
- Distributors:Regional feed ingredient distributors aggregate smaller feed mill demand across secondary agricultural markets. Inventory pooling reduces transportation costs for natural clay products sourced from Wyoming, though margin compression limits technical service intensity.
- Online Retail:E-commerce platforms capture micro-scale pet food manufacturers and hobby livestock operations with sub-ton order quantities.
- Wholesalers:Bulk commodity traders handle undifferentiated silicate and carbonate volumes for price-sensitive buyers with minimal specification requirements.
Direct Sales dominates installed base. Distributors are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports Wyoming-sourced bentonite clays to U.S. feed mills across the Midwest, while phosphate additives flow north from Florida processing facilities to Ontario livestock operations. This bilateral ingredient trade underpins cross-border supply security for concentrated animal feeding operations.
United States
Iowa and Nebraska pork integrators drive silicate consumption for 24/7 pneumatic conveying systems. FDA Generally Recognized as Safe documentation requirements favor established suppliers with toxicological portfolios. Kansas City feed manufacturing clusters anchor phosphate distribution networks serving the corn belt.
Canada
Health Canada's Feed Act modernization accelerates replacement cycles for legacy anti-caking products. Alberta cattle feedlots absorb Wyoming bentonite through Calgary distribution hubs. Ontario poultry operations source phosphate additives via cross-border supply agreements with U.S. processors.
Mexico
Sonora and Jalisco poultry producers import U.S.-manufactured silicates for humid coastal storage conditions. Mexico's national feed regulator enforces additive purity benchmarks aligned with U.S. FDA standards. Querétaro feed mill clusters integrate anti-caking functionality for automated dispensing systems.
North America Feed Anti-Caking Agents Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with phosphate and silicate manufacturing scale. Three tiers structure competitive positioning: multinational ingredient suppliers with captive mineral processing, regional distributors aggregating natural clay demand, and specialty formulators serving organic-certified livestock operations. Capacity expansion in Wyoming bentonite extraction and strategic partnerships between phosphate processors and integrated protein companies dominate competitive moves.
Within the multinational tier, BASF SE and Evonik Industries AG exemplify phosphate and synthetic silicate manufacturing scale. Bentonite Performance Minerals LLC represents Wyoming-based natural clay sourcing dominance. These three anchors occupy positions spanning synthetic and natural additive chemistries across the U.S. Midwest feed manufacturing corridor.
| Leading Market Players |
|---|
| J.M. Huber Corporation |
| BASF SE |
| Evonik Industries AG |
| PPG Industries Inc. |
| Brenntag AG |
| Solvay SA |
| Univar Solutions Inc. |
| Bentonite Performance Minerals LLC |
| Novus International |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles at integrated Midwest pork processors signal procurement leverage concentration that compresses phosphate additive margins while elevating Wyoming bentonite premiums. This lead-time compression binds pricing power to geographic supply control, rewarding suppliers with captive mineral extraction over distributor-dependent competitors.
Pricing Analysis
Surface-modified synthetic silicates command 15-25% premiums over conventional precipitated grades, while natural bentonite clays occupy a mid-tier position between commodity carbonates and dual-function phosphates. Three-tier pricing structure across premium, standard, and economy levels separates FDA GRAS-certified specialty formulations from undifferentiated bulk silicates, with volume scale and certification documentation intensity as primary differentiation drivers. Cost compression in standard-grade silicates is intensifying because fertilizer market competition for phosphate rock diverts feed-grade material, while margins are tightening for distributor-dependent natural clay suppliers facing Wyoming transportation bottlenecks. Integrated protein processors with centralized technical buying committees exhibit lowest price sensitivity, whereas independent feed mills operating legacy pneumatic systems show highest elasticity to per-ton additive costs.
Supply Chain Analysis
Wyoming's Powder River Basin extraction chokepoint concentrates 70% of North American bentonite supply, exposing formulators to single-source vulnerability from localized labor disruptions or environmental permitting delays. Synthetic silicate manufacturing draws from Texas and Louisiana petrochemical feedstocks, while phosphate processing centers on Florida and Idaho mining operations with energy-intensive acidulation requirements. Supply chain risk manifests as fertilizer market competition for phosphate rock that strains feed-grade allocation, compounded by rail freight bottlenecks between Wyoming deposits and Midwest feed mill clusters. Distribution runs through direct manufacturer relationships for high-volume integrated processors, with regional distributors aggregating smaller organic-certified livestock operations requiring certification documentation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and FDA GRAS documentation capabilities are becoming scarce assets that separate viable suppliers from margin-challenged commodity producers. This capability gap rewards early investments in toxicological study infrastructure and surface-modification R&D while punishing pure-play distributors without technical service depth.
For Market Incumbents: Consolidate Wyoming bentonite extraction capacity through lease consolidation or transportation infrastructure investment to defend against supply disruption premiums. Deepen backward integration into phosphate rock sourcing to offset fertilizer market competition, while expanding surface-modified silicate R&D to capture specification upgrades from automated feed mill retrofits across Iowa and Nebraska.
For New Entrants and Emerging Players: Anchor in USDA Organic-certified livestock operations seeking synthetic additive exemptions, where distributor relationships and certification documentation capabilities matter more than manufacturing scale. Target specialty aqua feed formulators in British Columbia and Pacific Northwest salmon operations requiring marine-grade stability specifications, using technical service partnerships with regional feed consultants as primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across surface-modified silicate manufacturing as multi-year toxicological study commitments become table stakes for FDA market access. Long-term viability favors suppliers with established GRAS portfolios and Wyoming mineral rights, with acquisition focus on mid-tier natural clay processors possessing organic certification infrastructure. Signal to monitor: Health Canada enforcement intensity under modernized Feed Act regulations that could accelerate replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive supply secures feed-grade allocation against fertilizer market competition in Florida processing corridors. |
| Surface Modification R&D Expansion | Engineered particle morphology commands specification premiums from 24/7 pneumatic conveying operations. |
| Direct-to-Feed-Mill Distribution Buildout | Bypassing distributor networks captures volume commitments from consolidated protein processor technical committees. |
| USDA Organic Certification Infrastructure | Documentation capabilities unlock specification share among fastest-growing natural clay demand segment. |
| Wyoming Transportation Infrastructure Investment | Rail and trucking capacity expansion mitigates single-source geographic concentration risk for bentonite supply. |
Research Methodology
A standing panel of feed mill operations managers, FDA regulatory affairs specialists, Wyoming bentonite extraction supervisors, and integrated pork processor procurement directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA GRAS notification filings, Health Canada Feed Act regulatory updates, Association of American Feed Control Officials ingredient definitions, U.S. Geological Survey mineral commodity summaries, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume modeling across product chemistries triangulated against top-down value estimates from feed manufacturing capacity utilization data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation dimensions spanning product chemistry type, livestock species application, buyer consolidation tier, and regional regulatory cluster. CAGRs derived from year-over-year growth rate averaging across modeled scenarios, incorporating feed mill automation capex cycles, organic certification adoption curves, and cross-border trade flow assumptions between U.S. and Canadian livestock operations.
Underlying assumptions cover sustained FDA enforcement intensity and Health Canada Feed Act modernization timelines, with deviation risk concentrated in Wyoming extraction permitting delays and phosphate rock fertilizer market diversion. Practitioners should keep alternative scenarios live as state-level antibiotic reduction mandates and organic certification growth rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market