
 Laser Safety Glasses Market | 2026-2036
Laser Safety Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Safety Glasses Market Foresight
Ultrafast laser proliferation in materials processing is reconfiguring optical density requirements across the protective eyewear value chain. Honeywell International leverages its industrial safety distribution network to sustain institutional procurement relationships. Thorlabs specializes in research-grade eyewear calibrated to narrow wavelength bands. Kentek Corporation anchors its position through in-house dye formulation capabilities that address emerging ultrafast applications.
Laser safety glasses are optical protective devices engineered with specific optical density ratings and wavelength absorption spectra to attenuate coherent light exposure below maximum permissible exposure limits, typically manufactured through dye-impregnated polycarbonate molding or coated glass lamination processes. Their primary purpose is preventing retinal injury and corneal damage across industrial, medical, and research settings where Class 3B and Class 4 lasers operate. Polycarbonate material formulations dominate volume due to impact resistance and lighter weight, though glass substrates retain preference in high-power continuous-wave environments where thermal loading exceeds polymer limits. Non-prescription glasses capture the broadest end-user base, while prescription configurations command premium positioning in healthcare and research labs where vision correction compliance intersects with safety mandates.
ANSI Z136.1 standards in the United States, EN 207/208 frameworks in Europe, and IEC 60825 classifications collectively define optical density testing protocols and product marking requirements that determine market access. OSHA workplace safety enforcement and FDA laser product regulations in the United States further compel employer provision of certified protective equipment. Stakeholders must monitor wavelength-specific certification gaps as fiber laser and ultrafast source portfolios diversify beyond legacy test specifications.
Market Dynamics
Ultrafast laser proliferation in materials processing is collapsing legacy optical density specifications and forcing recalibration of certification protocols across the protective eyewear value chain. Industrial buyers now demand wavelength-specific protection that legacy dye formulations cannot deliver.
Growth Catalysts
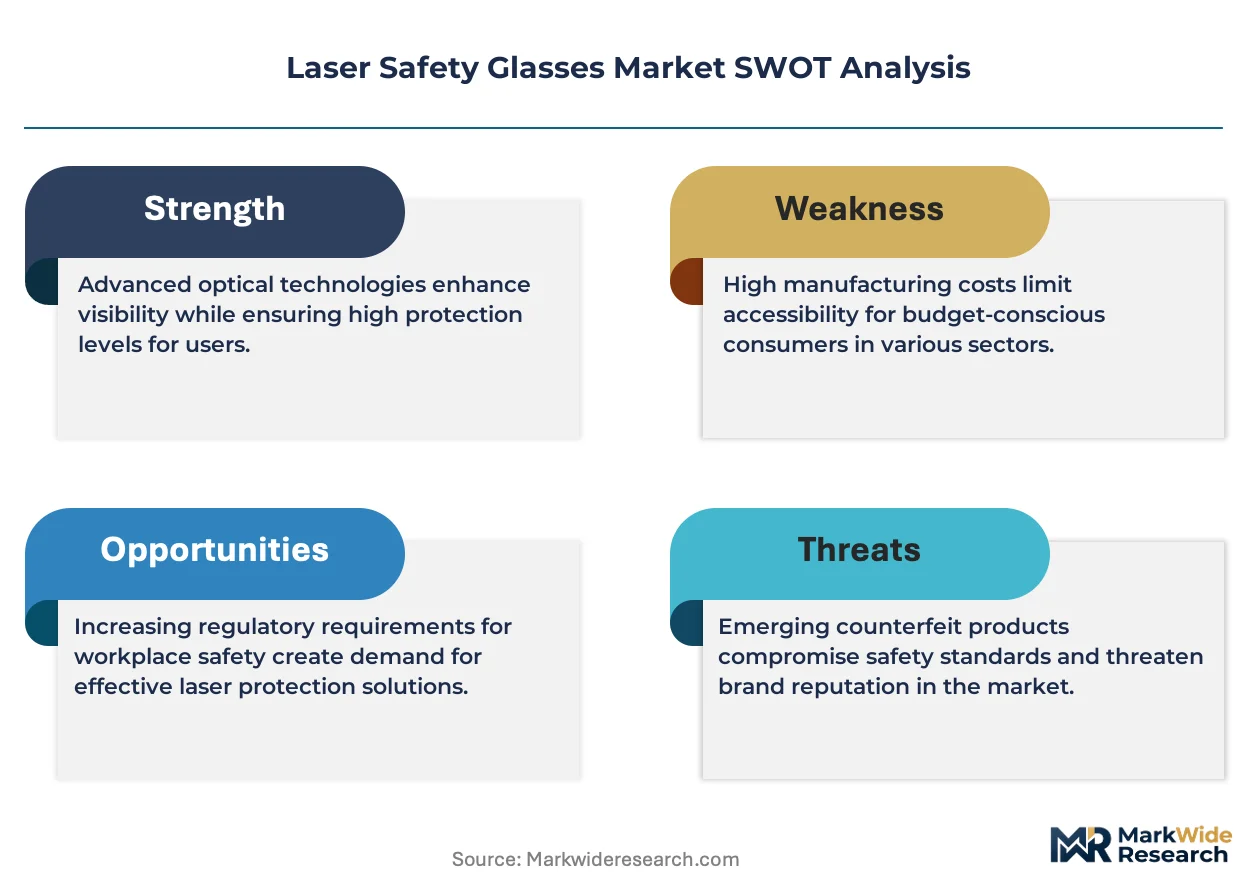
- ANSI Z136.1 Compliance Mandates:OSHA workplace safety enforcement in the United States compels employer provision of certified protective equipment across manufacturing facilities deploying Class 4 lasers.
- Medical Laser Expansion:Dermatology and ophthalmology procedures are driving healthcare procurement of prescription-configured safety eyewear with vision correction integration.
- Precision Manufacturing Concentration:Germany's industrial laser deployment density sustains institutional demand for EN 207-certified products in automotive and electronics fabrication.
Market Restraints
- Polycarbonate Thermal Limitations:High-power continuous-wave environments exceeding polymer thermal loading thresholds force retention of heavier glass substrates.
- Certification Testing Gaps:Fiber laser and ultrafast source diversification outpaces legacy IEC 60825 test specifications, creating compliance uncertainty.
- Input Material Concentration:Specialized dye formulation capabilities for emerging ultrafast applications concentrate among limited in-house producers.
Strategic Opportunities
- Underpenetrated Research Segments:Narrow wavelength band calibration for laboratory environments offers premium positioning beyond industrial commoditization.
- Convergence of Prescription and Safety:Healthcare vision correction compliance intersecting with safety mandates creates dual-certified product white space.
- Distribution Network Leverage:Industrial safety distribution relationships provide channel control for institutional procurement consolidation.
Industry Challenges
- Optical Density Recertification Timelines:Emerging ultrafast applications force repeated EN 208 and ANSI Z136.3 testing cycles that compress product development windows.
- Multi-Wavelength Integration Complexity:Simultaneous protection across fiber laser, diode, and ultrafast spectra demands stacked filter architectures that increase weight and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Safety Glasses Market |
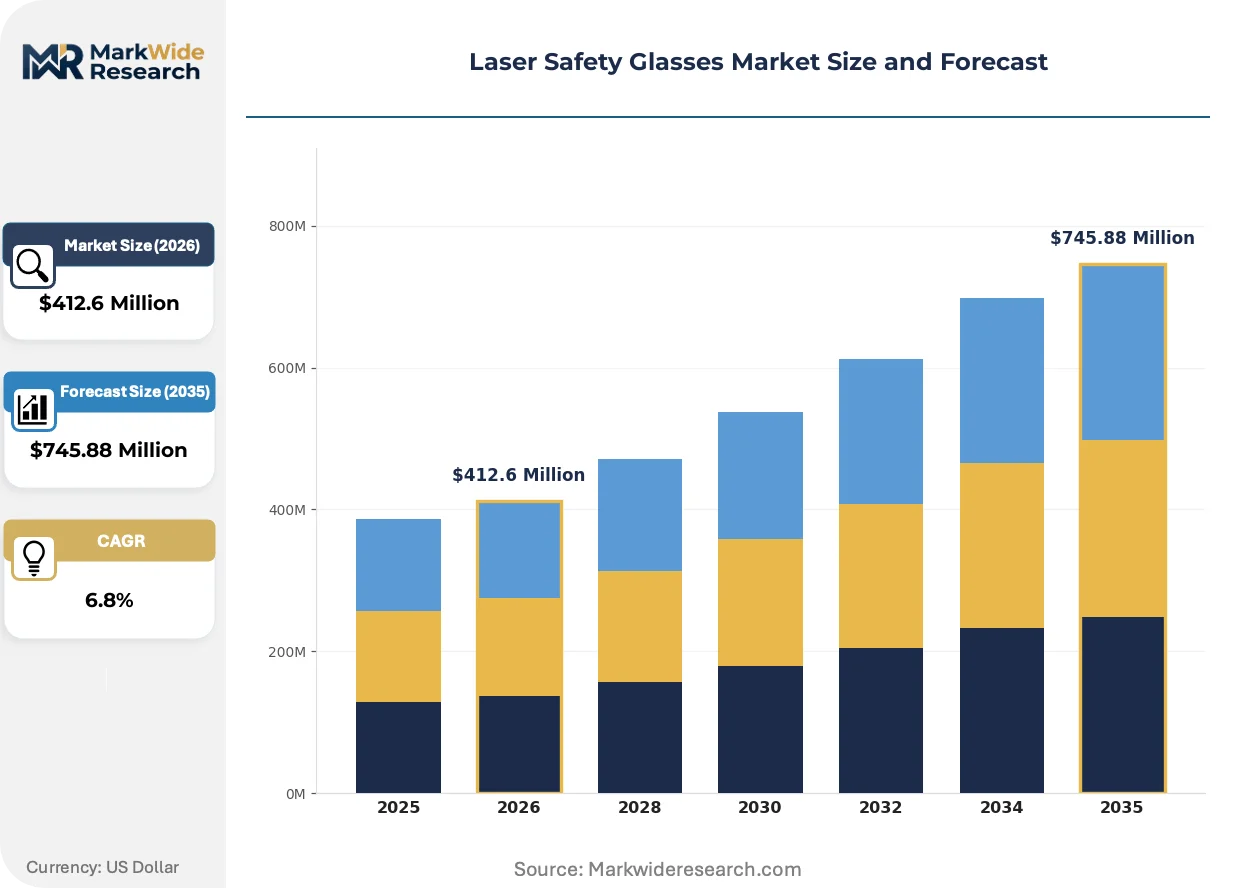
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Non-Prescription Glasses, Goggles, Face Shields End User: Manufacturing, Healthcare, Research Labs, Educational Institutions Material: Polycarbonate, Glass, Acrylic, Trivex Feature: Anti-Fog Coating, Scratch Resistance, Lightweight Design, UV Protection |
| Companies Covered | Honeywell International, uvex group, Thorlabs, Kentek Corporation, Laser Safety Industries, Phillips Safety Products, NoIR Laser Company, VS Eyewear, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Safety Glasses Market Shifts & Advancements
Active recalibration of protective specifications is reshaping how manufacturers formulate wavelength absorption and how buyers evaluate certification currency. The market is moving from universal protection claims toward source-specific optical density ratings.
Dielectric thin-film coating technology is collapsing the performance gap between polymer and glass substrates in high-power applications. Semiconductor fabrication facilities and battery cell manufacturing lines are adopting these coated polycarbonate systems at accelerated replacement cycles. The technology is collapsing the historical trade-off between impact resistance and thermal load capacity that previously forced substrate selection.
EN 207 and EN 208 framework revisions across Europe are tightening pulse duration testing protocols for ultrafast lasers. Industrial laser system manufacturers must now specify eyewear with explicit femtosecond and picosecond protection ratings. Medical aesthetic device distributors in France and aesthetic surgery centers in Germany are absorbing compliance costs through extended procurement contracts.
Institutional procurement consolidation is compressing vendor relationships toward integrated safety suppliers with in-house certification capabilities. Research laboratories and university physics departments are unbundling from specialized optical distributors toward broad-line industrial safety channels. This pattern is most visible in United States academic medical centers where consolidated purchasing agreements now specify ANSI Z136.1 compliance documentation as a mandatory bid requirement.
Laser Safety Glasses Market Segmentation
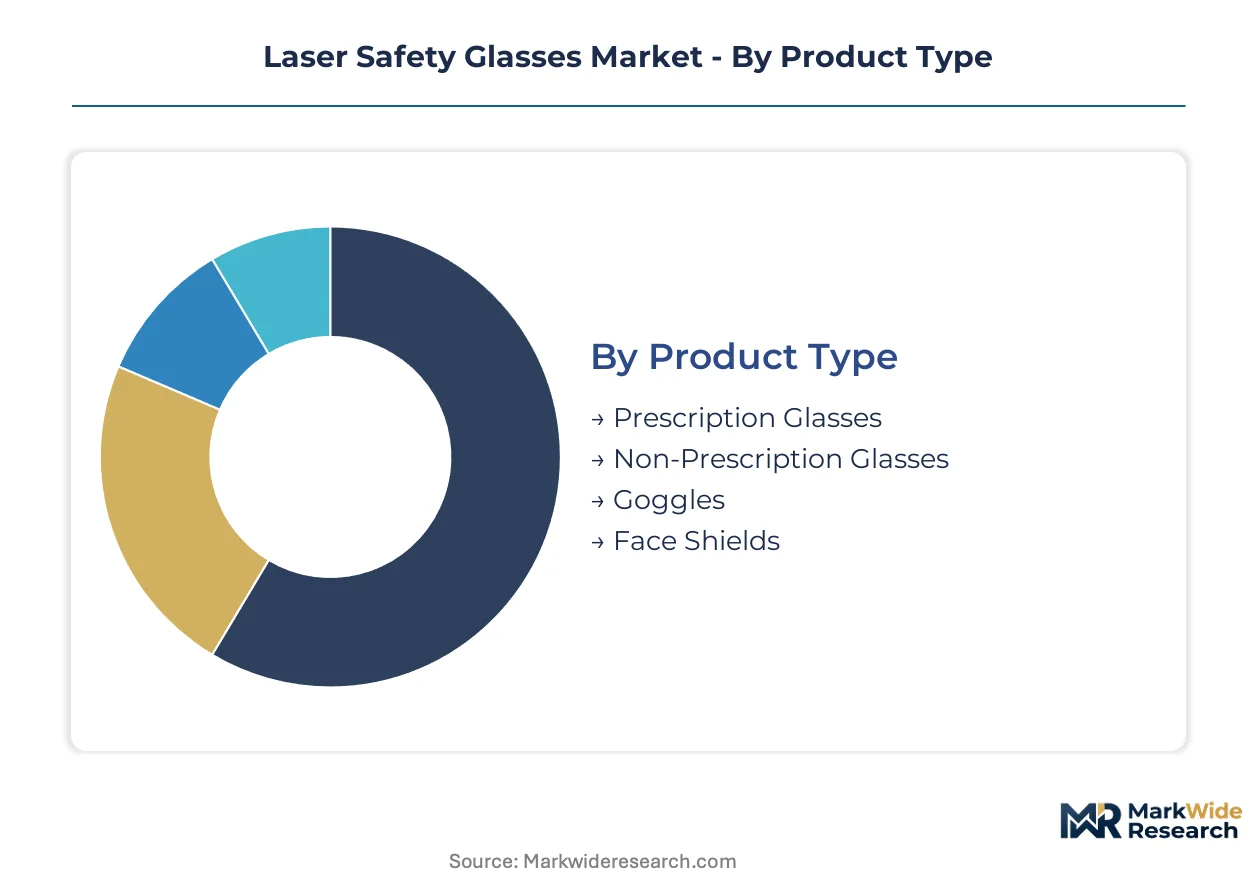
Laser safety eyewear segmentation reflects divergent technical requirements across power densities, exposure durations, and workplace compliance frameworks. Material selection and optical density specifications vary sharply between industrial metal cutting floors and dermatology suites. Procurement patterns in each segment respond to distinct certification mandates and replacement cycle economics.
Product Type:
Application context determines whether vision correction integration, peripheral sealing, or full facial coverage takes precedence in buyer specifications.
- Prescription Glasses:Custom-ground corrective lenses laminated with wavelength-specific absorptive dyes meet dual mandates for visual acuity and retinal protection. Healthcare facilities in Germany absorb premium positioning here as ophthalmology and dermatology staff require ANSI Z136.3-compliant vision correction during Class 4 laser procedures.
- Non-Prescription Glasses:Standardized polycarbonate platforms with fixed optical density ratings dominate volume procurement across manufacturing floors. Industrial safety distributors in the United States consolidate institutional purchasing around these SKUs where worker vision correction falls outside employer provision.
- Goggles:Periorbital sealing against backscattered radiation suits research environments with multi-axis beam paths. University physics departments specify these for ultrafast laser laboratories where diffuse reflections exceed ocular exposure limits.
- Face Shields:Extended coverage protects against direct beam exposure and chemical splash in battery cell manufacturing and semiconductor fabrication settings.
Non-prescription glasses command the established base. The steepest expansion runs through prescription-configured products.
End User:
Volume concentration and replacement frequency diverge across workplace safety enforcement intensity and capital equipment utilization rates.
- Manufacturing:Automotive fabrication lines and electronics assembly plants in Germany's precision manufacturing belt sustain dense procurement of EN 207-certified eyewear. High-power fiber laser deployment forces glass substrate retention despite weight penalties.
- Healthcare:Dermatology clinics and ophthalmology surgical centers drive prescription integration with ANSI Z136.3 compliance documentation. OSHA enforcement in the United States compels employer provision across outpatient surgical facilities.
- Research Labs:Narrow wavelength band calibration for femtosecond and picosecond sources commands premium positioning beyond industrial commoditization.
- Educational Institutions:Undergraduate physics laboratories and vocational training centers prioritize cost-efficient polycarbonate systems with multi-wavelength coverage.
Manufacturing anchors volume demand. Healthcare is climbing the fastest as aesthetic device proliferation accelerates procurement cycles.
Material:
Substrate selection trades impact resistance against thermal loading capacity and optical density stability under sustained irradiation.
- Polycarbonate:Dye-impregnated polymer molding delivers impact resistance and lighter weight for industrial floor deployment. Dielectric thin-film coatings are collapsing the performance gap with glass in high-power continuous-wave applications.
- Glass:Laminated filter substrates retain preference where thermal loading exceeds polymer limits in metal cutting and welding environments. German automotive laser facilities specify these for kilowatt-class fiber laser exposure.
- Acrylic:Lower-cost alternative for educational and light industrial settings with reduced optical density requirements.
- Trivex:Lightweight, high-abrasion-resistance polymer gaining traction in prescription configurations where comfort extends wear compliance.
Polycarbonate holds the volume base. Glass maintains defensive positioning in thermal-extreme applications.
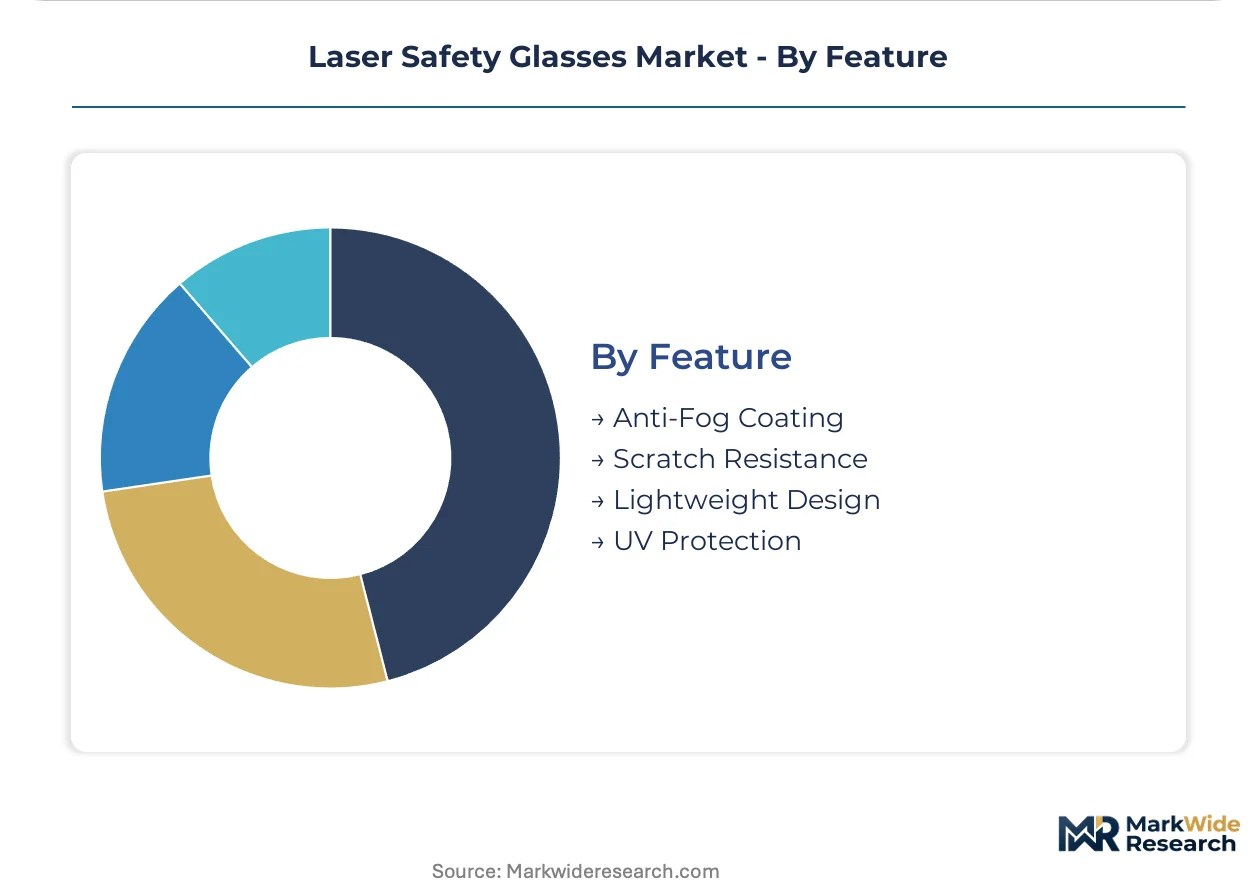
Feature:
Surface engineering and ergonomic attributes differentiate commoditized base products and support pricing stratification.
- Anti-Fog Coating:Hydrophilic surface treatments prevent vision occlusion in climate-controlled cleanrooms and surgical suites where temperature differentials induce condensation.
- Scratch Resistance:Hardcoat surface treatments extend service life in industrial environments where particulate exposure accelerates optical degradation. Manufacturing facilities in the United States specify these for extended replacement cycles.
- Lightweight Design:Reduced mass improves wearer compliance during extended procedures in healthcare and research settings.
- UV Protection:Broad-spectrum blocking addresses ancillary hazards in outdoor laser applications and dual-use industrial safety contexts.
Scratch resistance commands the established base. Anti-fog coating is gaining share fastest as cleanroom deployment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers export EN 207-certified eyewear to automotive fabrication lines across Central Europe, while United States industrial safety distributors channel ANSI Z136.1-compliant products into domestic manufacturing and healthcare facilities.
United States
OSHA workplace safety enforcement compels employer provision of certified protective equipment across Class 4 laser manufacturing floors. FDA laser product regulations govern medical aesthetic device compliance documentation. Detroit automotive laser welding facilities and Boston-area research universities sustain dense procurement of prescription-configured and non-prescription platforms.
Germany
Automotive fabrication lines and electronics assembly plants in Bavaria and Baden-Württemberg anchor institutional demand for EN 207-certified eyewear. The country's precision manufacturing belt sustains kilowatt-class fiber laser deployment that retains glass substrate preference. Stuttgart and Munich industrial clusters absorb compliance costs through extended procurement contracts with integrated safety suppliers.
China
Battery cell manufacturing and semiconductor fabrication facilities in the Yangtze River Delta and Pearl River Delta drive accelerated replacement cycles for dielectric thin-film coated polycarbonate systems. GB standards alignment with IEC 60825 frameworks shapes product marking requirements. Shenzhen and Shanghai cleanroom deployments specify anti-fog surface treatments for climate-controlled environments.
Japan
METI industrial safety guidelines and JIS standards calibration requirements shape procurement patterns for research-grade narrow wavelength band protection. Femtosecond laser laboratories in Tokyo and Osaka metropolitan areas command premium positioning beyond industrial commoditization. Osaka-based precision optics manufacturers supply dye-impregnated formulations to domestic physics departments.
United Kingdom
London academic medical centers specify ANSI Z136.1 compliance documentation as mandatory bid requirements under consolidated purchasing agreements. Midlands manufacturing clusters deploy multi-wavelength protection for fiber laser and ultrafast source portfolios. Cambridge and Oxford research laboratories unbundle from specialized optical distributors toward broad-line industrial safety channels.
Laser Safety Glasses Market Competitive Landscape
Channel-controlling players compete with product-specialist players across certification documentation and wavelength-specific calibration capabilities. The vendor base stratifies between integrated industrial safety suppliers with broad distribution networks and optical specialists with in-house dye formulation capabilities. Two dominant archetypes emerge: multi-line safety distributors leveraging institutional procurement relationships, and wavelength-specialist fabricators capturing premium positioning in research environments. Competitive moves center on certification protocol recalibration for ultrafast applications and backward integration into specialized absorptive dye production.
Among United States-based industrial safety conglomerates, Honeywell International occupies a position exemplifying channel-control archetypes through institutional procurement consolidation. Thorlabs and Kentek Corporation represent the specialist tier, with the former anchoring research-grade narrow wavelength positioning and the latter exemplifying in-house dye formulation capabilities for emerging ultrafast applications. These three entities collectively illustrate the competitive tension between scale-driven distribution leverage and technical specialization in wavelength-specific protection.
| Leading Market Players |
|---|
| Honeywell International |
| uvex group |
| Thorlabs |
| Kentek Corporation |
| Laser Safety Industries |
| Phillips Safety Products |
| NoIR Laser Company |
| VS Eyewear |
| Gentex Corporation |
| Others |
Supply & Pricing Matrix
Stuttgart's precision manufacturing cluster concentrates specialized dye formulation capabilities that feed downstream pricing power to EN 207-certified eyewear producers serving German automotive laser facilities. Capacity tightness at this node transmits directly to premium tiers where in-house absorptive dye production commands margin protection against commodity polycarbonate platforms.
Pricing Analysis
Next-generation dielectric thin-film coatings command substantial premiums over legacy dye-impregnated polycarbonate, while glass substrates retain defensive positioning in kilowatt-class fiber laser environments. Three-tier pricing structure across premium, standard, and economy levels separates prescription-configured healthcare products from industrial floor SKUs and educational institution bundles. Cost compression in standard-tier polycarbonate systems is intensifying because Chinese battery cell manufacturers are driving accelerated replacement cycles. Healthcare procurement committees show least price sensitivity where ANSI Z136.3 compliance documentation intersects with vision correction mandates.
Supply Chain Analysis
Export-control regimes limiting dual-use optical coating technologies constrain flows of specialized thin-film deposition equipment to Chinese semiconductor fabrication facilities. Manufacturing concentrates in Germany, the United States, and China, with Stuttgart and Munich clusters anchoring European EN 207 certification capacity. Raw material dependencies center on polycarbonate resin, rare-earth absorptive dyes, and precision coating substrates. Single-source vulnerability concentrates at specialized dye formulation houses serving ultrafast laser applications. Distribution runs through integrated industrial safety suppliers consolidating institutional procurement relationships in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as capital equipment replacement cycles in precision manufacturing reaccelerate following pandemic-deferred laser system deployments.
For Market Incumbents: Insulate certification currency through accelerated EN 208 and ANSI Z136.3 recertification investments ahead of ultrafast laser proliferation. Deepen backward integration into specialized absorptive dye production to defend margin position against emerging thin-film coating substitutes. Channel control through consolidated industrial safety distribution relationships provides defensive moats against research-grade specialists expanding downstream. For New Entrants and Emerging Players: Establish a beachhead in prescription-configured healthcare segments where dual-certified vision correction products face limited incumbent specialization. Target United States outpatient surgical facilities absorbing OSHA compliance costs through extended procurement contracts. Narrow wavelength band calibration for femtosecond laser laboratories offers premium positioning beyond industrial commoditization. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial safety conglomerates where laser eyewear represents non-core revenue pools with underexploited certification capabilities. Long-term viability hinges on wavelength-specific technical depth rather than distribution scale alone. Monitor EN 207 framework revision timelines as inflection indicators for recertification investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Formulation | In-house absorptive dye production secures supply for emerging ultrafast applications. |
| EN 208 Recertification Acceleration | Femtosecond and picosecond pulse duration testing captures premium positioning ahead of competitors. |
| Healthcare Distribution Partnership | Hospital system consolidated purchasing agreements specify ANSI Z136.1 compliance documentation. |
| Dielectric Thin-Film Coating Scale-Up | Semiconductor fabrication facilities adopt coated polycarbonate systems at accelerated replacement cycles. |
| Research-Grade Narrow Wavelength Calibration | University physics departments unbundle toward broad-line industrial safety channels. |
Research Methodology
Operator-level perspectives from laser safety officers, industrial procurement managers, biomedical engineers in hospital purchasing committees, and R&D directors at precision optics manufacturers anchored the qualitative base. Primary interview data combined with secondary validation from FDA laser product filings, OSHA enforcement records, IEC 60825 certification databases, and customs trade data for optical protective equipment. Bottom-up unit economics triangulated against top-down market sizing across material, product type, and end-user segmentation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with analytical frameworks modeling product type, material substrate, end-user industry, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against macro industrial laser deployment indicators. Forecast inputs incorporated fiber laser power scaling trajectories and ultrafast source proliferation rates in materials processing.
Macroeconomic conditions sit as an overlay; deviation in capital equipment investment cycles or precision manufacturing output would shift the trajectory. Forecasts reflect documented assumptions on certification protocol stability and dye formulation capacity expansion. Material shifts in EN 207/208 framework revision scope or export-control tightening on optical coating technologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Plastics in Personal Protective Equipment Market