
 Lightning Protection Technologies Market | 2026-2036
Lightning Protection Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Lightning Protection Technologies Market Foresight
Class-I surge protection with 25kA impulse current capacity is bifurcating the competitive landscape into premium-certified suppliers and commodity-grade providers. nVent Electric plc leverages its UL-listed manufacturing footprint across North America to sustain channel control in mission-critical data center contracts. DEHN SE + Co KG anchors its position through captive testing laboratories that validate products against IEC 61643-11 under extreme climatic conditions. Raycap competes aggressively in the telecommunication tower segment, where integrated remote monitoring capabilities now dominate procurement specifications.
Lightning protection technologies encompass engineered systems designed to intercept, conduct, and dissipate atmospheric electrical discharges safely to earth, typically incorporating air terminals with copper or aluminum alloy conductivity exceeding 58% IACS, down conductors, and low-impedance grounding electrodes bonded to structural steel. These installations primarily shield personnel, electronic equipment, and structural assets from thermal damage and electromagnetic interference caused by direct strikes or induced overvoltages. Rod systems and surge protectors together capture the dominant share of product-type revenue, with the latter pulling ahead as semiconductor-laden infrastructure proliferates across power generation and telecommunications applications. Passive systems retain volume leadership in mature markets, though hybrid configurations—combining early streamer emission with conventional Faraday cage shielding—are gaining traction in oil and gas facilities where ignition risk demands redundant protection layers.
NEC Article 250 and NFPA 780 in the United States, alongside IEC 62305 across European and Asia-Pacific jurisdictions, collectively mandate risk assessment protocols that determine protection level selection and installation geometry. These frameworks directly shape demand by classifying structures by lightning flash density, consequential loss tolerance, and occupancy type, thereby creating tiered compliance obligations that favor engineered solutions over basic hardware. Stakeholders must monitor evolving amendments to IEC 62561 series standards for component durability testing, as these will likely disqualify lower-tier suppliers unable to demonstrate corrosion resistance under accelerated salt-fog cycles.
Market Dynamics
The 5G infrastructure buildout across emerging economies is compressing installation cycles and forcing suppliers to certify surge protection systems for simultaneous lightning and electromagnetic pulse resilience.
Growth Catalysts
- NFPA 780 Risk Assessment Mandates:US commercial property insurers now require documented compliance for coverage renewal, pulling engineered solutions into retail and hospitality structures previously using basic hardware.
- India Utility-Scale Solar Expansion:Central Electricity Authority grounding standards for photovoltaic substations are mandating low-impedance electrode systems that exceed legacy agricultural specifications.
- Early Streamer Emission Advancement:Hybrid configurations combining ESE air terminals with conventional Faraday shielding are penetrating oil and gas facilities where ignition risk demands redundant protection architectures.
Market Restraints
- Copper Price Volatility:Down conductor material costs fluctuate with London Metal Exchange pricing, squeezing margin for installers locked into fixed-bid municipal contracts.
- Testing Laboratory Concentration:IEC 61643-11 validation capacity clusters in Germany and Switzerland, creating bottlenecks for Asian manufacturers seeking European market access.
- Grounding Electrode Lifespan Uncertainty:Accelerated salt-fog corrosion test protocols under IEC 62561 remain inconsistently applied, leaving asset owners without reliable 25-year performance benchmarks.
Strategic Opportunities
- Sub-Saharan Africa Telecom Infrastructure:Tower operators across Nigeria and Kenya lack integrated lightning monitoring, creating white space for remote diagnostic subscription services.
- Data Center Liquid Cooling Convergence:Surge protection vendors can bundle grounding systems with thermal management infrastructure, capturing electrical-mechanical package contracts.
- EU Green Deal Construction Standards:Embedded lightning protection in mass timber and cross-laminated timber buildings represents an unaddressed specification gap as sustainable materials penetrate commercial construction.
Industry Challenges
- Certified Lightning Protection Designer Shortage:NFPA 780-qualified engineers concentrate in coastal US markets, leaving interior states with installation quality variability.
- Legacy Electrical Infrastructure Bonding Complexity:1970s-era structural steel connections in industrial facilities often fail modern impedance testing, requiring costly remediation before new protection system activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightning Protection Technologies Market |
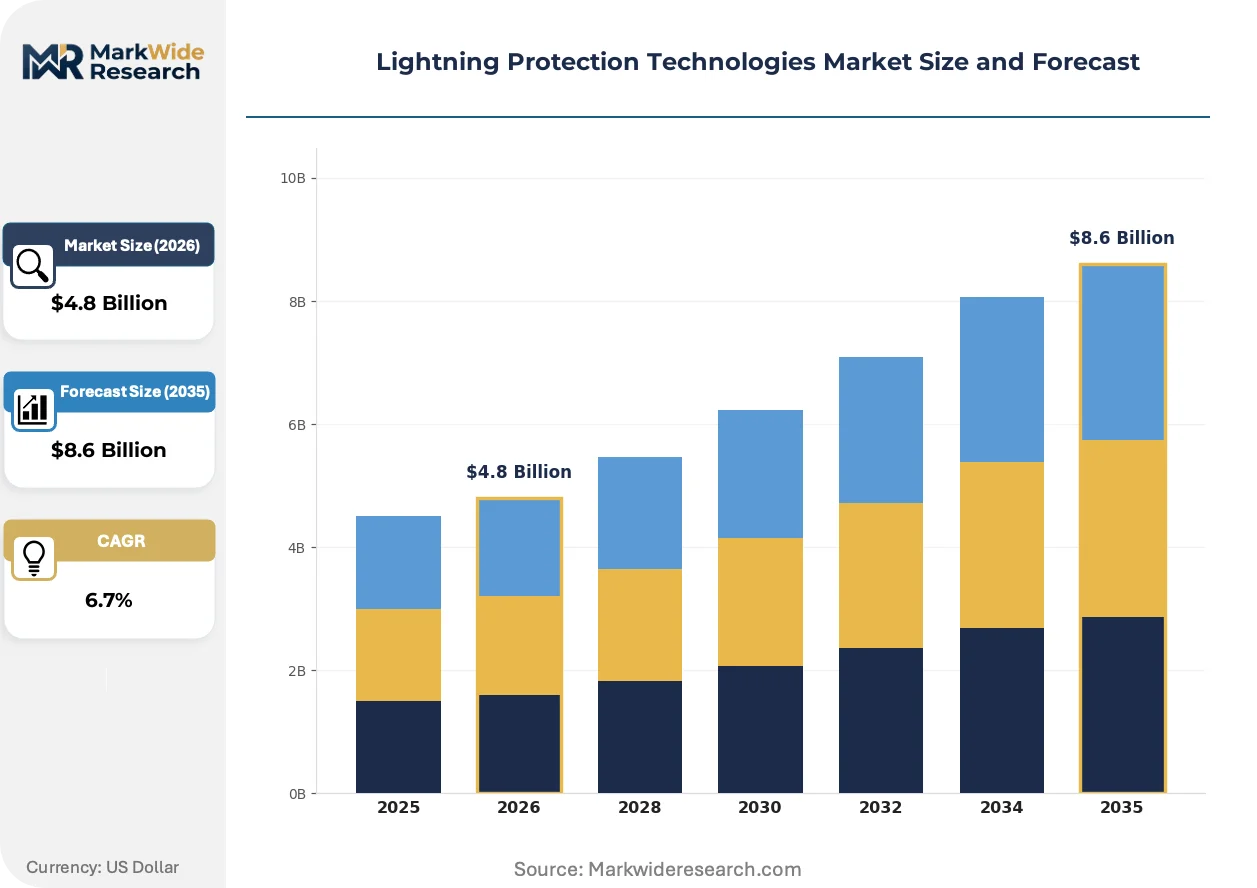
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod Systems, Shielding, Grounding Systems, Surge Protectors End User: Commercial Buildings, Residential Properties, Industrial Facilities, Telecommunication Towers Technology: Active Systems, Passive Systems, Hybrid Systems, Integrated Systems Application: Telecommunications, Power Generation, Transportation, Oil & Gas |
| Companies Covered | Pentair, Alltec Corporation, Raycap, Siemens AG, nVent Electric plc, Harger Lightning & Grounding, A.N. Wallis, INGESCO, DEHN SE + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightning Protection Technologies Market Shifts & Advancements
Remote monitoring capabilities are migrating from premium telecommunication tower installations into mid-market commercial and utility applications, compressing the service model from reactive maintenance to predictive intervention.
Photovoltaic-specific surge protection devices with 40kA impulse current capacity and integrated DC arc fault detection are supplanting generic AC-rated hardware in utility-scale solar farms. EPC contractors in India and Brazil now specify these combined-function units to reduce component count and commissioning complexity. The convergence is compressing supplier margins on standalone surge arrestors while rewarding vendors with captive semiconductor design teams.
REACH substance restrictions on cadmium and hexavalent chromium in grounding electrode coatings are forcing European manufacturers to reformulate corrosion protection layers. The industrial consequence is extended product qualification timelines as salt-fog and soil-resistivity testing protocols adapt to new material chemistries. German industrial facility operators are responding by consolidating procurement around suppliers with in-house metallurgical laboratories capable of accelerated validation.
Telecommunication tower operators are unbundling lightning protection maintenance from comprehensive site service contracts, creating direct procurement relationships with specialized surge protection vendors. TowerCos in Southeast Asia now issue standalone technical specifications for remote monitoring integration, bypassing general electrical contractors. This behavioral shift is most visible in Indonesia and the Philippines, where MTN and PLDT infrastructure subsidiaries have established vendor qualification programs separate from their primary EPC frameworks.
Lightning Protection Technologies Market Segmentation
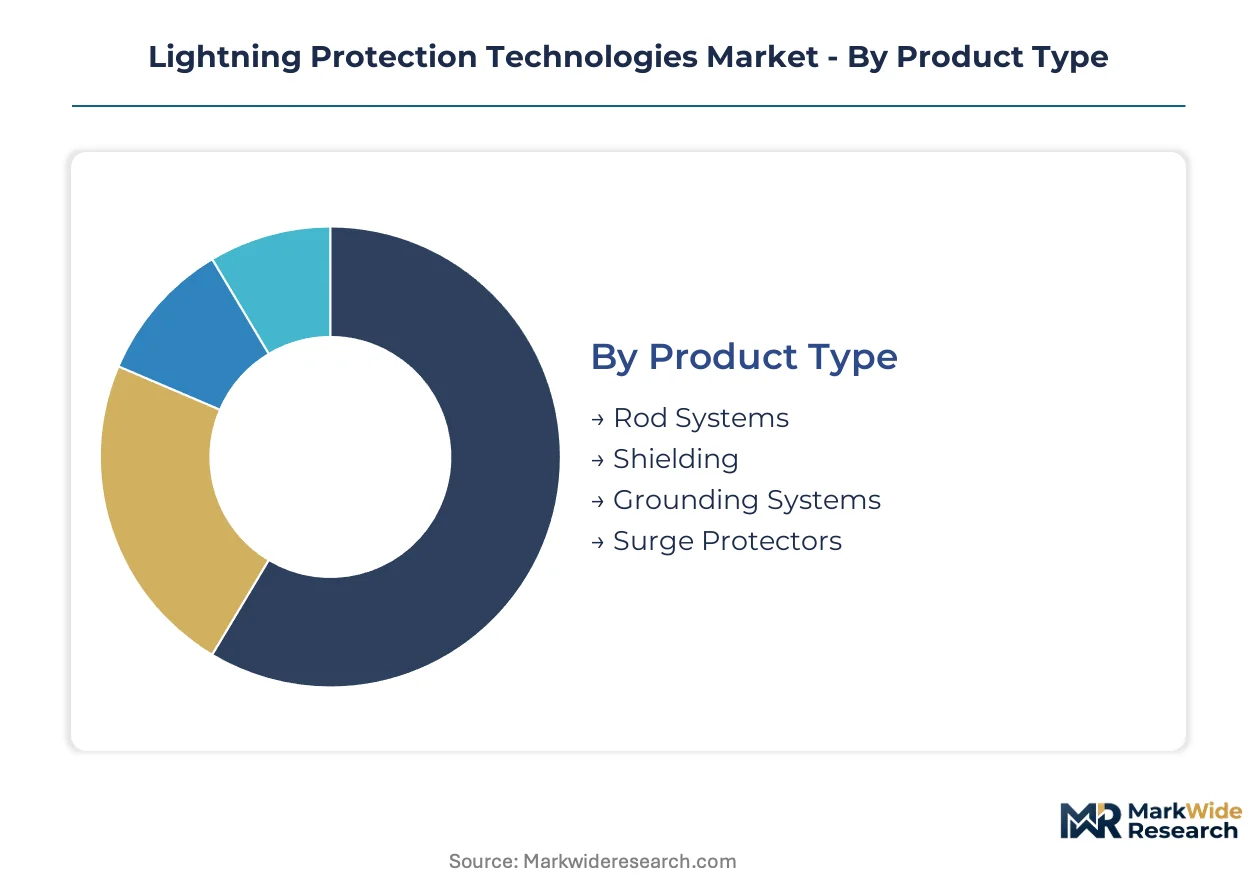
Segmentation in lightning protection technologies reveals how procurement patterns diverge between mature infrastructure markets and high-growth emerging economies. Each dimension—product, end user, technology, and application—carries distinct geographic signatures that shape supplier strategy and certification requirements.
Product Type:
Domestic manufacturing dominates rod systems and grounding electrodes due to copper transport economics, while surge protectors and shielding components flow through international supply chains concentrated in Germany and Switzerland.
- Rod Systems:Air terminals fabricated from copper or aluminum alloys exceeding 58% IACS conductivity form the physical interception layer. Indian utility-scale solar farms and Brazilian telecommunications infrastructure are pulling premium-grade rod systems with enhanced corrosion resistance for tropical deployment.
- Surge Protectors:Semiconductor-based devices with 25-40kA impulse current capacity protect downstream electronics from induced overvoltages. Data center operators in Virginia and Frankfurt specify these with integrated remote monitoring, displacing basic hardware in mission-critical contracts.
- Shielding:Faraday cage architectures using conductive mesh or structural steel bonding attenuate electromagnetic interference. Oil and gas facilities in the North Sea and Gulf of Mexico deploy redundant shielding layers where ignition risk tolerates zero failure.
- Grounding Systems:Low-impedance electrode networks bonded to structural steel dissipate strike energy safely. CEA grounding standards for Indian photovoltaic substations are mandating specifications that exceed legacy agricultural installations.
Rod systems command the established base. The steepest expansion runs through surge protectors.
End User:
Cost tier separation is pronounced: industrial and telecom buyers absorb premium certified systems, while residential procurement concentrates in economy-grade hardware with minimal engineering oversight.
- Telecommunication Towers:5G infrastructure buildouts across Nigeria, Kenya, and Indonesia require simultaneous lightning and electromagnetic pulse resilience. TowerCos now unbundle lightning protection from comprehensive site contracts, creating direct vendor relationships with specialized surge protection suppliers.
- Industrial Facilities:Petrochemical complexes, semiconductor fabs, and pharmaceutical plants demand redundant protection architectures. REACH substance restrictions on cadmium and hexavalent chromium in electrode coatings are forcing European operators to consolidate procurement around suppliers with in-house metallurgical laboratories.
- Commercial Buildings:NFPA 780 risk assessment mandates now pull engineered solutions into retail and hospitality structures across Florida and Texas. US commercial property insurers require documented compliance for coverage renewal.
- Residential Properties:Basic rod-and-conductor installations predominate, with procurement fragmented across local electrical contractors. Copper price volatility squeezes margins for installers locked into fixed-bid municipal contracts.
Industrial facilities command the established base. The steepest expansion runs through telecommunication towers.
Technology:
Application context determines technology selection: passive systems retain volume leadership in conventional construction, while hybrid and integrated configurations penetrate high-consequence environments.
- Passive Systems:Conventional Franklin rod and Faraday cage architectures without active ionization components. These retain dominance in mature North American and European construction markets where installation codes are deeply embedded.
- Hybrid Systems:Configurations combining early streamer emission air terminals with conventional shielding. Oil and gas facilities in the North Sea and Middle East deploy these where ignition risk demands redundant protection layers.
- Active Systems:Early streamer emission terminals using ionization technology to extend protection radius. Brazilian and Saudi Arabian infrastructure projects specify these for large-footprint installations requiring reduced conductor runs.
- Integrated Systems:Lightning protection bundled with surge protection, grounding, and remote monitoring in unified architectures. Indonesian and Philippine TowerCos issue standalone technical specifications for these, bypassing general electrical contractors.
Passive systems command the established base. The steepest expansion runs through integrated systems.
Application:
Volume concentrates in power generation and telecommunications, while margin accrues to oil and gas and transportation applications where failure consequences carry catastrophic liability.
- Telecommunications:5G infrastructure across emerging economies compresses installation cycles and forces certification for simultaneous lightning and electromagnetic pulse resilience. Tower operators in Sub-Saharan Africa lack integrated monitoring, creating white space for remote diagnostic subscription services.
- Power Generation:Utility-scale solar farms in India and Brazil specify photovoltaic-specific surge protection devices with 40kA impulse current capacity and integrated DC arc fault detection. EPC contractors favor combined-function units to reduce component count.
- Oil & Gas:Offshore platforms, refineries, and pipeline terminals demand redundant protection with documented ignition risk mitigation. IEC 62305 risk assessment protocols classify these structures by consequential loss tolerance, creating tiered compliance obligations.
- Transportation:Airports, rail electrification, and electric vehicle charging infrastructure require protection against direct strikes and induced overvoltages. FAA and national aviation regulators mandate specific protection geometries for airside facilities.
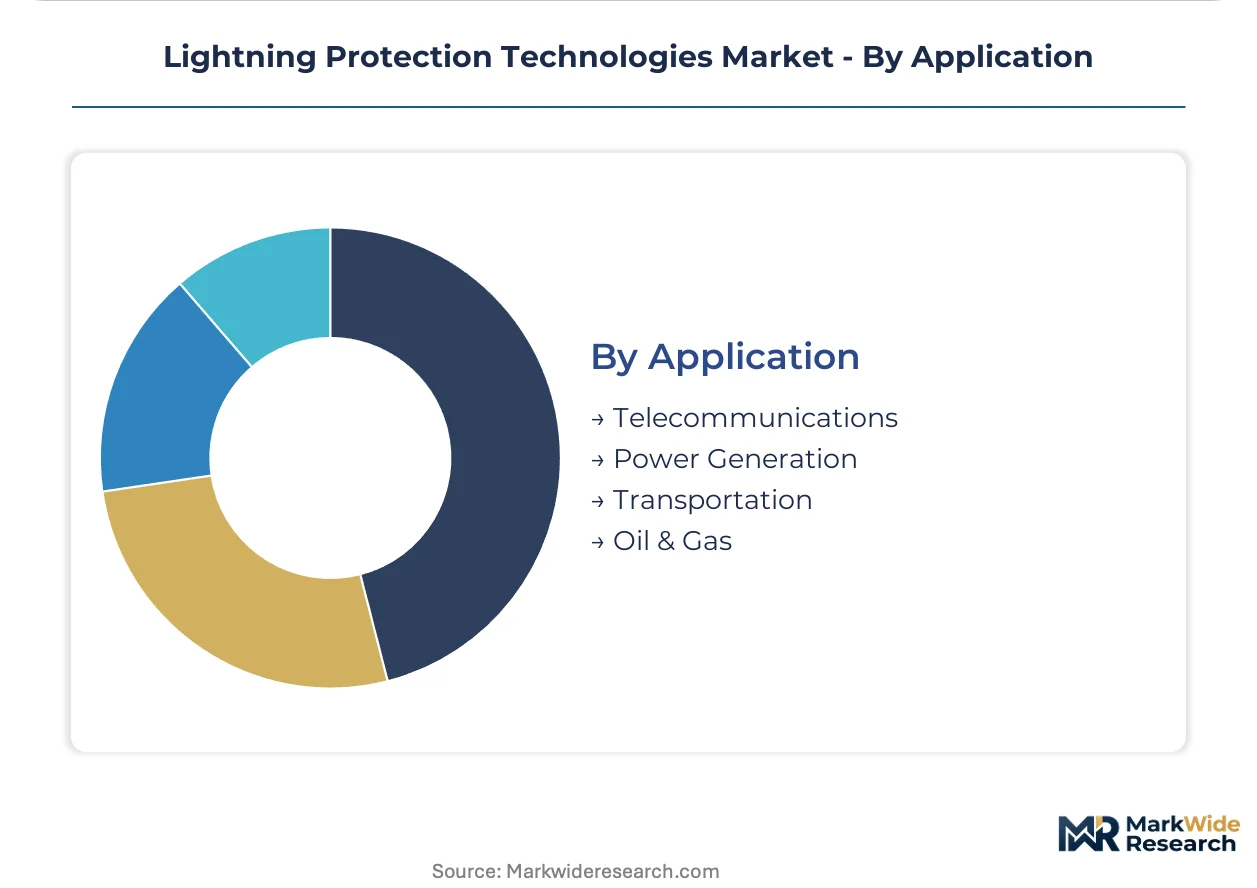
Power generation commands the established base. The steepest expansion runs through telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for surge protection components concentrates in Germany and Switzerland, while copper rod systems flow through domestic supply chains in India and Brazil. Export competitiveness clusters around IEC-certified manufacturing hubs serving emerging economy infrastructure buildouts.
United States
Data center construction in Virginia and Texas drives demand for UL-listed surge protection with remote monitoring integration. NFPA 780 risk assessment mandates now condition commercial property insurance renewal on documented compliance. Florida and coastal Gulf states concentrate installation activity where lightning flash density exceeds national averages.
Germany
Industrial facility operators consolidate procurement around suppliers with captive metallurgical laboratories following REACH substance restrictions on electrode coatings. IEC 61643-11 validation capacity clusters in German and Swiss testing facilities, creating bottlenecks for Asian market access. Bavaria and North Rhine-Westphalia anchor manufacturing of certified protection components for European distribution.
India
Utility-scale solar farms in Rajasthan and Gujarat accelerate procurement of photovoltaic-specific surge protection devices under CEA grounding standards. Smart grid investments in Maharashtra and Karnataka pull advanced grounding systems exceeding legacy agricultural specifications. Domestic copper rod fabrication serves regional infrastructure buildouts.
Brazil
Telecommunications infrastructure expansion across São Paulo and Rio de Janeiro specifies early streamer emission terminals for large-footprint installations. EPC contractors favor combined-function surge protection units to reduce component count in photovoltaic substations. Local manufacturing of rod systems avoids copper import logistics.
Saudi Arabia
Oil and gas facilities in the Eastern Province deploy hybrid protection configurations where ignition risk demands redundant architectures. Megaproject construction in NEOM and Riyadh specifies integrated lightning and surge protection systems. IEC 62305 risk assessment protocols classify structures by consequential loss tolerance.
Lightning Protection Technologies Market Competitive Landscape
Concentration sits with diversified electrical infrastructure conglomerates and specialized surge protection engineering houses. The vendor base separates into three tiers: premium-certified suppliers with captive testing laboratories, mid-scale regional fabricators serving domestic construction markets, and commodity-grade providers competing on copper conductor pricing. Strategic moves center on certification portfolio expansion into photovoltaic and telecommunications verticals, plus backward integration into semiconductor-based surge protection device design.
Among diversified electrical component manufacturers, Siemens AG and nVent Electric plc exemplify scale-driven positioning with broad certification coverage across IEC and NFPA jurisdictions. DEHN SE + Co KG occupies a specialized tier as a German-based engineering house with captive validation capabilities. Raycap represents the telecommunications-focused archetype, while Pentair anchors diversified infrastructure exposure. These named entities illustrate how competitive positioning stratifies between comprehensive electrical platforms and targeted vertical specialists.
| Leading Market Players |
|---|
| Pentair |
| Alltec Corporation |
| Raycap |
| Siemens AG |
| nVent Electric plc |
| Harger Lightning & Grounding |
| A.N. Wallis |
| INGESCO |
| DEHN SE + Co KG |
| Others |
Supply & Pricing Matrix
Project-based fixed-bid contracts for municipal and utility-scale installations lock in copper conductor pricing at award, exposing installers to London Metal Exchange volatility while securing supply access through nominated distributors. This structure concentrates price risk on installation contractors while awarding procurement stability to asset owners in India and Brazil.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with UL-listed and IEC-certified systems commanding substantial premiums over commodity-grade hardware. Price differentiation rests on certification grade and captive testing laboratory access, with German and Swiss suppliers extracting premiums for accelerated validation services. Cost compression in the economy tier is intensifying because copper price volatility squeezes margins on fixed-bid contracts. Residential electrical contractors exhibit highest price sensitivity, while data center operators absorb premium pricing for integrated remote monitoring capabilities.
Supply Chain Analysis
Germany and Switzerland anchor semiconductor-based surge protection device fabrication and IEC 61643-11 validation capacity, while India and Brazil host domestic copper rod system manufacturing for regional infrastructure buildouts. The supply chain draws from copper cathode, semiconductor components, and specialized electrode coatings as critical inputs. Single-source vulnerability concentrates in German testing laboratory capacity, creating bottlenecks for Asian manufacturers seeking European market access. Distribution runs through electrical distributors and direct procurement channels to TowerCos and EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as 5G infrastructure buildouts across emerging economies compress installation cycles and force certification upgrades.
For Market Incumbents: Shield market position by deepening backward integration into semiconductor-based surge protection device design to capture photovoltaic and telecommunications verticals. Consolidate procurement relationships with TowerCos in Southeast Asia before specialized vendors establish direct channels. Certification investment in IEC 62561 corrosion resistance protocols represents the critical defensive lever against REACH-driven supplier disqualification. For New Entrants and Emerging Players: Remote diagnostic subscription services for Sub-Saharan African telecom towers represent the most penetrable white space, as Nigerian and Kenyan operators lack integrated lightning monitoring capabilities. Target photovoltaic-specific surge protection with combined DC arc fault detection for Indian utility-scale solar farms, where EPC contractors favor reduced component count. A go-to-market angle bundling grounding systems with data center thermal management infrastructure captures electrical-mechanical package contracts. For Investors and Strategic Acquirers: Capital is best deployed toward specialized surge protection engineering houses with captive metallurgical laboratories capable of accelerated salt-fog validation under evolving REACH substance restrictions. Long-term viability over the coming decade hinges on certification portfolio breadth across IEC and NFPA jurisdictions. The signal to watch is unbundling of lightning protection maintenance from comprehensive site service contracts, which accelerates direct vendor relationships and displaces general electrical contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Design | Captures margin from photovoltaic-specific surge protection devices with integrated DC arc fault detection. |
| Captive Testing Laboratory Investment | Validates products against IEC 61643-11 under extreme climatic conditions, accelerating European market access. |
| Remote Monitoring Platform Development | Addresses unmet demand from Indonesian and Philippine TowerCos issuing standalone technical specifications. |
| REACH-Compliant Coating Reformulation | Prevents disqualification from European procurement as substance restrictions tighten on cadmium and hexavalent chromium. |
| Direct TowerCo Relationship Building | Bypasses general electrical contractors as MTN and PLDT infrastructure subsidiaries establish separate vendor qualification programs. |
Research Methodology
A standing panel of EPC contractors, TowerCo procurement directors, electrical distributors, and certified lightning protection designers provided ongoing calibration across primary interviews and secondary validation. The analysis combined field intelligence from installation contractors in Florida, Texas, and coastal Gulf states with regulatory filings from IEC and NFPA standard-setting bodies, customs and trade data on copper conductor flows, and SEC disclosures from diversified electrical infrastructure conglomerates. Bottom-up project pipeline assessment and top-down market sizing triangulated volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling by product type, end user, technology, and application. The framework incorporated lightning flash density mapping, 5G infrastructure deployment schedules, and utility-scale solar farm commissioning timelines as industry-specific forecast inputs. CAGRs were derived from installed base growth rates and replacement cycle analysis.
Forecasts assume regulatory continuity in IEC 62305 and NFPA 780 compliance frameworks; material policy shifts would require re-modeling. Specific risks include copper price volatility, testing laboratory capacity constraints, and accelerated salt-fog protocol amendments under IEC 62561. Recalibration cycles align with material shifts in 5G deployment velocity, solar farm commissioning rates, and REACH substance restriction timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market