
 Aviation Software Market | 2026-2036
Aviation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Software Market Analysis
Cloud-native architectures are restructuring aviation software economics as on-premise legacy stacks give way to scalable, API-driven platforms. Collins Aerospace dominates integrated flight operations suites through its embedded avionics-to-ground data links. Honeywell leverages predictive maintenance algorithms to anchor aftermarket service contracts. Palantir differentiates through federated data integration across airline, OEM, and regulator silos.
Aviation software encompasses mission-critical applications governing flight planning, crew scheduling, maintenance tracking, and passenger reservation workflows, typically operating on real-time data feeds from aircraft sensors, ground radar, and weather satellites. Flight Operations and Maintenance Management segments lead current revenue pools where ARINC 633 and ATA Spec 2000 protocols govern data interchange standards. Cloud-Based deployment is displacing legacy mainframe installations fastest among low-cost carriers seeking OpEx flexibility, while Hybrid architectures persist at full-service network airlines managing split regulatory jurisdictions.
FAA airworthiness directives and EASA Part-M maintenance regulations mandate digital record retention and audit trails, forcing Maintenance Management software upgrades across Part 121 and Part 145 operators. China's CAAC interoperability standards and GB/T data localization requirements shape vendor market access for foreign platform providers. Stakeholders must weigh sovereign data requirements against cross-fleet analytics value when selecting deployment architectures.
Market Dynamics
Cloud-native migration is forcing aviation software vendors to rebuild core platforms around microservices architectures, abandoning monolithic codebases that anchored the industry for three decades. This structural shift compresses development cycles while exposing legacy integrators to displacement from API-first competitors.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for predictive maintenance data retention are compelling Part 121 carriers to upgrade Maintenance Management platforms, creating immediate replacement demand across US-flagged fleets.
- ATA Spec 2000:The aviation industry's standardized data exchange protocol is harmonizing MRO documentation workflows, reducing integration friction between airline operators and component suppliers.
- China's Air Traffic Modernization:CAAC investments in smart airport infrastructure are accelerating procurement of flight operations suites at hub airports in Beijing, Shanghai, and Guangzhou.
Market Restraints
- Aviation-Grade Certification Costs:DO-178C software assurance compliance adds 18-24 months to development timelines, erecting capital barriers for new entrants targeting safety-critical applications.
- Specialized Talent Scarcity:The shallow labor pool for embedded systems engineers with ARINC protocol expertise concentrates development capacity at established vendors.
- Hybrid Architecture Lock-In:Full-service network airlines' split regulatory jurisdictions prevent pure cloud migration, fragmenting addressable market for SaaS-native providers.
Strategic Opportunities
- Sustainability Analytics:EU Green Deal emissions tracking requirements are opening white space for fuel optimization algorithms that integrate flight planning with carbon reporting dashboards.
- Urban Air Mobility:eVTOL manufacturers represent an underpenetrated customer segment requiring lightweight, real-time mission management software distinct from traditional airline stacks.
- Federated Data Architectures:Convergence of edge computing and 5G aeronautical connectivity is enabling distributed analytics that process sensor data aboard aircraft before ground transmission.
Industry Challenges
- Legacy System Integration:Airlines operating 1990s-era mainframe reservation systems face API mapping complexity when connecting to modern crew scheduling modules, inflating implementation costs.
- Cybersecurity Certification Lag:DO-326A airworthiness security process timelines have not compressed to match agile development cycles, creating deployment bottlenecks for threat-hardened platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Software Market |
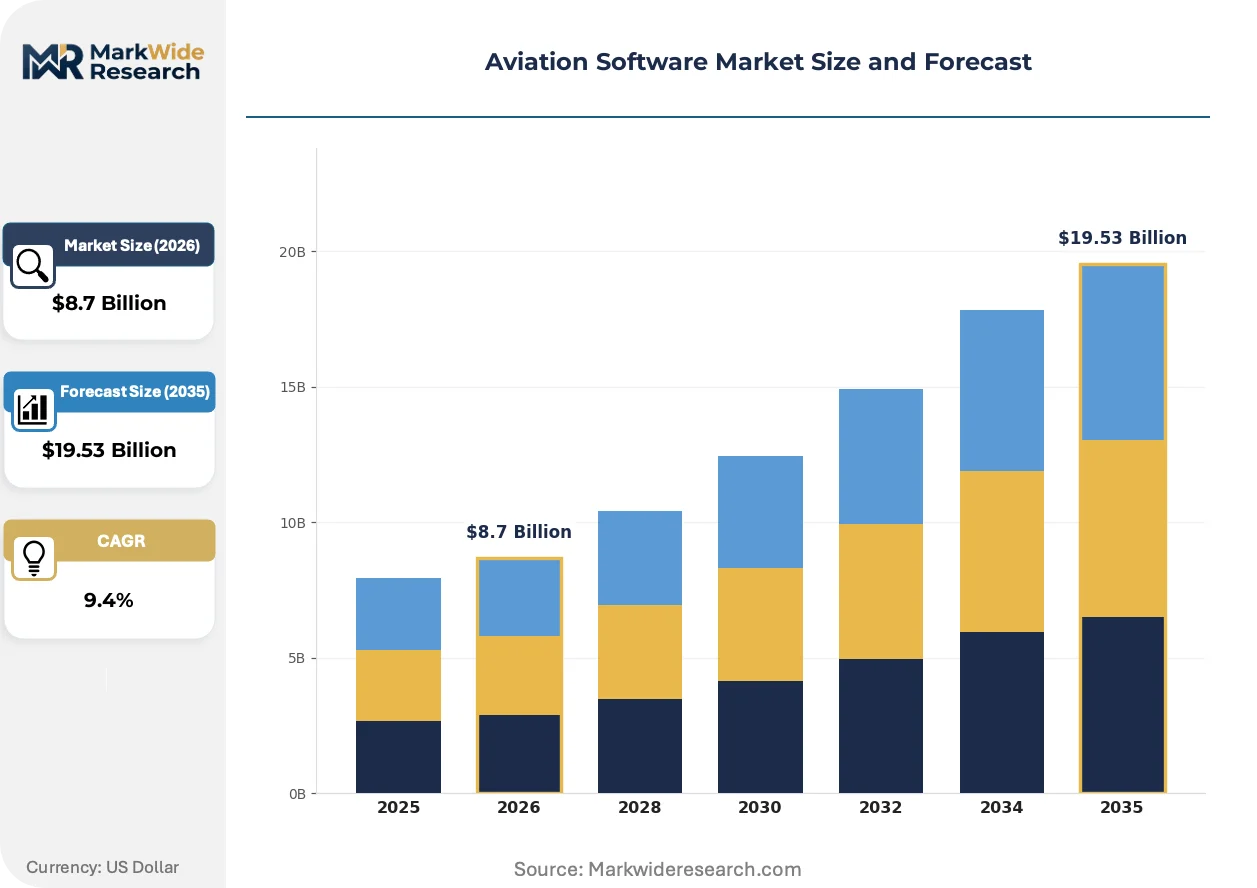
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Operations, Maintenance Management, Crew Management, Reservation Systems Deployment: On-Premise, Cloud-Based, Hybrid, Legacy Systems End User: Airlines, Aircraft Manufacturers, Ground Handlers, Maintenance Providers Application: Flight Planning, Safety Management, Resource Management, Training Solutions |
| Companies Covered | Swiss-AS, Ramco Aviation, IBM, Palantir, Collins Aerospace, Honeywell, Trax, aiOla, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Software Market Emerging Trajectories
Artificial intelligence is penetrating aviation software workflows at the operational layer, moving from decision-support tools to autonomous execution systems that reduce human intervention in routine processes. This transformation is restructuring vendor competitive advantage around algorithmic performance rather than feature breadth.
Machine learning algorithms trained on engine performance telemetry are automating anomaly detection in predictive maintenance workflows, flagging component degradation patterns before threshold breaches trigger manual alerts. Low-cost carriers with younger, sensor-dense fleets are deploying these systems fastest, compressing unscheduled removal rates and extending on-wing time for high-value rotating assemblies. The structural consequence is a shift in MRO contract economics toward guaranteed availability pricing rather than labor-hour billing.
EASA's Part-IS cybersecurity regulation is mandating security management systems for all EU-registered operators above specified mass thresholds, forcing software vendors to embed threat monitoring and incident response capabilities directly into maintenance and flight operations platforms. The industrial consequence is a bifurcation between vendors with native security architectures and those bolting on compliance modules. Maintenance Management suites serving European flag carriers face the steepest retrofit requirements, with implementation deadlines compressing procurement cycles.
Airlines are consolidating vendor relationships to reduce integration tax, favoring platform providers with unified data models spanning flight operations, crew management, and maintenance tracking. The segment being disrupted is the point-solution middleware layer that historically translated between siloed systems. This concentration is most visible among US network carriers restructuring procurement around single-stack commitments that bundle multiple functional domains under master service agreements with penalty clauses for data fragmentation.
Aviation Software Market Segmentation
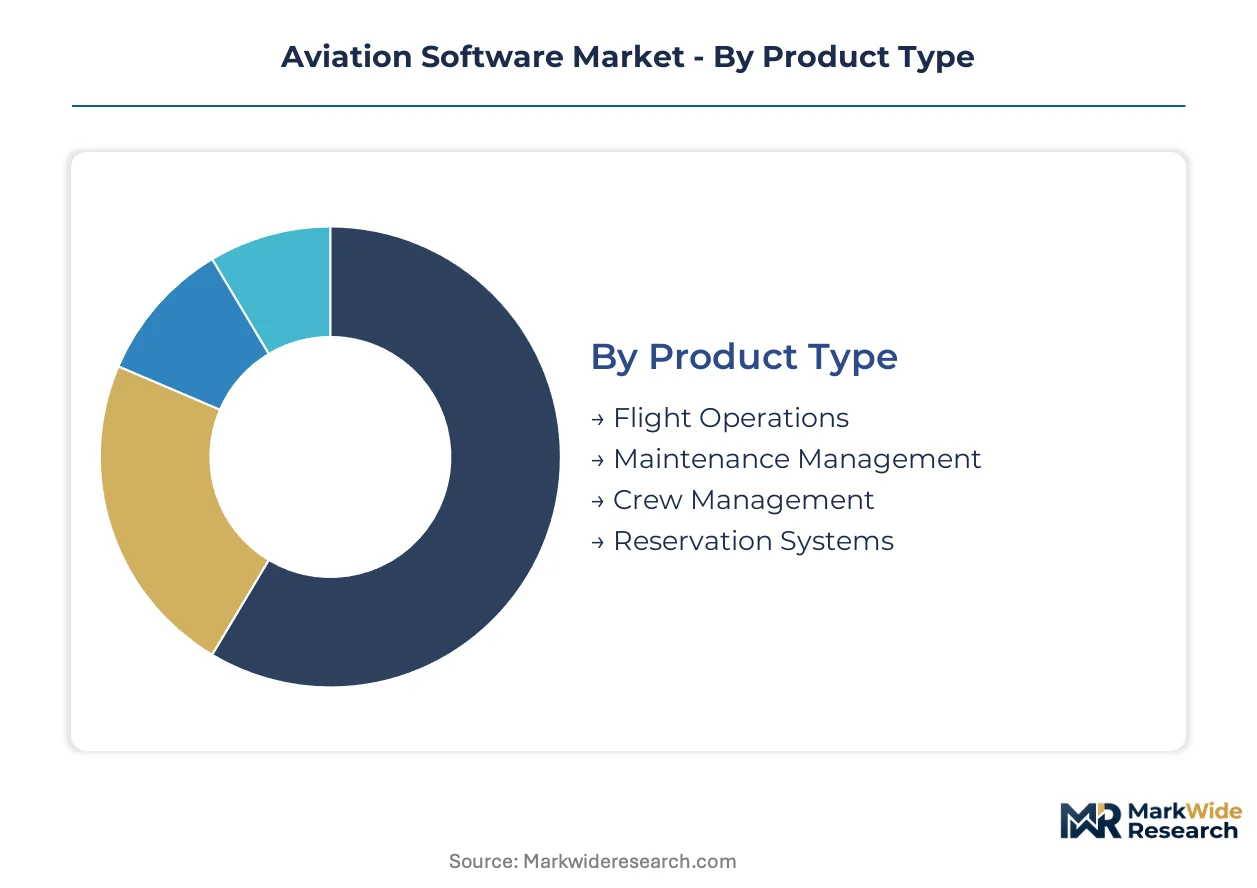
Aviation software procurement concentrates around operational-criticality tiers, with flight operations and maintenance management commanding premium deployment budgets due to FAA and EASA airworthiness mandates. Segmentation reveals how regulatory jurisdiction, fleet age profiles, and data sovereignty requirements fragment vendor addressable markets across deployment architectures and end-user categories.
Product Type:
Supply concentration in integrated platform providers favors vendors bundling multiple functional domains under unified data models, displacing point-solution specialists.
- Flight Operations:Real-time mission management platforms governing dispatch, fuel optimization, and route planning through ARINC 633 data links. United States network carriers and Chinese hub operators drive replacement demand as legacy mainframe systems reach end-of-life.
- Maintenance Management:Predictive analytics platforms processing sensor telemetry for component lifecycle forecasting and digital record retention per ATA Spec 2000 protocols. Low-cost carriers with younger, sensor-dense fleets deploy these systems fastest, compressing unscheduled removal rates.
- Crew Management:Scheduling and qualification tracking modules integrating fatigue risk management with regulatory duty-time limits.
- Reservation Systems:Passenger booking engines and revenue management platforms, historically anchored on 1990s-era mainframe architectures.
Maintenance Management absorbs the bulk of installed capacity; Flight Operations is expanding most quickly.
Deployment:
Cost tier differentiation separates capital-intensive on-premise installations from OpEx-flexible cloud alternatives, with hybrid architectures commanding intermediate pricing.
- Cloud-Based:Microservices-native platforms delivered via API-driven SaaS models, enabling rapid scaling without infrastructure capital. Low-cost carriers across Germany, the United States, and India prioritize this tier for fleet expansion flexibility.
- Hybrid:Split architectures maintaining sensitive operational data on-premise while leveraging cloud analytics for non-critical workloads. Full-service network airlines operating across multiple regulatory jurisdictions default to this model.
- On-Premise:Dedicated infrastructure installations retaining full data control for sovereign compliance requirements.
- Legacy Systems:Monolithic mainframe and client-server installations reaching end-of-support, driving replacement cycles.
Hybrid deployments retain the largest installed base; Cloud-Based architectures are climbing the fastest.
End User:
Customer type fragmentation creates divergent procurement patterns, with airlines prioritizing integrated suites while maintenance providers seek specialized MRO documentation tools.
- Airlines:Full-service and low-cost carriers procuring unified platforms spanning flight operations, crew management, and maintenance tracking. Consolidation of vendor relationships reduces integration tax and data fragmentation penalties.
- Maintenance Providers:Part 145 repair stations and independent MROs requiring ATA Spec 2000-compliant documentation systems for component traceability and airworthiness certification.
- Aircraft Manufacturers:OEMs embedding software platforms into new aircraft deliveries and aftermarket service offerings.
- Ground Handlers:Airport service providers managing turnaround coordination, baggage tracking, and gate allocation workflows.
Airlines command the dominant procurement volume; Maintenance Providers are gaining share fastest.
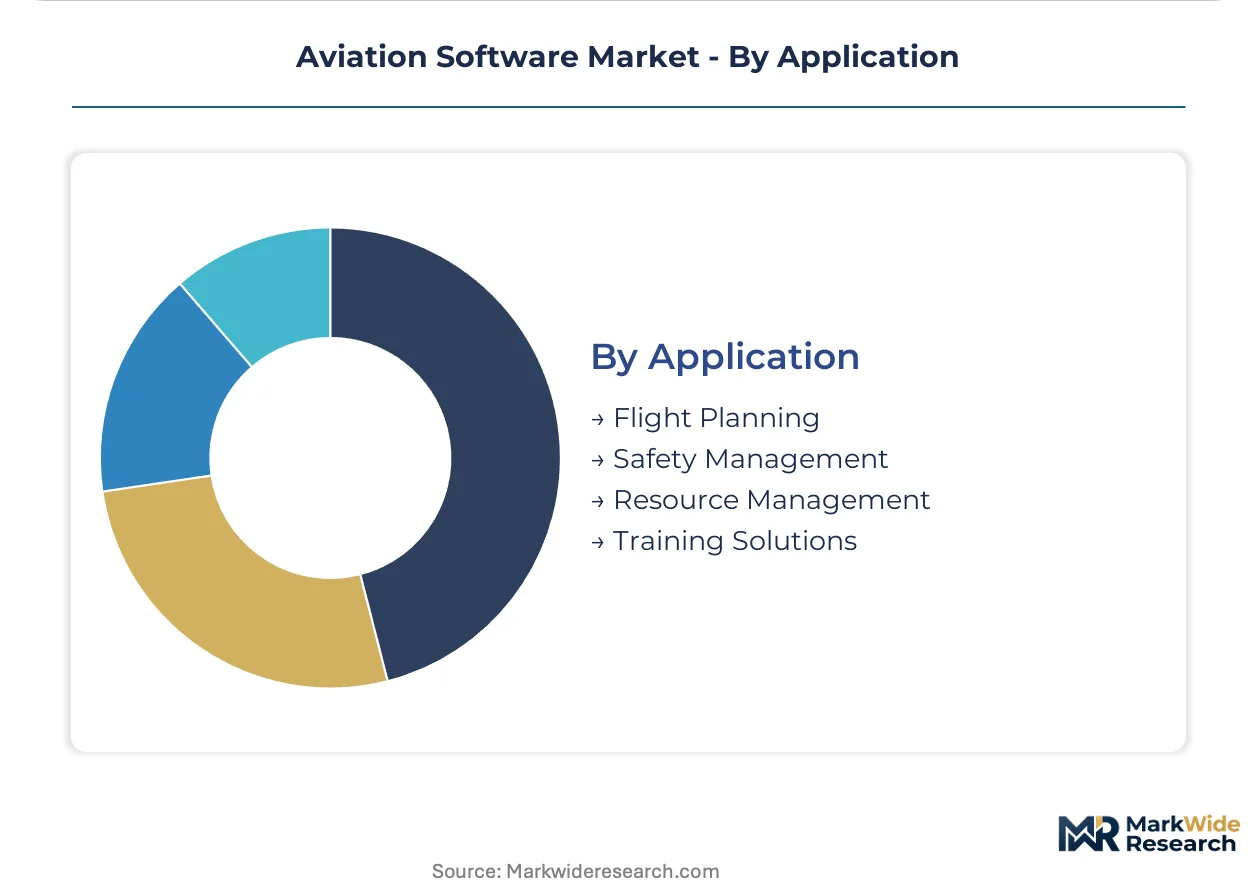
Application:
Maturity gradients separate established flight planning markets from emerging safety management automation, with regulatory deadlines accelerating procurement in newer categories.
- Safety Management:Predictive risk analytics platforms automating incident reporting, hazard identification, and regulatory submission workflows. EASA Part-IS cybersecurity mandates and FAA safety management system requirements are compressing implementation timelines across European and US operators.
- Flight Planning:Route optimization and fuel calculation engines integrating real-time weather, NOTAM, and airspace restriction data. Established market with replacement demand driven by sustainability reporting requirements.
- Resource Management:Asset allocation and inventory optimization tools for spare parts, tooling, and ground equipment.
- Training Solutions:Computer-based instruction and simulator management platforms for pilot and maintenance technician qualification.
Flight Planning retains the deepest installed base; Safety Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerospace zones in Toulouse, Hamburg, and Seattle concentrate software procurement budgets as airlines and MROs cluster near OEM engineering centers. These tax-advantaged districts accelerate platform deployment timelines by 12-18 months through co-located certification support.
United States
FAA Airworthiness Directives mandating predictive maintenance data retention are forcing Part 121 carriers to replace legacy systems. The agency's 2025 safety management system deadlines compress procurement cycles at Dallas-Fort Worth and Atlanta hub operators. Seattle's aerospace corridor anchors cloud-native platform development through proximity to Boeing engineering centers.
Germany
EASA Part-IS cybersecurity regulations require security management systems for all EU-registered operators above specified mass thresholds. Lufthansa Technik's Hamburg headquarters drives MRO software standardization across European flag carriers. Munich's aviation cluster concentrates predictive analytics procurement for sensor-dense Airbus A350 and A320neo fleets.
China
CAAC interoperability standards and GB/T data localization requirements shape vendor market access for foreign platform providers. Smart airport investments at Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun accelerate flight operations suite deployment. The Yangtze River Delta hosts domestic software development for CAAC-certified maintenance platforms.
United Kingdom
CAA alignment with EASA post-Brexit maintains regulatory pressure on maintenance documentation systems. London Heathrow and Gatwick operators consolidate vendor relationships to reduce integration tax across flight operations and crew management. Cambridge's technology corridor attracts aviation AI development for anomaly detection algorithms.
France
EU Green Deal emissions tracking requirements open procurement for fuel optimization algorithms integrating flight planning with carbon reporting. Air France-KLM's Paris-CDG hub drives sustainability analytics platform adoption across European network carriers. Toulouse's aerospace valley concentrates OEM-embedded software development for next-generation aircraft programs.
Aviation Software Market Vendor Landscape
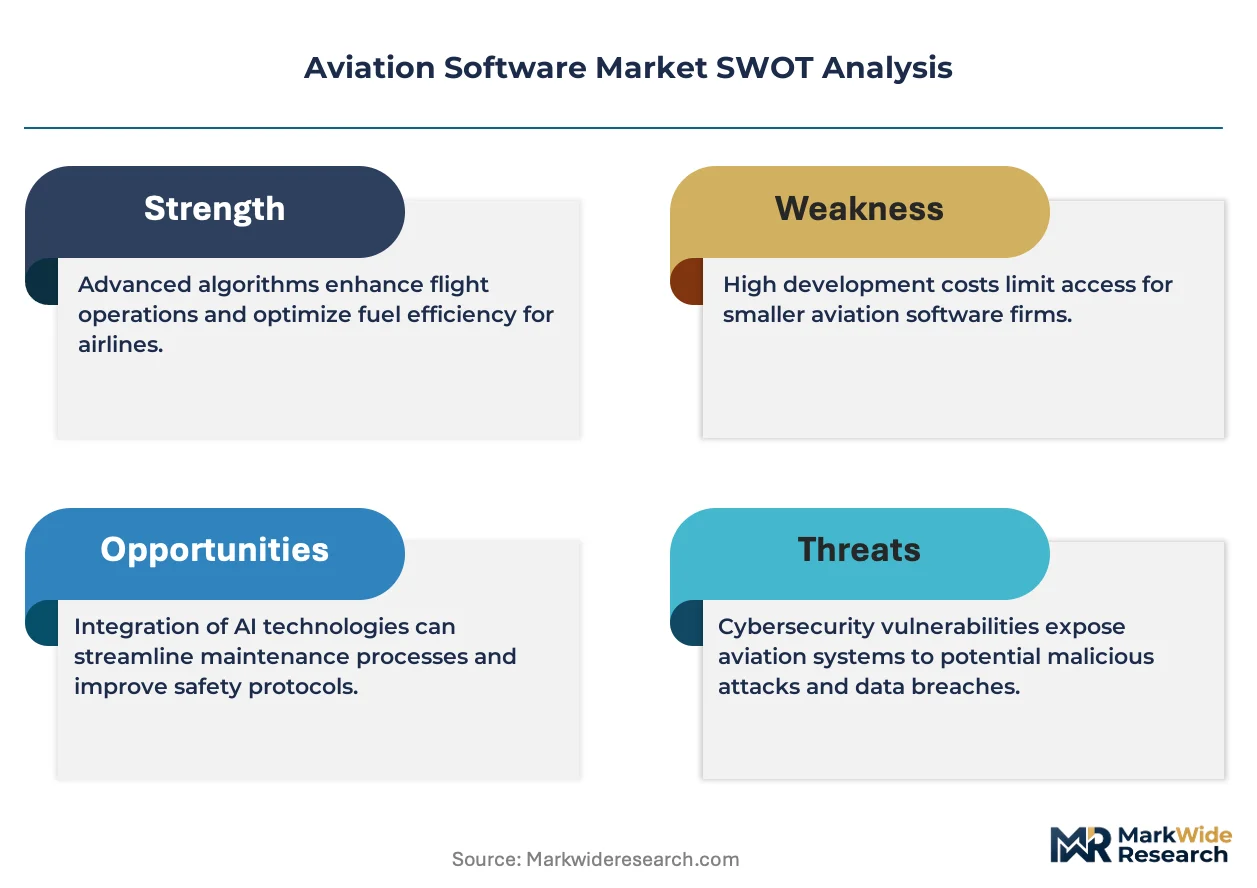
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers commanding premium pricing against point-solution middleware vendors. The vendor base concentrates around three strategic archetypes: avionics-embedded systems houses, federated data integration specialists, and cloud-native SaaS challengers. Dominant competitive moves include M&A to acquire ARINC protocol expertise and strategic partnerships with low-cost carriers seeking OpEx flexibility.
Within the integrated systems tier, Collins Aerospace and Honeywell exemplify avionics-to-ground platform consolidation. Palantir occupies a distinct position in federated data architectures spanning airline, OEM, and regulator silos. Swiss-AS and Ramco Aviation represent the maintenance management specialization vector, anchoring MRO documentation workflows.
| Leading Market Players |
|---|
| Swiss-AS |
| Ramco Aviation |
| IBM |
| Palantir |
| Collins Aerospace |
| Honeywell |
| Trax |
| aiOla |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Jet fuel price indices cascading through airline operating budgets compress procurement flexibility for software platforms, forcing vendors to stratify offerings across subscription tiers that align with carrier cash-flow cycles and fleet modernization schedules.
Pricing Analysis
Short lead-time premiums for rapid cloud deployment separate pricing tiers, with low-cost carriers paying standard SaaS rates while full-service network airlines negotiate customized hybrid architectures at 40-60% cost premiums. Price differentiation hinges on DO-178C certification grade and ARINC protocol integration depth. Pricing pressure intensifies as open-source middleware alternatives erode margins on non-critical crew scheduling modules. Maintenance providers exhibit highest price sensitivity due to thin MRO contract margins; OEM-embedded platform buyers show lowest sensitivity given bundled airframe procurement.
Supply Chain Analysis
Direct-to-airline channels handle hyperscale carrier demand while systems integrators and aviation consultancies distribute to mid-tier operators and Part 145 repair stations. Software development concentrates in the United States, Germany, and India, with Bangalore hosting embedded systems engineering for ARINC protocol stacks. Component dependencies include cloud infrastructure from hyperscalers, specialized avionics hardware from Toulouse and Hamburg clusters, and cybersecurity certification services from UK-based consultancies. Single-source vulnerability in DO-178C compliance auditing creates bottleneck risk for new platform releases. Distribution runs through OEM aftermarket networks and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation software has become a vertical-integration race, with platform providers capturing upstream data integration layers and downstream MRO service contracts to lock in recurring revenue streams.
For Market Incumbents: Lock in fleet-wide platform commitments through multi-year master service agreements that penalize data fragmentation, while acquiring ARINC protocol specialists to defend against API-first challengers. FAA safety management system deadlines and EASA Part-IS cybersecurity mandates create immediate upgrade demand that incumbents can capture through bundled compliance modules. For New Entrants and Emerging Players: eVTOL manufacturers and urban air mobility operators represent an underserved buyer archetype requiring lightweight, real-time mission management distinct from legacy airline stacks. Target this segment through cloud-native microservices architectures and 5G aeronautical connectivity partnerships, bypassing entrenched vendor relationships at network carriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor federated data integration specialists in the United States and maintenance documentation platform providers in Germany, where EASA regulatory pressure accelerates replacement demand. Long-term viability centers on vendors with native security architectures rather than bolt-on compliance modules. Watch for inflection when CAAC certifies foreign cloud platforms for Chinese hub operators.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of ARINC Protocol Specialist | Consolidates embedded avionics expertise against API-first competitors. |
| Platform Integration with OEM Aftermarket Networks | Captures embedded software placement on new aircraft deliveries. |
| Strategic Partnership with Low-Cost Carrier | Validates cloud-native architecture for rapid fleet scaling. |
| Geographic Expansion to CAAC-Certified Operations | Unlocks procurement at Beijing, Shanghai, and Guangzhou hub airports. |
| Product Launch of Federated Data Architecture | Enables distributed analytics across airline, OEM, and regulator silos. |
Methodological Framework
FAA airworthiness directive databases, EASA regulatory filing repositories, and CAAC certification records formed the secondary backbone, cross-referenced with primary interviews involving fleet operations directors, MRO procurement managers, avionics platform engineers, and regulatory compliance officers. Bottom-up and top-down triangulation validated segment sizing across deployment architectures and end-user categories.
Bottom-up modeling aggregated carrier-level procurement patterns while top-down analysis cross-checked against OEM aftermarket disclosures and cloud infrastructure spending trends. Segmentation dimensions included deployment model, fleet size tier, regulatory jurisdiction cluster, and integration complexity level. CAGRs derived from fitted growth curves applied to replacement cycle timelines and mandate-driven upgrade schedules, with sensitivity testing against fuel price volatility and certification backlog scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAAC data localization rulings, eVTOL certification timelines, and DO-326A cybersecurity process streamlining. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Spa and Salon Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
Managed Information Services Market
Software & Services
VFX Software Market
Software & Services
Global Content Management Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Gym Motion Tracking Software Market
Software & Services
Harbor and Marina Management Software Market
Software & Services
API Design Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global Demand Planning Software Market
Software & Services
3PL Software Market
Software & Services
Ground Handling Software Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Software Construction Components Market