

Dynamic Slotting and Storage Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Slotting and Storage Optimization Software Market Insights
Aftermarket service revenue from slotting algorithm updates and storage analytics subscriptions is rewriting how vendors capture lifetime value in this space. Manhattan Associates leverages its deep warehouse management heritage to anchor enterprise accounts with integrated optimization modules. Blue Yonder competes through AI-native demand forecasting that extends slotting decisions into upstream planning. Körber Supply Chain differentiates via its European manufacturing base and specialized control systems for complex storage environments.
Dynamic slotting and storage optimization software comprises algorithmic engines that calculate optimal product placement within warehouse racking systems based on velocity profiles, dimensional constraints, and retrieval frequency, typically processing thousands of stock-keeping units against real-time inventory signals to minimize travel distance and maximize cubic utilization. The primary commercial purpose centers on reducing order fulfillment labor hours while improving inventory accuracy in high-throughput distribution operations. Warehouse Management System deployments occupy the largest installed base due to their foundational role in facility control, though Cloud-Based delivery is accelerating fastest as multi-tenant architectures lower upfront capital barriers for mid-market operators. Order Fulfillment Software represents a concentrated margin pool where slotting logic directly interfaces with customer service-level agreements and same-day delivery commitments.
FDA traceability requirements for pharmaceutical distribution and OSHA warehouse safety standards shape how slotting software incorporates lot tracking and ergonomic pick-path design in regulated facilities. The EPA's emissions frameworks for logistics fleets indirectly pressure storage density optimization as warehouses expand to offset transportation energy intensity. Stakeholders must monitor how EU AI Act algorithmic transparency mandates will affect black-box optimization engines deployed across European fulfillment networks.
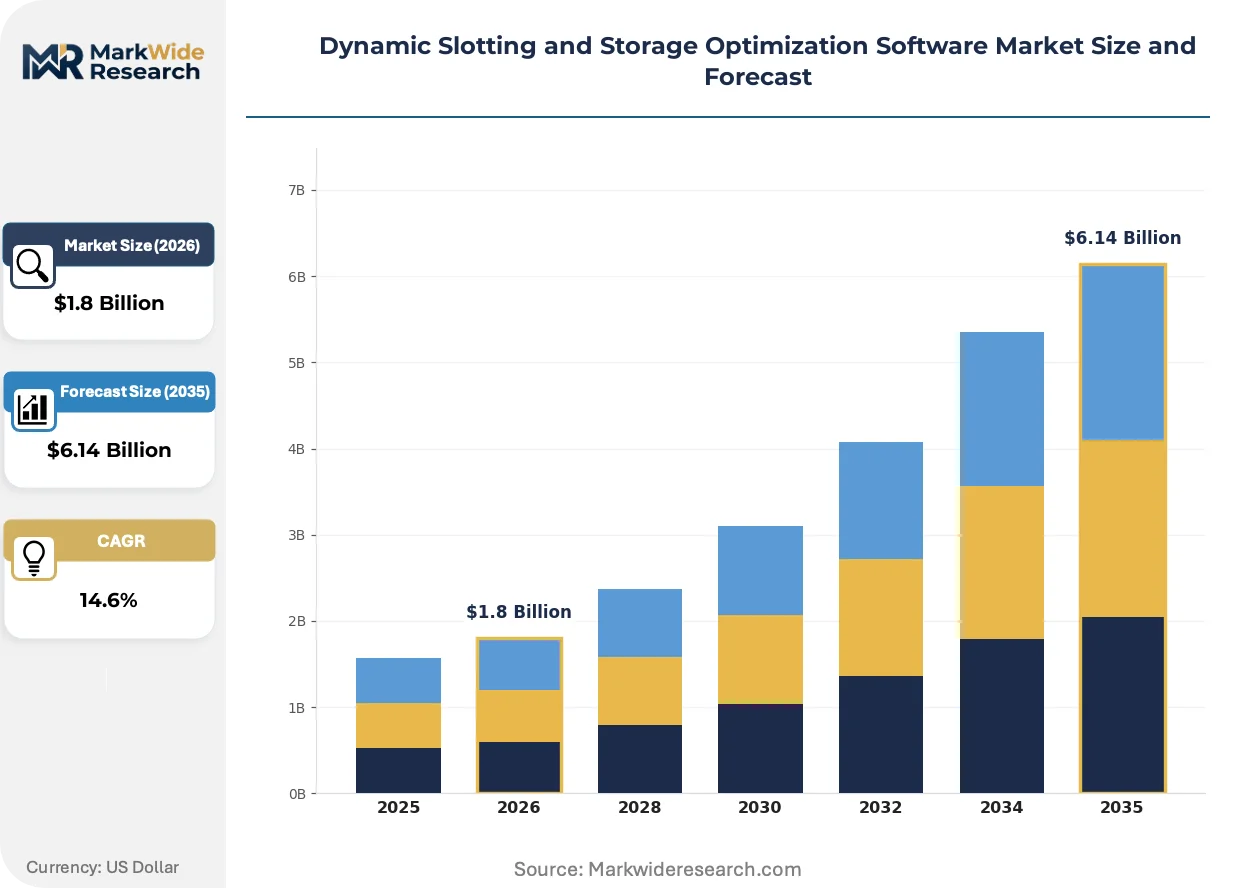
Market Dynamics
Cloud-native architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to rearchitect legacy codebases while mid-market operators bypass on-premise infrastructure entirely. This shift is redistributing competitive advantage toward software-as-a-service specialists with multi-tenant optimization engines.
Growth Catalysts
- E-commerce fulfillment velocity:Third-party logistics providers operating same-day delivery networks require real-time slotting recalculation as order profiles fragment across SKU portfolios. These operators represent the most aggressive adopters of algorithmic warehouse management.
- OSHA ergonomic mandates:Warehouse safety inspectors in the United States are penalizing facilities with excessive vertical reach distances and repetitive motion injuries. Slotting software that optimizes pick-path height variance reduces compliance exposure and workers compensation claims.
- Digital twin convergence:Integration between slotting algorithms and physics-based warehouse simulations allows operators to test layout changes without physical reconfiguration. This capability is accelerating procurement decisions among capital-constrained distributors.
Market Restraints
- Data interoperability barriers:Proprietary warehouse control system protocols from material handling equipment manufacturers create integration friction. Slotting engines cannot access real-time conveyor status or automated storage retrieval system occupancy without expensive middleware development.
- Algorithmic transparency requirements:The EU AI Act mandates explainable decision-making for automated systems affecting worker task allocation. Black-box optimization engines face compliance retrofit costs before deployment in European fulfillment networks.
- Skilled operations research talent scarcity:Facilities require analysts capable of interpreting velocity heat maps and tuning genetic algorithm parameters. The shortage of industrial engineering graduates with computational optimization training limits implementation quality.
Strategic Opportunities
- Cold chain pharmaceutical distribution:FDA traceability rules for drug lot tracking create demand for slotting systems that segregate temperature zones while maintaining retrieval efficiency. Vaccine distributors represent an underserved vertical with premium pricing tolerance.
- Subscription analytics revenue:Vendors can unbundle storage optimization from core warehouse management licenses, charging recurring fees for demand forecasting modules and seasonal slotting recommendations. This model improves customer lifetime value metrics.
- Retrofit automation integration:Brownfield facilities adding autonomous mobile robots need slotting software that coordinates human pick zones with machine-to-machine buffer locations. This hybrid orchestration capability commands implementation premiums.
Industry Challenges
- Multi-warehouse network synchronization:Enterprise operators struggle to maintain consistent slotting logic across distributed fulfillment nodes with varying racking configurations and local demand patterns. Centralized optimization engines often generate suboptimal recommendations for non-standard facilities.
- Legacy WMS migration complexity:Decades-old warehouse management installations carry custom code modifications that resist API-based integration. Slotting vendors must maintain parallel connector development for obsolete platform versions, diluting engineering resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Slotting and Storage Optimization Software Market Trends and Innovations
Reinforcement learning architectures are displacing rule-based heuristics in slotting optimization, enabling systems to autonomously discover placement strategies that human engineers never codified. This transition is compressing the performance gap between specialized optimization vendors and generalist supply chain platforms.
Reinforcement learning-based slotting engines is hybridizing predictive inventory positioning with automated storage retrieval system choreography. Pharmaceutical distributors with high-value temperature-controlled SKUs are piloting these integrated stacks. The technology is hybridizing what were previously separate capital budgeting decisions for software and material handling equipment.
REACH chemical substance restrictions are forcing European third-party logistics providers to track hazardous material segregation requirements within slotting algorithms. Facilities storing flammable aerosols or corrosive cleaning products must maintain minimum separation distances that override pure velocity-based placement. German chemical distributors are retrofitting slotting modules with hazard class compatibility matrices to preempt regulatory enforcement.
Buyer procurement committees are consolidating vendor selection authority from individual facility managers to centralized supply chain technology teams. This concentration is lengthening sales cycles but expanding contract values as enterprise-wide deployments replace point solutions. United States-based retail conglomerates with multi-brand portfolios are most advanced in this centralization, leveraging purchasing scale to demand source code escrow and custom development roadmaps.
Dynamic Slotting and Storage Optimization Software Market Segmentation
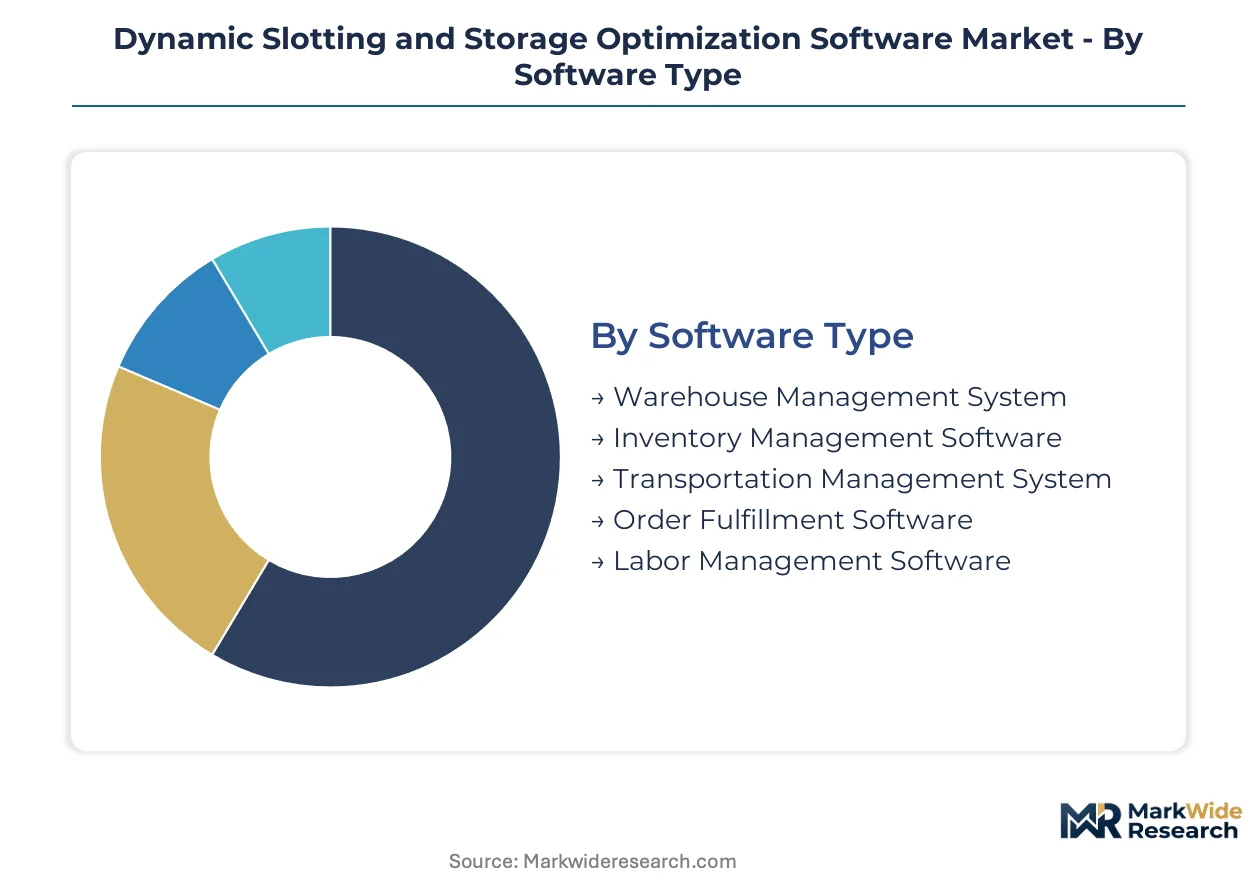
Warehouse operators select slotting optimization modules based on existing technology footprints and capital constraints. Deployment choices cascade through integration complexity, subscription economics, and real-time data architecture requirements. Understanding how demand fragments across these dimensions clarifies where vendors must anchor product development resources.
Software Type:
Cost tier determines adoption sequencing as facilities balance functionality depth against implementation risk.
- Warehouse Management System:Embedded slotting engines leverage existing inventory tracking infrastructure without separate data pipelines. E-commerce fulfillment centers in the United States prioritize these integrated modules to avoid middleware development costs.
- Order Fulfillment Software:Specialized applications interface directly with customer service-level agreements and same-day delivery commitments. Third-party logistics providers operating multi-tenant facilities drive demand for these purpose-built optimization layers.
- Inventory Management Software:Lightweight slotting add-ons serve mid-market distributors with limited IT staff.
- Transportation Management System:Cross-functional platforms incorporate storage density calculations to reduce drayage detention fees.
- Labor Management Software:Workforce optimization suites integrate pick-path efficiency metrics into productivity scoring engines.
Warehouse Management System holds installed capacity. Order Fulfillment Software is rotating up the share rankings.
Application:
Functional priority reflects facility maturity and operational pain points rather than technology sophistication.
- Order Picking Optimization:Algorithms calculate travel-minimizing pick sequences across zone-routed warehouses. Retail distribution networks with high SKU velocity deploy these modules to reduce labor hours per order.
- Space Utilization:Cubic density maximization addresses real estate cost pressure in urban fulfillment locations. Japanese automotive parts distributors prioritize these capabilities given constrained warehouse footprints near manufacturing plants.
- Inventory Allocation:Demand-driven positioning logic prevents stockouts in fast-moving categories.
- Load Balancing:Work distribution algorithms prevent congestion at high-throughput pick stations.
- Demand Forecasting:Predictive positioning engines pre-stage seasonal inventory ahead of volume spikes.
Order Picking Optimization commands current procurement attention. Space Utilization is climbing the fastest as real estate costs escalate.
Deployment Model:
Customer type and infrastructure legacy dictate architecture selection across the buyer base.
- Cloud-Based:Multi-tenant platforms eliminate server procurement and accelerate deployment timelines. Mid-market third-party logistics providers in Germany favor these subscriptions to preserve capital for automated material handling equipment.
- Software-as-a-Service:Usage-based pricing aligns costs with seasonal volume fluctuations. E-commerce pure-plays with variable demand patterns select these models to avoid fixed license commitments.
- On-Premises:Air-gapped installations serve defense contractors and pharmaceutical distributors with data sovereignty requirements.
- Hybrid:Split architectures keep sensitive inventory data local while leveraging cloud analytics.
- Edge Computing:On-device processing enables sub-second slotting recalculation for automated storage retrieval systems.
On-Premises retains entrenched positions in regulated verticals. Cloud-Based is gaining share fastest among new facility deployments.
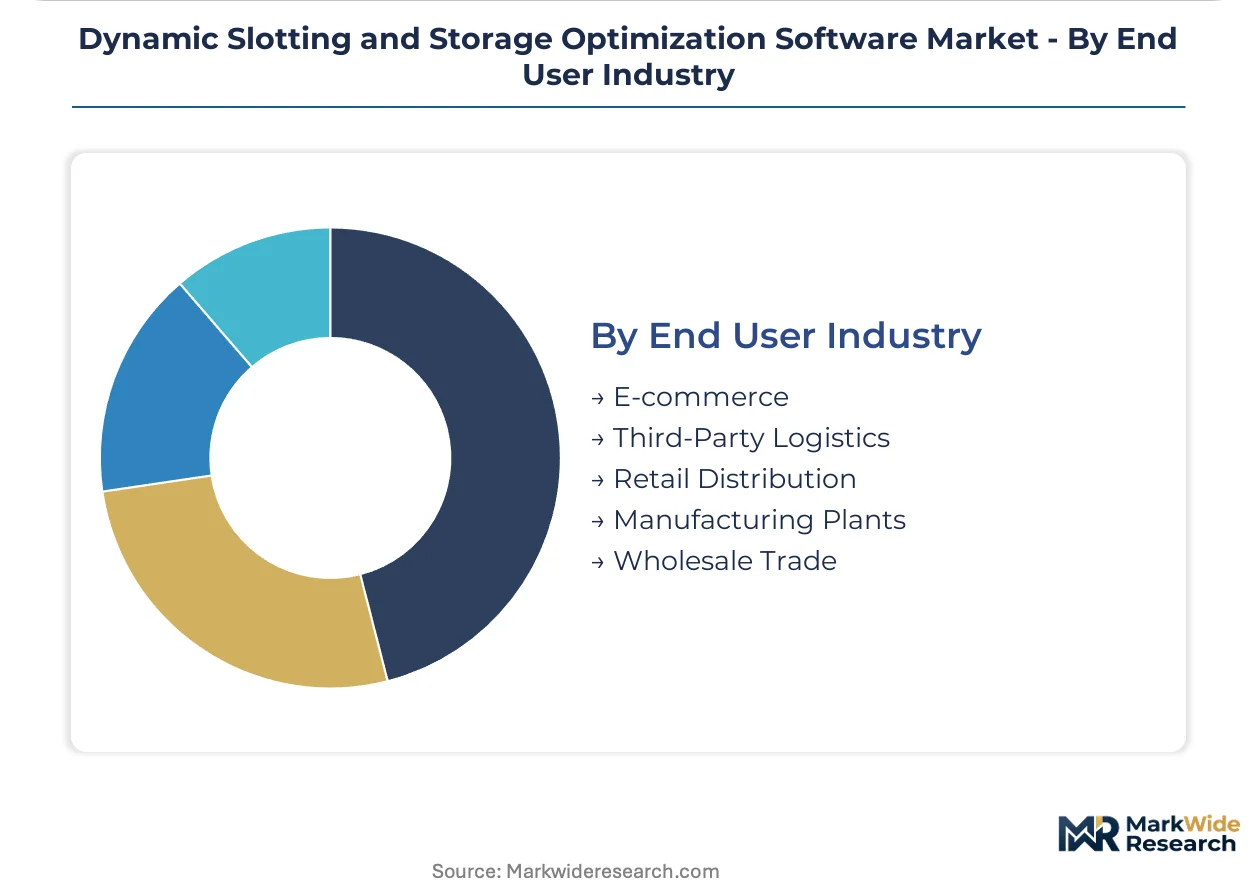
End User Industry:
Volume concentration and margin structure shape technology investment willingness across sectors.
- Third-Party Logistics:Multi-client operators require configurable slotting rules that segregate inventory ownership while maximizing shared infrastructure utilization. United States-based 3PLs serving retail conglomerates represent the most aggressive adopters of real-time optimization.
- E-commerce:Direct-to-consumer fulfillment networks process fragmented order profiles with extreme velocity variance. Same-day delivery commitments in urban markets force continuous slotting recalculation.
- Retail Distribution:Store replenishment operations balance case-pick efficiency with broken-case e-commerce demand.
- Manufacturing Plants:Production-line feeding applications prioritize retrieval speed over storage density.
- Wholesale Trade:Full-pallet operations apply lighter optimization requirements given lower handling frequency.
Retail Distribution holds legacy deployment share. Third-Party Logistics is expanding most quickly as outsourced fulfillment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate lowest price sensitivity given elevated labor costs and automation budgets, while mid-market operators in Southern Europe and Southeast Asia prioritize subscription economics over feature depth.
United States
E-commerce fulfillment centers and third-party logistics providers drive aggressive adoption of real-time slotting recalculation tools. OSHA warehouse safety standards mandate ergonomic pick-path design, pushing facilities toward algorithmic height optimization. The Inland Empire logistics corridor in Southern California anchors the densest concentration of automated distribution facilities undergoing slotting system upgrades.
Germany
Automotive parts distributors and chemical logistics operators require specialized storage optimization for complex SKU portfolios. REACH chemical substance restrictions force slotting engines to incorporate hazard class compatibility matrices for flammable and corrosive materials. The Rhine-Ruhr industrial cluster hosts the highest density of brownfield warehouses retrofitting hybrid human-robot slotting coordination systems.
China
Domestic e-commerce platforms and cross-border fulfillment networks process extreme velocity variance across fragmented order profiles. SAMR data localization requirements push multinational operators toward on-premise or hybrid deployment architectures. The Yangtze River Delta manufacturing belt concentrates demand for production-line feeding slotting systems serving just-in-time assembly plants.
Japan
Constrained urban warehouse footprints near manufacturing plants prioritize cubic density maximization over retrieval speed. METI industrial productivity initiatives subsidize digital twin integration for testing layout changes without physical reconfiguration. The Chubu region around Nagoya anchors automotive parts distribution networks deploying space utilization optimization modules.
United Kingdom
Retail conglomerates with multi-brand portfolios centralize procurement authority toward enterprise-wide slotting deployments. GDPR data processing requirements influence cloud architecture decisions for inventory velocity analytics. The Midlands logistics golden triangle—bounded by Derby, Nottingham, and Birmingham—hosts the densest cluster of third-party logistics facilities adopting subscription-based optimization analytics.
Dynamic Slotting and Storage Optimization Software Market Competitive Landscape
Capability concentration sits with specialized optimization vendors possessing deep operations research expertise; scale advantage sits with integrated supply chain platforms leveraging existing warehouse management relationships. The vendor landscape stratifies across three tiers: enterprise suites with embedded slotting modules, pure-play optimization specialists, and emerging cloud-native challengers. Dominant competitive moves include portfolio diversification into adjacent warehouse automation software and strategic partnerships with autonomous mobile robot manufacturers.
Within the enterprise suite tier, Manhattan Associates anchors North American warehouse management heritage, while Blue Yonder occupies a position among AI-native demand forecasting platforms extending slotting into upstream planning. Körber Supply Chain exemplifies the European manufacturing base archetype with specialized control systems for complex storage environments. These three companies represent contrasting geographic and technological positioning strategies without implying specific market share or performance claims.
| Leading Market Players |
|---|
| Manhattan Associates |
| Blue Yonder |
| Körber Supply Chain |
| Tecsys |
| Softeon |
| Made4net |
| Generix Group |
| Lucas Systems |
| FORTNA |
| Others |
Pricing and Supply Chain Analysis
The Inland Empire logistics corridor anchors North American capacity for warehouse automation software development, with concentrated engineering talent in Southern California creating asymmetric pricing power for vendors serving e-commerce fulfillment networks. This geographic concentration of optimization expertise feeds downstream into subscription pricing structures that vary sharply by buyer sophistication and deployment complexity.
Pricing Analysis
Aftermarket service revenue from algorithm updates and storage analytics subscriptions drives lifetime value capture across vendor portfolios. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration depth and data throughput requirements. Price differentiation rests on certification tier for FDA-regulated pharmaceutical facilities versus general warehouse deployments. Cost compression in the mid-market tier is intensifying because cloud-native entrants are undercutting legacy license models with usage-based alternatives. Third-party logistics providers exhibit highest price sensitivity due to thin operating margins, while pharmaceutical distributors show lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Contract manufacturing concentration for optimization software development sits with specialized systems integrators in the United States, Germany, and India. Raw material dependencies center on cloud infrastructure services, GPU compute capacity for machine learning workloads, and proprietary sensor networks for warehouse automation integration. Supply chain risk hinges on single-source vulnerability for reinforcement learning training clusters operated by hyperscale cloud providers. Distribution runs through direct enterprise sales teams for large accounts and channel partners serving mid-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors must defend against substitution from generalist supply chain platforms embedding slotting modules as loss-leader features. The threat of vertical integration by e-commerce giants building in-house optimization capabilities demands preemptive strategic positioning.
For Market Incumbents: Pre-empt platform substitution by deepening API integration with autonomous mobile robot manufacturers, cementing orchestration capabilities that generalist WMS vendors cannot replicate. Anchor enterprise accounts through source code escrow arrangements and custom development roadmaps that raise switching costs. Defend against cloud-native challengers by accelerating multi-tenant architecture migration to match deployment timeline compression.
For New Entrants and Emerging Players: Establish a beachhead in cold chain pharmaceutical distribution, where FDA traceability requirements create compliance-driven demand with premium pricing tolerance. Target brownfield facilities retrofitting hybrid human-robot coordination systems, as incumbent vendors struggle with legacy WMS connector maintenance. Lead with digital twin integration capabilities that compress capital budgeting decisions and accelerate procurement cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because slotting optimization becomes embedded in warehouse operating technology stacks with high switching costs. Acquisition targets should display deep operations research talent pools and existing pharmaceutical or cold chain vertical penetration. Watch cloud-native deployment share crossing majority thresholds in new facility procurement as the inflection signal for vendor consolidation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding slotting engines within WMS cores reduces middleware friction for Manhattan Associates-tier deployments. |
| Strategic Partnership | Autonomous mobile robot coordination agreements with Locus Robotics-tier vendors command implementation premiums. |
| Acquisition of Specialist Firm | Operations research boutiques with pharmaceutical vertical expertise accelerate FDA compliance pathway integration. |
| Geographic Expansion | Rhine-Ruhr cluster penetration captures German chemical logistics retrofit demand under REACH hazard matrices. |
| Product Launch | Reinforcement learning-native slotting engines displace rule-based heuristics in high-velocity e-commerce networks. |
Research Methodology
Operator-level perspectives from warehouse operations directors, supply chain technology procurement officers, and third-party logistics facility managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings of publicly traded WMS vendors, hyperscaler cloud infrastructure capex disclosures, and OSHA enforcement data on warehouse ergonomic violations. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against aggregate automation investment flows ensured segmentation integrity.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting cloud migration velocity variance and regulatory enforcement intensity. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity with legacy WMS installations, and regional adoption pattern by logistics corridor density. CAGRs were derived from fitting S-curve penetration models to historical WMS upgrade cycles and cloud-native replacement trajectories. Forecast inputs incorporated e-commerce fulfillment volume projections and automated storage retrieval system installation rates as demand proxies.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles among retail conglomerates or interest rate sensitivity among mid-market 3PLs would shift the trajectory. Forecasts reflect documented assumptions on cloud infrastructure cost curves and algorithmic transparency compliance costs under EU AI Act implementation. Quarterly review of warehouse automation capital commitment announcements and cloud-native slotting vendor funding rounds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.