
 Global Press Release Distribution Software Market | 2026-2036
Global Press Release Distribution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Press Release Distribution Software Market Foresight
Native API-first architecture is shifting the underlying delivery economics away from legacy email-relay systems toward real-time programmatic distribution. PR Newswire (Cision) leverages its established journalist network to sustain premium positioning in enterprise accounts. GlobeNewswire anchors North American financial disclosure workflows through its SEC filing integrations. Business Wire competes on regulatory compliance depth across multiple jurisdictions.
Press release distribution software comprises cloud-native platforms that automate the creation, targeting, transmission, and performance tracking of corporate announcements to journalists, newsrooms, and digital channels, typically incorporating metadata tagging for search discoverability and engagement analytics dashboards. Cloud-Based deployment leads volume adoption due to minimal infrastructure overhead and rapid onboarding cycles for marketing agencies and small businesses, while API Integration represents the fastest-expanding segment as public relations firms embed distribution capabilities directly into proprietary workflow tools. Analytics & Reporting commands disproportionate margin attention because performance attribution data commands recurring subscription premiums from investor relations departments.
The U.S. SEC mandates structured disclosure formats that shape product feature requirements for domestic-listed companies, while the EU GDPR constrains contact database management practices across European customer implementations. The EU AI Act introduces emerging compliance obligations for automated content targeting algorithms that vendors must address. Stakeholders should monitor how regulatory divergence between American and European frameworks affects platform development priorities and cross-border service architectures.
Market Dynamics
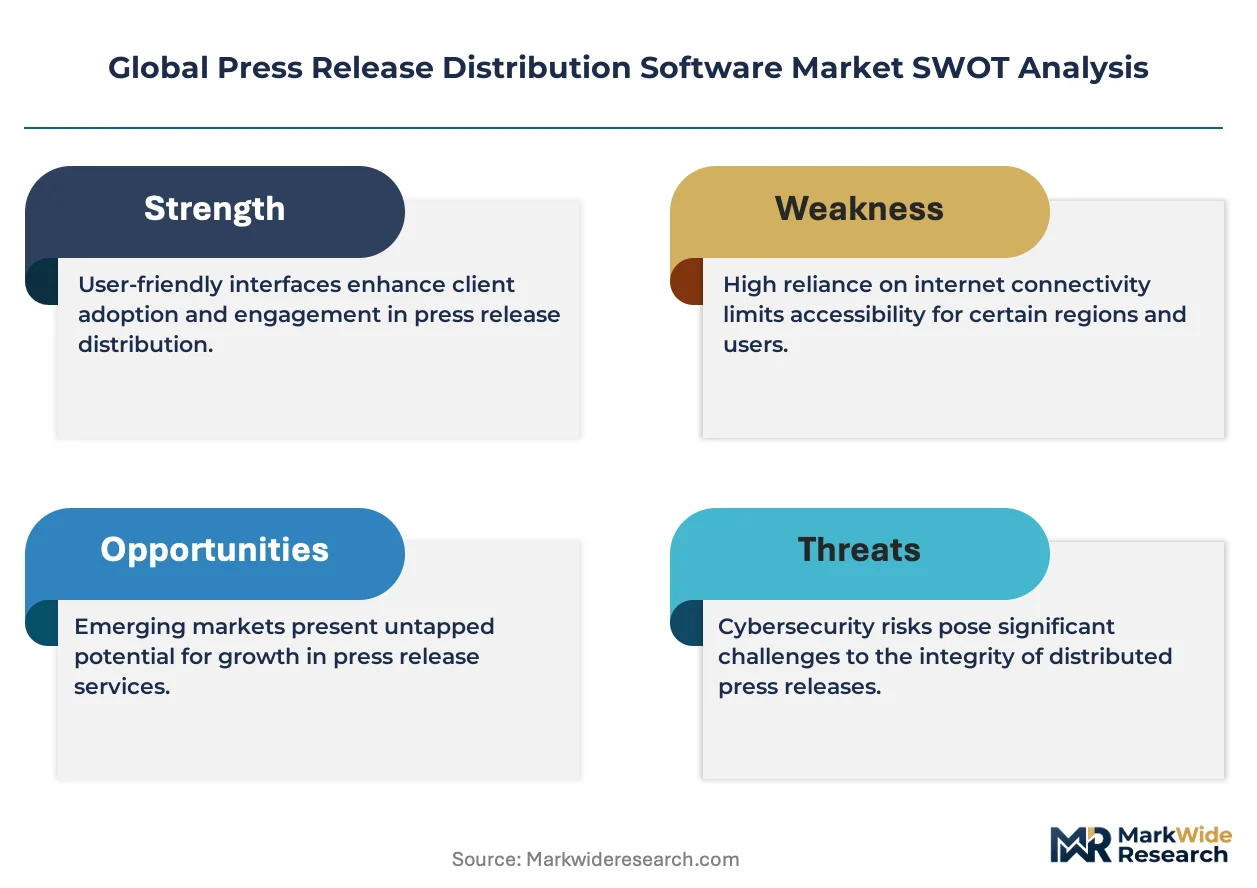
API-first architecture is compressing delivery economics and forcing legacy email-relay vendors to restructure their infrastructure investments or cede share to programmatic-native competitors.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements are accelerating procurement of compliant distribution platforms among European financial services firms preparing for enforcement timelines.
- SEC structured disclosure rules:U.S.-listed technology companies must automate filing workflows, creating sustained demand for integrated press release and regulatory submission tools.
- Real-time programmatic distribution:Cloud-native transmission protocols are replacing batch-processing systems, reducing latency for crisis communications and earnings announcements.
Market Restraints
- GDPR contact database constraints:European customer implementations face recurring compliance audits that inflate operational overhead and limit journalist list expansion.
- Input cost volatility in cloud infrastructure:Compute and storage pricing fluctuations at hyperscale providers compress margins for SaaS vendors operating multi-tenant architectures.
- Substitution by owned-channel strategies:Large technology firms are building proprietary media networks that bypass third-party distribution entirely.
Strategic Opportunities
- Underpenetrated Indian market:SEBI disclosure modernization and BSE/NSE listing growth are creating first-mover openings for compliant distribution platforms.
- Convergence of AI content generation with distribution:Automated drafting-to-deployment pipelines are attracting marketing agencies seeking end-to-end workflow consolidation.
- Japan METI digital disclosure incentives:Subsidies for corporate transparency tools are expanding addressable market among TSE-listed mid-cap enterprises.
Industry Challenges
- Integration complexity with legacy CRM systems:Enterprise sales and marketing stacks require costly custom connectors that extend implementation timelines.
- Certification timeline compression:Multiple concurrent regulatory frameworks demand parallel compliance engineering that strains product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Press Release Distribution Software Market |
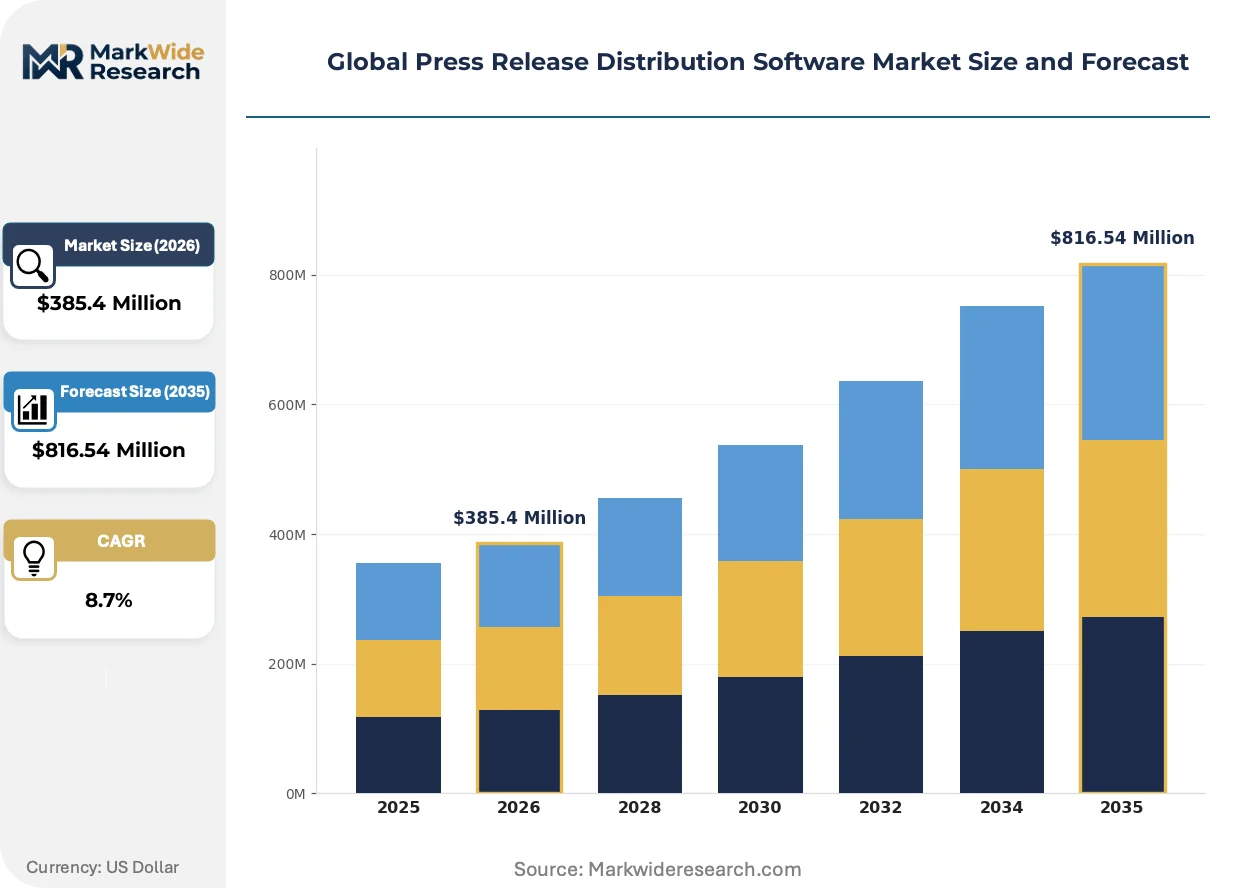
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, API Integration Solution Type: Media Monitoring, Content Management, Analytics & Reporting, Social Media Distribution, Email Marketing Use Case: Brand Awareness, Crisis Management, Investor Relations, Product Launches, Event Promotion Customer Type: Public Relations Firms, Corporate Communications, Marketing Agencies, Small Businesses, Nonprofits |
| Companies Covered | GlobeNewswire, eReleases, PR Newswire (Cision), EAK Digital, PRWeb (Cision), Business Wire, Chainwire, Agility PR Solutions, RedPress.net, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Press Release Distribution Software Market Shifts & Advancements
Native API architecture is collapsing the traditional separation between content creation, targeting, and performance measurement into unified workflow layers.
Embedded distribution modules are unifying press release functionality directly into marketing automation and CRM platforms. Mid-market SaaS companies are adopting these integrations fastest, eliminating standalone tool procurement. This convergence is compressing vendor count in martech stacks and favoring platform-native solutions over point products.
The EU AI Act's algorithmic transparency requirements are mandating explainability features for automated content targeting. Vendors must now document decision logic for journalist matching and channel selection. European financial disclosure workflows are most affected, with compliance engineering consuming disproportionate roadmap resources.
Subscription-based procurement is displacing per-release pricing among investor relations departments. Annual platform commitments with unlimited distribution volume are replacing transaction-based contracts. This shift is most visible in the United States, where recurring revenue models now dominate enterprise SaaS procurement for communications infrastructure.
Global Press Release Distribution Software Market Segmentation
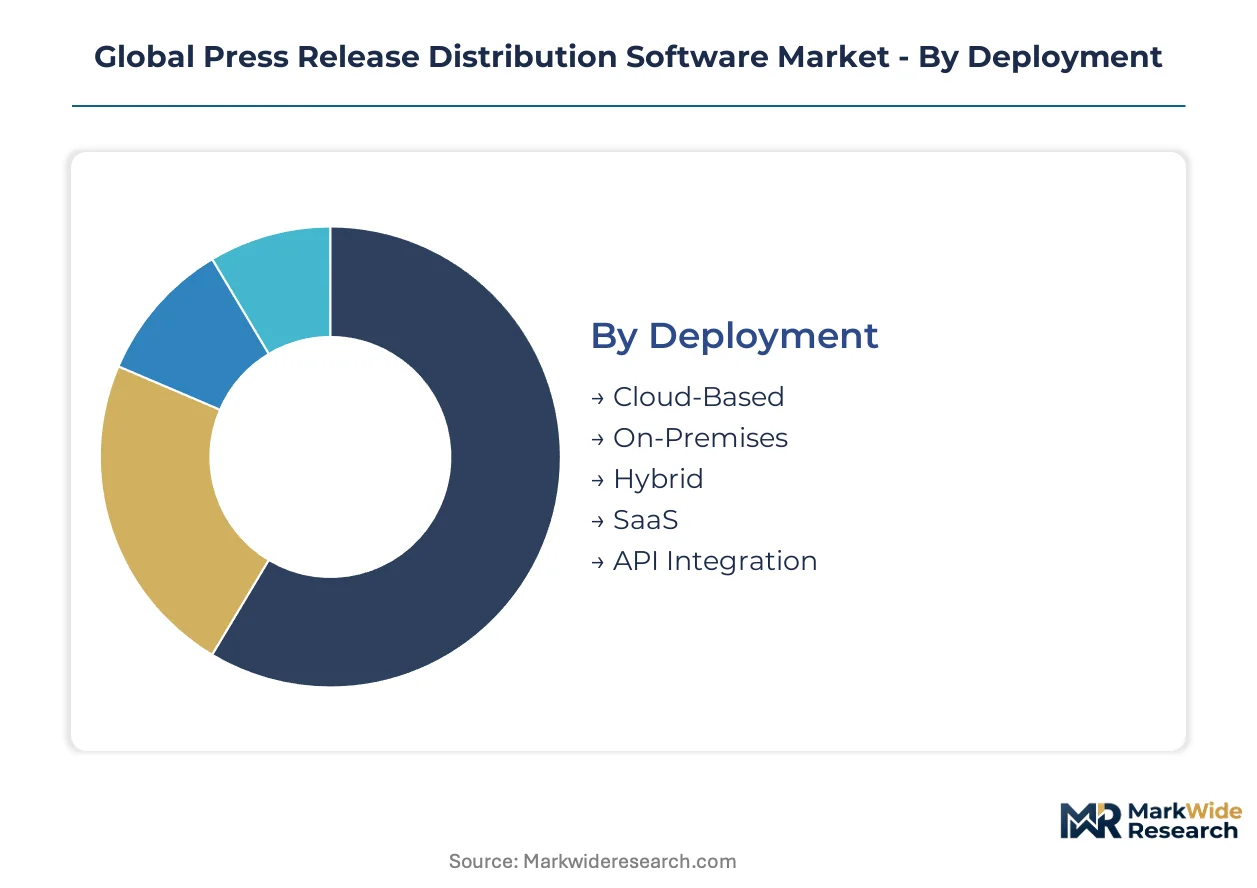
Press release distribution software segments diverge sharply in infrastructure requirements and recurring revenue potential. Deployment mode determines capital intensity, while solution type shapes margin profiles across customer tiers.
Deployment:
Capital intensity peaks with on-premises installations demanding server hardware and dedicated IT staffing, while cloud-native alternatives minimize upfront commitment.
- Cloud-Based:Multi-tenant architectures eliminate data center expenditure for marketing agencies and small businesses. Demand concentrates in the United States among SaaS companies seeking rapid onboarding without infrastructure overhead.
- API Integration:Real-time programmatic interfaces embed distribution into proprietary workflow tools. Public relations firms in Germany and France are adopting these fastest to satisfy EU AI Act transparency mandates for algorithmic targeting.
- SaaS:Subscription models with standardized feature sets serve mid-market corporate communications teams.
- Hybrid:Split architectures accommodate regulated industries requiring local data residency alongside cloud scalability.
- On-Premises:Self-hosted deployments persist among Japanese financial institutions with strict data sovereignty requirements under METI guidelines.
Most installed capacity flows through Cloud-Based platforms. Expansion is steepest in API Integration.
Solution Type:
Margin concentration follows data intensity, with analytics commanding premium pricing against commoditized distribution channels.
- Analytics & Reporting:Performance attribution dashboards with engagement metrics and conversion tracking. Investor relations departments in the United States pay recurring premiums for SEC-compliant disclosure analytics.
- Media Monitoring:Real-time journalist activity tracking and competitive mention alerts. European financial services firms under GDPR constraints prioritize privacy-compliant monitoring tools.
- Content Management:Centralized drafting, approval workflows, and version control for distributed communications teams.
- Social Media Distribution:Native amplification across LinkedIn, Twitter, and industry-specific channels for technology product launches.
- Email Marketing:Legacy journalist outreach with deliverability optimization and list hygiene automation.
Revenue gravity centers on Analytics & Reporting. Social Media Distribution is climbing the fastest as owned-channel strategies mature.
Use Case:
Procurement urgency varies by disclosure mandate, with regulatory-driven workflows outperforming discretionary marketing spend.
- Investor Relations:Structured disclosure automation for earnings releases and material event filings. U.S.-listed technology companies sustain demand through SEC filing integration requirements.
- Crisis Management:Sub-minute latency distribution with pre-approved stakeholder lists. Financial institutions in the United Kingdom prioritize these capabilities for reputational risk mitigation.
- Brand Awareness:Sustained visibility campaigns targeting trade publications and vertical journalists.
- Product Launches:Coordinated embargo management and tiered journalist access for consumer technology releases.
- Event Promotion:Time-bound amplification for conferences and earnings calls with RSVP integration.
Contract value concentrates in Investor Relations. Crisis Management is gaining share fastest as regulatory enforcement intensifies.
Customer Type:
Account complexity escalates with organizational scale, from self-service small business interfaces to enterprise procurement through procurement departments.
- Corporate Communications:Integrated platforms spanning internal and external messaging for Fortune 500 technology firms. Procurement in the United States favors annual platform commitments with unlimited volume.
- Public Relations Firms:Multi-client workflow tools with white-label reporting and client-specific journalist segmentation. Agencies in France and Germany face EU AI Act compliance engineering costs.
- Marketing Agencies:Campaign-centric tools with creative asset management and performance benchmarking.
- Small Businesses:Template-driven self-service with per-release pricing and minimal customization.
- Nonprofits:Discounted or donated access with simplified feature sets for cause-driven announcements.
Revenue concentration sits with Corporate Communications. Public Relations Firms are expanding most quickly as agency consolidation drives platform standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's technology corridor sustains the densest concentration of press release distribution software procurement, with corporate communications teams at SaaS firms driving platform adoption for investor relations automation and crisis response protocols.
United States
SEC structured disclosure mandates compel domestic-listed technology companies to automate earnings release workflows, creating sustained procurement of integrated filing and distribution platforms. The regulator's EDGAR system integration requirements shape vendor feature roadmaps. New York's financial district and Silicon Valley's venture-backed clusters anchor enterprise contract concentration, with fintech startups in Miami emerging as a secondary demand node.
Germany
Public relations firms in Frankfurt and Munich are accelerating API-first platform adoption to satisfy EU AI Act transparency obligations for algorithmic journalist targeting. The national data protection authority enforces GDPR constraints on contact database management that inflate operational overhead. Berlin's startup ecosystem is generating mid-market demand for cloud-native solutions with embedded compliance documentation.
United Kingdom
Financial institutions in the City of London prioritize sub-minute latency distribution capabilities for reputational risk mitigation during crisis scenarios. The Financial Conduct Authority's disclosure guidelines intersect with EU regulatory spillover effects post-Brexit. Manchester's expanding technology sector is adopting self-service platforms for product launch amplification.
Japan
METI digital disclosure subsidies are expanding addressable market penetration among Tokyo Stock Exchange-listed mid-cap enterprises seeking transparency tool modernization. The ministry's incentives reduce procurement friction for cloud-based investor relations automation. Osaka's industrial conglomerates are piloting hybrid deployment models to satisfy data sovereignty requirements.
India
SEBI disclosure modernization and Bombay Stock Exchange listing growth are creating first-mover openings for compliant distribution platforms among financial services firms. The regulator's structured data mandates parallel SEC requirements. Bengaluru's SaaS export cluster is adopting API-integrated solutions for coordinated global product announcements.
Global Press Release Distribution Software Market Competitive Landscape
Strategic partnership formation dominates the current landscape as vendors seek to embed distribution capabilities into adjacent martech platforms. The vendor base organizes around three archetypes: established newswire incumbents with journalist network assets, cloud-native challengers with API-first architectures, and specialized agencies offering white-label workflow tools. Consolidation pressure is intensifying as enterprise procurement shifts toward unified platform commitments over point solutions. Technology licensing and portfolio diversification represent the primary competitive vectors for mid-scale players seeking differentiation.
Within the established newswire tier, PR Newswire and Business Wire exemplify legacy positioning anchored in regulatory compliance depth and SEC filing integration capabilities. GlobeNewswire occupies a position bridging traditional newswire services with programmatic distribution modernization. These three entities represent contrasting strategic postures: one emphasizes enterprise journalist network scale, another competes on multi-jurisdictional regulatory coverage, and the third targets financial disclosure workflow automation.
| Leading Market Players |
|---|
| GlobeNewswire |
| eReleases |
| PR Newswire (Cision) |
| EAK Digital |
| PRWeb (Cision) |
| Business Wire |
| Chainwire |
| Agility PR Solutions |
| RedPress.net |
| Others |
Supply & Pricing Matrix
Enterprise-journalist network scale separates premium newswire tiers from commodity API relay services, with that divergence manifesting in both subscription pricing power and cloud infrastructure sourcing strategies. Tier-one vendors anchor pricing on SEC filing integration depth and proprietary media relationships, while programmatic challengers compete on hyperscale compute efficiency and minimal data residency overhead.
Pricing Analysis
Hyperscale compute and storage pricing at AWS, Azure, and Google Cloud feeds directly into SaaS vendor margin structures, compressing economics for multi-tenant architectures. Three-tier pricing structure across premium, standard, and economy levels aligns with journalist network access depth and regulatory compliance certification tiers. Pricing pressure stems from cloud infrastructure cost volatility and enterprise procurement's shift toward annual platform commitments with unlimited volume. Small businesses and marketing agencies exhibit highest price sensitivity, while investor relations departments at U.S.-listed technology firms demonstrate lowest sensitivity due to SEC mandate compliance requirements.
Supply Chain Analysis
Freight and logistics costs are immaterial in this digital-native market, where transmission latency and data sovereignty compliance constitute the operative supply chain constraints. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with compute and storage capacity drawing from hyperscale provider networks. Raw material dependencies center on semiconductor availability for server hardware, fiber optic cable deployment for low-latency connections, and electricity pricing for data center operations. Single-source vulnerability runs through AWS, Azure, and Google Cloud dominance in enterprise cloud services. Distribution runs through direct SaaS procurement, API marketplace integrations, and strategic partnerships with adjacent martech platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Press Release Distribution Software Market functions as a stable compounder, with regulatory disclosure mandates across multiple jurisdictions generating recurring, non-discretionary demand that insulates revenue from economic cyclicality.
For Market Incumbents: Cement regulatory compliance depth as the primary defensive moat by accelerating EU AI Act transparency engineering and deepening SEC EDGAR integration capabilities. API-first challengers threaten enterprise share through programmatic latency advantages; counter by acquiring specialized workflow automation firms to embed distribution into proprietary martech stacks.
For New Entrants and Emerging Players: SEBI disclosure modernization in India opens a window for compliant platform launches targeting financial services firms preparing for structured data mandates. White-space targets include mid-cap TSE-listed enterprises in Japan responding to METI subsidies, and Indian SaaS exporters requiring coordinated global announcement capabilities. A partner-channel go-to-market through public relations firm consolidators accelerates client acquisition without direct enterprise sales overhead.
For Investors and Strategic Acquirers: Consolidation pressure builds where enterprise procurement shifts from point solutions toward unified martech platform commitments. Long-term viability favors vendors with regulatory certification depth across multiple jurisdictions and API-native architectures that compress delivery economics. Acquisition target archetype: mid-scale challengers with EU AI Act compliance documentation and established journalist network relationships. Watch for hyperscale cloud provider pricing announcements as margin inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Modernization | Real-time programmatic distribution collapses latency for crisis communications and earnings releases. |
| Regulatory Compliance Engineering | EU AI Act transparency documentation and SEC filing integration sustain premium positioning in enterprise accounts. |
| Strategic Partnership Formation | Embedded distribution modules in marketing automation and CRM platforms compress vendor count in martech stacks. |
| Geographic Expansion | SEBI-aligned platform launches capture first-mover positioning among Indian financial services firms. |
| Acquisition of Specialist Firm | Workflow automation targets accelerate convergence of AI content generation with distribution deployment pipelines. |
Research Methodology
Bottom-up investor relations and corporate communications modeling reconciled against top-down cloud infrastructure and API marketplace tracking forms the analytical core of this study. Primary interviews with chief communications officers, investor relations directors, public relations agency principals, and martech procurement officers combined with secondary validation from SEC EDGAR filings, EU regulatory transparency databases, hyperscaler capex disclosures, and trade association communications technology surveys. Triangulation across these sources ensures segmentation accuracy and demand-side calibration.
Input-output matrix framing connects deployment mode adoption rates, solution type procurement patterns, and customer type account complexity against cloud infrastructure capacity expansion and regulatory compliance engineering investments. Segmentation dimensions modeled include deployment architecture, solution functionality, use case urgency, and customer organizational scale across the projection horizon. CAGRs derive from regression analysis of historical platform adoption curves and forward-looking regulatory mandate timelines, with sensitivity testing against cloud pricing volatility and enterprise SaaS procurement cycle shifts.
Revisions become necessary when regulatory enforcement timelines accelerate, hyperscale cloud provider pricing structures shift materially, or enterprise martech consolidation patterns deviate from partnership-formation assumptions. Forecasts reflect documented assumptions about compliance cost trajectories and API adoption velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Disclosure Management Software Market
Software & Services
India Sports Management Software Market
Software & Services
Web Scraping Software Market
Software & Services
Global Website Builder Software Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Credit Management Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Global Architecture Design Software Market
Software & Services
Attendance Management Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
API Testing Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
AI Sales Assistant Software Market