
 Live Software Market | 2026-2036
Live Software Market Size, Share, and Industry Trends Forecast 2026-2036
Live Software Market Insights
Cloud-native engineering talent scarcity is bifurcating vendor performance across the Live Software Market. IBM leverages its Red Hat OpenShift backbone to sustain hybrid deployment credibility for regulated clients. Brightcove anchors its position through specialized video delivery APIs that dominate media and entertainment workflows. Kaltura competes in educational technology by extending its Learning Management System integrations across North American and European campuses.
Live software encompasses real-time video encoding, low-latency streaming protocols, and interactive broadcast management platforms that process sub-three-second glass-to-glass latency for synchronous communication. The technology stack integrates WebRTC, SRT, and HLS adaptive bitrate algorithms to enable scalable one-to-many and many-to-many transmission across variable network conditions. Public cloud deployment leads in absolute volume due to elastic capacity provisioning for event streaming spikes, while hybrid cloud configurations capture margin pools from financial services and healthcare buyers with data residency constraints. Enterprise end users represent the fastest-growing demand segment as Fortune 500 firms replace legacy conferencing stacks with API-first live collaboration infrastructure.
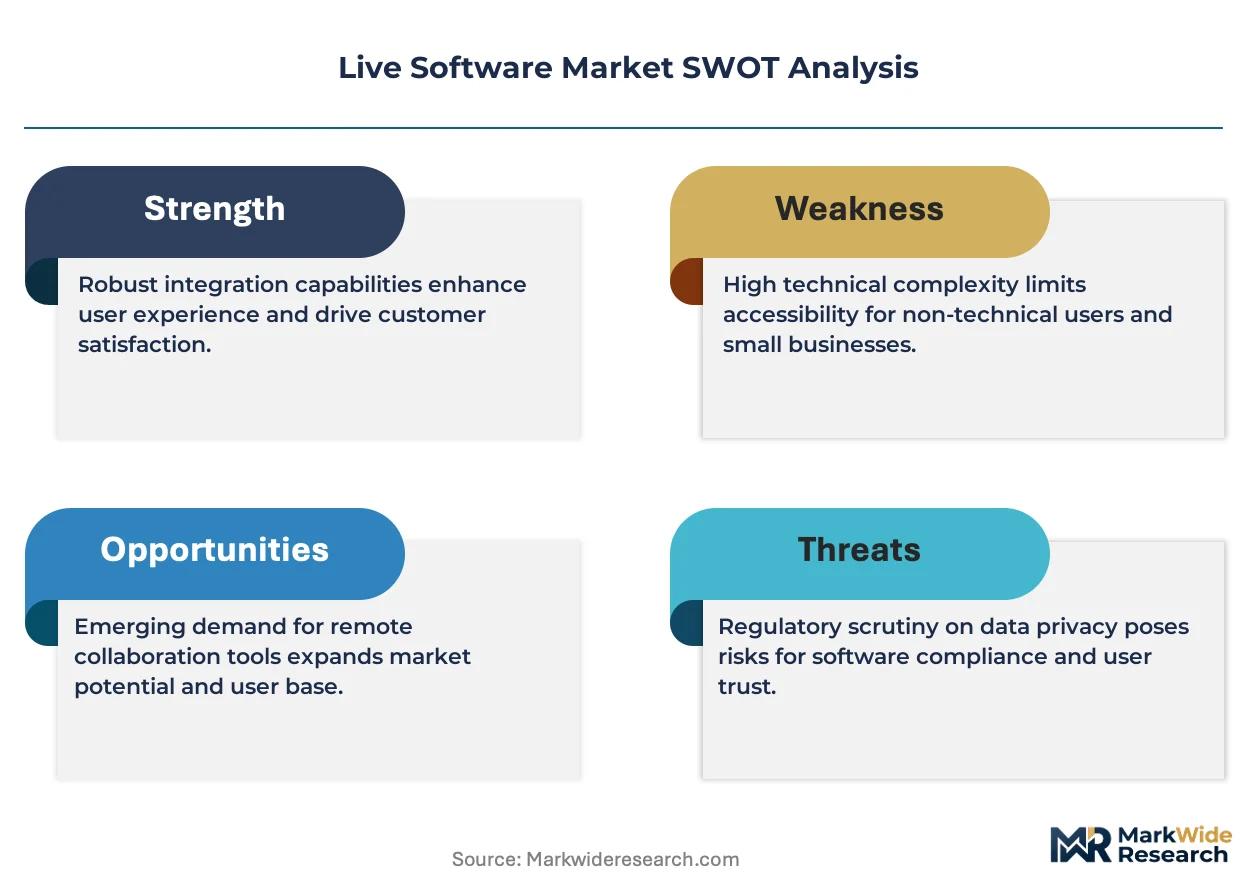
The EU AI Act, GDPR, and the U.S. CLOUD Act create divergent compliance architectures that reshape vendor product roadmaps and customer procurement criteria. HIPAA constraints on healthcare live streaming in the United States further segment addressable market boundaries between general-purpose and vertically certified platforms. Stakeholders must monitor regulatory fragmentation as a primary determinant of which deployment modes and geographic data center footprints will unlock scalable revenue in regulated industries.
Market Dynamics
Enterprise IT departments are replacing legacy conferencing stacks with API-first live collaboration infrastructure, compressing procurement cycles and forcing vendors to rearchitect around sovereign data residency requirements.
Growth Catalysts
- GDPR Article 44 cross-border transfer rules:EU enterprises are mandating EU-based data processing for live streaming workloads, expanding addressable market for regional cloud providers.
- Financial services real-time collaboration:Investment banks and trading floors are deploying sub-500ms latency stacks for synchronous market data sharing and client engagement.
- WebRTC codec optimization:Browser-native real-time communication is eliminating plugin dependencies and collapsing deployment friction for mid-market buyers.
Market Restraints
- GPU and edge compute input costs:Real-time video encoding workloads depend on NVIDIA and AMD accelerator availability, exposing margins to semiconductor supply volatility.
- Transatlantic cable concentration:Low-latency streaming between Europe and North America relies on a handful of subsea routes, creating single-point-of-failure risk for synchronous applications.
- H.266/VVC patent pool complexity:Next-generation codec licensing from Access Advance and MPEG LA is fragmenting royalty structures and delaying adoption roadmaps.
Strategic Opportunities
- India's Digital India Act implementation:Data localization mandates for government and financial services are creating captive demand for domestic live software infrastructure.
- AI-generated live content moderation:Convergence of real-time streaming with transformer-based classification models is opening automated compliance tooling for scaled broadcasts.
- Direct-to-cloud procurement channels:Hyperscaler marketplaces are disintermediating traditional systems integrators and compressing sales cycles for standardized API bundles.
Industry Challenges
- WebRTC engineering talent scarcity:Specialized low-latency protocol development expertise concentrates in a handful of technical hubs, inflating compensation and slowing product iteration.
- FedRAMP and StateRAMP certification timelines:US government cloud authorizations require 12-18 month assessment cycles, gating public sector revenue for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Software Market |
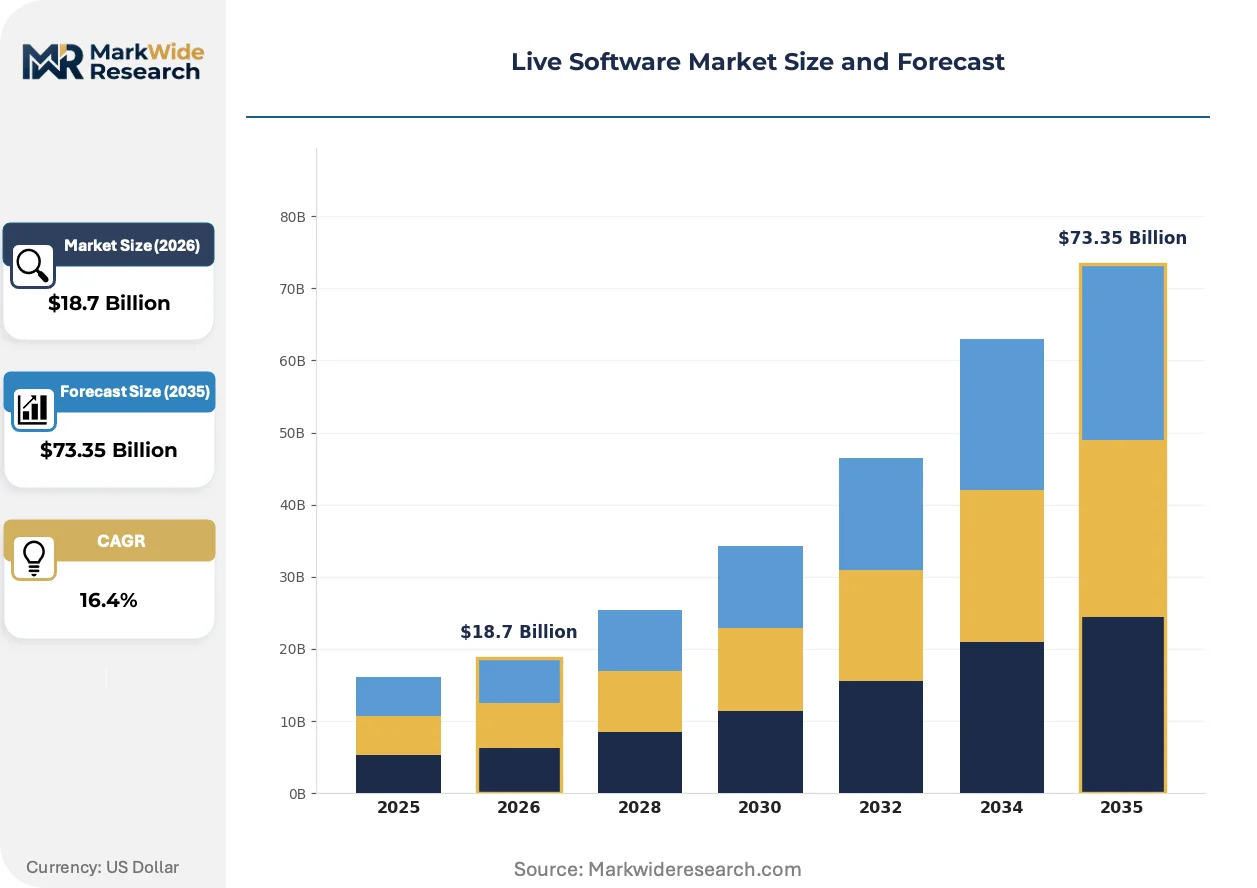
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise Solution: Video Conferencing, Project Management, Collaboration Tools, Customer Support End User: Small Businesses, Enterprises, Educational Institutions, Government Agencies Application: Remote Work, Online Learning, Event Streaming, Customer Engagement |
| Companies Covered | IBM, Brightcove, Kaltura, Vimeo, Edgio, Wowza Media Systems, Dacast, Haivision, Panopto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Software Market Trends and Innovations
Monolithic streaming stacks are fragmenting into composable microservices, enabling buyers to assemble best-of-breed pipelines while forcing incumbents to defend integration value.
WebRTC is decomposing traditional broadcast infrastructure by embedding real-time peer-to-peer connectivity directly into browsers and mobile operating systems. Media enterprises and enterprise IT departments are adopting WebRTC-native workflows for internal communications and customer-facing broadcasts. This decomposition is compressing addressable market for dedicated hardware encoders and collapsing the traditional broadcast supply chain into software-defined layers.
The EU AI Act risk classification framework is mandating human oversight and transparency logging for AI-powered live content moderation and automated captioning systems. Vendors must now maintain audit trails and bias documentation for real-time classification models deployed in European jurisdictions. Healthcare and financial services broadcasters face the steepest compliance burdens, driving demand for explainable AI tooling in live production stacks.
Enterprise buyers are unbundling after-sales support from core platform licenses, preferring consumption-based professional services and community-driven troubleshooting. This fragmentation is disrupting traditional vendor support revenue models and elevating the importance of developer documentation quality and open-source ecosystem health. North American Fortune 500 firms are leading this disaggregation, pressuring vendors to publish granular API reference architectures and self-service migration tooling.
Live Software Market Segmentation
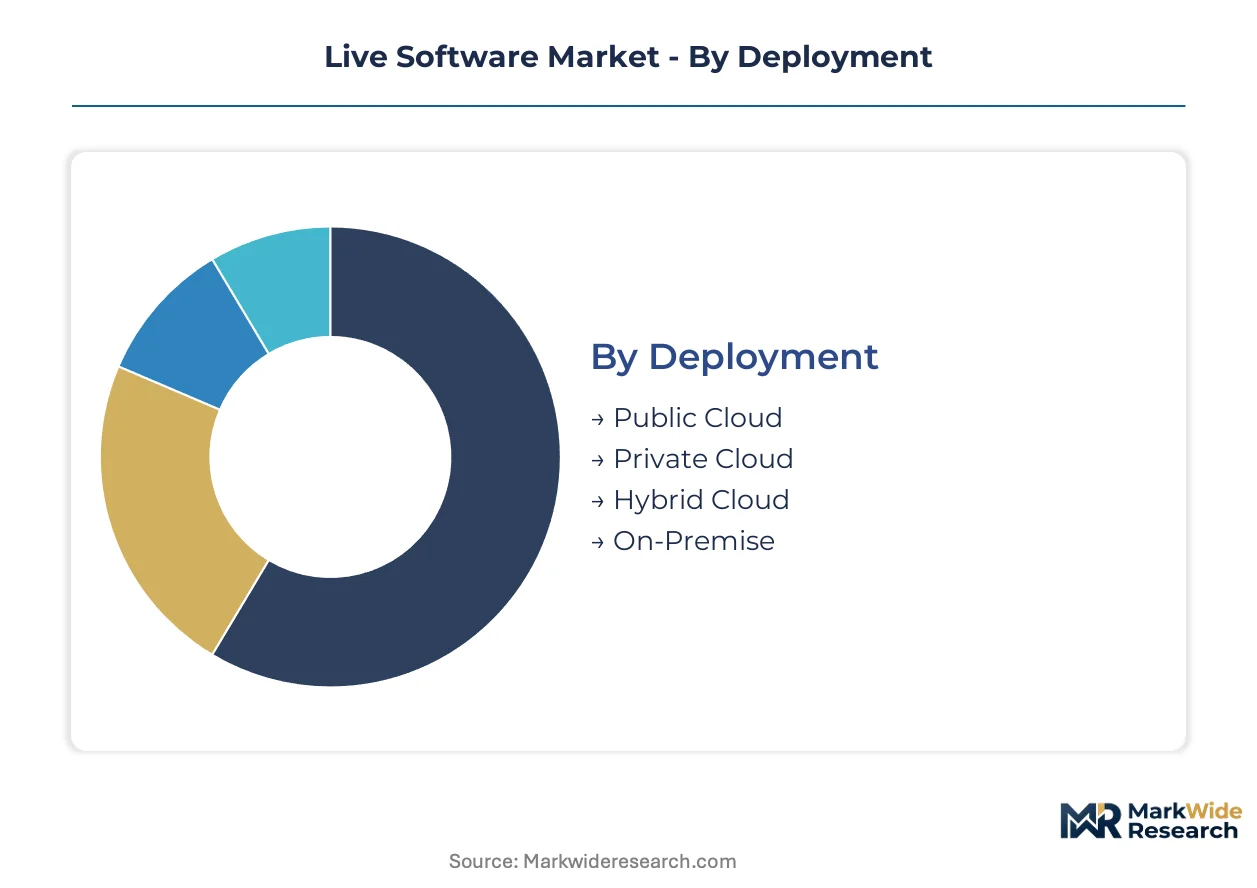
Live software procurement patterns diverge sharply across deployment modes and end-user scale, with regulatory data residency requirements fragmenting what was once a cloud-dominated supply base. Understanding segment substitution dynamics reveals which technology stacks face imminent displacement versus sustained incumbent protection.
Deployment:
Public cloud deployments face the most acute substitution pressure from sovereign infrastructure mandates, while on-premise installations confront obsolescence risk from browser-native streaming protocols.
- Public Cloud:Elastic compute provisioning enables burst capacity for concurrent viewer spikes exceeding 100,000 streams. Financial services firms in Frankfurt and Singapore are migrating workloads to EU and APAC sovereign zones under GDPR Article 44 and local data localization statutes, compressing pure public cloud growth in regulated segments.
- Hybrid Cloud:Split-stack architectures partition real-time encoding at the edge while archiving to centralized object storage. Healthcare systems across Germany and Japan select hybrid configurations to satisfy HIPAA and PMDA clinical data retention rules without sacrificing elastic scale for external-facing broadcasts.
- Private Cloud:Dedicated infrastructure serves defense contractors and intelligence agencies with air-gapped security requirements. FedRAMP and StateRAMP certification timelines of 12-18 months limit vendor participation to established platforms.
- On-Premise:Legacy hardware encoders persist in broadcast television master control rooms with decade-long depreciation cycles. WebRTC browser-native workflows are displacing dedicated appliance dependence for mid-market buyers seeking sub-three-second latency without capital expenditure.
Public cloud anchors the volume base while hybrid cloud gains share at the steepest rate.
Solution:
Cost tier stratification separates enterprise-grade API platforms from freemium collaboration tools, with integration depth determining switching economics.
- Video Conferencing:Real-time peer-to-peer and selective forwarding unit architectures deliver synchronous multi-party video with sub-500ms end-to-end latency. Investment banks in London and New York deploy specialized stacks for client-facing market commentary and internal trading floor coordination.
- Collaboration Tools:Persistent workspace integrations combine live video with document co-editing and threaded messaging. North American Fortune 500 firms unbundle these from monolithic suites, preferring API-first assembly of best-of-breed components.
- Project Management:Task-centric platforms embed live status updates and sprint retrospectives within workflow automation. Construction and engineering consultancies in Australia and Canada drive demand for field-to-office synchronous coordination.
- Customer Support:Cobrowsing and live agent video reduce resolution times for complex technical inquiries. E-commerce platforms in South Korea and the UAE deploy these for high-value transaction assistance.
Video conferencing captures the largest revenue pool while collaboration tools expand most quickly through enterprise unbundling.
End User:
Customer type determines procurement sophistication, with government agencies imposing the most stringent certification barriers and small businesses the highest price elasticity.
- Enterprises:Centralized IT procurement teams negotiate multi-year enterprise license agreements with custom SLA terms. German automotive manufacturers and Japanese electronics conglomerates mandate EU and domestic data center footprints for workforce collaboration.
- Government Agencies:Sovereign cloud requirements and classified network integration dominate vendor selection. India's Digital India Act implementation is creating captive demand for domestic infrastructure providers serving public sector live streaming.
- Educational Institutions:Learning Management System integration requirements concentrate procurement around platforms with LTI Advantage certification. North American and European campuses extend synchronous lecture capture and virtual office hours.
- Small Businesses:Self-service onboarding and consumption-based pricing predominate, with browser-native WebRTC solutions eliminating IT administration overhead. Freelance consultants and professional services micro-firms across Brazil and Mexico adopt these for client presentations.
Enterprises dominate current spending while government agencies present the steepest expansion trajectory through digital transformation mandates.
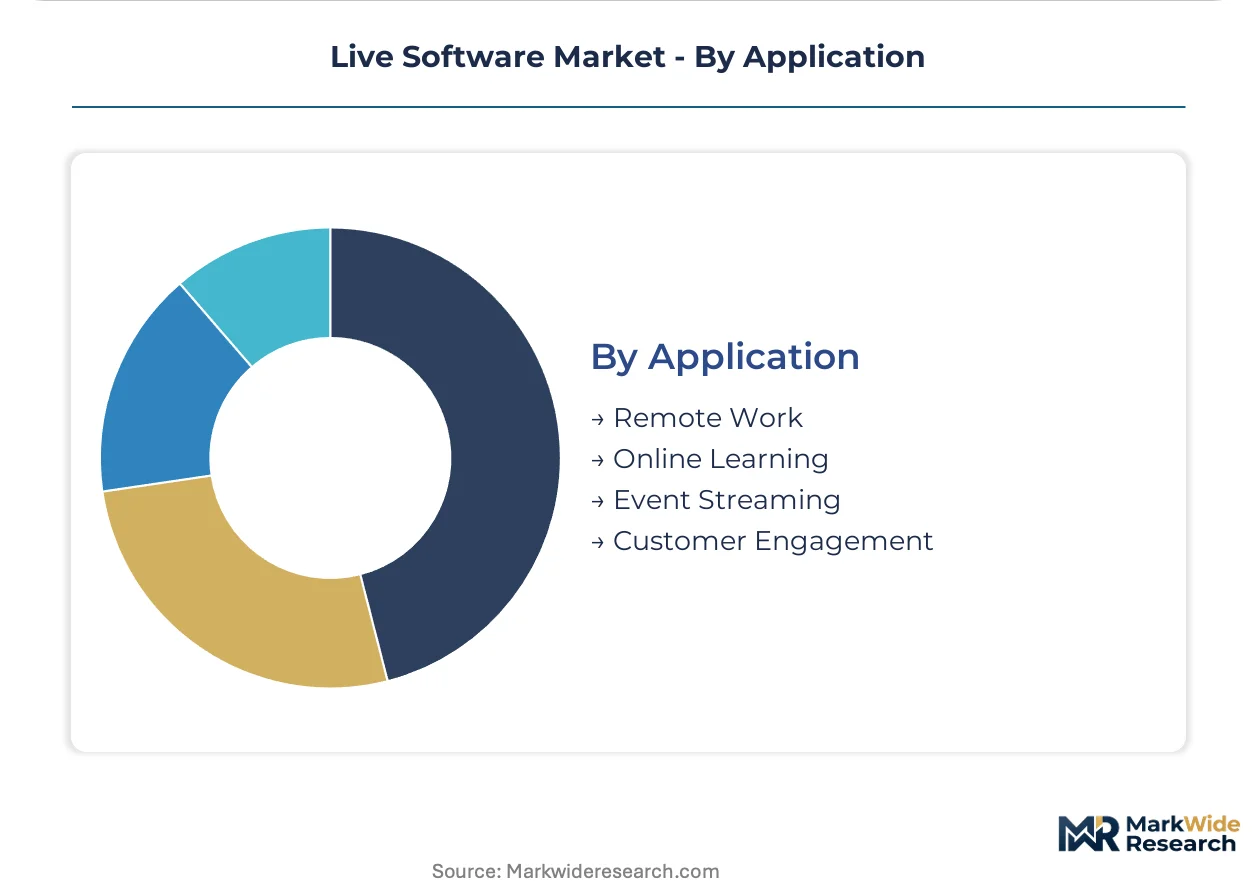
Application:
Volume concentration in pandemic-accelerated use cases is shifting toward purpose-built vertical deployments as generic remote work tools mature.
- Remote Work:Distributed workforce enablement spans synchronous standups, asynchronous video messaging, and virtual watercooler spaces. Technology sector employers in Seattle, Bangalore, and Tel Aviv compete on collaboration stack sophistication for engineering talent retention.
- Online Learning:Credential-bearing programs and corporate training departments require proctoring integration and engagement analytics. Accredited universities in the United Kingdom and Australia face TEF and TEQSA quality assurance scrutiny for virtual delivery equivalence.
- Event Streaming:Hybrid conference formats combine in-person production with global digital audiences. Trade show organizers in Las Vegas and Frankfurt deploy specialized low-latency stacks for real-time Q&A and networking matchmaking.
- Customer Engagement:Shoppable livestreams and product launches integrate commerce transactions with broadcast interactivity. Luxury brands in Milan and Paris deploy these for exclusive collection reveals to high-net-worth client segments.
Remote work retains the largest installed base while customer engagement climbs the fastest through retail media network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a factor of three, reflecting divergent procurement sophistication and regulatory burden. German enterprises pay premiums for sovereign cloud compliance that Asian buyers rarely encounter. Japanese buyers demand sub-500ms latency guarantees that reshape vendor cost structures.
United States
Investment banks in Manhattan and technology firms in Seattle drive demand for API-first live collaboration stacks. HIPAA constraints on healthcare live streaming segment the addressable market between general-purpose and vertically certified platforms. The San Francisco Bay Area concentration of WebRTC engineering talent inflates compensation and slows product iteration for vendors without established development centers.
Germany
Automotive manufacturers in Stuttgart and Munich mandate EU-based data processing for workforce collaboration under GDPR Article 44. The EU AI Act risk classification framework imposes human oversight requirements on AI-powered live content moderation deployed in European jurisdictions. Frankfurt's financial services cluster deploys hybrid cloud configurations to satisfy clinical data retention rules without sacrificing elastic scale.
Japan
Electronics conglomerates in Tokyo and Osaka drive procurement of low-latency streaming infrastructure for synchronous market data sharing. PMDA clinical data requirements segment healthcare live streaming from general enterprise applications. The Nagoya manufacturing corridor extends Learning Management System integrations for virtual training across automotive supplier networks.
India
The Digital India Act implementation creates captive demand for domestic live software infrastructure serving government and financial services. Data localization mandates restrict cross-border processing for public sector workloads. Bangalore's technology services cluster and Mumbai's financial district concentrate procurement of browser-native WebRTC solutions for mid-market buyers.
United Kingdom
Accredited universities in London and Edinburgh face TEF quality assurance scrutiny for virtual delivery equivalence in credential-bearing programs. The Information Commissioner's Office enforces GDPR compliance for student data processing in live streaming workloads. The Cambridge technology corridor hosts specialized vendors serving financial services real-time collaboration requirements.
Live Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with protocol optimization specialists commanding premium pricing against commodity API providers. The market structure consolidates around three tiers: hyperscaler-backed platforms with elastic capacity, vertical specialists with regulatory certifications, and open-source-native challengers with developer community traction. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion into sovereign cloud zones.
Within the enterprise infrastructure tier, IBM exemplifies hybrid deployment credibility through its established cloud architecture relationships. Brightcove occupies a position representing specialized video delivery API dominance in media and entertainment workflows. Kaltura sits within the educational technology specialist archetype, anchoring procurement decisions across North American and European campus deployments.
| Leading Market Players |
|---|
| IBM |
| Brightcove |
| Kaltura |
| Vimeo |
| Edgio |
| Wowza Media Systems |
| Dacast |
| Haivision |
| Panopto |
| Others |
Pricing and Supply Chain Analysis
FedRAMP and StateRAMP certification timelines simultaneously gate vendor qualification and stratify pricing tiers across the live software market, compressing supplier pools while enabling premium capture by cleared incumbents serving defense and intelligence agencies. This regulatory scaffolding forces buyers into extended procurement cycles that favor established platforms with amortized compliance investments.
Pricing Analysis
Geographic pricing power spreads by a factor of three between the United States and India, reflecting divergent procurement sophistication and regulatory burden. Subscription-based SaaS tiers dominate, with premium-mid-economy pricing differentiation anchored by certification level and integration complexity. Cost compression in the mid-market tier is intensifying because browser-native WebRTC solutions eliminate hardware dependencies and collapse deployment friction. Small businesses exhibit the highest price sensitivity, while government agencies accept substantial premiums for air-gapped security and sovereign data residency.
Supply Chain Analysis
Port congestion on trans-Pacific routes and container availability constraints inflate inbound logistics costs for edge compute hardware destined for live encoding clusters. Supply concentrates in Taiwan for semiconductor fabrication, the United States for GPU accelerator design, and China for server assembly and networking equipment. Raw material dependencies center on NVIDIA and AMD accelerator availability, high-bandwidth memory modules, and specialized optical transceivers. Single-source vulnerability in GPU supply exposes margins to semiconductor foundry allocation decisions. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels, with systems integrator intermediation compressing for standardized API bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live software markets reward service-attach strategies because consumption-based professional services and developer support subscriptions expand faster than core platform licensing revenue. Recurring revenue layers around API integration assistance and sovereign cloud migration consulting outpace hardware-centric growth curves.
For Market Incumbents: Shield installed base relationships through backward integration into edge compute infrastructure and captive supply of specialized encoding hardware. Vertical certification investments in FedRAMP, StateRAMP, and EU sovereign cloud architectures raise switching costs for defense and public sector accounts. Channel control through exclusive systems integrator partnerships defends margin pools against hyperscaler marketplace disintermediation. For New Entrants and Emerging Players: Developer documentation quality gaps among established vendors create white-space opportunities for API-first challengers with community-driven ecosystems. India's Digital India Act implementation presents the most penetrable geography, with data localization mandates forcing procurement toward domestic infrastructure providers. Construction and engineering consultancies in Australia and Canada represent underserved verticals for field-to-office synchronous coordination tools. Go-to-market positioning should emphasize self-service onboarding and consumption-based pricing to bypass lengthy enterprise procurement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sovereign cloud infrastructure deployments, favoring asset-light software layers over hardware-heavy encoding appliance manufacturers. Long-term viability over the coming decade hinges on regulatory certification moats rather than pure technology differentiation. Acquisition targets should display established FedRAMP or GDPR Article 44 compliance footprints with expanding government agency revenue streams. The signal to watch is hyperscaler marketplace revenue share crossing threshold levels that indicate disintermediation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first assembly of best-of-breed components displaces monolithic suite procurement across Fortune 500 firms. |
| Geographic Expansion | EU sovereign zone deployments capture GDPR Article 44 compliance premiums from Frankfurt financial services clusters. |
| Acquisition of Specialist Firm | WebRTC engineering talent concentration in San Francisco and Tel Aviv justifies targeted capability purchases. |
| Strategic Partnership | Systems integrator alliances defend integration value against hyperscaler marketplace compression. |
| Product Launch | AI-powered live content moderation tools address EU AI Act transparency logging requirements for European broadcasters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners across enterprise technology deployments, and secondary validation through SEC filings, hyperscaler capex disclosures, regulatory submission databases, and trade flow records. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators established market boundary conditions.
Across the projection horizon, the analytical framework modeled deployment mode, organization scale, vertical industry, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs derived from historical trajectory analysis and technology diffusion curve positioning. Industry-specific forecast inputs incorporated WebRTC codec adoption rates and sovereign cloud infrastructure buildout timelines.
Underlying assumptions cover regulatory stability in data localization regimes and sustained GPU supply availability, with deviation risk concentrated in semiconductor foundry allocation shocks and transatlantic cable infrastructure disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
G Suite Technology Services Market
Software & Services
US Digital Marketing Software Market
Software & Services
Plant Design Software Market
Software & Services
Application Virtualization Market
Software & Services
Human Identification Analysis Software Market
Software & Services
SRM Software Market
Software & Services
Global UIUX Software Market
Software & Services
India Software Services Export Market
Software & Services
Global Recipe Apps Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Global Business Software Market
Software & Services
Computer Backup Software Market
Software & Services
Search and Discovery Software Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Poultry Farm Management Software Market