
 Automotive Dealership Software Market | 2026-2036
Automotive Dealership Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Dealership Software Market Insights
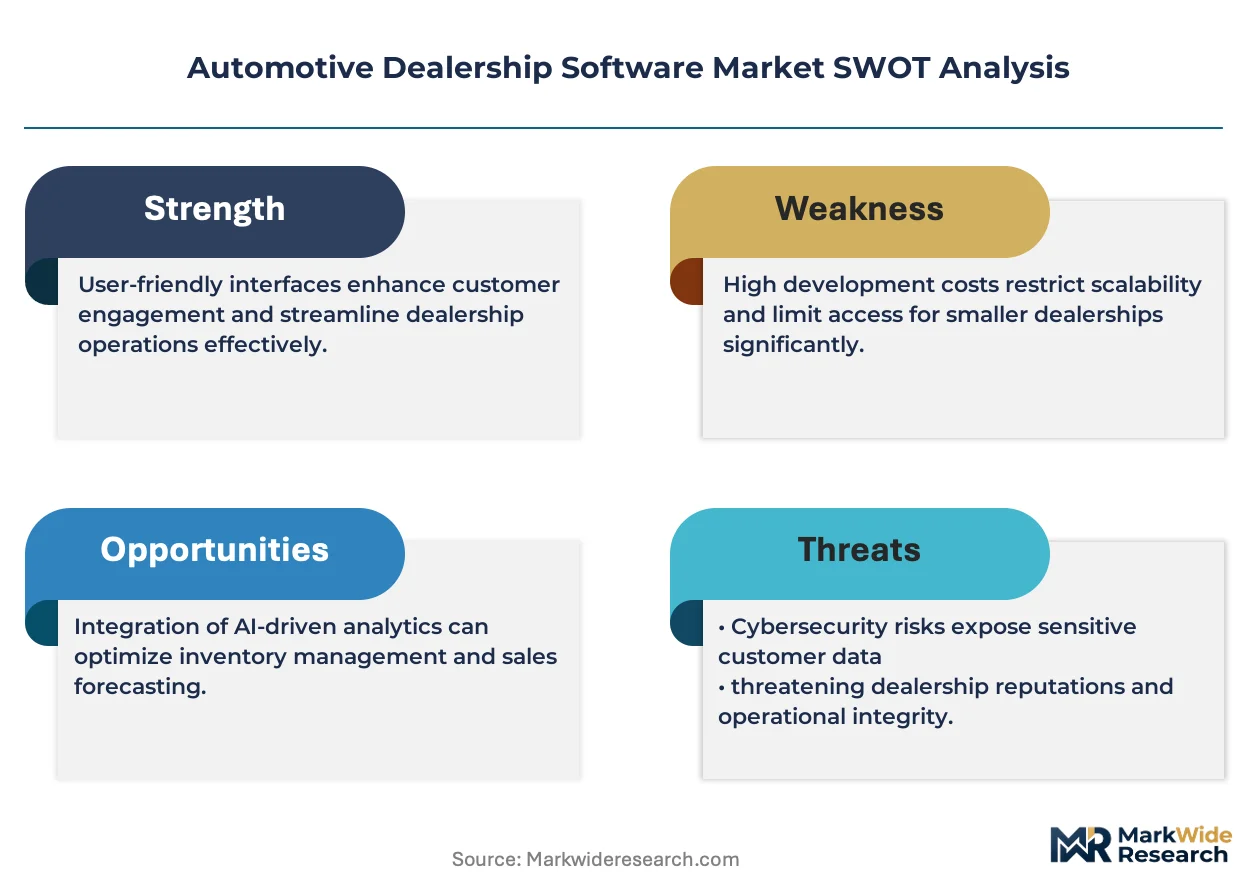
Franchised dealer groups are unwinding their historical preference for monolithic on-premises systems as independent dealers and online retailers gain procurement influence. Cox Automotive leverages vertical integration across digital retailing and financing workflows to sustain platform stickiness. CDK Global anchors its position through deep DMS penetration across tier-one dealer networks. Reynolds and Reynolds differentiates via proprietary data architectures that control sensitive customer and vehicle records.
Automotive dealership software encompasses integrated digital platforms that manage vehicle inventory, customer relationships, financing, and service operations through centralized databases with real-time synchronization across showroom, service bay, and online channels. Its primary commercial purpose is to compress transaction cycles and unify fragmented operational workflows within retail automotive environments. Cloud-based deployment is capturing the fastest expansion as dealers shed capital-intensive server infrastructure, while CRM modules concentrate margin pools through recurring subscription models and high switching costs. API integration layers are maturing rapidly as OEMs mandate standardized data exchange protocols with their retail networks.
NHTSA guidelines on connected vehicle data security and FTC Safeguards Rule requirements for customer financial information are compelling dealers to upgrade software architectures with embedded compliance controls. ISO 27001 certification and SOC 2 attestation are becoming baseline prerequisites for vendor selection in enterprise procurement cycles. Stakeholders must monitor how OEM direct-to-consumer sales channels reshape the dealer software value chain and prioritize platforms that accommodate hybrid retail models.
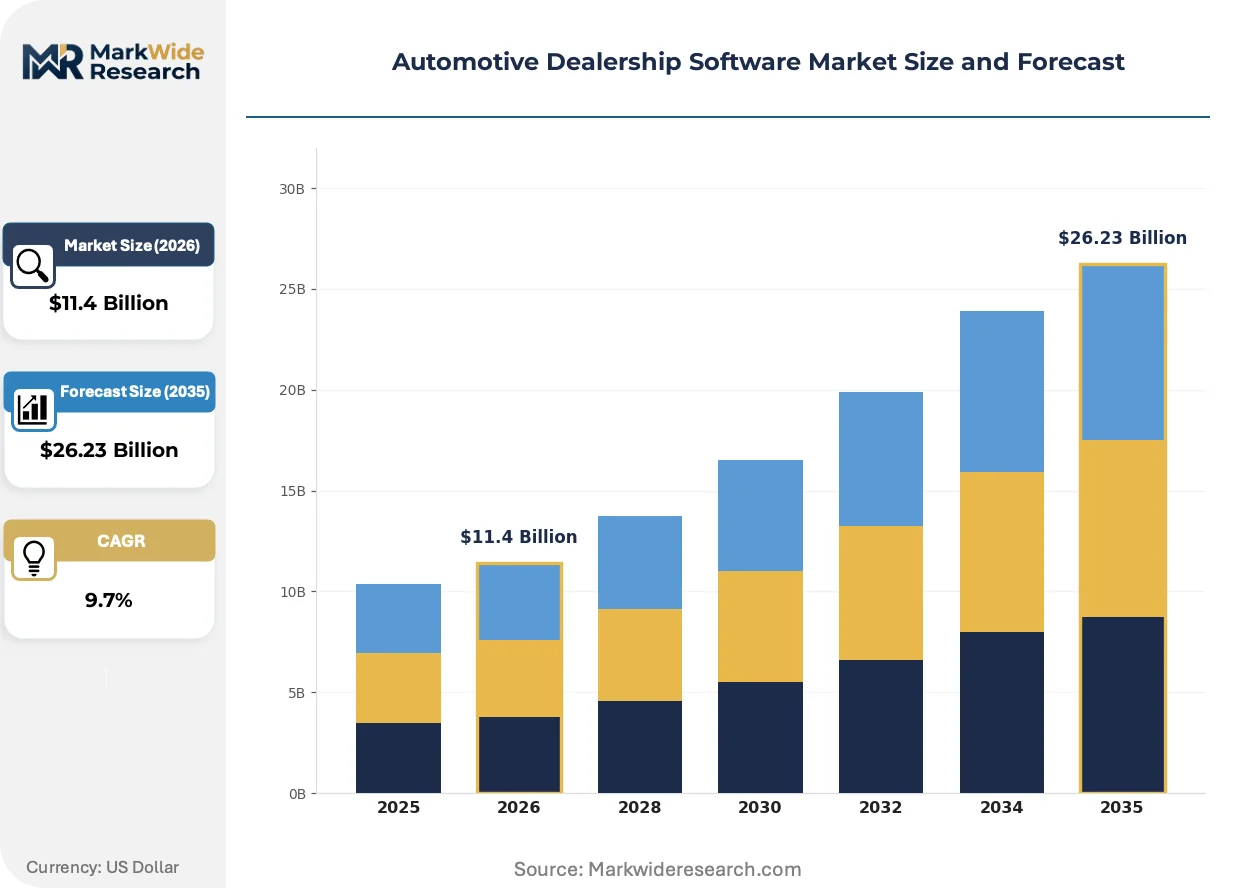
Market Dynamics
Cloud-native architectures are displacing legacy on-premises dealer management systems as independent dealer groups and digital-native retailers gain procurement influence, forcing incumbent vendors to rearchitect delivery models.
Growth Catalysts
- NHTSA Cybersecurity Mandates:Connected vehicle data protection requirements are compelling dealers to adopt compliant software stacks with embedded security controls, accelerating replacement cycles for outdated systems.
- API Standardization:OEM-mandated data exchange protocols are maturing integration layers between dealership platforms and manufacturer networks, reducing friction in multi-brand retail environments.
- Independent Dealer Consolidation:Mid-sized dealer groups in the United States are pooling procurement power to demand cloud-based solutions with lower capital requirements and faster deployment timelines.
Market Restraints
- Data Migration Complexity:Proprietary data architectures at established vendors create switching costs that lock tier-one dealer networks into legacy systems despite functional limitations.
- Compliance Certification Delays:ISO 27001 and SOC 2 attestation timelines stretch vendor sales cycles, particularly for smaller software providers lacking dedicated compliance infrastructure.
- Hybrid Retail Integration:OEM direct-to-consumer channels fragment data flows, requiring dealers to maintain parallel systems that increase operational overhead without proportional revenue gains.
Strategic Opportunities
- FTC Safeguards Rule Alignment:Customer financial information protection requirements create demand for embedded compliance modules that vendors can monetize through premium subscription tiers.
- Service Bay Digitization:Predictive maintenance scheduling and parts inventory optimization represent underpenetrated modules within existing dealer relationships, offering expansion revenue.
- Subscription Pricing Migration:Recurring revenue models for CRM and digital retailing components are displacing perpetual licenses, improving vendor cash flow predictability and customer lifetime value metrics.
Industry Challenges
- Cybersecurity Talent Scarcity:Dealers lack in-house expertise to configure NIST-aligned controls, forcing reliance on vendor professional services that strain implementation capacity.
- Multi-Platform Orchestration:Showroom, service bay, and online channel synchronization requires real-time data architecture investments that exceed capital budgets at smaller dealer groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Dealership Software Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRM, DMS, Inventory Management, Marketing Automation End User: Franchised Dealers, Independent Dealers, Online Retailers, Aftermarket Providers Deployment: On-Premises, Cloud-Based, Hybrid, Mobile-Optimized Integration Level: API Integration, Full System Integration, Middleware Solutions, Standalone |
| Companies Covered | Cox Automotive, CDK Global, Reynolds and Reynolds, Dealertrack, Autosoft, Dominion DMS, Tekion, Quorum DMS, DealerSocket, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Dealership Software Market Trends and Innovations
Edge computing architectures are reshaping how dealership software processes vehicle telemetry and customer interactions, compressing latency for real-time inventory and financing decisions.
Mobile-first service advisor applications are miniaturizing core DMS functions for tablet-based deployment in service lanes. Tier-two dealer groups are adopting these stripped-down interfaces faster than enterprise counterparts. This technology is miniaturizing hardware requirements while expanding addressable market segments previously priced out of full platform deployments.
FTC Safeguards Rule amendments are mandating multi-factor authentication and encryption standards for customer financial data stored in dealer systems. Vendors must embed these controls natively or risk disqualification from enterprise procurement cycles. Smaller independent dealers face the steepest compliance burden, driving consolidation toward vendors with pre-certified architectures.
Digital retailing workflows are unbundling the traditional showroom transaction into discrete online steps that customers complete before physical visits. Franchise dealers in the United States are deploying these tools to defend against pure-play online retailers. This behavioral shift concentrates margin pressure on F&I product penetration, requiring software platforms to embed financing pre-qualification and aftermarket presentation earlier in the purchase path.
Automotive Dealership Software Market Segmentation
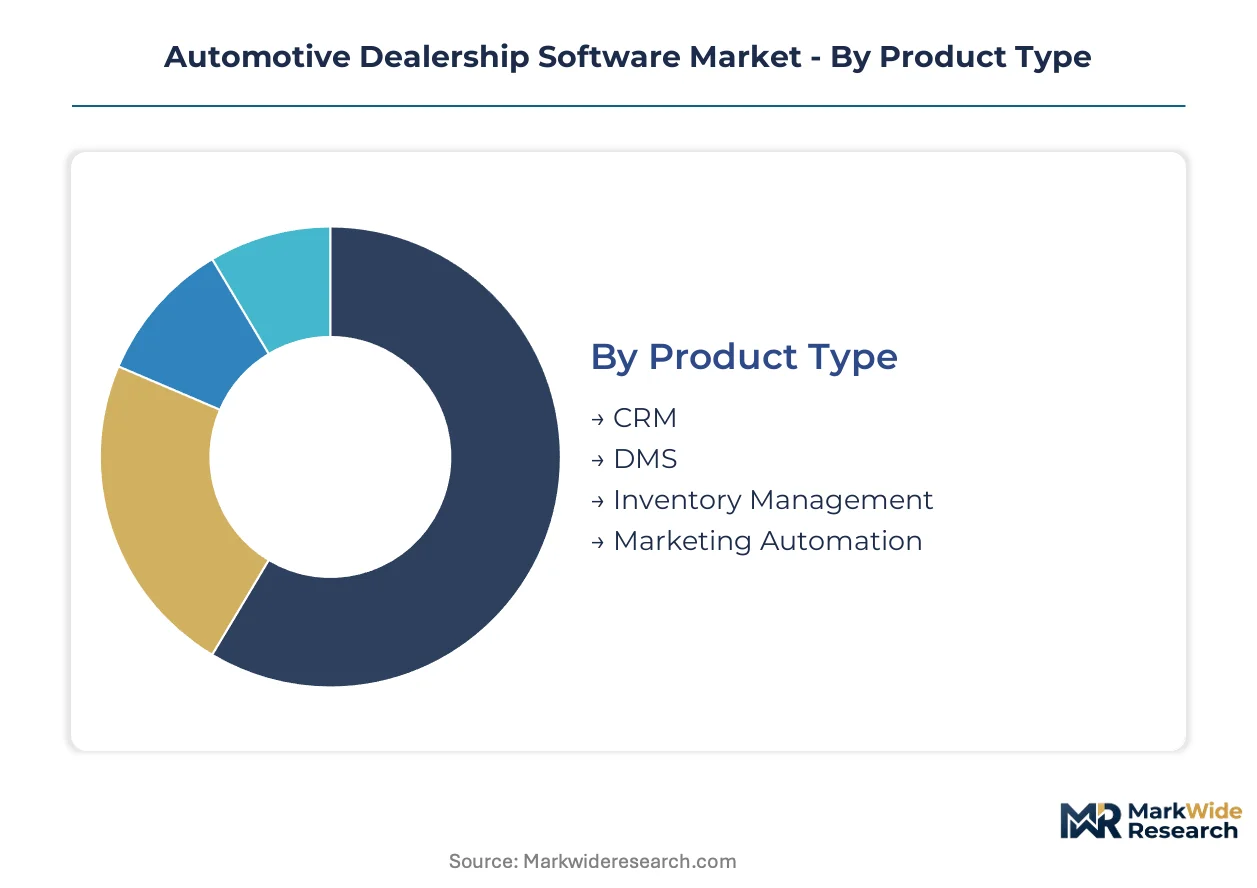
Segmentation in automotive dealership software reveals how procurement power flows through distinct channel configurations. Each dimension exposes different margin pools and switching-cost dynamics that vendors must navigate.
Product Type:
Channel-mix dynamics show CRM modules flowing through subscription channels with recurring revenue, while DMS platforms concentrate in enterprise direct sales with implementation services.
- CRM:Customer relationship platforms capture recurring subscription revenue through SaaS delivery models. United States franchised dealers concentrate procurement here as they defend against digital-native competitors. NHTSA data security mandates embed compliance costs that favor established vendors with pre-certified architectures.
- DMS:Dealer management systems anchor operational workflows across showroom, service bay, and back-office functions. Large dealer groups in the United States dominate procurement, driving consolidation toward cloud-native platforms that shed capital-intensive server infrastructure. FTC Safeguards Rule requirements for customer financial data protection accelerate replacement cycles.
- Inventory Management:Real-time vehicle tracking modules synchronize online and physical lot visibility.
- Marketing Automation:Campaign orchestration tools target lead generation across digital retailing touchpoints.
By volume, DMS leads. By growth pace, CRM is expanding most quickly.
End User:
Cost-tier stratification separates enterprise-grade platforms for franchised networks from leaner solutions serving capital-constrained independents.
- Franchised Dealers:OEM-affiliated retail networks demand deep DMS penetration with manufacturer-mandated data exchange protocols. These buyers concentrate in the United States and command vendor attention through multi-year enterprise contracts. API standardization requirements from OEMs reshape procurement specifications.
- Independent Dealers:Non-affiliated dealer groups pool procurement power to demand cloud-based solutions with faster deployment timelines. Mid-sized groups in the United States are accelerating adoption of mobile-optimized platforms previously priced out of full deployments. Consolidation trends amplify their collective bargaining position.
- Online Retailers:Pure-play digital automotive sellers require modular, API-first architectures.
- Aftermarket Providers:Service-focused operators prioritize service bay digitization and parts inventory optimization.
Franchised dealers dominate revenue concentration. Independent dealers are gaining share fastest.
Deployment:
Application-criticality determines deployment choice: core transaction systems migrate to cloud, while latency-sensitive functions retain on-premises or hybrid configurations.
- Cloud-Based:Scalable architectures displace legacy server infrastructure as dealers shed capital-intensive IT ownership. Independent dealer groups and digital-native retailers drive fastest expansion here. ISO 27001 certification and SOC 2 attestation are becoming baseline prerequisites for vendor selection.
- On-Premises:Legacy installations persist at tier-one dealer networks locked in by proprietary data architectures and high switching costs. These deployments concentrate in established franchised groups with sunk infrastructure investments.
- Hybrid:Mixed architectures balance compliance-sensitive data on-premises with customer-facing tools in cloud.
- Mobile-Optimized:Tablet-based service lane applications miniaturize core DMS functions for tier-two dealer adoption.
Cloud-based deployment leads by new implementation volume. Mobile-optimized solutions show steepest expansion trajectory.
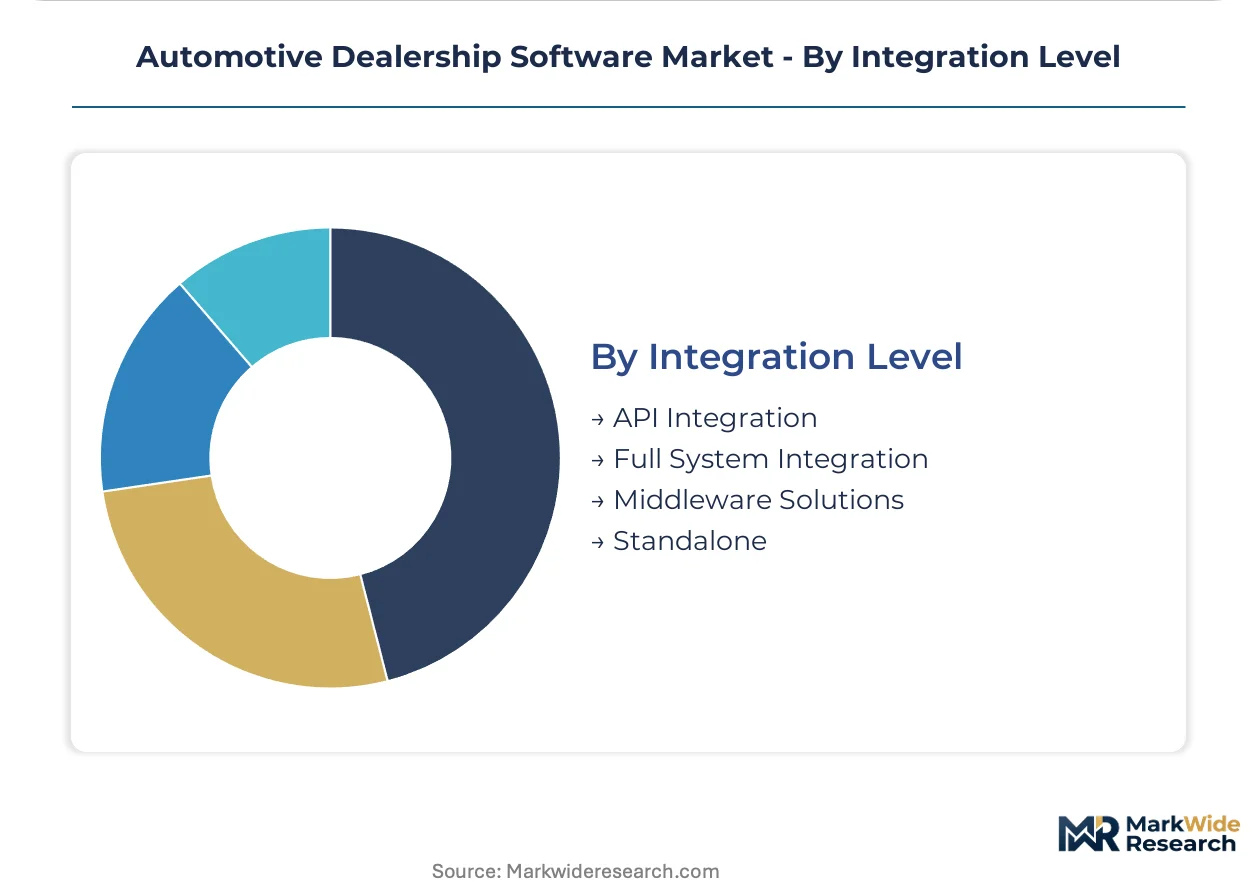
Integration Level:
Customer maturity and technical sophistication separate buyers demanding full-stack unification from those accepting modular point solutions.
- API Integration:Standardized data exchange protocols mature rapidly as OEMs mandate connectivity with retail networks. Multi-brand dealer groups in the United States concentrate demand here to reduce friction across manufacturer relationships. NHTSA cybersecurity guidelines push embedded security controls into these integration layers.
- Full System Integration:End-to-end platform unification targets large dealer groups seeking single-vendor accountability. These implementations require substantial professional services and extended deployment timelines.
- Middleware Solutions:Translation layers connect legacy systems to modern cloud applications.
- Standalone:Point solutions serve niche functions for smaller dealers with limited integration budgets.
API integration leads by implementation count. Full system integration commands highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based software vendors export cloud-native dealership platforms to Canada, Mexico, and select European markets, establishing a transatlantic trade corridor in automotive retail technology.
United States
Large dealer groups concentrate procurement power through multi-year enterprise contracts, driving consolidation toward integrated DMS-CRM suites. NHTSA cybersecurity mandates for connected vehicle data protection compel system upgrades across franchised networks. The Dallas-Fort Worth metroplex hosts expanding development centers for cloud-native platform providers serving tier-one automotive retailers.
Canada
Cross-border dealer groups demand API-standardized platforms compatible with US parent company systems, accelerating cloud migration timelines. Health Canada coordinates with Transport Canada on vehicle data privacy frameworks affecting dealership software requirements. The Greater Toronto Area concentrates implementation partnerships between domestic dealer associations and US-based platform vendors.
Germany
OEM-mandated data exchange protocols reshape procurement specifications for multi-brand dealer groups operating across European markets. GDPR compliance requirements for customer data processing embed additional architectural constraints into vendor selection criteria. Munich and Stuttgart industrial clusters concentrate headquarters of automotive manufacturers driving standardization demands downstream to retail software providers.
United Kingdom
Franchised dealer networks prioritize platforms supporting hybrid retail models as OEM direct-to-consumer channels fragment traditional sales workflows. The Financial Conduct Authority's consumer duty rules extend to dealership financing software, mandating embedded compliance controls. London-based dealer groups lead adoption of digital retailing modules that unbundle showroom transactions into pre-visit online steps.
Japan
Domestic dealer associations resist full cloud migration due to data sovereignty concerns, sustaining demand for hybrid deployment architectures. METI guidelines on automotive data utilization influence software procurement specifications for connected vehicle integration. The Nagoya industrial corridor concentrates tier-one dealer groups with sunk investments in on-premises infrastructure that vendors must accommodate through middleware solutions.
Automotive Dealership Software Market Competitive Landscape
Listed leaders compete with private specialists across capital structure, forcing divergent growth strategies around acquisition pace versus organic R&D investment. The vendor base concentrates around three tiers: legacy incumbents with deep DMS penetration, cloud-native challengers with API-first architectures, and vertical specialists targeting service bay digitization. Dominant competitive moves include strategic partnerships with OEMs for data exchange standardization and portfolio diversification into financing workflow modules.
Within the legacy incumbent tier, Cox Automotive, CDK Global, and Reynolds and Reynolds exemplify entrenched positioning through proprietary data architectures and multi-decade dealer relationships. These US-based entities occupy positions sustained by high switching costs at tier-one franchised networks, though cloud-native challengers like Tekion represent the architectural direction independent dealer groups increasingly favor. The competitive tension between these archetypes concentrates on migration pathways for dealers locked into on-premises infrastructure.
| Leading Market Players |
|---|
| Cox Automotive |
| CDK Global |
| Reynolds and Reynolds |
| Dealertrack |
| Autosoft |
| Dominion DMS |
| Tekion |
| Quorum DMS |
| DealerSocket |
| Others |
Pricing and Supply Chain Analysis
Multi-year enterprise subscription contracts with tier-one dealer groups lock in both cloud infrastructure access and predictable cost visibility across the deployment cycle. These contractual structures concentrate procurement power among large United States dealer networks while compressing margins for vendors serving smaller independent groups without comparable volume leverage.
Pricing Analysis
Legacy on-premises DMS platforms command premium maintenance fees against cloud-native alternatives priced through SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade implementations with dedicated compliance modules from stripped-down mobile-optimized solutions. Cost compression in the independent dealer segment is intensifying because mid-sized groups pool procurement power to demand faster deployment timelines. Franchised dealer networks show lowest price sensitivity due to OEM-mandated system requirements and high switching costs.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates hardware delivery costs for on-premises server deployments serving legacy dealer networks. Software development talent concentrates in the United States, India, and Ireland, with cloud infrastructure provisioning anchored in hyperscaler data centers across North America and Europe. The supply chain rests on specialized cybersecurity certification bodies for ISO 27001 and SOC 2 attestation. Single-source vulnerability exists in API standardization protocols controlled by OEM technical committees. Distribution runs through direct enterprise sales teams for tier-one accounts and channel partners serving independent dealer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward independent dealer groups as consolidation amplifies their collective procurement influence, fragmenting the historical dominance of tier-one franchised networks.
For Market Incumbents: Secure cloud-native platform certifications ahead of NHTSA cybersecurity mandate enforcement timelines. Deepen API integration partnerships with OEM technical committees to control data exchange standardization. Incumbent vendors must accelerate migration pathway development for dealers locked in proprietary on-premises architectures before independent challengers capture replacement cycles. For New Entrants and Emerging Players: Anchor in mobile-optimized service bay digitization modules where tier-two dealer groups face the steepest compliance burden under FTC Safeguards Rule amendments. The independent dealer segment offers the most penetrable entry point due to lower switching costs and faster procurement decisions. A channel partner go-to-market strategy accelerates reach without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Cloud-native challengers with pre-certified compliance architectures represent the highest-conviction acquisition target archetype for portfolio positioning. Long-term viability hinges on platforms accommodating hybrid retail models as OEM direct-to-consumer channels reshape dealer software requirements. Watch NHTSA enforcement action timing as the critical inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies DMS, CRM, and digital retailing workflows under single vendor accountability for large dealer groups. |
| Acquisition of Specialist Firm | Captures service bay digitization capabilities that expand recurring revenue within existing dealer relationships. |
| Strategic Partnership | Secures OEM-mandated API standardization access that reduces friction in multi-brand retail environments. |
| Geographic Expansion | Establishes Canadian and Mexican implementation capacity to serve cross-border dealer group requirements. |
| Product Launch | Introduces embedded FTC Safeguards Rule compliance modules monetizable through premium subscription tiers. |
Research Methodology
A spread of perspectives from dealership operations executives, OEM platform integration specialists, software vendor product managers, and cybersecurity compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, NHTSA regulatory dockets, dealer association procurement surveys, and hyperscaler cloud service disclosures. Bottom-up deployment estimates across cloud-native and on-premises configurations triangulated with top-down market sizing from vendor revenue disclosures.
Segmentation dimensions modeled include deployment architecture, dealer group size tier, integration complexity level, and regional regulatory framework variation across the analysis window. CAGR derivation incorporated replacement cycle acceleration from compliance mandate deadlines, independent dealer consolidation velocity, and OEM direct-to-consumer channel penetration rates. Forecast inputs captured cloud migration capex trade-offs and API standardization protocol adoption curves.
Material uncertainties — NHTSA enforcement timing variability, OEM direct sales channel expansion pace, and cybersecurity talent scarcity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about dealer group consolidation trajectories and compliance cost pass-through viability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Taxi Booking Software Market
Software & Services
Media Planning Software Market
Software & Services
Global Data Warehouse Software Market
Software & Services
BFSI Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Managed Information Services Market
Software & Services
APAC Interior Design Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Global CMMS Software Market
Software & Services
Ad Creation Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
UI Design Software Market
Software & Services
Global Church Management Software Market
Software & Services
Performance Management Software Market
Software & Services
E-Invoicing Software Market