
 Global Club Management Software Market | 2026-2036
Global Club Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Club Management Software Market Foresight
The capital-intensity divergence between cloud-native entrants and legacy on-premise incumbents is unwinding competitive dynamics across the sector. MINDBODY leverages extensive third-party integrations to sustain ecosystem lock-in among boutique fitness studios. Jonas Club Software anchors its position through deep specialization in private golf and country club workflows. Virtuagym competes on modular architecture that allows health clubs to assemble capability without full-platform commitment.
Club management software denotes integrated digital platforms that automate membership lifecycle operations, facility scheduling, payment processing, and member communications through centralized databases with API-enabled interoperability. Cloud-based deployment leads solution offering mix as operators prioritize remote accessibility and automatic security patching over capital-heavy server ownership. Event scheduling and billing modules command disproportionate margin pools due to their direct linkage to revenue collection and retention metrics. Health and fitness centers represent the fastest-growing application segment as post-pandemic hybrid service models require flexible booking infrastructure.
GDPR in Europe, HIPAA in the United States, and Australia's Privacy Act collectively mandate encrypted member data handling and explicit consent architectures that elevate compliance costs for smaller vendors. The EU AI Act introduces additional algorithmic transparency requirements for platforms deploying automated member recommendations or dynamic pricing. Stakeholders must monitor regulatory divergence across jurisdictions when evaluating platform portability and data sovereignty provisions.
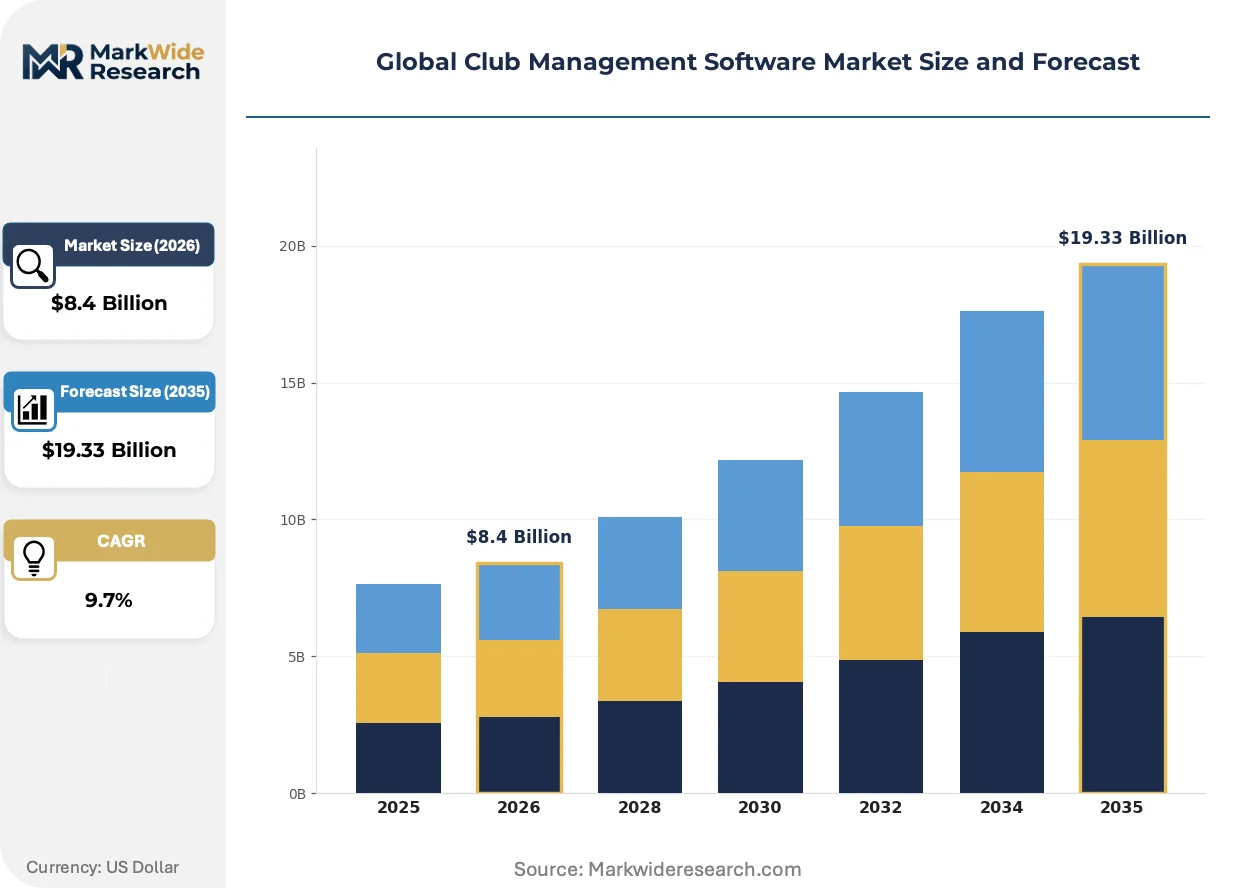
Market Dynamics
Cloud-native architectures are compressing replacement cycles as operators abandon on-premise server ownership for subscription-based accessibility, while GDPR-aligned data governance mandates in Europe force compliance investments that favor established vendors with dedicated legal infrastructure.
Growth Catalysts
- GDPR and EU AI Act:European data governance mandates accelerate platform upgrades as operators seek vendors with pre-built consent architectures and algorithmic transparency documentation.
- Hybrid fitness service models:Health clubs deploying flexible booking infrastructure for virtual and in-person sessions drive demand for modular scheduling modules with API interoperability.
- Payment processing automation:Integrated billing systems reduce administrative overhead and improve cash flow visibility, particularly among boutique fitness studios with limited back-office staff.
Market Restraints
- Compliance cost escalation:HIPAA in the United States and Australia's Privacy Act impose encrypted data handling requirements that elevate operational expenses for smaller software vendors lacking dedicated security teams.
- Legacy system entrenchment:Private golf and country clubs maintain deep customization in incumbent platforms, creating switching friction that slows cloud migration timelines.
- API standardization gaps:Inconsistent interoperability protocols between fitness wearables, access control hardware, and accounting software force expensive custom integration work.
Strategic Opportunities
- Underpenetrated German market:High private club density combined with stringent BDSG data protection enforcement creates demand for GDPR-native platforms with localized hosting options.
- Artificial intelligence convergence:Automated member recommendation engines and dynamic pricing algorithms represent white space for vendors with machine learning capabilities and regulatory compliance frameworks.
- Embedded finance integration:Native lending and insurance products within member management workflows unlock new revenue streams for platforms serving capital-constrained independent studios.
Industry Challenges
- Cybersecurity talent scarcity:Shortages of engineers with healthcare data protection expertise strain vendor capacity to maintain HIPAA and GDPR audit readiness.
- Multi-system integration complexity:Health clubs operating hybrid technology stacks face prolonged deployment timelines when connecting cloud-native modules to legacy access control and accounting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Club Management Software Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Offering: Membership Management, Event Scheduling, Billing & Invoicing, Facility Booking, Communication Tools Application: Sports Clubs, Social Clubs, Health & Fitness Centers, Community Centers, Hobby Clubs End User: Private Clubs, Public Organizations, Educational Institutions, Non-Profit Associations |
| Companies Covered | Active Network, ClubExpress, ClubRunner, MINDBODY, Zen Planner, Glofox, Virtuagym, Jonas Club Software, EZFacility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Club Management Software Market Shifts & Advancements
Platform architectures are fragmenting as buyers reject monolithic suites in favor of composable systems, while regulatory pressure and shifting member expectations reshape how vendors compete on capability depth versus integration breadth.
API-first modular platforms are displacing all-in-one legacy suites as mid-market health clubs assemble best-of-breed scheduling, billing, and engagement tools through standardized interfaces. Operators in Australia and Germany prioritize vendors with pre-certified GDPR and Privacy Act compliance over feature-rich but legally unverified alternatives. This shift compresses margins for incumbents dependent on upgrade revenue from locked-in customer bases.
The EU AI Act introduces mandatory documentation requirements for automated decision-making systems used in member pricing and retention campaigns. Vendors deploying algorithmic recommendations must maintain audit trails and human oversight protocols, elevating development costs but creating differentiation for compliant platforms. Health and fitness centers in France and Germany face the steepest compliance timelines given CNIL and BDSG enforcement precedents.
Subscription fatigue among boutique studio owners is compressing vendor pricing power and accelerating unbundling of previously integrated modules. Operators in the United States increasingly procure scheduling and billing functions from separate specialists rather than accepting bundled discounts, forcing platforms to compete on individual module performance. This pattern is most visible in urban California and New York markets where studio density supports multi-vendor technology stacks.
Global Club Management Software Market Segmentation
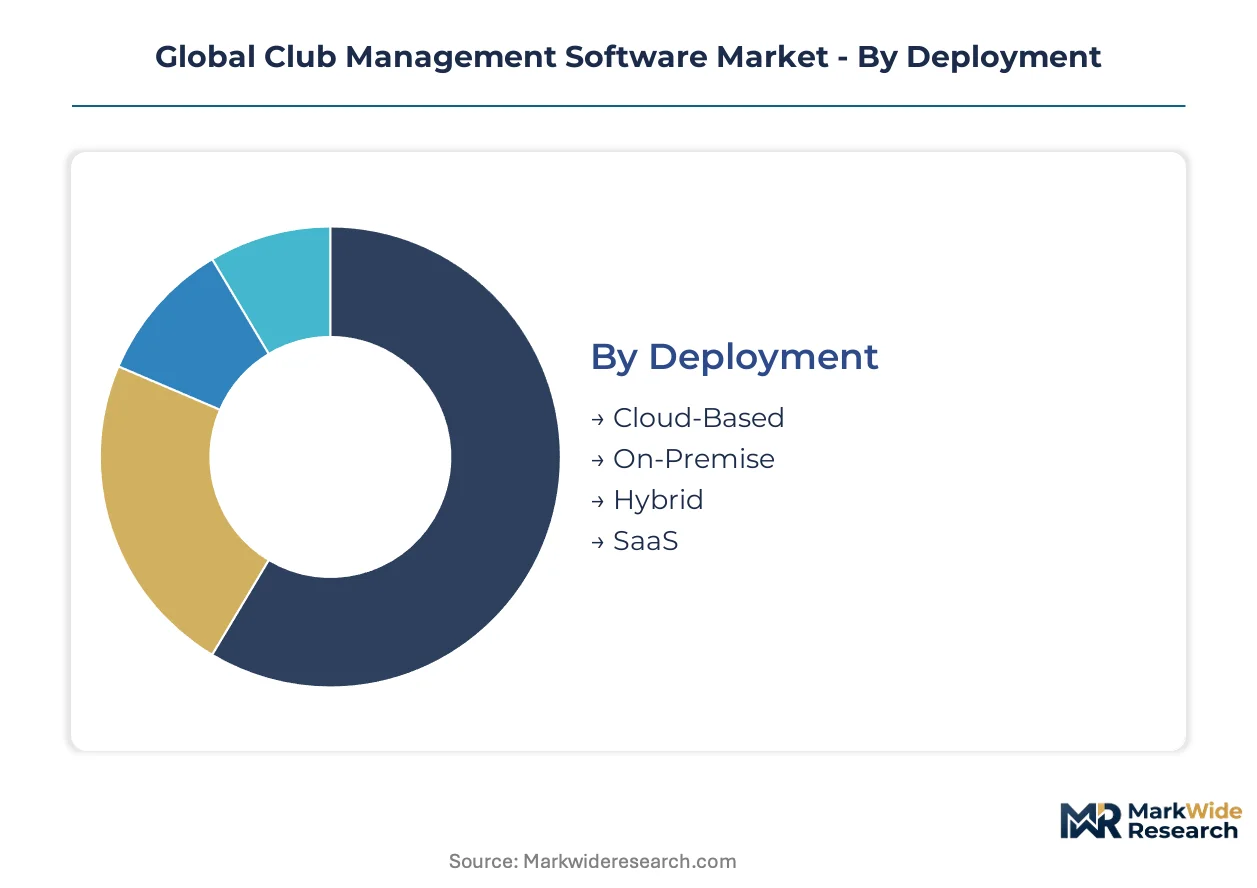
Club management software segments reflect divergent technology maturity and regulatory exposure across deployment models, solution depth, and end-user sophistication. Understanding these splits reveals where vendor investment concentrates and which customer profiles command premium pricing power.
Deployment:
Cloud-native delivery channels dominate new procurement, though hybrid architectures persist where legacy hardware investments constrain immediate migration.
- Cloud-Based:Multi-tenant architectures with automatic patching and remote accessibility serve boutique fitness studios and mid-market health clubs seeking zero server maintenance. Demand concentrates in Germany and Australia where GDPR and Privacy Act enforcement elevate trust in vendor-managed security over self-hosted alternatives.
- SaaS:Subscription licensing with usage-based tiering enables independent studios to scale capability without capital commitment. Operators in California and New York markets favor unbundled SaaS modules over monolithic suites, driving fastest growth among deployment modes.
- Hybrid:Split architectures retain sensitive member data on-premise while pushing scheduling and payments to cloud infrastructure. Private golf clubs in the United States deploy hybrid models to preserve deep customization in legacy systems while capturing mobile booking convenience.
- On-Premise:Perpetual license models with dedicated server ownership persist among country clubs with decade-old platform investments and limited IT staff turnover.
By volume, Cloud-Based leads. By growth pace, SaaS is expanding most quickly.
Solution Offering:
Margin concentration follows revenue-touching modules, with scheduling and billing commanding disproportionate vendor investment relative to administrative tools.
- Billing & Invoicing:Integrated payment processing with automated dunning and cash flow visibility reduces administrative overhead for studios with limited back-office staff. Health and fitness centers in urban United States markets prioritize PCI-compliant billing modules with embedded lending options.
- Event Scheduling:Multi-resource calendar management with API interoperability supports hybrid virtual and in-person service models. Demand from German health clubs accelerates as BDSG-compliant consent architectures become mandatory for member data handling in booking workflows.
- Membership Management:Lifecycle automation from enrollment through retention tracking anchors platform value for social clubs and community centers.
- Facility Booking:Real-time availability management with access control integration serves sports clubs managing high-utilization courts and fields.
- Communication Tools:Automated outreach with preference-based segmentation supports non-profit associations with limited marketing staff.
By revenue contribution, Billing & Invoicing leads. By capability investment, Event Scheduling is gaining share fastest.
Application:
End-use differentiation drives feature prioritization, with fitness operators demanding mobile-first interfaces and social clubs requiring legacy compatibility.
- Health & Fitness Centers:Flexible booking infrastructure for hybrid service models with wearable integration and dynamic class capacity management. Post-pandemic operators in Australia and the United States drive steepest expansion trajectory as member expectations shift toward seamless digital engagement.
- Sports Clubs:Court and field scheduling with league management and referee coordination serves tennis, squash, and multi-sport facilities.
- Social Clubs:Dining reservation integration with member directory privacy controls addresses private club workflows in the United States and Germany.
- Community Centers:Subsidized membership tiering with grant reporting compliance supports municipal operators with constrained technology budgets.
- Hobby Clubs:Lightweight scheduling with minimal administrative overhead serves volunteer-run organizations with episodic meeting patterns.
By installed base, Social Clubs lead. By modernization urgency, Health & Fitness Centers are climbing the fastest.
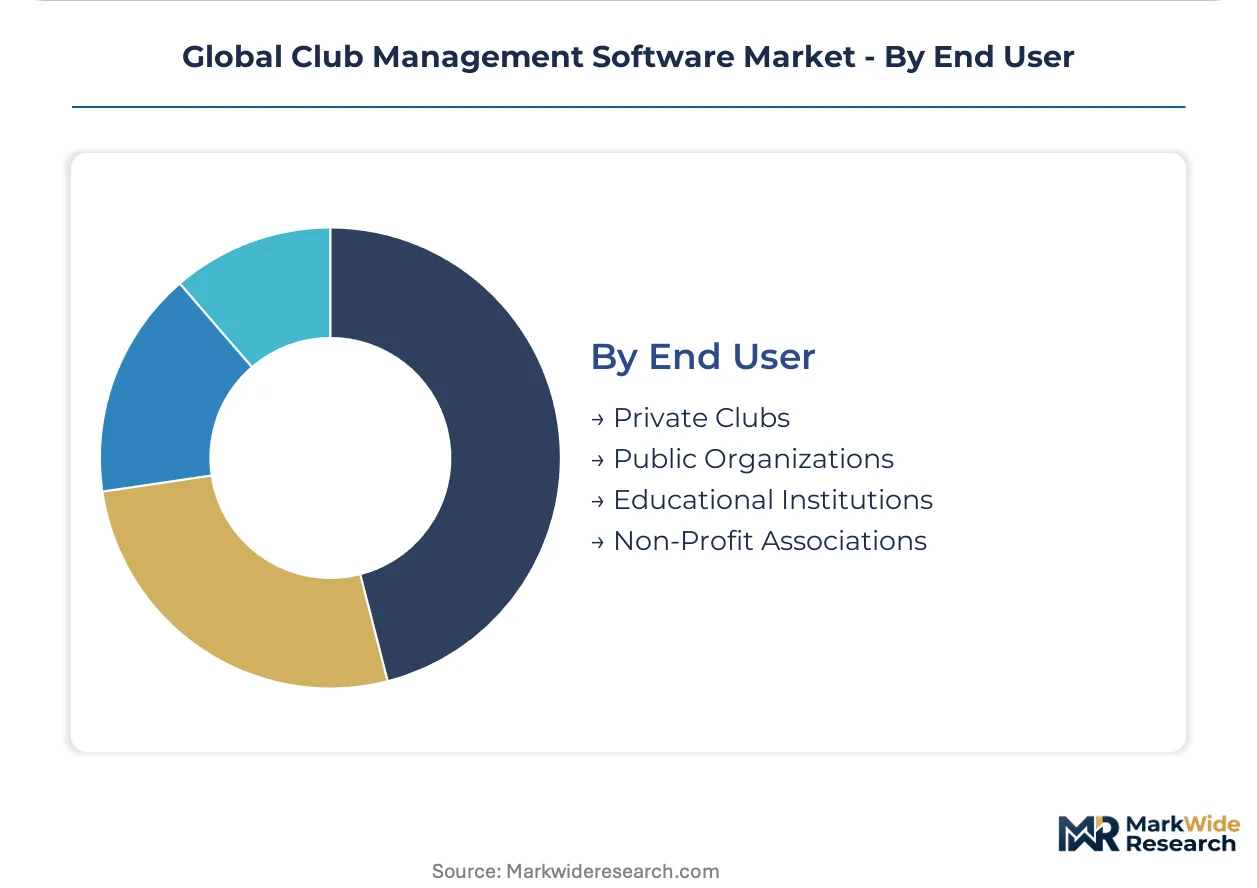
End User:
Procurement authority and compliance sophistication vary sharply across ownership structures, with private clubs demanding customization and public entities requiring audit transparency.
- Private Clubs:Golf and country clubs with dedicated general managers and technology committees evaluate platforms on workflow depth and legacy migration support. Switching friction remains highest in this segment due to deep customization in incumbent systems.
- Educational Institutions:Campus recreation centers with student membership integration and semester-based billing cycles require flexible academic calendar alignment.
- Public Organizations:Municipal recreation departments with open records requirements and competitive procurement mandates prioritize audit trails and vendor diversity certification.
- Non-Profit Associations:Volunteer-governed hobby and special-interest clubs with minimal staff prioritize low-touch implementation and donor management integration.
By contract value, Private Clubs lead. By procurement velocity, Educational Institutions are moving fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity as private clubs prioritize workflow depth over cost minimization, while Australian boutique studios exhibit acute sensitivity to subscription pricing amid fragmented vendor options.
United States
Health and fitness centers in California and New York drive cloud procurement as hybrid service models demand flexible booking infrastructure. HIPAA mandates encrypted member data handling and audit-ready consent architectures that elevate compliance investments. The Los Angeles and Manhattan studio clusters accelerate unbundling of scheduling and billing modules from monolithic suites.
Germany
Private club density in Bavaria and North Rhine-Westphalia sustains demand for specialized workflow platforms with deep customization capabilities. BDSG enforcement through regional data protection authorities mandates GDPR-native hosting with localized server options. Berlin health clubs face compressed upgrade timelines as CNIL-aligned consent architectures become mandatory for member data handling.
Australia
Boutique fitness studios in Sydney and Melbourne prioritize Privacy Act-compliant platforms with pre-certified data sovereignty provisions over feature-rich alternatives. The national privacy regulator mandates encrypted handling of biometric and payment data collected through wearable integrations. Queensland sports clubs drive fastest adoption of modular SaaS architectures with API interoperability.
United Kingdom
Social clubs in London and the Southeast evaluate platforms on legacy migration support and dining reservation integration depth. The Information Commissioner's Office enforces GDPR-aligned consent documentation for automated member communications and retention campaigns. Manchester and Birmingham health clubs accelerate replacement of on-premise systems with cloud-native alternatives.
Canada
Educational institutions in Ontario and British Columbia procure campus recreation platforms with semester-based billing cycles and student membership integration. Health Canada guidelines intersect with provincial privacy statutes to mandate encrypted data handling for university-affiliated fitness centers. Toronto and Vancouver operators prioritize vendors with cross-border data portability for multi-location chains.
Global Club Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium pricing through ecosystem lock-in and the lower tier competing on modular flexibility. Cloud-native entrants compress replacement cycles while legacy incumbents defend entrenched positions in private golf workflows. Two strategic archetypes dominate: vertically integrated platform providers and best-of-breed module specialists. Competitive moves concentrate on M&A to fill capability gaps and strategic partnerships to secure API interoperability.
Within the integrated platform tier, MINDBODY and Jonas Club Software exemplify divergent specialization strategies, with the former anchoring ecosystem lock-in among boutique fitness studios and the latter representing deep workflow customization for private clubs. Virtuagym occupies a position in the modular architecture segment, allowing health clubs to assemble capability without full-platform commitment. These three companies collectively illustrate how competitive positioning splits between breadth-driven and depth-driven value propositions.
| Leading Market Players |
|---|
| Active Network |
| ClubExpress |
| ClubRunner |
| MINDBODY |
| Zen Planner |
| Glofox |
| Virtuagym |
| Jonas Club Software |
| EZFacility |
| Others |
Supply & Pricing Matrix
Subscription-based capacity reservation locks in multi-year SaaS commitments for health clubs and fitness studios, binding price visibility to vendor-managed infrastructure access across GDPR-regulated European markets and HIPAA-governed United States operations.
Pricing Analysis
After-sales service revenue from implementation support and API integration consulting drives lifetime value for vendors serving boutique fitness studios with limited technical staff. Three-tier pricing structure across premium, standard, and economy levels segments by module depth and compliance certification, with GDPR-native platforms commanding premium positioning in Germany. Cost compression in the mid-market SaaS tier is intensifying because unbundling allows operators to procure scheduling and billing from separate specialists. Boutique studios in Australia's urban markets exhibit acute price sensitivity, while private golf clubs in the United States demonstrate lowest elasticity due to workflow customization requirements.
Supply Chain Analysis
Cloud infrastructure concentration in Ireland, Germany, and the Netherlands underwrites data sovereignty compliance for European health club operators navigating BDSG enforcement timelines. Vendor development capacity draws from specialized cybersecurity talent pools in the United States, India, and Eastern Europe, with machine learning engineering for recommendation engines resting on scarce healthcare data protection expertise. Single-source vulnerability in API middleware providers creates deployment risk when connecting scheduling modules to legacy access control hardware. Distribution runs through direct enterprise sales teams for private clubs and self-service digital channels for independent studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud migration cycles are compressing replacement timelines as post-pandemic hybrid service models normalize, positioning the market for sustained expansion through technology refresh waves.
For Market Incumbents: Compound ecosystem lock-in through deeper third-party fitness wearable integrations and pre-certified compliance architectures that elevate switching costs for HIPAA and GDPR-bound operators. Defend against modular disaggregation by unbundling billing and scheduling modules into standalone SaaS tiers while maintaining API interoperability. Capacity addition in German and Australian hosting regions strengthens data sovereignty positioning against cloud-native challengers. For New Entrants and Emerging Players: Anchor in the underpenetrated municipal recreation segment where public procurement mandates and open records requirements favor audit-transparent platforms over legacy incumbents. White-space targets include embedded finance integration for capital-constrained independent studios and AI-driven dynamic pricing for hybrid virtual-in-person service models. Go-to-market execution through channel partnerships with fitness equipment distributors accelerates trust-building in fragmented secondary markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with compliance infrastructure and API-first architectures over point solutions lacking regulatory documentation. Long-term viability hinges on vendors' capacity to maintain audit readiness across diverging jurisdictional requirements without fragmenting development resources. Acquisition target archetype: modular SaaS providers with pre-certified GDPR and Privacy Act compliance and established API marketplaces. Signal to watch: regulatory enforcement timelines in France and Germany accelerating vendor replacement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep MINDBODY and Virtuagym API interoperability reduces custom development for hybrid technology stacks. |
| Acquisition of Specialist Firm | Consolidation of boutique billing module vendors addresses unbundling pressure in California and New York markets. |
| Strategic Partnership | Fitness wearable manufacturer alliances embed scheduling data directly into member-facing mobile applications. |
| Geographic Expansion | Localized hosting in Bavaria and North Rhine-Westphalia satisfies BDSG data protection authority mandates. |
| Product Launch | EU AI Act-compliant recommendation engines with audit trails differentiate vendors in French and German markets. |
Research Methodology
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings on compliance cost structures and replacement cycle timing. Primary fieldwork engaged software vendor product managers, health club operations directors, private club general managers, and data protection officers at regional authorities. Secondary sources encompassed SEC filings from listed platform providers, GDPR enforcement decisions from CNIL and BDSG authorities, and Privacy Act guidance from Australia's national privacy regulator. Bottom-up sizing from individual vendor revenue disclosures triangulates against top-down estimates from aggregate IT spending surveys.
Sensitivity analysis on cloud adoption pace and regulatory enforcement timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include deployment architecture, solution module depth, end-use application, and ownership structure. CAGRs derive from installed base evolution and average contract value trends. Forecast inputs incorporate API standardization progress and cybersecurity talent availability constraints.
Decision-makers should treat outputs as directional under assumptions of sustained hybrid service model adoption and stable regulatory enforcement intensity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act implementation timelines and wearable integration standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Casino Management Systems Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Tech Support Services Market
Software & Services
Construction Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Spain Sports Management Software Market
Software & Services
Binary Drivers Market
Software & Services
Construction and Design Software Market
Software & Services
House Cleaning App Market
Software & Services
Software Release Management Tools Market