
 Remote Sensing Software Market | 2026-2036
Remote Sensing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Sensing Software Market Intelligence
Platform bundling is consolidating vendor offerings across image processing, GIS integration, and machine learning modules into unified subscription tiers. Esri leverages its ArcGIS ecosystem to anchor enterprise accounts with deep geospatial workflows. Hexagon AB sustains competitive pressure through specialized sensor-to-software integration for defense and industrial clients. Trimble Inc. dominates precision agriculture channels with field-calibrated spectral tools that tie directly to farm equipment fleets.
Remote sensing software encompasses algorithms and platforms that process, analyze, and interpret electromagnetic radiation data captured by satellites, aircraft, or drones, typically handling multispectral and hyperspectral imagery with spatial resolutions ranging from sub-meter to kilometer scale for terrestrial observation. The technology serves commercial, scientific, and governmental users who require actionable intelligence about land cover, atmospheric conditions, or resource distributions without physical site contact. Commercial software and proprietary platforms capture the dominant share of revenue as defense agencies and large enterprises prioritize security-certified, fully supported deployments over open-source alternatives. Image processing and GIS integration represent mature, high-volume segments where established vendors extract recurring maintenance fees, while machine learning and data analytics emerge as faster-growing capability layers where specialized entrants compete on algorithmic accuracy.
The EU Green Deal and REACH frameworks compel European environmental agencies to adopt standardized spectral monitoring protocols for carbon accounting and pollution tracking. The US EPA and FAA jointly shape market access through emissions verification requirements and unmanned aerial system flight authorizations that determine which remote sensing platforms can operate commercially. China’s MEE enforces dual carbon goals through satellite-based environmental compliance audits that drive domestic software procurement. Stakeholders must monitor how fragmented national certification regimes for AI-assisted image classification fragment vendor addressable markets and force redundant product development cycles.
Market Dynamics
Platform bundling is compressing vendor margins as enterprise buyers demand unified subscriptions spanning image processing, GIS integration, and machine learning modules rather than point solutions. This consolidation pressure is forcing specialized remote sensing software vendors to embed within larger geospatial ecosystems or cede direct customer relationships to platform orchestrators.
Growth Catalysts
- EU Green Deal mandates:Member state environmental agencies must deploy standardized spectral monitoring protocols for carbon accounting and pollution tracking, creating procurement pull for certified software platforms.
- Precision agriculture expansion:Brazilian farming operations are scaling satellite imagery adoption for crop yield optimization, generating channel demand for field-calibrated spectral tools.
- Hyperspectral sensor proliferation:Sub-meter resolution data volumes from new satellite constellations are overwhelming legacy processing architectures and forcing infrastructure refresh cycles.
Market Restraints
- Compute cost volatility:Cloud-based image processing for petabyte-scale hyperspectral datasets faces input cost pressure from GPU and specialized AI accelerator pricing swings.
- Supply concentration in launch services:Dependence on a narrow set of orbital deployment providers creates mission delay risk that cascades into software platform revenue recognition timing.
- Fragmented national certification regimes:Divergent AI-assisted image classification standards across jurisdictions force redundant product development and delay market entry.
Strategic Opportunities
- Defense and intelligence verticals:Security-certified deployments for spectral analysis represent a white space where proprietary platforms command premium positioning over open-source alternatives.
- Machine learning-GIS convergence:Automated feature extraction fused with real-time geospatial visualization creates new subscription tiers for infrastructure monitoring applications.
- German federal procurement:Federal agencies deploying advanced spectral analysis for land use planning are concentrating demand and creating anchor customer relationships.
Industry Challenges
- PhD-level talent scarcity:The intersection of remote sensing physics, machine learning engineering, and geospatial informatics creates recruitment bottlenecks that throttle product development velocity.
- Legacy system integration friction:Enterprise accounts with entrenched Esri ArcGIS workflows resist modular replacements, forcing vendors to build costly compatibility layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Sensing Software Market |
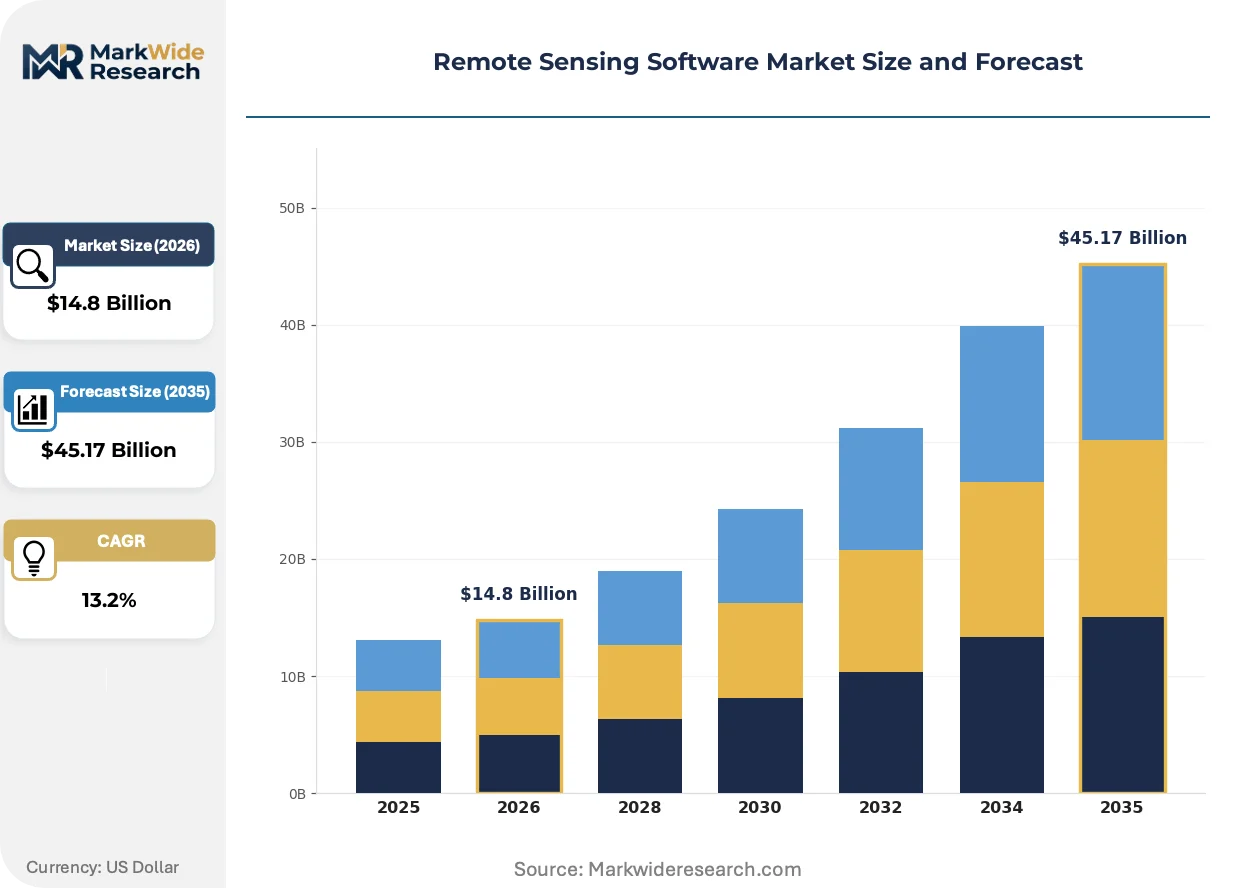
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $45.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Software, Open Source Software, Proprietary Software, Custom Solutions Technology: Image Processing, Data Analytics, Machine Learning, GIS Integration End User: Aerospace, Agriculture, Environmental Agencies, Urban Planning Application: Land Use Mapping, Disaster Management, Climate Monitoring, Resource Management |
| Companies Covered | Esri, Hexagon AB, Trimble Inc., BAE Systems, L3Harris Technologies, Harris Geospatial Solutions, Inc., PCI Geomatics, Textron Systems, EOS Data Analytics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Sensing Software Market Strategic Shifts & Innovations
Edge computing architectures are redistributing processing loads from centralized cloud facilities toward sensor-adjacent nodes, reshaping how spectral data pipelines are architected and where software value capture occurs.
Federated learning frameworks are absorbing sensitive geospatial datasets that defense and intelligence clients refuse to centralize, enabling model training across distributed classified environments without data exfiltration. Pentagon and allied defense agencies are piloting these architectures for infrastructure monitoring, compressing the traditional air-gap between operational technology and analytics platforms.
REACH framework amendments are tightening substance emission verification requirements for industrial facilities, compelling manufacturers to adopt continuous satellite-based monitoring rather than periodic ground inspections. Chemical processing and heavy manufacturing sectors in Germany, France, and the Netherlands face the steepest compliance deadlines, driving procurement of automated change-detection algorithms.
Subscription unbundling is fragmenting what were unified platform contracts into component-level negotiations, with procurement teams separating image processing licenses from analytics modules and support services. Systems integrators and managed service providers are capturing intermediary positions in this disaggregation, particularly visible in US federal and European environmental agency contracting where budget scrutiny has intensified.
Remote Sensing Software Market Segmentation
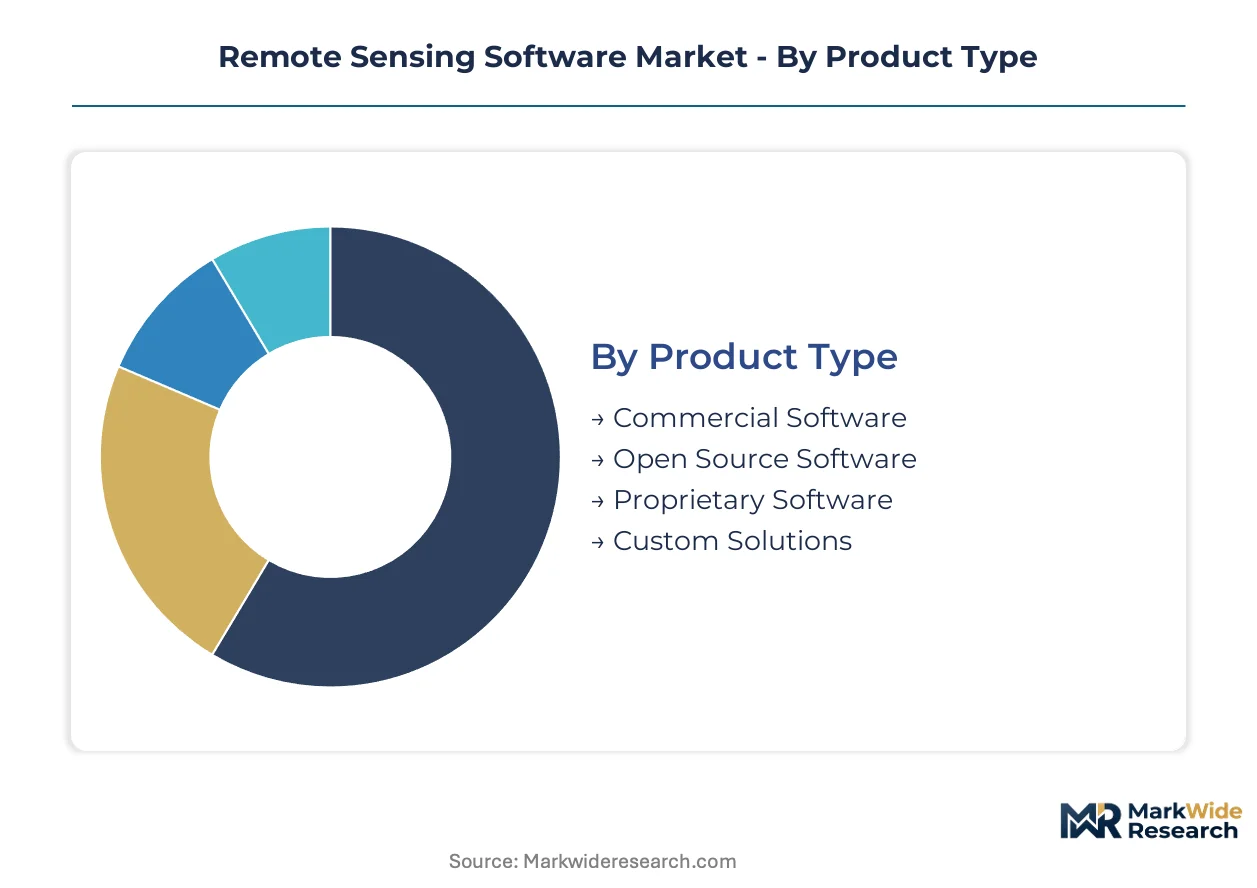
Remote sensing software vendors architect product portfolios around distinct integration depths, from standalone specialized tools to embedded modules within broader geospatial platforms. Segmentation reveals where procurement budgets concentrate and which capability layers command premium positioning.
Product Type:
Standalone deployments dominate defense and enterprise accounts requiring security-certified environments, while embedded solutions proliferate through platform bundling strategies.
- Commercial Software:Fully supported, security-certified platforms with vendor maintenance agreements. Demand concentrates in US federal agencies and EU member state environmental bodies under EU Green Deal procurement mandates, where audit trails and compliance documentation are non-negotiable.
- Proprietary Software:Closed-source architectures with specialized spectral analysis engines. Defense intelligence verticals in Germany and classified installations in allied nations drive procurement, prioritizing air-gapped deployment capabilities over open alternatives.
- Open Source Software:Community-developed toolkits with modular extensibility. Academic institutions and research consortia leverage these for algorithmic experimentation without licensing overhead.
- Custom Solutions:Bespoke development for unique sensor configurations or classified processing pipelines. Prime contractors integrate these for Pentagon and allied defense programs requiring mission-specific adaptations.
Volume placements concentrate in Commercial Software; the faster expansion belongs to Proprietary Software.
Technology:
Capability maturity varies sharply across the technology stack, with established layers facing margin pressure while emerging modules capture disproportionate investment.
- Image Processing:Core algorithms for radiometric correction, orthorectification, and spectral unmixing. Brazilian precision agriculture operations and German federal land use agencies anchor demand for field-calibrated processing pipelines that integrate directly with farm equipment and municipal GIS systems.
- GIS Integration:Spatial data infrastructure coupling with enterprise geospatial platforms. Urban planning departments across EU member states deploy these for infrastructure monitoring under standardized REACH environmental protocols.
- Machine Learning:Automated feature extraction and change detection models. Federated learning architectures are absorbing defense sector demand for distributed training across classified environments.
- Data Analytics:Statistical inference and predictive modeling layers. Climate monitoring applications leverage these for carbon accounting verification under tightening EU emissions frameworks.
Revenue gravity sits with Image Processing; capability investment flows fastest into Machine Learning.
End User:
Vertical specialization determines procurement authority, with regulatory compliance mandates shaping budget allocation across institutional buyers.
- Environmental Agencies:National regulators enforcing satellite-based compliance audits. China's MEE deploys these for dual carbon goal verification, while EU agencies standardize spectral monitoring protocols under Green Deal frameworks.
- Agriculture:Commercial farming operations and agricultural cooperatives. Brazilian soybean and corn producers scale satellite imagery adoption for yield optimization, driving channel demand for field-calibrated spectral tools.
- Aerospace:Satellite operators and mission control facilities requiring ground segment software. Launch service concentration creates mission delay risk that cascades into platform revenue timing.
- Urban Planning:Municipal and regional authorities managing land use transformation. German federal agencies concentrate demand for advanced spectral analysis in infrastructure and zoning applications.
Contract value peaks with Environmental Agencies; seat expansion runs strongest through Agriculture.
Application:
Use case specificity determines processing architecture requirements, from real-time disaster response to longitudinal climate baselining.
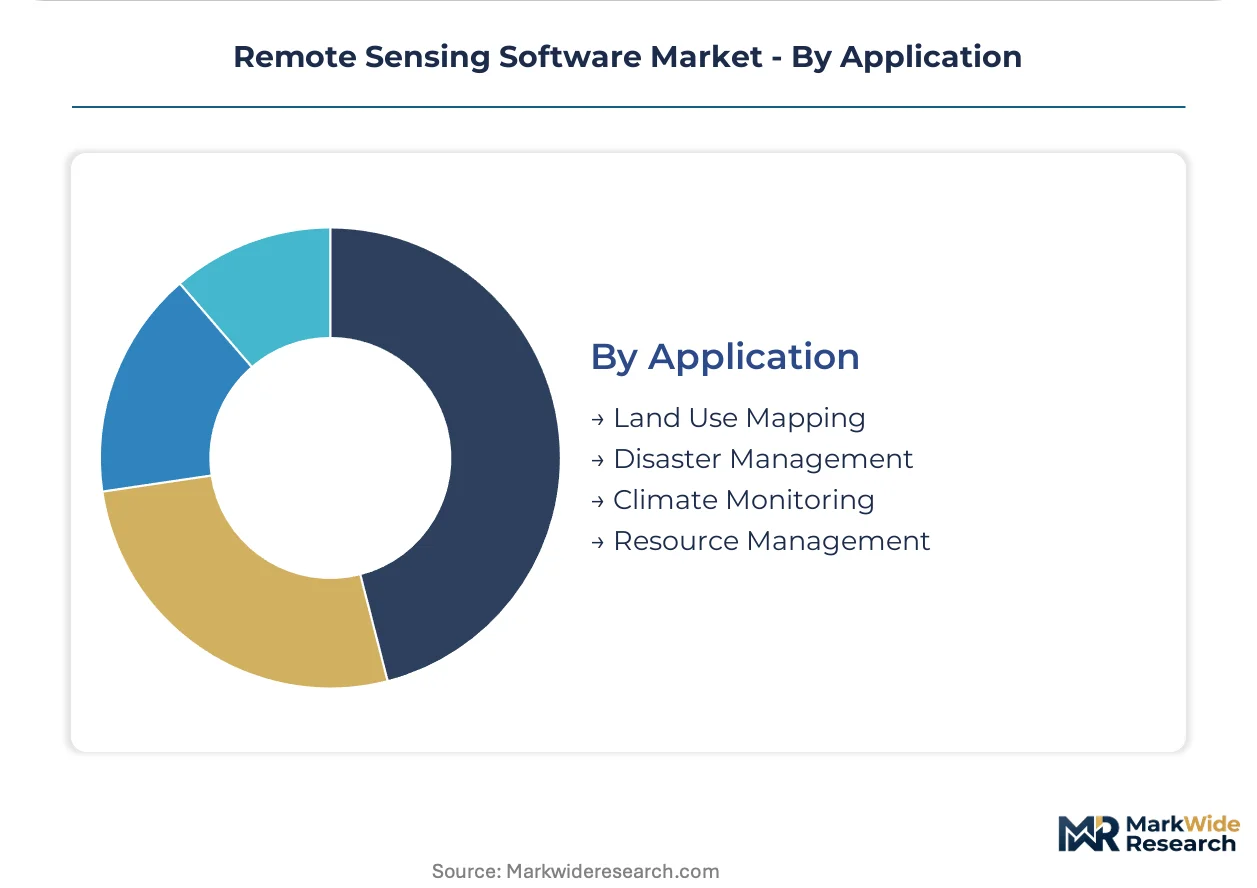
- Land Use Mapping:Cadastral boundary delineation and zoning classification. German federal procurement anchors enterprise deployments for infrastructure planning and agricultural parcel monitoring.
- Climate Monitoring:Long-term atmospheric and surface trend analysis. EU Green Deal mandates standardize spectral protocols for carbon accounting, creating procurement pull across member state environmental bodies.
- Disaster Management:Rapid damage assessment and resource mobilization. Real-time processing requirements favor edge computing architectures redistributing loads toward sensor-adjacent nodes.
- Resource Management:Forestry, water, and mineral asset tracking. Industrial facilities under REACH framework amendments adopt continuous satellite monitoring for emission verification.
Deployment scale favors Land Use Mapping; regulatory tailwinds propel Climate Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Germany while consumption spreads across agricultural and environmental monitoring programs in Brazil, China, and EU member states. Satellite data processing infrastructure clusters near defense and research institutions. Procurement authority fragments across national environmental regulators with divergent certification requirements.
United States
Defense intelligence contracts and EPA emissions verification programs anchor demand for security-certified spectral analysis platforms. The FAA shapes commercial drone operations through unmanned aerial system flight authorizations that determine platform market access. Washington DC and Colorado's aerospace corridor concentrate prime contractor activity for Pentagon ground segment software.
Germany
Federal land use agencies deploy advanced spectral analysis for infrastructure planning while REACH framework amendments tighten industrial emission monitoring requirements. The EU Green Deal mandates standardized protocols across member states, creating procurement pull for certified software. Munich and Stuttgart anchor defense and industrial automation clusters where sensor-to-software integration commands premium positioning.
Brazil
Soybean and corn producers scale satellite imagery adoption for crop yield optimization, generating channel demand for field-calibrated spectral tools. ANVISA and environmental regulators enforce agricultural compliance through remote monitoring mandates. Mato Grosso and São Paulo state farming cooperatives concentrate precision agriculture software procurement.
China
The MEE enforces dual carbon goals through satellite-based environmental compliance audits that drive domestic software procurement. MIIT standards shape AI-assisted image classification certification for government contracts. Beijing and Shenzhen anchor state-owned satellite operator ground segments with captive software development.
United Kingdom
Climate monitoring applications leverage spectral data for carbon accounting verification under tightening emissions frameworks. The UK Space Agency coordinates national Earth observation strategy with procurement standards for research institutions. Oxford and Cambridge academic clusters advance algorithmic experimentation with open-source toolkits.
Remote Sensing Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the remote sensing software value chain. Platform bundling pressures compress vendor margins as enterprise buyers demand unified subscriptions spanning image processing, GIS integration, and machine learning modules. Three archetypes dominate: geospatial platform orchestrators anchoring enterprise workflows, defense-specialized sensor integrators, and precision agriculture channel partners. Consolidation pressure forces M&A activity and ecosystem embedding strategies.
Within the geospatial platform tier, Esri leverages its ArcGIS ecosystem to anchor enterprise accounts with deep geospatial workflows. Hexagon AB represents the defense-specialized archetype through its sensor-to-software integration positioning. Trimble Inc. occupies the precision agriculture channel, with field-calibrated spectral tools tying directly to farm equipment fleets. These three exemplify how vendor archetypes map to distinct procurement authority centers.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Trimble Inc. |
| BAE Systems |
| L3Harris Technologies |
| Harris Geospatial Solutions, Inc. |
| PCI Geomatics |
| Textron Systems |
| EOS Data Analytics, Inc. |
| Others |
Cost & Logistics Intelligence
GPU and specialized AI accelerator costs cascade through cloud-based hyperspectral processing tiers, compressing margins for vendors serving petabyte-scale datasets while forcing tiered subscription restructuring that separates image processing licenses from analytics modules.
Pricing Analysis
Cost-down pressure on mid-tier subscriptions accelerates because procurement teams at US federal and EU environmental agencies now unbundle unified platform contracts into component-level negotiations. Three-tier pricing structure across premium, standard, and economy levels separates security-certified deployments from academic open-source alternatives. Certification grade and volume scale drive price differentiation, with defense intelligence verticals absorbing premium positioning while agricultural cooperatives in Brazil prioritize field-calibrated economy tiers.
Supply Chain Analysis
Security clearance and air-gap certification requirements gate vendor participation in Pentagon and allied defense programs, concentrating qualified suppliers in the United States and Germany. The supply chain draws from Taiwan for GPU accelerators, South Korea for memory components, and domestic US facilities for classified software development. Single-source vulnerability in orbital launch services creates mission delay risk that cascades into revenue recognition timing. Distribution runs through systems integrators and managed service providers capturing intermediary positions in federal and European environmental contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform bundling pressures are forcing specialized remote sensing software vendors to embed within larger geospatial ecosystems or exit direct customer relationships entirely.
For Market Incumbents: Anticipate subscription unbundling demands by pre-emptively modularizing image processing, GIS integration, and machine learning components into separately negotiable tiers. Defend against channel disintermediation by systems integrators through direct federal procurement relationships anchored in security certification. Prioritize backward integration into sensor-to-software pipelines for defense and industrial automation clusters in Germany. For New Entrants and Emerging Players: Precision agriculture cooperatives in Brazil's Mato Grosso and São Paulo states offer the most penetrable entry point for field-calibrated spectral tools. Federated learning architectures for defense intelligence clients represent white-space positioning against centralized cloud competitors. Pursue OEM partnerships with farm equipment manufacturers to bypass entrenched Esri ArcGIS workflows. For Investors and Strategic Acquirers: German federal procurement concentration for advanced spectral analysis is the leading indicator that anchor customer relationships will determine long-term viability. Target acquisition candidates with security-cleared development teams and existing Pentagon ground segment software integration. Monitor REACH framework amendment implementation timelines as the signal for industrial emission monitoring procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Esri ArcGIS ecosystem embedding captures enterprise accounts with deep geospatial workflows. |
| Acquisition of Specialist Firm | Sensor-to-software integration targets defense and industrial automation in Germany. |
| Strategic Partnership | Federated learning alliances enable distributed training across classified Pentagon environments. |
| Geographic Expansion | Brazilian precision agriculture channels scale field-calibrated spectral tool deployment. |
| Product Launch | Edge computing architectures redistribute processing loads toward sensor-adjacent nodes. |
Research Approach
Multi-period observation of satellite constellation deployment timelines, hyperspectral data volume growth, and defense procurement cycles anchored the trend analysis, supplemented by interviews with satellite mission directors, geospatial platform engineers, defense procurement officers, and precision agriculture cooperative managers. Secondary validation drew from FAA unmanned aerial system authorization databases, EU Green Deal implementation tracking, EPA emissions verification program disclosures, and SEC filings of diversified geospatial technology providers. Bottom-up segment sizing and top-down market triangulation cross-checked volume and value estimates.
Segment-weighting across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs were derived from fitted growth curves across the projection horizon, incorporating inputs from hyperspectral sensor proliferation rates and cloud compute cost trajectories. Machine learning capability investment flows and environmental regulatory mandate implementation timelines informed sector-specific trajectory adjustments.
Caveats apply where fragmented national AI-assisted image classification certification regimes or launch service supply concentration could materially shift the outlook. Forecasts reflect assumptions about EU Green Deal procurement continuity and US federal defense budget allocation patterns. A model refresh is warranted upon material change in orbital deployment provider consolidation or REACH framework enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Form Builder Software Market
Software & Services
Creative Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Online Project Management Software Market
Software & Services
Estate Management Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Video Editing Software Market
Software & Services
Global Plumbing Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Vertical Software Market
Software & Services
Feedback Management Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Employee Referral Software Market
Software & Services
Global App Design Software Market
Software & Services
Global Third-Party Logistics Software Market