
 Torque Software Market | 2026-2036
Torque Software Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Software Market Insights
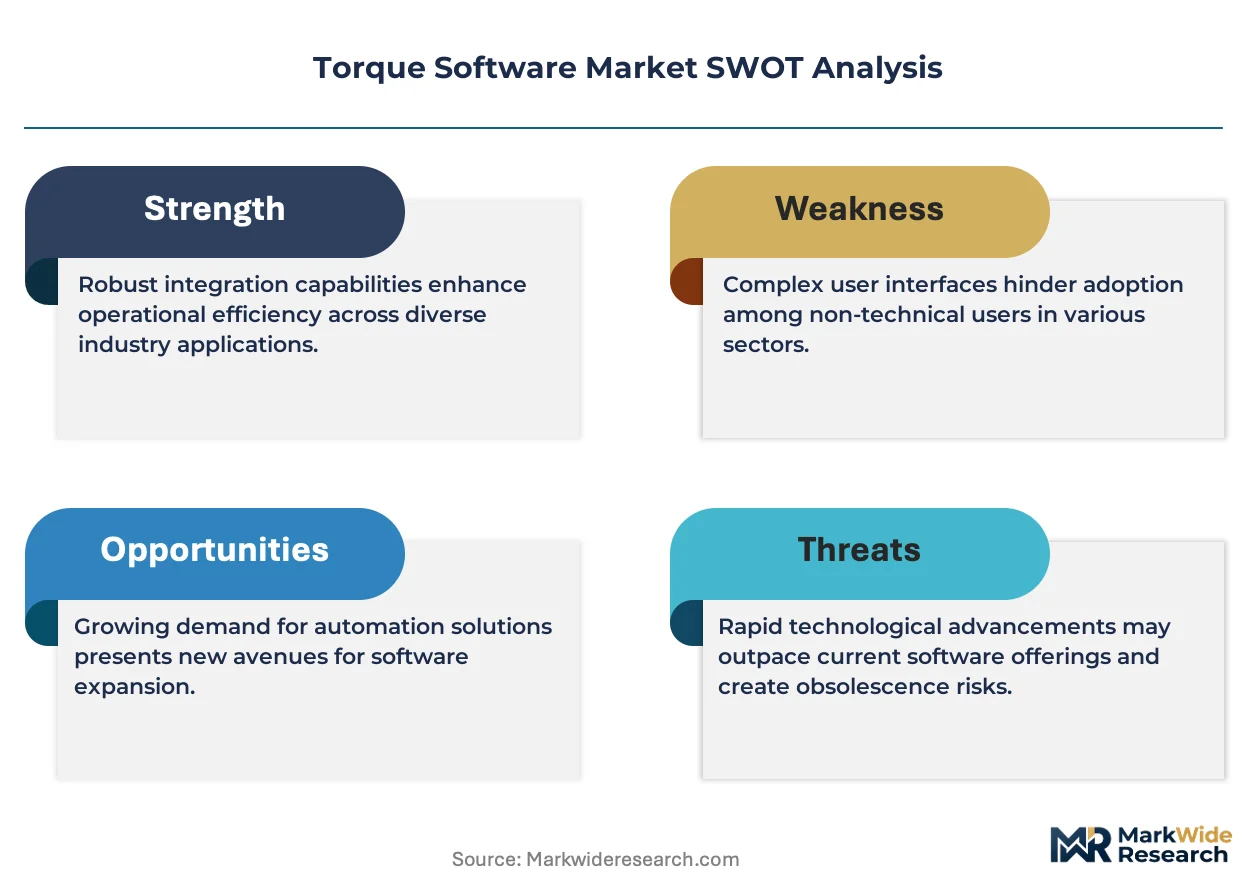
Platform licensing is reshaping margin pools away from perpetual software sales toward recurring subscription architectures. Mecmesin leverages its sensor-hardware heritage to bundle analytics dashboards with calibration equipment. Crane Electronics sustains competitive position through deep specialization in aerospace torque traceability workflows. HYTORC anchors North American demand with field-service-integrated software that ties hydraulic tool fleets to digital work instructions.
Torque software encompasses digital platforms that capture, analyze, and report rotational force data from assembly tools, test benches, and production lines, typically processing signals from strain-gauge transducers or rotary encoders at sampling rates exceeding 1 kHz to validate joint integrity. The primary industrial purpose is to eliminate fastening failures by correlating real-time torque-angle curves against specification envelopes. Cloud-based deployment leads revenue contribution as manufacturers prioritize centralized access to torque histories across multi-site operations, while simulation technology within the technology segment shows the fastest expansion as digital twin adoption spreads into fastener design validation. Quality assurance applications retain the deepest margin pools due to regulatory documentation burdens in medical device and aerospace supply chains.
ISO 6789 governs torque tool calibration protocols and directly shapes software validation requirements for measurement uncertainty reporting. The EU AI Act and FDA 21 CFR Part 11 impose divergent compliance burdens on algorithmic torque prediction and electronic record integrity, fragmenting vendor certification roadmaps. Stakeholders must monitor how emerging cybersecurity frameworks for operational technology networks reshape cloud deployment architectures and customer procurement criteria.
Market Dynamics
Cloud-native torque analytics platforms are compressing deployment timelines from months to weeks while forcing legacy on-premise vendors to rearchitect their delivery models around subscription economics.
Growth Catalysts
- ISO 6789 calibration mandates:Automotive OEMs in Germany and Japan now require digital torque traceability documentation for every assembly joint, driving platform adoption across Tier-1 supplier networks.
- Digital twin convergence:Aerospace manufacturers are integrating real-time torque data into fastener lifecycle simulations, creating pull-through demand for high-fidelity analytics engines.
- Medical device supply chains:FDA 21 CFR Part 11 electronic record requirements are forcing quality departments to replace paper-based torque logs with validated software systems.
Market Restraints
- Sensor hardware dependency:Strain-gauge transducer costs and lead times from East Asian component suppliers create margin pressure for bundled software-hardware offerings.
- EU AI Act algorithmic validation:Predictive torque analytics using machine learning now require conformity assessments that extend sales cycles by 6-12 months in European markets.
- Legacy system entrenchment:Decades-old manufacturing execution systems in heavy machinery plants resist API integration with modern torque data platforms.
Strategic Opportunities
- Battery assembly expansion:Electric vehicle gigafactories in the US and South Korea present greenfield deployment opportunities for cloud-first torque validation suites.
- Wind turbine manufacturing:Offshore wind OEMs need bolt tension monitoring across geographically dispersed installation fleets, creating demand for mobile-integrated torque software.
- India PLI scheme:Production-linked incentives for advanced automotive and electronics manufacturing are accelerating precision assembly investments requiring traceable torque systems.
Industry Challenges
- OT cybersecurity skill scarcity:Manufacturing IT departments lack personnel trained to harden cloud-connected torque systems against ransomware targeting operational technology networks.
- Multi-standard certification burden:Vendors must simultaneously validate software against FDA 21 CFR Part 11, EU AI Act algorithmic requirements, and ISO 6789 measurement uncertainty protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Software Market |
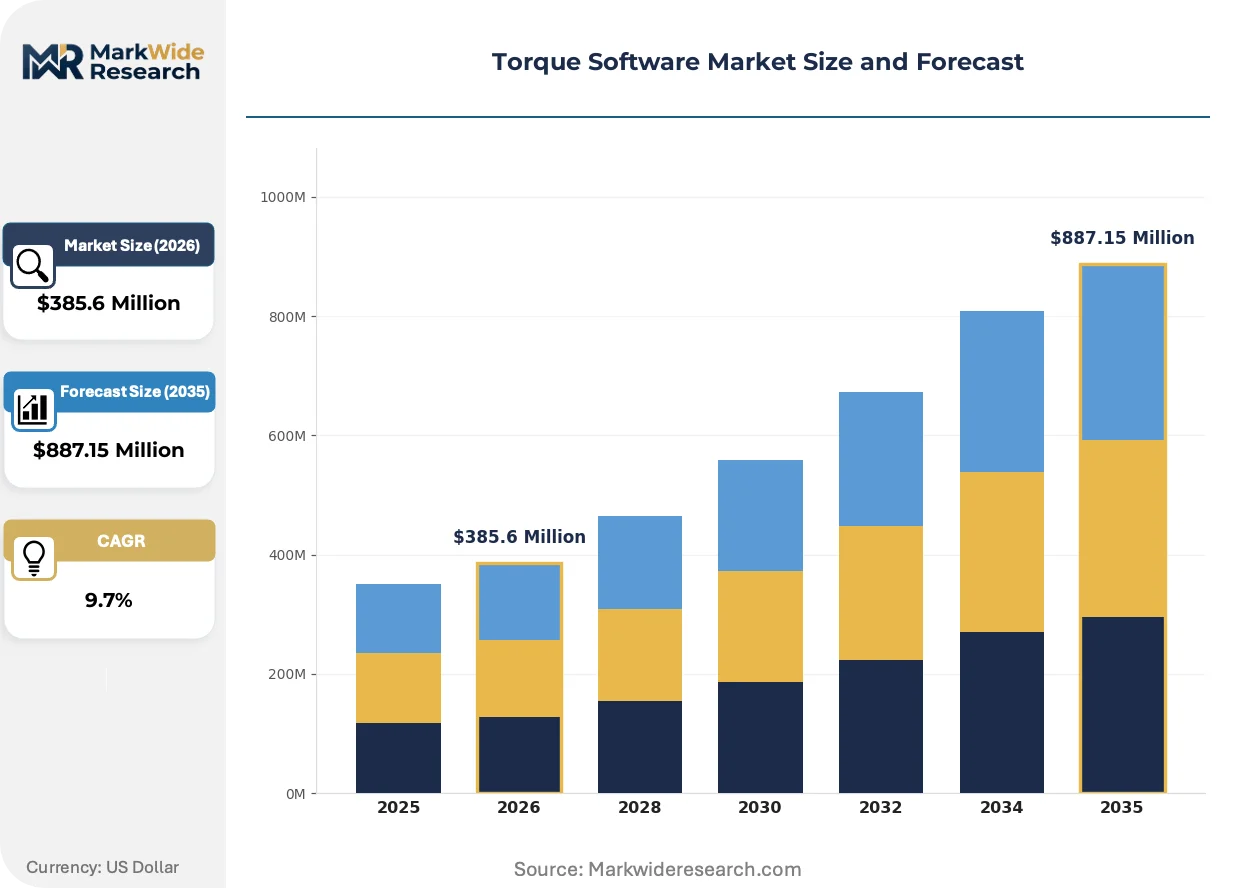
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Open Source End User: Manufacturing, Automotive, Aerospace, Energy Technology: Simulation, Data Analysis, Modeling, Control Systems Application: Product Design, Performance Testing, Maintenance, Quality Assurance |
| Companies Covered | Mecmesin, Crane Electronics, Creosys, Tecware, Magtrol, Sturtevant Richmont, Torque IT Solutions, HYTORC, Launch Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Software Market Trends and Innovations
Edge computing architectures are redistributing torque data processing from centralized clouds to factory floors, enabling sub-millisecond feedback loops for critical fastening operations while complicating vendor platform roadmaps.
Embedded edge inference engines are collapsing the latency gap between torque signal capture and joint quality determination. Automotive powertrain plants in Stuttgart and Detroit are deploying these systems for real-time rework decisions on cylinder head assembly lines. The technology is collapsing the historical separation between quality control and production execution functions.
The EU AI Act's risk-based classification system is forcing torque software vendors to document algorithmic decision pathways for predictive failure models. Medical device manufacturers in Ireland and the Netherlands now demand third-party audits of machine learning training datasets before procurement approval. This regulatory layer is fragmenting vendor certification roadmaps between European and North American deployment architectures.
Buyers are consolidating torque software procurement under enterprise-wide manufacturing intelligence platforms rather than point solutions for individual assembly lines. Tier-1 aerospace suppliers in Toulouse and Wichita are mandating API-first architectures that feed torque data directly into their MES and ERP systems. This integration imperative favors vendors with pre-built connectors to Siemens Opcenter and Dassault DELMIA platforms.
Torque Software Market Segmentation
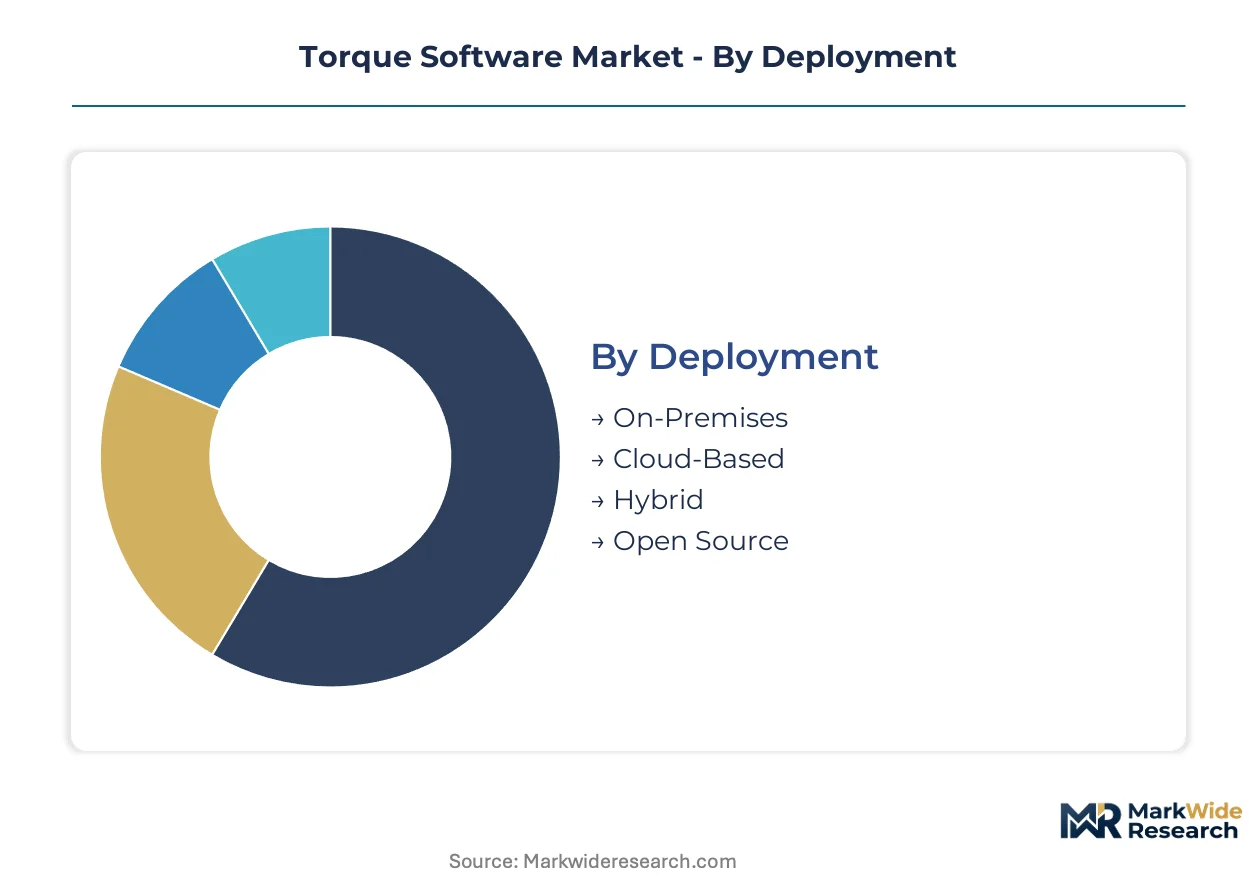
Segmentation in torque software reveals how deployment architectures, end-user requirements, and application workflows fragment vendor roadmaps. Understanding these divisions exposes where margin pools concentrate and which technology investments align with procurement patterns across industrial verticals.
Deployment:
Mature on-premise installations coexist with emerging cloud-native architectures as manufacturers navigate data sovereignty constraints.
- On-Premises:Legacy server installations process torque data within facility firewalls, satisfying air-gapped security mandates in defense and nuclear supply chains. German automotive OEMs in Stuttgart and Wolfsburg retain these systems for ISO 6789 calibration labs where network isolation is non-negotiable.
- Cloud-Based:SaaS platforms centralize torque histories across multi-site operations, enabling real-time dashboards for quality managers. Battery gigafactories in South Korea and the US favor this model for rapid scaling without capital infrastructure.
- Hybrid:Edge-cloud splits process critical fastening data locally while archiving compliance records centrally. Aerospace suppliers in Toulouse deploy this architecture to balance latency requirements with regulatory retention.
- Open Source:Community-developed libraries attract research institutions and specialized integrators seeking customization without licensing fees.
Cloud-based deployment commands revenue concentration; open source claims the steepest expansion curve among niche adopters.
End User:
Customer type determines pricing tolerance and integration complexity, with capital-intensive sectors driving premium platform adoption.
- Manufacturing:General industrial producers apply torque software across mixed assembly lines, prioritizing interoperability with existing MES investments. Japanese precision toolmakers integrate these systems for JIS-compliant quality documentation.
- Automotive:Powertrain and chassis assembly plants demand sub-millisecond sampling rates for cylinder head and suspension fastening. OEMs in Detroit and Munich mandate digital torque traceability for every joint under tightening warranty regulations.
- Aerospace:Airframe manufacturers require algorithmic validation for predictive failure models under EU AI Act risk classifications. Suppliers in Wichita and Hamburg face extended procurement cycles for machine learning-enabled analytics.
- Energy:Wind turbine OEMs and offshore installation fleets need mobile-integrated torque validation for geographically dispersed bolt tension monitoring.
Automotive retains volume leadership; energy holds the steepest expansion trajectory as renewable infrastructure scales.
Technology:
Functional purpose separates platforms into design-phase simulation versus operational-phase analytics, with convergence emerging at the digital twin interface.
- Simulation:Finite element and multibody models predict fastener behavior before physical prototyping. Aerospace engineers in Seattle and Toulouse deploy these tools for lightweight joint optimization under extreme load cycles.
- Data Analysis:Statistical process control platforms identify torque-angle curve anomalies for quality trending. Medical device manufacturers in Ireland rely on these systems for FDA 21 CFR Part 11 electronic record compliance.
- Modeling:Physics-based digital twins correlate real-time torque data with predictive lifecycle simulations. Battery assembly lines in Nevada integrate these engines for cell-to-pack fastening validation.
- Control Systems:Closed-loop feedback architectures adjust tool parameters mid-cycle based on sensor input. Automotive plants in Stuttgart deploy edge inference for real-time rework decisions.
Data analysis commands installed base dominance; simulation gains share fastest as digital twin adoption penetrates fastener design workflows.
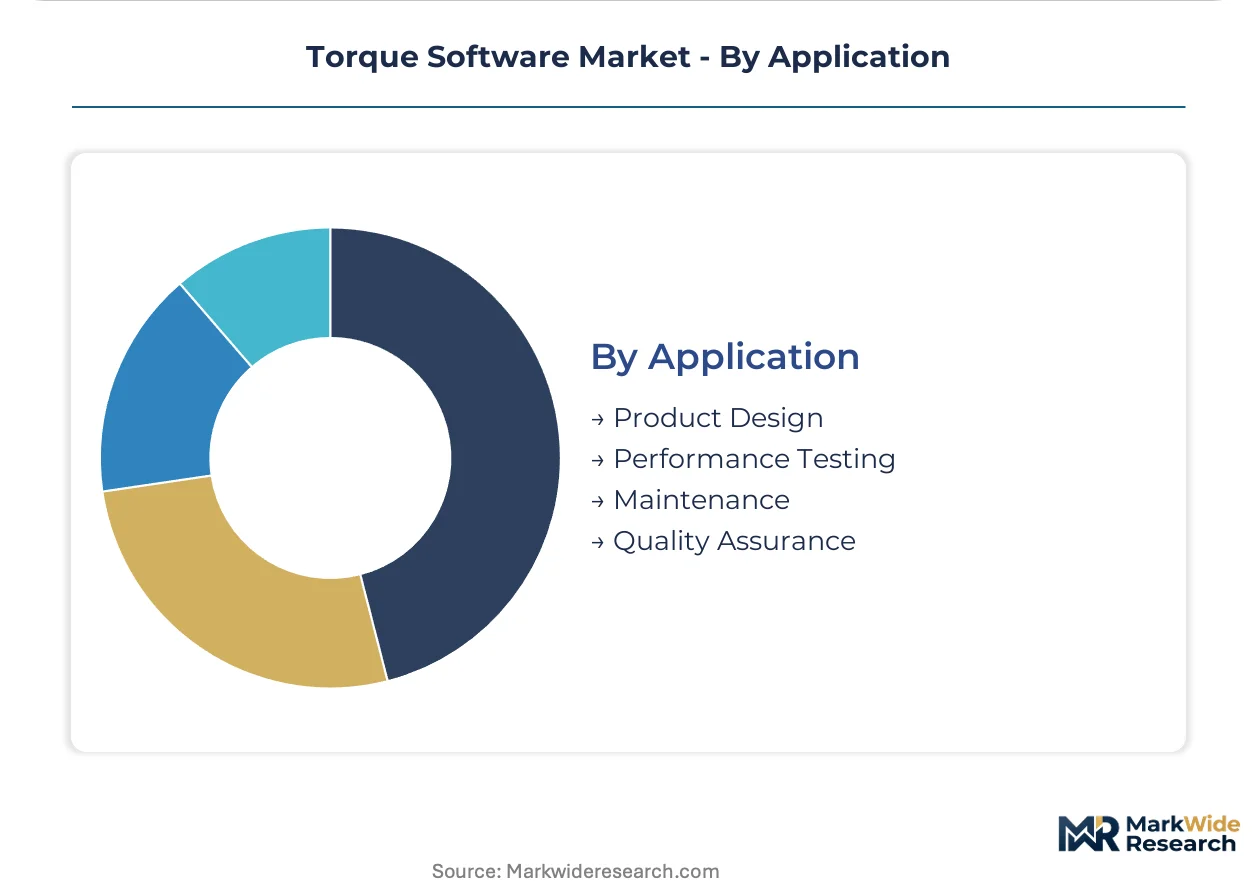
Application:
Workflow position determines regulatory exposure and margin structure, with post-production documentation carrying the heaviest compliance burden.
- Product Design:Early-stage fastener specification tools integrate with CAD environments for joint sizing and material selection. Aerospace OEMs in Wichita embed these capabilities within Dassault DELMIA platforms.
- Performance Testing:Validation suites correlate torque signatures against specification envelopes during prototype evaluation. German test bench manufacturers bundle analytics with strain-gauge transducer sales.
- Maintenance:Field service platforms track bolt tension degradation across turbine and infrastructure fleets. Offshore wind operators in the North Sea demand mobile-integrated torque logging for remote access.
- Quality Assurance:Regulatory documentation systems generate audit trails for FDA, EASA, and ISO compliance. Medical device suppliers in the Netherlands and Minnesota face the most stringent electronic record requirements.
Quality assurance retains margin leadership; maintenance climbs fastest as predictive service models displace scheduled inspection regimes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes torque software primarily for ISO 6789 calibration documentation, while the United States deploys it for FDA-regulated medical device traceability and South Korea leverages cloud-native suites for battery gigafactory scaling. This consumption-mix differential shapes vendor roadmaps across geographies.
United States
Medical device manufacturers in Minnesota and Massachusetts drive FDA 21 CFR Part 11 compliant torque documentation for implantable device assembly. The FDA mandates electronic record integrity for quality audits. Minneapolis-St. Paul hosts concentrated demand from cardiovascular and orthopedic instrument suppliers replacing paper-based torque logs.
Germany
Automotive OEMs in Stuttgart and Wolfsburg require digital torque traceability for every powertrain joint under tightening warranty liability regulations. The KBA enforces assembly documentation standards that cascade through Tier-1 supplier networks. The industrial automation corridor between Stuttgart and Munich anchors Europe's deepest concentration of calibration-integrated torque analytics deployments.
Japan
Precision toolmakers and automotive transplants apply torque software for JIS-compliant quality documentation across mixed-model assembly lines. METI promotes smart factory standards that incentivize cloud-based torque data centralization. Toyota City and Nagoya industrial clusters lead adoption of edge-computing torque validation for sub-millisecond powertrain fastening feedback.
South Korea
Battery gigafactories in Gyeonggi Province and Ulsan deploy cloud-first torque suites for cell-to-pack assembly validation at production scale. The MFDS and national industrial policy prioritize manufacturing data traceability for export certification. Samsung SDI and LG Energy Solution facilities near Seoul drive fastest-in-region adoption of simulation-integrated torque modeling for fastener lifecycle prediction.
India
Automotive and electronics manufacturers in Pune and Chennai accelerate precision assembly investments under the PLI scheme for advanced manufacturing. BIS standards for torque tool calibration create compliance pull-through for software platforms. The Tamil Nadu automotive cluster around Sriperumbudur represents the fastest-expanding greenfield deployment opportunity for cloud-native torque validation systems.
Torque Software Market Competitive Landscape
Capability concentration sits with sensor-hardware heritage players; scale advantage sits with cloud-native platform vendors. The market exhibits tiered structure where bundled equipment-software offerings coexist with pure-play analytics subscriptions. Three archetypes dominate: calibration equipment bundlers, aerospace traceability specialists, and field-service-integrated hydraulic tool vendors. Competitive moves center on API-first architecture development for MES integration and edge-computing capability acquisition.
Within the sensor-heritage tier, Mecmesin and Crane Electronics occupy positions that exemplify hardware-originated platform strategies. HYTORC anchors the North American field-service integration archetype. These three represent divergent pathways for embedding software into industrial torque workflows.
| Leading Market Players |
|---|
| Mecmesin |
| Crane Electronics |
| Creosys |
| Tecware |
| Magtrol |
| Sturtevant Richmont |
| Torque IT Solutions |
| HYTORC |
| Launch Tech |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian strain-gauge transducer fabrication is compressing margins for bundled software-hardware offerings while forcing pure-play analytics vendors toward subscription pricing to escape component cost volatility.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement, with automotive OEMs in Stuttgart and Wolfsburg locking in multi-year SaaS subscriptions for ISO 6789 calibration platforms. Pricing stratifies across premium certification tiers, with FDA 21 CFR Part 11 validated suites commanding substantial premiums over standard analytics modules. Cost compression in the mid-market segment intensifies as cloud-native entrants undercut legacy on-premise vendors. Tier-1 aerospace suppliers exhibit lowest price sensitivity due to regulatory documentation burdens, while general manufacturing buyers negotiate aggressively on per-seat licensing.
Supply Chain Analysis
Upstream feedstock dependencies center on precision-machined sensor housings and semiconductor-grade analog-to-digital converters sourced predominantly from Taiwan, Japan, and Germany. Strain-gauge element fabrication draws from specialized alloys with concentrated supply in South Korea and China. Single-source vulnerability persists for high-sampling-rate ADC chipsets used in sub-millisecond torque validation systems. Distribution runs through calibration equipment OEMs and industrial automation distributors, with direct SaaS sales gaining share among battery gigafactory operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torque software demand tracks automotive production cycles and capital equipment refresh waves, positioning the market for recovery as electric vehicle assembly capacity accelerates across North America and Europe.
For Market Incumbents: Build switching-cost moats through deep API integration with Siemens Opcenter and Dassault DELMIA platforms. Incumbents should acquire edge-computing inference specialists to defend against cloud-native entrants attacking the real-time rework decision layer. Certification investment in EU AI Act algorithmic validation represents a critical defensive lever against regulatory fragmentation. For New Entrants and Emerging Players: India's Tamil Nadu automotive cluster offers underpenetrated greenfield deployment opportunities as PLI scheme incentives accelerate precision assembly investments. New entrants should target battery gigafactory quality departments with mobile-integrated torque suites for geographically dispersed installation fleets. A channel partnership strategy with German test bench manufacturers provides fastest route to calibration-lab credibility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because tightening ISO 6789 and FDA 21 CFR Part 11 mandates embed software vendors deeply into customer compliance workflows. Acquisition targets should display pre-built MES connectors and established algorithmic validation documentation. The signal to watch is EU AI Act conformity assessment backlog duration as an indicator of vendor certification capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Pre-built connectors to Siemens Opcenter and DELMIA satisfy Tier-1 aerospace procurement mandates in Toulouse. |
| Edge Computing Capability Acquisition | Sub-millisecond inference engines collapse quality control and production execution functions in Stuttgart powertrain plants. |
| EU AI Act Certification Investment | Algorithmic validation documentation extends sales cycles but creates procurement preference among Dutch medical device suppliers. |
| Cloud-Native Geographic Expansion | SaaS deployment without capital infrastructure matches South Korean battery gigafactory scaling requirements. |
| Sensor Hardware Bundling | Calibration equipment heritage anchors margin pools against pure-play analytics commoditization in German automotive corridors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with quality assurance directors, calibration lab managers, MES integration specialists, and industrial automation procurement officers; and secondary validation against SEC filings from sensor-hardware vendors, ISO 6789 implementation guidelines, FDA 21 CFR Part 11 guidance documents, and customs records for strain-gauge transducer trade flows. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Forecast inputs incorporated deployment architecture splits, end-user vertical penetration rates, technology segment adoption curves, and application workflow regulatory exposure. The analytical framework modeled cloud-based, on-premise, hybrid, and open-source deployment modes alongside automotive, aerospace, energy, and manufacturing end-user segments. CAGRs derived from segment-level growth rate blending weighted by revenue contribution, with simulation technology expansion rates informed by digital twin adoption patterns in fastener design validation.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by cloud-native entrants or sudden EU AI Act enforcement acceleration would shift outcomes beyond modeled ranges. Cross-checking against hyperscaler industrial IoT capex disclosures and automotive OEM software procurement budget benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Municipal Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Media Planning Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
Online Donation Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Content Creation Software Market
Software & Services
Simulation Software Market
Software & Services
Quality and Lifecycle Management Software Market
Software & Services
Transient Analysis Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Workflow Automation and Optimization Software Market