
 Krill Oil Phospholipid Market | 2026-2036
Krill Oil Phospholipid Market Size, Share, and Industry Trends Forecast 2026-2036
Krill Oil Phospholipid Market Insights
MSC certification for Antarctic krill fisheries is rotating the competitive set, filtering out suppliers without sustainable harvesting credentials. Aker BioMarine leverages its vertically integrated Antarctic operations from catch to capsule, sustaining long-term supply security. Rimfrost anchors its position through Norwegian coastal processing infrastructure, while Neptune Wellness Solutions differentiates via North American distribution reach and branded finished goods.
Krill oil phospholipid denotes omega-3 fatty acids bound to phospholipid molecules rather than triglycerides, yielding superior intestinal absorption and direct cellular uptake due to amphiphilic properties that facilitate passage through intestinal walls. The substance serves primarily as a bioavailable source of EPA and DHA for cardiovascular, cognitive, and inflammatory health applications. Softgel capsules dominate current volume as consumers favor convenient dosing formats, while liquid concentrate formats capture premium positioning in clinical and pediatric segments. Pharmaceutical-grade specifications remain the fastest-growing application tier as drug developers explore phospholipid-bound actives for enhanced bioavailability.
FDA oversight of dietary supplement Good Manufacturing Practices and the Marine Stewardship Council's fishery sustainability standards jointly determine market access for krill-derived ingredients in the United States. EFSA novel food evaluations and EU F-Gas Regulation implications for Antarctic vessel operations add compliance layers for European market participation. Stakeholders must monitor Antarctic krill biomass assessment updates and phospholipid concentration standardization protocols as these variables will determine which suppliers retain formulation partnerships with major nutraceutical brands.
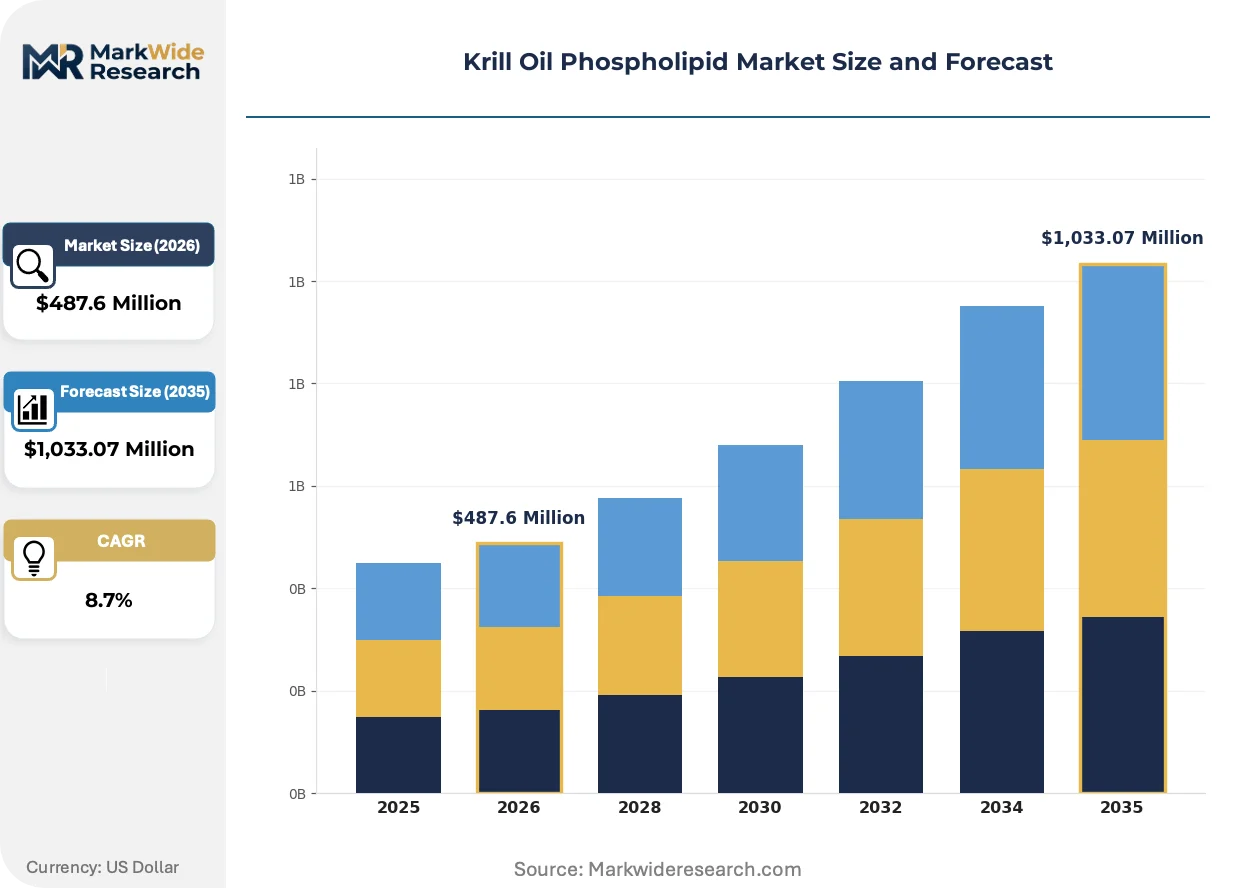
Market Dynamics
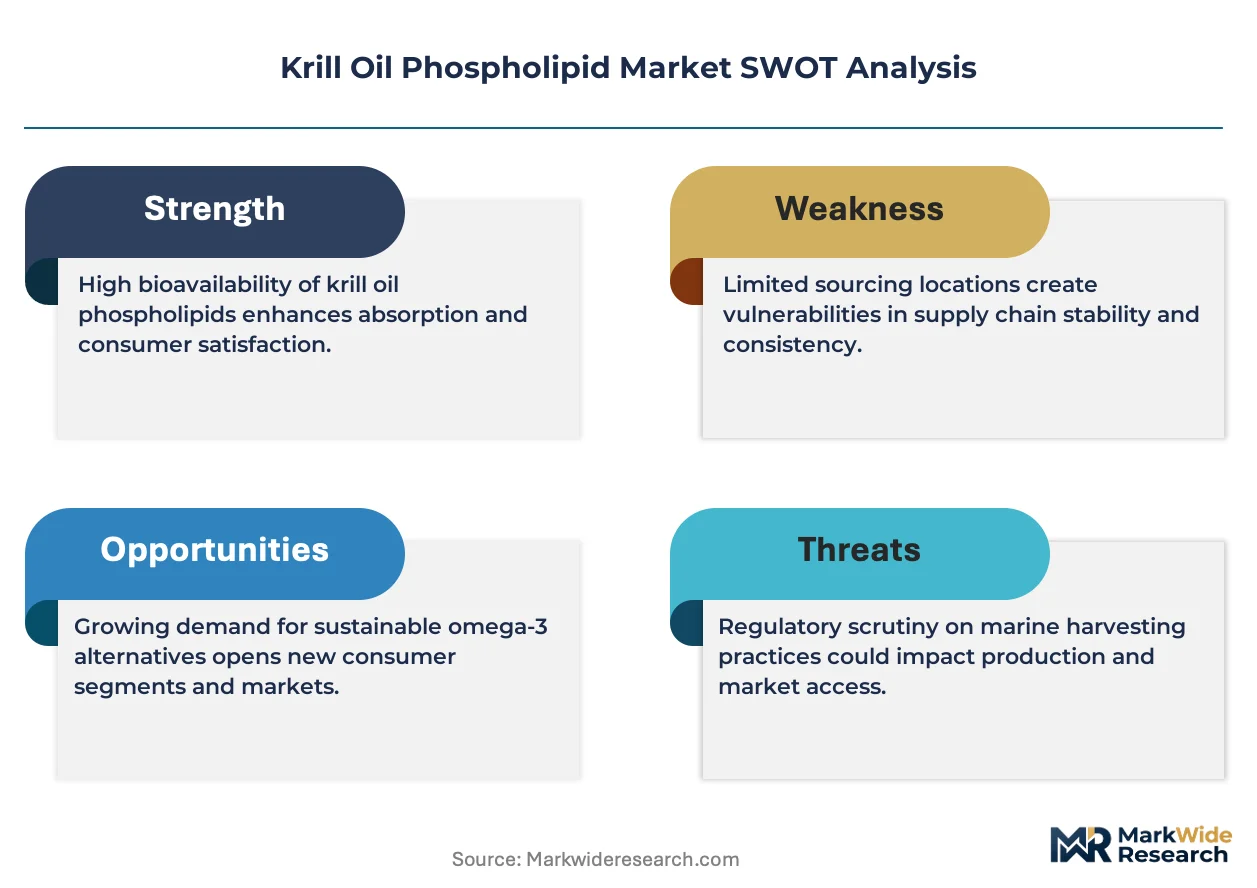
MSC certification requirements for Antarctic krill fisheries are compressing supplier margins and forcing capital redeployment toward traceable catch-to-capsule infrastructure, fundamentally restructuring competitive access in omega-3 phospholipid sourcing.
Growth Catalysts
- EFSA novel food evaluations:Streamlined approval pathways for phospholipid-bound omega-3 concentrates accelerate European market entry for purified formulations targeting cardiovascular health applications.
- Pharmaceutical-grade specifications:Drug developers actively incorporate phospholipid-complexed actives into bioavailability-enhanced delivery systems, pulling demand from nutraceutical into clinical trial supply chains.
- Norwegian coastal processing clusters:Concentrated extraction infrastructure around Bergen and Ålesund reduces logistics costs for Antarctic raw material landing, improving margin capture for Nordic suppliers.
Market Restraints
- Antarctic biomass volatility:CCAMLR quota adjustments based on ecosystem monitoring create supply uncertainty that compresses forward contracting windows for krill meal and oil processors.
- Algal oil substitution:Fermentation-derived DHA and EPA from Schizochytrium strains bypass marine harvest constraints entirely, capturing vegan-formulation market share in dietary supplements.
- F-Gas Regulation compliance costs:EU restrictions on hydrofluorocarbon refrigerants for Antarctic vessel operations elevate capital expenditure requirements for fleet operators serving the fishery.
Strategic Opportunities
- Pediatric liquid concentrates:Palatable emulsion formats for children with neurodevelopmental protocols represent an underserved application segment with limited current phospholipid-specific offerings.
- India nutraceutical expansion:FSSAI regulatory harmonization with CODEX standards opens import pathways for MSC-certified krill oil into ayurveda-integrated wellness formulations.
- Direct-to-clinic distribution:Bypassing retail pharmacy chains through functional medicine practitioner networks captures higher-margin patient-specific dosing protocols for inflammatory conditions.
Industry Challenges
- Phospholipid standardization protocols:Absence of unified analytical methods for phosphatidylcholine and phosphatidylethanolamine quantification creates batch-to-batch variability that complicates pharmaceutical partnerships.
- Antarctic logistics reconfiguration:Seasonal ice dynamics and port congestion at Punta Arenas and Montevideo force continuous supply chain recalibration for just-in-time extraction campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Krill Oil Phospholipid Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid Concentrate, Capsule, Tablet Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics, Animal Nutrition End User: Dietitians, Wellness Centers, Pharmaceutical Manufacturers, Pet Nutritionists Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Direct Sales, Health Clinics |
| Companies Covered | Aker BioMarine, Rimfrost, Neptune Wellness Solutions, Coastside Bio Resources, NutriGold, Qingdao Kangjing Marine Biotechnology, Fuji Chemicals, Xi'an Prius Biological Engineering, Norwegian Fish Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Krill Oil Phospholipid Market Trends and Innovations
Extraction technology advances and certification-driven procurement criteria are fragmenting traditional supply relationships while enabling new entry paths for specialized phospholipid processors.
Supercritical CO2 extraction with ethanol co-solvent modification is fragmenting the conventional hexane-based processing landscape. Boutique Norwegian processors deploy this technology to preserve phospholipid integrity for pharmaceutical-grade specifications. The method commands premium positioning but compresses throughput economics for mass-market softgel manufacturers.
EU F-Gas Regulation phase-down schedules for mobile refrigeration systems are accelerating vessel retrofit investments among Antarctic fleet operators. Compliance deadlines force capital allocation toward ammonia-based or transcritical CO2 systems before 2030 deployment windows. Norwegian-flagged operators face the steepest cost curves given their high-latitude operational intensity.
Practitioner-channel purchasing for functional medicine protocols is displacing retail-centric brand loyalty in high-value patient segments. Clinicians in the United States increasingly specify phospholipid-bound omega-3s for bioavailability-optimized protocols over standard ethyl ester formulations. This channel rotation concentrates volume with distributors holding medical education credentials and third-party testing documentation.
Krill Oil Phospholipid Market Segmentation
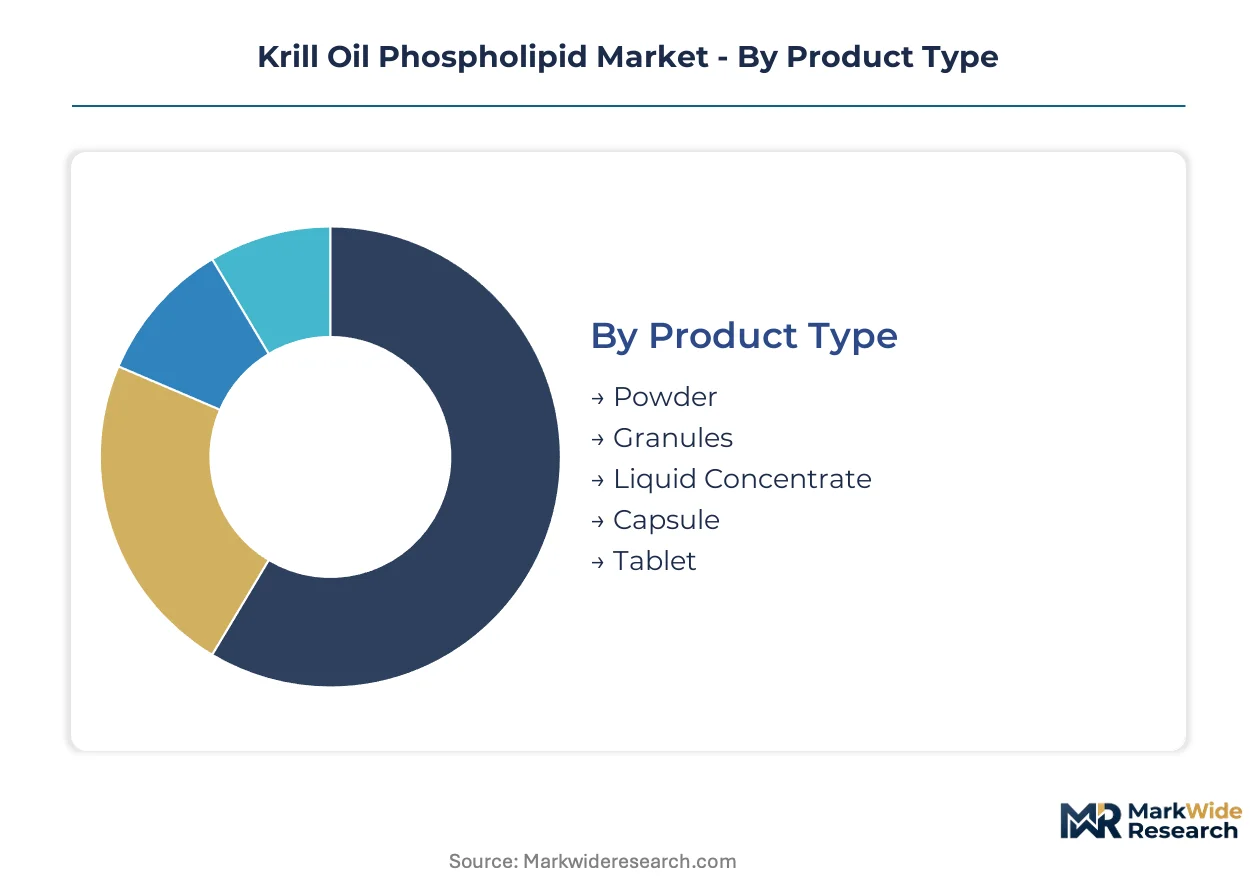
Channel configuration determines which phospholipid formats reach end users. Pharmaceutical-grade specifications flow through practitioner networks while mass-market softgels dominate retail pharmacy and e-commerce pathways.
Product Type:
Capsule and liquid concentrate formats command premium shelf placement in practitioner channels, while powder and granule variants serve bulk formulation contracts.
- Capsule:Softgel encapsulation protects phospholipid integrity from oxidation during shelf life. Demand clusters with Norwegian and US dietary supplement manufacturers seeking convenient dosing formats for cardiovascular wellness protocols.
- Liquid Concentrate:Emulsion-based delivery enables precise titration for pediatric neurodevelopmental and clinical anti-inflammatory applications. Functional medicine practitioners in the United States specify this format for bioavailability-optimized patient protocols.
- Powder:Bulk handling suits functional food fortification and pet nutrition premix operations.
- Granules:Free-flowing properties facilitate automated tableting and sachet packaging lines.
- Tablet:Compressed formats target pharmacy chains with stability advantages for extended distribution cycles.
Capsule dominates installed base. Liquid concentrate is where expansion concentrates.
Application:
Cost tier stratification separates pharmaceutical-grade specifications from commodity nutraceutical positioning, with extraction purity determining margin capture.
- Dietary Supplements:Standardized phosphatidylcholine content drives formulation consistency for omega-3 positioning. Norwegian coastal processors supply MSC-certified concentrate to North American and European brand owners.
- Pharmaceuticals:Drug developers incorporate phospholipid-bound actives into bioavailability-enhanced delivery systems for cardiovascular and CNS indications. EMA and FDA GMP compliance requirements filter supplier qualification.
- Functional Foods:Microencapsulation technologies enable beverage and dairy fortification without sensory degradation.
- Cosmetics:Topical phospholipid complexes support skin barrier function claims in dermocosmetic formulations.
- Animal Nutrition:Aquaculture feed applications leverage krill meal co-products for marine farmed species.
Dietary supplements anchor volume throughput. Pharmaceuticals is climbing the fastest on value per kilogram.
End User:
Customer type determines specification stringency, with pharmaceutical manufacturers demanding batch-level phospholipid quantification unavailable to general wellness channels.
- Pharmaceutical Manufacturers:Require certificate of analysis documentation for phosphatidylcholine and phosphatidylethanolamine ratios. FDA 21 CFR Part 111 compliance and EMA GMP certification gate supplier relationships.
- Wellness Centers:Functional medicine clinics in the United States specify phospholipid-bound omega-3s for inflammatory condition protocols, bypassing retail channels.
- Dietitians:Clinical nutrition specialists recommend concentrated formats for metabolic health interventions.
- Pet Nutritionists:Veterinary channel demand concentrates in North American specialty pet retail.
Wellness centers dominate practitioner-channel volume. Pharmaceutical manufacturers is where partnership stickiness concentrates.
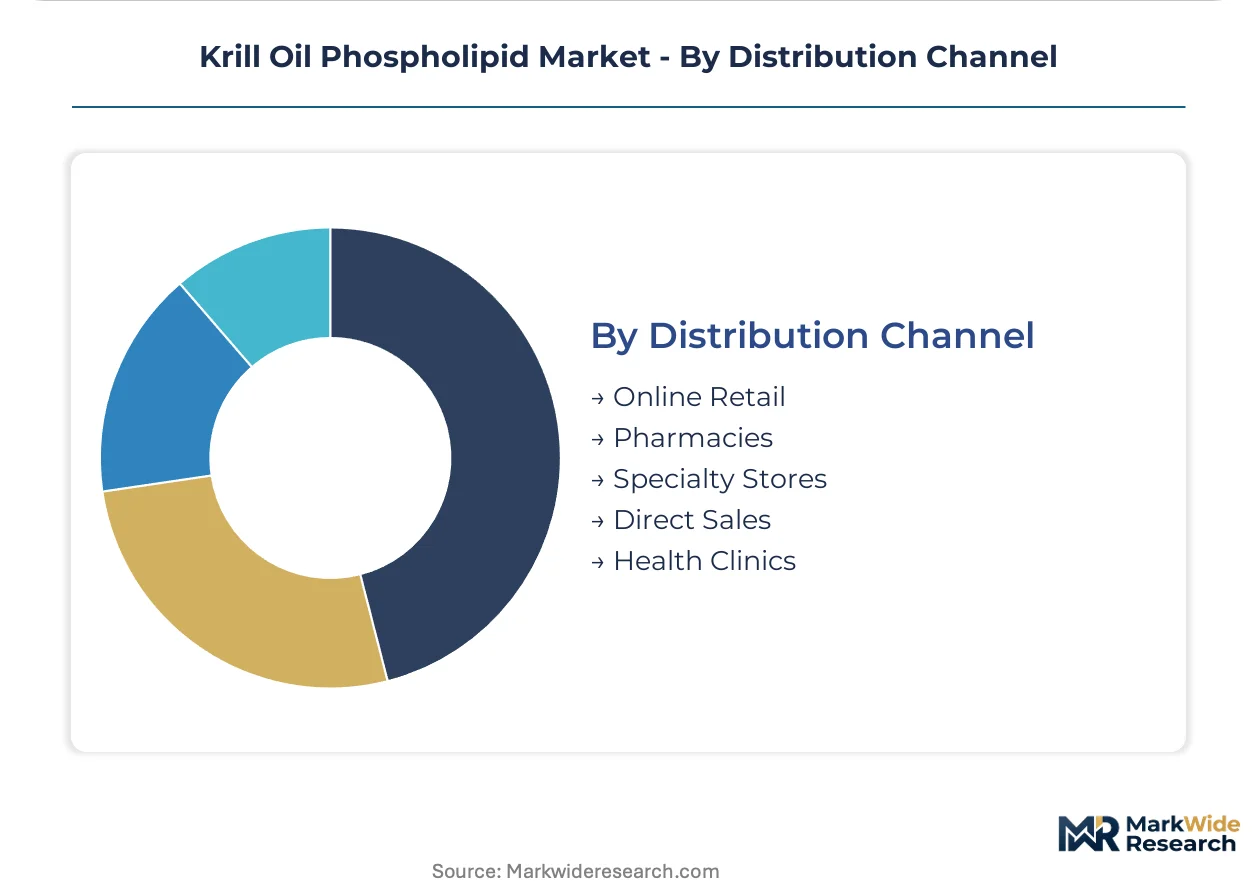
Distribution Channel:
Geography determines channel viability, with health clinics and specialty stores concentrated in high-income urban clusters while online retail penetrates secondary markets.
- Health Clinics:Functional medicine networks in the United States capture premium pricing through patient-specific dosing protocols. Direct-to-clinic distribution bypasses pharmacy chain margin stacking.
- Online Retail:Amazon and direct-to-consumer platforms enable MSC-certified product discovery outside traditional pharmacy footprints. Norwegian and US brands compete on phospholipid concentration transparency.
- Pharmacies:Chain retail captures mass-market softgel volume with shelf-stable inventory economics.
- Specialty Stores:Natural products retailers curate premium-positioned liquid concentrate and capsule formats.
- Direct Sales:Multi-level marketing channels persist in Asian markets with personalized consultation models.
Pharmacies dominate unit volume throughput. Health clinics is gaining share fastest on margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dietary supplement GMP enforcement and EFSA novel food pathways are redirecting procurement toward MSC-certified suppliers with verified Antarctic catch documentation. Norwegian coastal processing infrastructure and US clinical research networks concentrate value capture in high-specification phospholipid segments.
United States
Functional medicine practitioners in California and New York Metro specify phospholipid-bound omega-3s for inflammatory condition protocols, bypassing retail pharmacy channels. FDA 21 CFR Part 111 compliance requirements filter supplier relationships toward documented Antarctic sourcing. Boston-area clinical research infrastructure supports pharmaceutical-grade specification development for cardiovascular trial supply chains.
Norway
Bergen and Ålesund extraction clusters reduce logistics costs for Antarctic raw material landing, improving margin capture for Nordic processors. The Norwegian Food Safety Authority enforces EU-aligned novel food standards for phospholipid concentrate imports. Tromsø-based marine research institutions coordinate biomass assessment data with CCAMLR quota negotiations.
Germany
EMA GMP certification requirements gate pharmaceutical-grade krill oil partnerships for cardiovascular drug developers in Frankfurt and Munich. EU F-Gas Regulation phase-down schedules force Antarctic vessel fleet retrofits, elevating capital costs for operators serving German processors. Hamburg logistics hubs coordinate MSC-certified concentrate distribution across Central European nutraceutical manufacturers.
China
Qingdao and Xi'an marine biotechnology processors import Antarctic krill meal for phospholipid extraction targeting domestic dietary supplement brands. NMPA health food registration requirements create compliance bottlenecks for imported omega-3 concentrates. Yangtze River Delta distribution networks channel certified products toward tier-one city wellness retail.
India
Maharashtra and Gujarat nutraceutical formulators seek FSSAI import clearance for MSC-certified krill oil integration into ayurveda-adjacent wellness products. CDSCO novel substance evaluation pathways remain underdeveloped for phospholipid-bound actives, delaying pharmaceutical-tier market entry. Mumbai-based contract manufacturers pilot microencapsulation technologies for functional food fortification applications.
Krill Oil Phospholipid Market Competitive Landscape
Player mix skews toward vertically integrated Antarctic operators and regional extraction specialists with coastal processing assets. Three to five suppliers control premium-tier MSC-certified volume through catch-to-capsule infrastructure investments. Strategic archetypes include Antarctic fleet owners with proprietary harvesting rights, Nordic coastal processors with supercritical extraction capabilities, and North American distributors with practitioner-channel relationships. Competitive moves concentrate on certification maintenance, extraction technology licensing, and direct-to-clinic distribution network expansion.
Within the vertically integrated tier, Aker BioMarine and Rimfrost occupy positions defined by Antarctic operational control and Norwegian coastal processing infrastructure respectively. Neptune Wellness Solutions represents the North American distribution-focused archetype with branded finished goods positioning. Qingdao Kangjing Marine Biotechnology and Xi'an Prius Biological Engineering exemplify Chinese processors leveraging import raw material access for domestic formulation supply. Norwegian Fish Oil occupies a specialist position within Nordic coastal extraction clusters.
| Leading Market Players |
|---|
| Aker BioMarine |
| Rimfrost |
| Neptune Wellness Solutions |
| Coastside Bio Resources |
| NutriGold |
| Qingdao Kangjing Marine Biotechnology |
| Fuji Chemicals |
| Xi'an Prius Biological Engineering |
| Norwegian Fish Oil |
| Others |
Pricing and Supply Chain Analysis
Antarctic fleet capacity utilization above 85 percent compresses per-unit harvesting costs for MSC-certified operators while erecting price floors that exclude non-integrated processors from pharmaceutical-grade contracting. This scale concentration amplifies buyer power asymmetry between Norwegian coastal extractors and North American brand owners seeking traceable phospholipid supply.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and commodity nutraceutical tiers. MSC certification combined with EMA GMP compliance commands 40-60 percent premiums over uncertified concentrate in practitioner-channel procurement. Cost compression in mass-market softgels is intensifying because algal oil substitutes erode volume-based economies for hexane-extracted krill oil. Retail pharmacy buyers exhibit highest price sensitivity, while functional medicine clinics absorb premium positioning for liquid concentrate formats.
Supply Chain Analysis
Punta Arenas port congestion during Antarctic summer campaigns creates seasonal chokepoints that delay raw material landing for Norwegian and Chinese processors. Antarctic krill harvest concentrates in Norway, China, and South Korean-flagged operations drawing from CCAMLR-managed biomass zones. Extraction infrastructure rests on ethanol and CO2 inputs for supercritical processing, plus gelatin and plant-derived capsule shell materials. Single-source vulnerability runs through Antarctic vessel operators dependent on Montevideo repair facilities. Distribution runs through Hamburg logistics hubs for European nutraceutical manufacturers and direct-to-clinic networks for US functional medicine practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party phospholipid testing and certification documentation services expand faster than raw krill oil extraction hardware, creating recurring-revenue attach opportunities for quality assurance providers serving pharmaceutical partnerships.
For Market Incumbents: Fortify Antarctic catch-to-capsule infrastructure against algal oil substitution threats by locking practitioner-channel relationships through medical education investments. Prioritize supercritical CO2 extraction capacity additions in Bergen coastal clusters to preserve pharmaceutical-grade margin capture as hexane processing commoditizes. For New Entrants and Emerging Players: FSSAI harmonization with CODEX standards creates a certification fast-track for MSC-certified concentrate entry into India nutraceutical formulations. Pediatric liquid concentrate applications represent the most penetrable white-space segment with limited current phospholipid-specific offerings. Pursue direct-to-clinic distribution partnerships with US functional medicine networks to bypass retail pharmacy margin stacking. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors supercritical extraction specialists with pharmaceutical-grade qualification over commodity softgel manufacturers facing algal oil displacement. Five-to-ten year viability hinges on Antarctic biomass assessment stability and phospholipid standardization protocol adoption. Monitor CCAMLR quota adjustment announcements as the critical inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| MSC Certification Maintenance | Sustains Antarctic fishery access for Norwegian and Chinese fleet operators under CCAMLR ecosystem monitoring protocols. |
| Supercritical CO2 Extraction Scale-Up | Preserves phospholipid integrity for EMA GMP-compliant pharmaceutical partnerships against hexane-based commodity competition. |
| Direct-to-Clinic Distribution Expansion | Bypasses retail pharmacy margin capture for US functional medicine networks specifying bioavailability-optimized omega-3 protocols. |
| Pediatric Liquid Concentrate Development | Addresses underserved neurodevelopmental application segment with palatable emulsion formats for precise titration dosing. |
| Antarctic Vessel Fleet Retrofit | EU F-Gas Regulation compliance for ammonia-based refrigeration systems maintains Norwegian-flagged operational licensing. |
Research Methodology
A spread of perspectives from Antarctic fleet operators, Norwegian extraction plant managers, US functional medicine practitioners, and EMA regulatory affairs specialists converged on the working assumptions for phospholipid demand trajectories. Primary interviews with dietary supplement brand owners and pharmaceutical formulation scientists combined with secondary validation from CCAMLR biomass assessments, FDA 21 CFR Part 111 guidance documents, EFSA novel food evaluation records, and EU F-Gas Regulation implementation schedules. Bottom-up volume modeling across product formats triangulated against top-down value projections from regional consumption patterns.
Segmentation dimensions modeled include product type, application tier, end-user specification stringency, and distribution channel configuration across the analysis window. Pharmaceutical-grade versus nutraceutical positioning, MSC certification status, and supercritical versus conventional extraction method differentiated margin capture assumptions. CAGRs derived from installed base growth rates adjusted for algal oil substitution elasticity and practitioner-channel penetration curves. Antarctic biomass volatility and phospholipid standardization protocol adoption served as scenario-weighting inputs.
Decision-makers should treat outputs as directional under sustained CCAMLR quota stability and EMA GMP compliance maintenance assumptions; material deviation in Antarctic ecosystem monitoring or EU refrigerant regulation enforcement would warrant model refresh. Forecasts reflect these base conditions without anticipating regulatory discontinuities or breakthrough algal oil cost reductions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Carnitine Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market