
 Asia-Pacific Feed Prebiotics Market | 2026-2036
Asia-Pacific Feed Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Feed Prebiotics Market Outlook
The Asia-Pacific feed prebiotics sector is repositioning around a widening gap between pharmaceutical-grade inulin and commodity oligosaccharide blends. Cargill Inc leverages its Bangkok formulation hub to supply standardized fructooligosaccharide premixes across ASEAN livestock operations. Beneo GmbH anchors premium positioning through chicory root extraction capacity in Chile that feeds Asian pharmaceutical and specialty feed channels.
Feed prebiotics are non-digestible carbohydrate substrates, typically inulin or fructooligosaccharides with polymerization degrees of 2-60, that selectively ferment in the distal gut to promote beneficial microflora and suppress pathogenic colonization in monogastric and ruminant species. Their primary commercial purpose is to replace or reduce prophylactic antibiotic use while maintaining feed conversion efficiency. Oligosaccharides and fructooligosaccharides command volume leadership due to lower production costs and broader compatibility with standard feed mills, though chicory root extract captures concentrated margin pools in antibiotic-free and organic certification tiers. Powder formulations dominate manufacturing logistics across Indonesia and Thailand, while liquid prebiotics gain traction in Vietnam's intensive shrimp pond systems where tank-mixing protocols favor aqueous delivery.
India's BIS feed additive standards, China's SAMR registration requirements for imported prebiotic substrates, and Vietnam's CEA-aligned agricultural input quality protocols collectively shape product registration timelines and import documentation burdens. These frameworks push multinational suppliers toward localized fermentation partnerships or joint ventures to circumvent extended approval cycles. Stakeholders must track evolving substrate purity thresholds and country-of-origin documentation rules as regional regulators harmonize with Codex Alimentarius guidelines.
Market Dynamics
Antibiotic reduction mandates across Southeast Asian livestock sectors are compressing feed formulation cycles and forcing rapid prebiotic substitution protocols. Vietnam's CEA-aligned agricultural input quality protocols and China's SAMR registration requirements for imported substrates create dual-track compliance burdens that favor localized fermentation partnerships over direct import models.
Growth Catalysts
- GB Standards Tightening:China's feed additive purity thresholds are accelerating substrate specification upgrades across integrated poultry operations. Domestic suppliers with captive chicory root processing capacity capture preferential procurement slots.
- Shrimp Pond Intensification:Vietnam's Mekong Delta aquaculture belt is driving liquid prebiotic adoption for tank-mixing protocols. Aqueous delivery systems bypass powder formulation limitations in high-density pond systems.
- FSSAI Alignment:India's quality protocol harmonization with food safety standards is elevating pharmaceutical-grade inulin demand. Specialty feed channels now require documented substrate chain-of-custody from extraction to finished premix.
Market Restraints
- Chicory Root Supply Concentration:European and Chilean extraction capacity controls premium inulin feedstock. Asian formulators face margin compression when currency volatility hits euro-denominated raw material contracts.
- SAMR Registration Timelines:China's imported substrate approval cycles extend 18-24 months. Multinational suppliers delay market entry rather than absorb working capital burdens from documentation backlogs.
- Commodity Oligosaccharide Substitution:Lower-polymerization fructooligosaccharide blends from domestic fermentation displace premium substrates in price-sensitive broiler operations. Feed conversion efficiency gaps narrow under controlled farm trials.
Strategic Opportunities
- Indonesia's Integrated Poultry Corridors:Java and Sumatra operations lack localized prebiotic blending capacity. Joint ventures with domestic feed mills bypass import documentation burdens while capturing vertical integration premiums.
- Dual Carbon Policy Convergence:China's MEE methane reduction targets and Vietnam's CEA sustainable agriculture incentives create regulatory tailwinds. Prebiotic suppliers positioning ruminant methane suppression claims access preferential procurement frameworks.
- Precision Fermentation Scale-Up:Biosynthetic oligosaccharide production is modularizing substrate manufacturing. Thai and Malaysian biotechnology parks offer tax-advantaged infrastructure for pilot-to-commercial fermentation expansion.
Industry Challenges
- Microbiome Assay Standardization:Gut flora response measurement lacks cross-laboratory consistency. Feed formulators cannot benchmark prebiotic efficacy across supplier claims without harmonized in-vitro fermentation protocols.
- Legacy Feed Mill Retrofit Costs:Powder-to-liquid handling systems require capital outlays that mid-scale Indonesian operations defer. Aqueous prebiotic adoption concentrates among integrated multinationals with captive engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Feed Prebiotics Market |
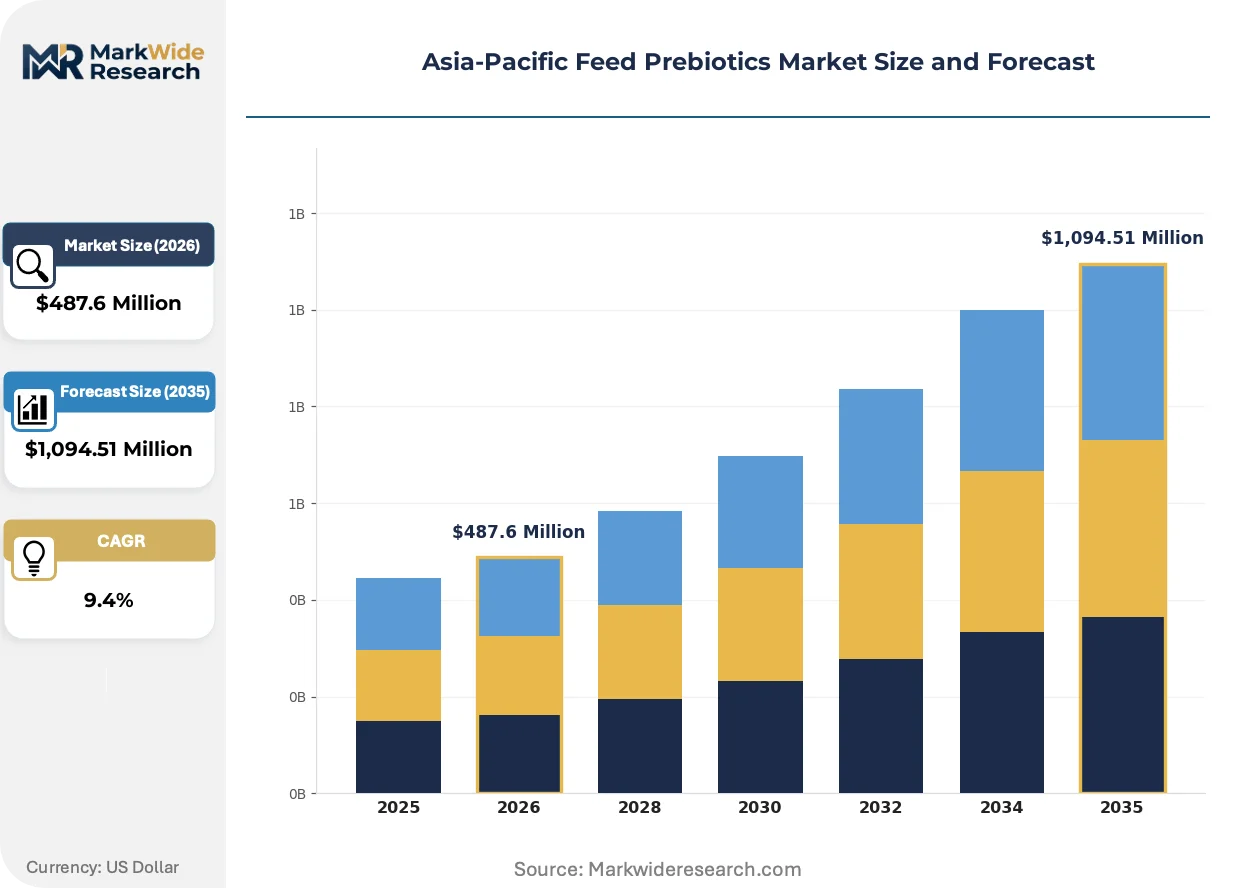
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligosaccharides, Chicory Root Extract, Fructooligosaccharides End User: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granular, Pellets Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | Behn Meyer, Acadian Seaplants Ltd, Beneo GmbH, FrieslandCampina Domo, Abbott Laboratories, Cargill Inc, Cosucra Groupe Warcoing SA, Impextraco NV, Alltech Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Feed Prebiotics Market Strategic Shifts
Bioprocess engineering advances and regulatory chemistry disclosure requirements are compressing the gap between commodity oligosaccharide production and pharmaceutical-grade substrate purification. Three distinct vectors are reshaping competitive positioning across the Asia-Pacific feed prebiotics sector.
Precision fermentation platforms using engineered yeast strains are modularizing oligosaccharide manufacturing. Thai biotechnology clusters and Malaysian industrial parks host pilot-scale facilities that bypass chicory root extraction dependencies. Integrated poultry operations in Indonesia's Java corridor now source biosynthetic fructooligosaccharides with polymerization degrees tunable to specific growth-stage formulations.
SAMR's 2023 feed additive registration amendments mandate full substrate impurity profiling for imported prebiotics. Chinese livestock conglomerates are forcing supplier qualification audits that extend 14-18 months. Domestic fermentation joint ventures in Shandong and Guangdong provinces capture market share by circumventing extended import approval cycles.
Certificate-of-origin documentation is displacing price-based supplier selection in Vietnam's shrimp export sector. Mekong Delta intensive pond operators now require BIS-aligned or FSSAI-equivalent quality attestations to satisfy EU import residue standards. Premium pricing for documented pharmaceutical-grade inulin concentrates among antibiotic-free certification tiers serving European retail channels.
Asia-Pacific Feed Prebiotics Market Segmentation
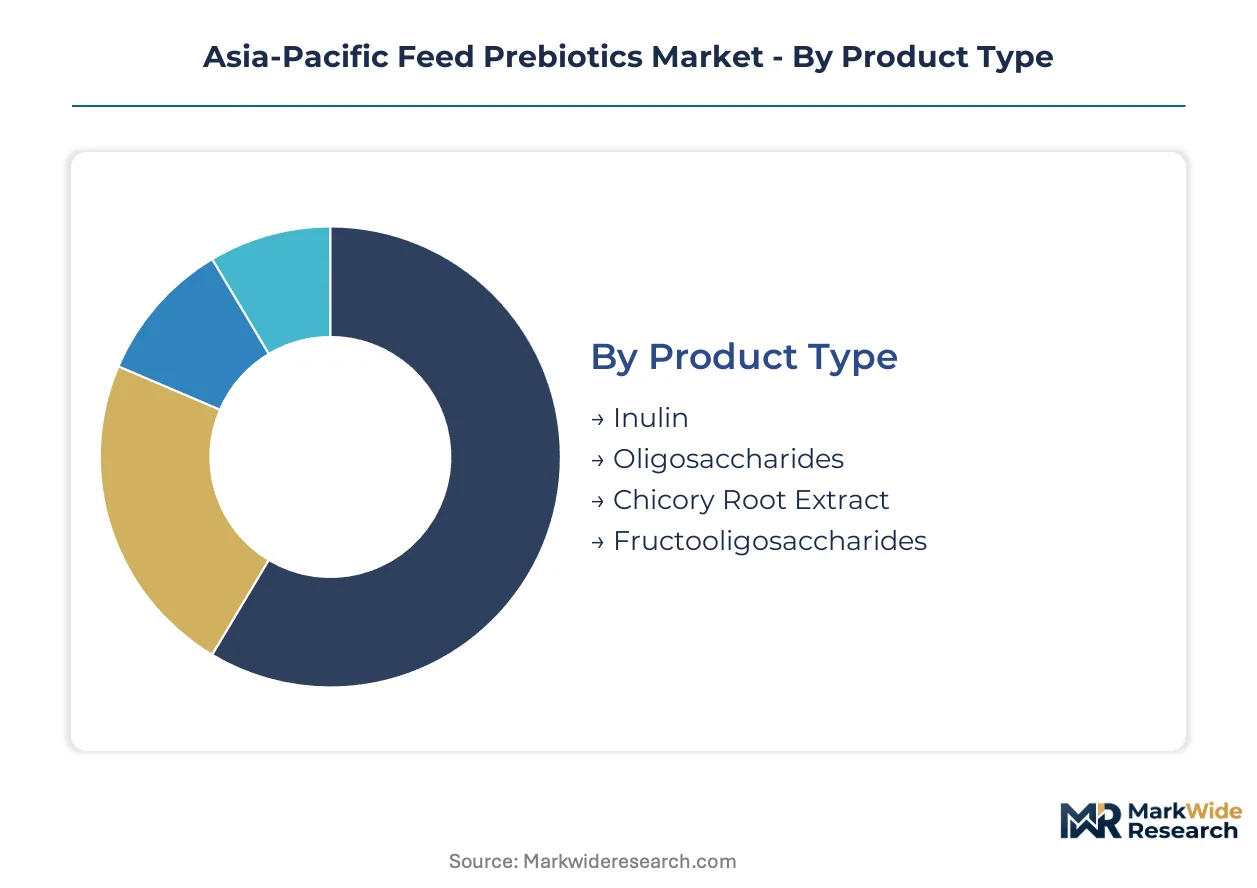
Feed prebiotic segmentation across Asia-Pacific reveals divergent commercial logics between commodity oligosaccharide volume plays and pharmaceutical-grade substrate margin capture. Formulation requirements vary sharply across Vietnam's intensive aquaculture, Indonesia's integrated poultry corridors, and India's emerging antibiotic-free certification tiers.
Product Type:
Volume leadership concentrates in lower-polymerization substrates, while premium positioning attaches to documented chain-of-custody extraction processes.
- Inulin:Long-chain fructan with polymerization degrees of 10-60, extracted primarily from chicory root through hot water diffusion and spray-drying refinement. Pharmaceutical-grade specifications command concentrated demand from India's FSSAI-aligned specialty feed channels and China's antibiotic-free poultry certification tiers, constrained by euro-denominated raw material exposure.
- Oligosaccharides:Short-chain carbohydrates with degrees of polymerization below 10, manufactured through enzymatic hydrolysis of sucrose or starch substrates. Domestic fermentation partnerships in Thailand and Malaysia supply standardized blends across Indonesia's broiler operations, bypassing SAMR import documentation burdens.
- Chicory Root Extract:Concentrated inulin fractions from Belgian and Chilean processing capacity, serving premium organic certification segments.
- Fructooligosaccharides:Beta-2,1 linked fructose oligomers with prebiotic selectivity for bifidobacteria colonization in monogastric species.
Mature deployment sits with Oligosaccharides. Newer deployment is concentrated in Chicory Root Extract.
End User:
Species-specific gut physiology dictates formulation polymerization requirements and delivery system choices.
- Poultry:Broiler operations across Java and Sumatra corridors drive powder premix incorporation at starter and grower phases. GB standards tightening accelerates substrate specification upgrades among China's integrated poultry conglomerates.
- Aquaculture:Vietnam's Mekong Delta intensive shrimp ponds favor liquid prebiotic delivery through tank-mixing protocols. Aqueous systems bypass powder formulation limitations in high-density pond environments where feed conversion efficiency directly determines export viability.
- Swine:Post-weaning diarrhea suppression protocols in South Korean and Japanese operations favor oligosaccharide inclusion.
- Ruminants:Methane suppression claims align with China's MEE dual carbon targets and Vietnam's CEA sustainable agriculture incentives.
Swine applications represent the most established end-use baseline. Aquaculture deployment is expanding most quickly.
Form:
Handling infrastructure maturity determines adoption patterns across mid-scale versus integrated operations.
- Powder:Dominates manufacturing logistics across Indonesia and Thailand feed mills, compatible with standard premix blending equipment. Legacy mill infrastructure sustains powder preference despite liquid efficacy advantages in specific applications.
- Liquid:Gains traction in Vietnam's shrimp pond systems and Philippine aquaculture zones where tank-mixing protocols enable precise dosing control. Capital requirements for powder-to-liquid handling retrofits concentrate adoption among multinational integrated operations.
- Granular:Flowability-optimized for automated feed mill dosing systems in Australian and New Zealand ruminant operations.
- Pellets:Co-extruded prebiotic incorporation for specialty antibiotic-free certification tiers.
Granular formulations anchor current infrastructure compatibility. Liquid systems are gaining share fastest.
Distribution Channel:
Regulatory documentation burdens reshape channel preference between direct supply and intermediated procurement.
- Direct Sales:Multinational suppliers with localized fermentation joint ventures in Shandong and Guangdong bypass extended SAMR registration timelines. Captive relationships with China's livestock conglomerates lock in 14-18 month qualification cycles.
- Distributors:Indonesian and Vietnamese mid-scale feed mills rely on regional distributors for fragmented procurement of commodity oligosaccharide blends. Documentation aggregation across multiple suppliers reduces per-transaction compliance overhead.
- Online:Emerging platform-based procurement for standardized premix specifications in Australian and Japanese specialty feed segments.
- Offline:Traditional feed additive trading networks sustain volume in Philippine and Malaysian broiler operations.
Offline channels retain volume concentration. Direct Sales deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok anchors formulation activity across Southeast Asia through Cargill's regional blending hub. Chinese livestock conglomerates in Shandong and Guangdong provinces drive substrate specification upgrades. Vietnam's Mekong Delta intensive aquaculture belt favors liquid delivery systems for tank-mixing protocols.
China
Integrated poultry operations in Shandong and Guangdong provinces demand pharmaceutical-grade inulin for antibiotic-free certification tiers. SAMR registration requirements extend 18-24 months for imported substrates, pushing domestic fermentation joint ventures to capture preferential procurement slots. Guangdong's livestock conglomerates now require full substrate impurity profiling under 2023 feed additive amendments.
Vietnam
Mekong Delta shrimp pond intensification drives liquid prebiotic adoption for high-density tank-mixing protocols. CEA-aligned agricultural input quality protocols mandate documented chain-of-custody for EU export compliance. Can Tho and An Giang provinces concentrate aqueous delivery system deployment where feed conversion efficiency determines export viability.
Indonesia
Java and Sumatra integrated poultry corridors lack localized prebiotic blending capacity, creating joint venture opportunities with domestic feed mills. Mid-scale operations defer powder-to-liquid handling retrofits due to capital constraints. Surabaya and Medan feed mill clusters sustain commodity oligosaccharide demand through legacy infrastructure compatibility.
India
Maharashtra and Gujarat specialty feed channels elevate pharmaceutical-grade inulin demand under FSSAI-aligned quality protocols. Documented substrate chain-of-custody from extraction to finished premix now serves antibiotic-free certification tiers. Pune and Ahmedabad formulators capture margin pools in organic poultry segments requiring BIS feed additive standard compliance.
Thailand
Biotechnology parks in Pathum Thani and Rayong provinces host precision fermentation pilot facilities for biosynthetic oligosaccharide production. Tax-advantaged infrastructure attracts modular substrate manufacturing investments. Bangkok's formulation hub supplies standardized fructooligosaccharide premixes across ASEAN livestock operations with tunable polymerization degrees.
Asia-Pacific Feed Prebiotics Market Competitive Environment
Premium-margin players sit above commodity-margin players across substrate purity and documentation tiers. Chicory root extraction specialists command concentrated margin pools in pharmaceutical-grade and organic certification segments, while domestic fermentation partnerships capture volume in standardized oligosaccharide blends. Three archetypes dominate: European extraction houses with captive raw material control, Asian joint venture formulators bypassing import documentation burdens, and precision fermentation startups modularizing production. Competitive moves center on localized fermentation partnerships to circumvent SAMR registration timelines and backward integration into chicory root processing to defend margin position.
Among European extraction specialists, Beneo GmbH and Cosucra Groupe Warcoing SA exemplify premium-tier positioning through captive chicory root supply chains. Cargill Inc anchors the multinational formulator archetype with regional blending infrastructure. These three represent divergent strategic paths: extraction-dependent margin capture, fermentation-based volume scaling, and integrated formulation logistics across ASEAN corridors.
| Leading Market Players |
|---|
| Behn Meyer |
| Acadian Seaplants Ltd |
| Beneo GmbH |
| FrieslandCampina Domo |
| Abbott Laboratories |
| Cargill Inc |
| Cosucra Groupe Warcoing SA |
| Impextraco NV |
| Alltech Inc |
| Others |
Value Chain & Pricing Dynamics
Fermentation engineering talent concentration in Thai biotechnology parks widens labor-cost differentials between precision-manufactured oligosaccharides and extraction-dependent inulin grades. This workforce asymmetry propagates three-tier pricing spreads across pharmaceutical-grade, certified-standard, and commodity substrate tiers.
Pricing Analysis
Yield-linked pricing anchors premium tiers, with pharmaceutical-grade inulin commanding spreads tied to documented feed conversion efficiency in antibiotic-free poultry certifications. Price differentiation separates FSSAI-aligned chain-of-custody substrates from commodity fermentation blends, with GB standards tightening in China accelerating specification upgrades. Pricing pressure stems from domestic oligosaccharide substitution in Indonesian broiler operations, where controlled farm trials narrow efficiency gaps. Mid-scale feed mills exhibit highest price sensitivity, while integrated livestock conglomerates absorb premiums for documented impurity profiles.
Supply Chain Analysis
SAMR registration requirements and FSSAI-aligned quality protocols gate supply access, extending qualification timelines for imported substrates. Raw material dependencies center on Chilean and Belgian chicory root extraction, Thai and Malaysian fermentation capacity, and Chinese domestic enzymatic processing. Supply chain risk concentrates in euro-denominated raw material exposure amid currency volatility. Distribution runs through Bangkok formulation hubs for ASEAN coverage, direct sales to Chinese livestock conglomerates, and regional distributors serving fragmented Indonesian and Vietnamese mid-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
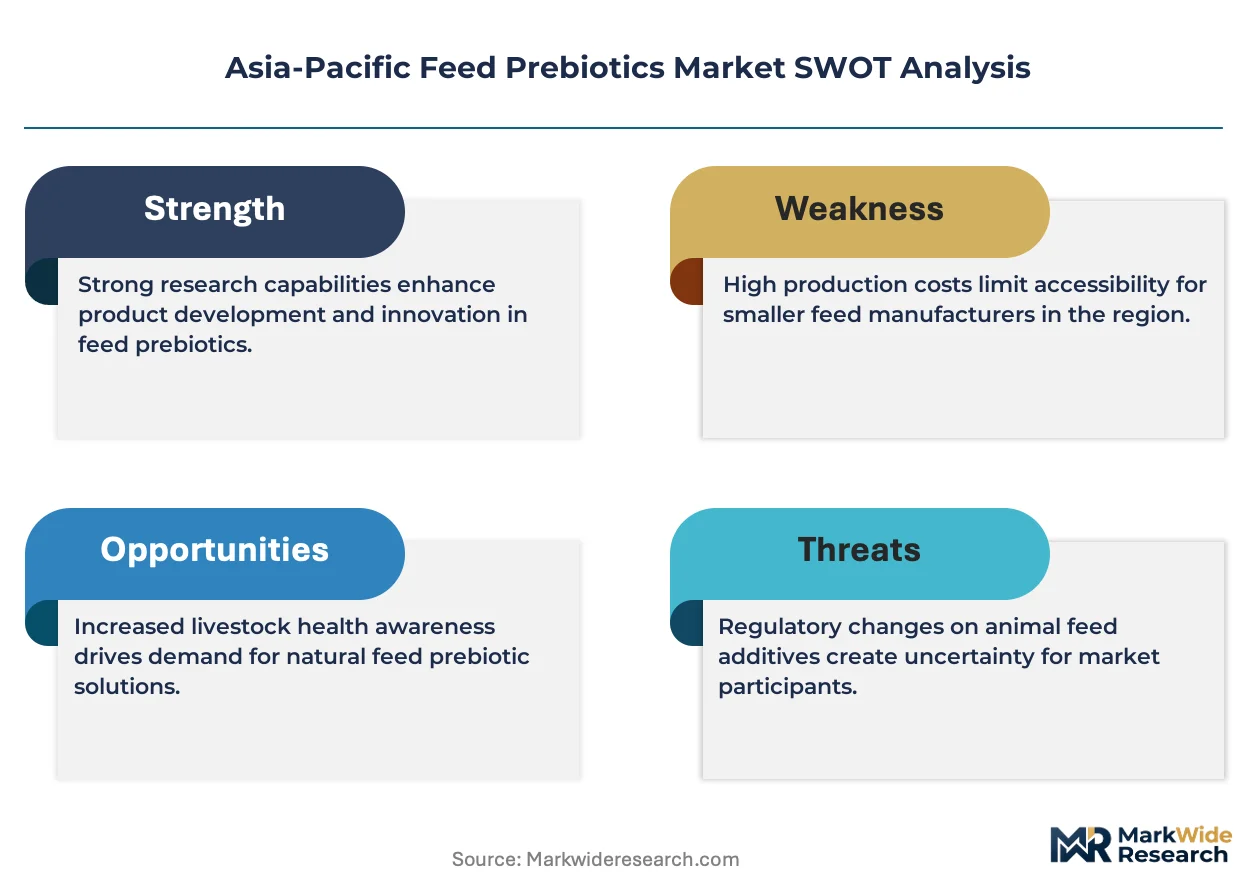
Chicory root processing capacity constraints in Europe and Chile prop pricing power for extraction-dependent grades, creating a supply-constrained market structure favoring backward-integrated players.
For Market Incumbents: Cement captive chicory root supply through offtake agreements with Chilean processors before currency hedging costs escalate. Expand fermentation joint ventures in Shandong and Guangdong provinces to circumvent SAMR registration bottlenecks threatening import-dependent competitors. For New Entrants and Emerging Players: Begin with precision fermentation platforms in Thai biotechnology parks, targeting standardized oligosaccharide supply to Indonesian feed mills lacking localized blending capacity. Pursue aqueous delivery system partnerships with Mekong Delta shrimp operators seeking tank-mixing alternatives to powder limitations. For Investors and Strategic Acquirers: Re-rating potential sits with domestic fermentation joint ventures given SAMR's 18-24 month import approval timelines compressing competitive entry. Long-term viability frames around biosynthetic substrate modularization displacing extraction-dependent supply chains. Watch for CEA-aligned documentation mandates spreading beyond Vietnam to other ASEAN export corridors as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Modularizes oligosaccharide production in Thai biotechnology parks, bypassing chicory root dependencies. |
| Domestic Joint Venture Formation | Circumvents SAMR registration timelines through Shandong and Guangdong localized manufacturing partnerships. |
| Backward Integration into Extraction | Captures margin pools in pharmaceutical-grade inulin through Chilean chicory root processing control. |
| Liquid Delivery System Development | Addresses Vietnam Mekong Delta tank-mixing protocols where powder formulations face technical limitations. |
| Certification Documentation Investment | Secures FSSAI-aligned and BIS-equivalent chain-of-custody for EU export compliance in antibiotic-free tiers. |
Study Parameters
Document review covered SAMR registration filings, FSSAI quality protocol amendments, CEA agricultural input standards, and ASEAN customs trade data, complemented by interviews with feed formulators, livestock procurement directors, fermentation plant managers, and regulatory affairs specialists. Secondary validation drew from BIS feed additive standards, GB specification updates, and Codex Alimentarius guideline harmonization reports. Bottom-up substrate volume estimates triangulated against top-down premix consumption models.
Segment-level outputs across product type, end user, form, and distribution channel dimensions were generated through demand-side aggregation and supply-side capacity reconciliation. CAGRs derived from installed fermentation capacity expansion curves, poultry and aquaculture stocking density projections, and regulatory compliance cost trajectories. Model inputs incorporated polymerization degree specification trends, antibiotic reduction mandate implementation schedules, and export certification tier penetration rates.
Currency volatility in euro-denominated raw material contracts, SAMR registration timeline extensions, and commodity oligosaccharide substitution efficacy breakthroughs are the dominant revision risks. Forecasts reflect assumptions regarding CEA protocol harmonization pace and MEE methane reduction target enforcement intensity. A model refresh is warranted upon material change in SAMR feed additive amendment implementation or chicory root harvest yield volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Vegan Supplements Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
Tongkat Ali Extract Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Tryptophan Market