
 Policosanol Market | 2026-2036
Policosanol Market Size, Share, and Industry Trends Forecast 2026-2036
Policosanol Market Analytics
Direct-to-consumer online channels is reshaping how policosanol reaches end users, bypassing traditional pharmacy gatekeepers. Sabinsa leverages its botanical extraction infrastructure to sustain supply consistency across multiple geodes. Bioriginal Food & Science Corp anchors its position through backward integration into raw material sourcing. ZXCHEM Group competes on manufacturing scale, occupying cost-sensitive bulk segments in Asia-Pacific supply chains.
Policosanol comprises long-chain aliphatic alcohols, typically C24 to C34, extracted from plant waxes through saponification and solvent purification processes; it functions primarily as a lipid-modulating agent in dietary supplements and functional foods. Sugar cane-derived policosanol dominates commercial volumes due to higher octacosanol yields, while wheat germ grades command premium positioning in European nutraceutical formulations. The pharmaceutical end-use segment leads value pools, though nutraceutical tablets and capsules represent the fastest-expanding formulation category as self-directed wellness consumption rises.
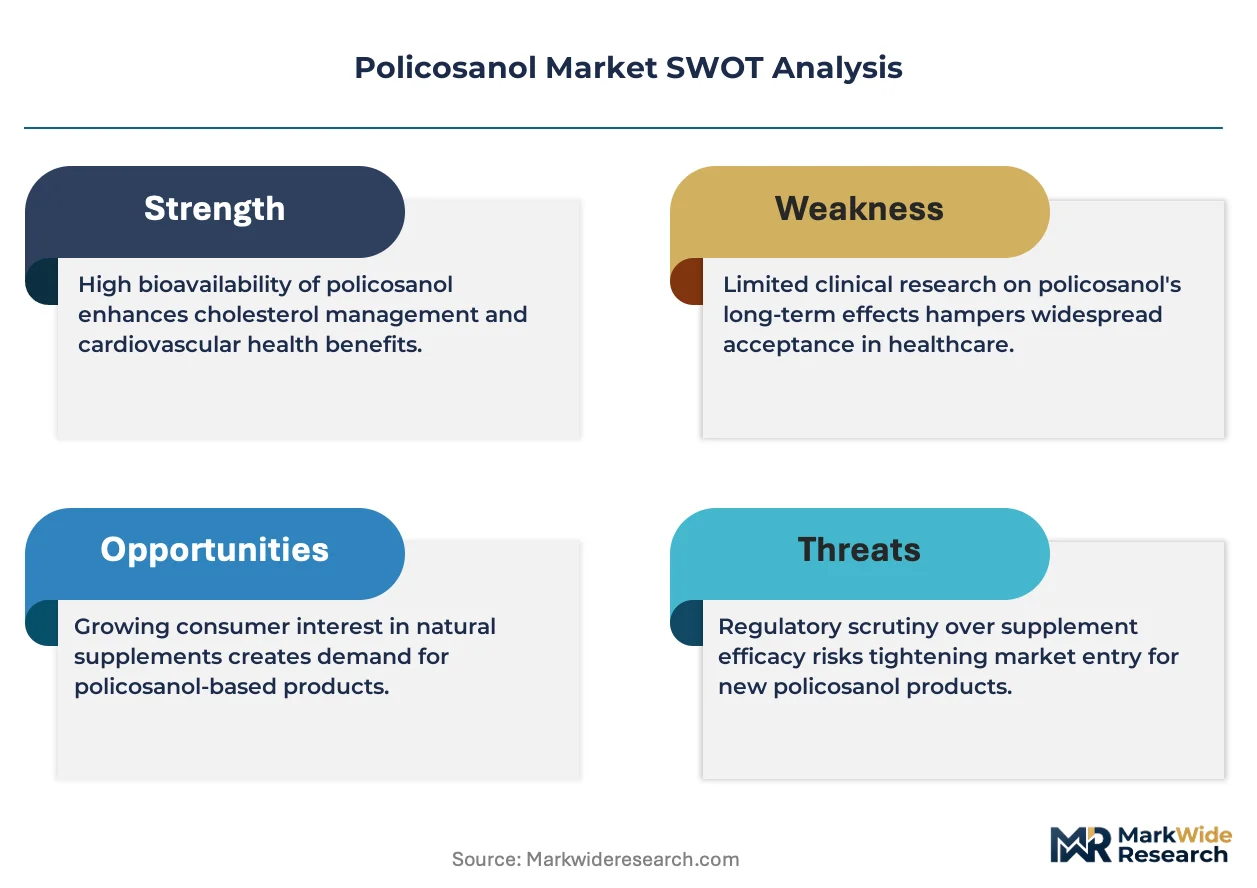
The U.S. FDA's dietary supplement cGMP enforcement and the EFSA's health claims authorization framework jointly determine market access thresholds for policosanol products across North America and Europe. India's FSSAI and CDSCO regulate import purity standards and novel food approvals, creating compliance complexity for Asian manufacturers targeting subcontinent demand. Stakeholders must monitor evolving pharmacovigilance requirements for botanical cholesterol modifiers as regulators scrutinize cardiovascular benefit substantiation.
Market Dynamics
Direct-to-consumer nutraceutical channels are compressing traditional pharmacy distribution, forcing policosanol suppliers to reconfigure fulfillment infrastructure around e-commerce velocity and subscription-based replenishment models.
Growth Catalysts
- Sugar cane wax extraction yields:Brazilian and Cuban biomass processors achieve higher octacosanol purity through improved saponification methods, lowering input costs for cholesterol-management formulations.
- FDA New Dietary Ingredient pathway:Clarified notification requirements reduce regulatory uncertainty for U.S. supplement manufacturers launching policosanol SKUs.
- Self-directed cardiovascular wellness:Consumer preference for non-statin lipid modifiers drives tablet and capsule demand through online direct channels.
Market Restraints
- Raw material geographic concentration:Sugar cane wax supply clusters in tropical zones expose processors to climate-induced harvest volatility and shipping disruption.
- EFSA health claims authorization gaps:Unapproved cholesterol-reduction claims block European pharmaceutical positioning and limit premium pricing power.
- Red yeast rice substitution:Competing botanical lipid modifiers with stronger clinical trial visibility capture shelf space in North American retail.
Strategic Opportunities
- Indian functional food integration:FSSAI novel food approval pathways enable policosanol incorporation into fortified edible oils and dairy alternatives.
- Wheat germ premium positioning:European organic certification standards support higher-margin pharmaceutical-grade extraction for cosmeceutical applications.
- Subscription direct-to-consumer models:Automated replenishment platforms bypass wholesale markups and capture lifetime value through compliance-driven repeat purchase.
Industry Challenges
- Phytochemical standardization expertise:Shortage of analytical chemists skilled in aliphatic alcohol chromatography slows quality control scaling.
- cGMP facility certification timelines:FDA inspection backlogs delay commercial launch schedules for new manufacturing entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Policosanol Market |
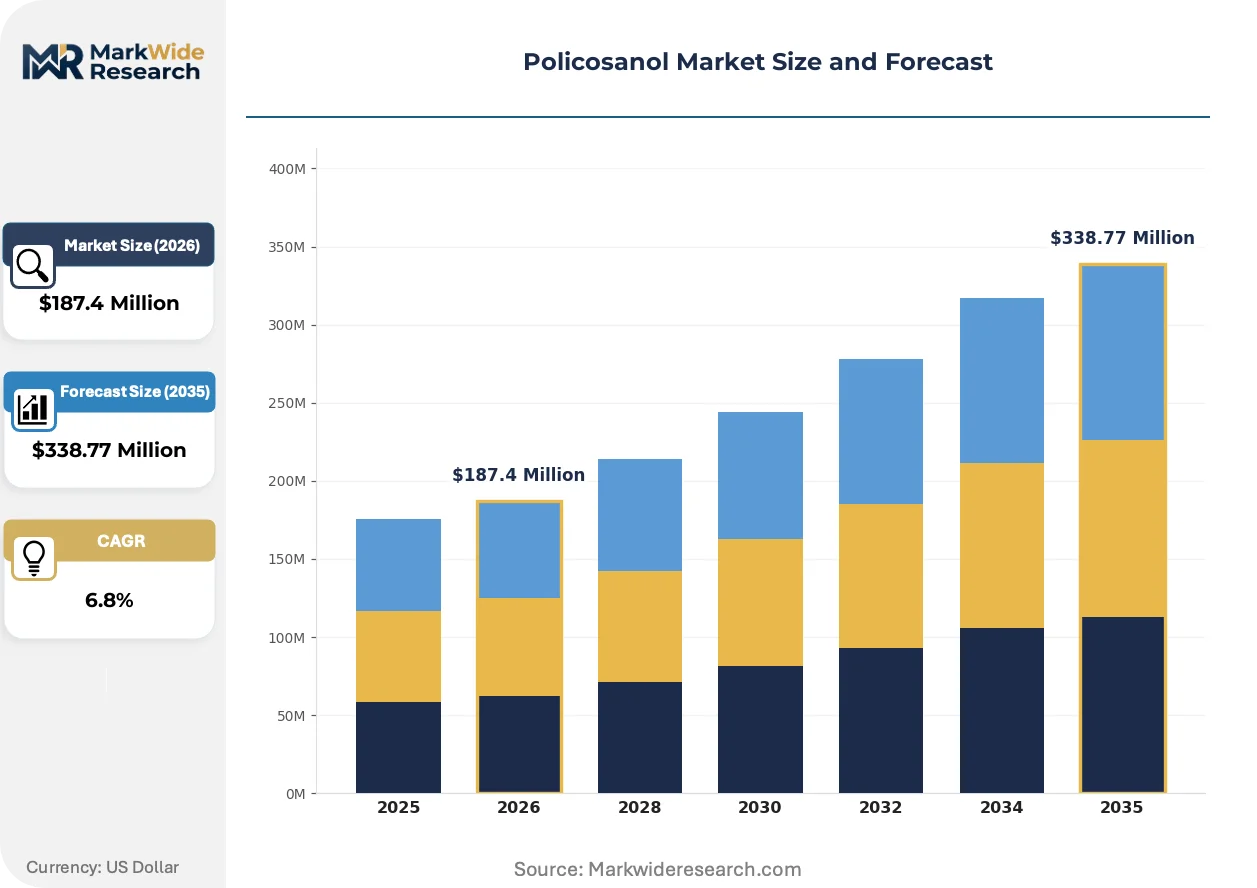
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Germ, Sugar Cane, Rice Bran, Others End User: Pharmaceuticals, Nutraceuticals, Food Industry, Cosmetics Formulation: Tablets, Capsules, Powders, Liquid Distribution Channel: Online Stores, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | ZXCHEM Group, Sabinsa, Sunpure Extracts Pvt Ltd., Bioriginal Food & Science Corp, Ambe Phytoextracts Pvt. Ltd., Manus Aktteva Biopharma LLP, BOC Sciences, Huzhou Shengtao Biotech LLC, Botanic Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Policosanol Market Evolving Landscape
Process analytical technology and blockchain traceability systems are redefining how policosanol batches move from biomass sourcing through finished supplement, compressing quality assurance cycles and enabling real-time chain-of-custody verification.
Supercritical CO2 extraction systems are digitizing traditional solvent-based purification workflows in sugar cane wax processing facilities. Mid-sized nutraceutical contract manufacturers in Germany and the United States are adopting these platforms to reduce residual solvent contamination risks. The technology is digitizing batch record documentation and enabling continuous manufacturing economics previously unavailable to botanical extractors.
REACH registration requirements for novel plant wax derivatives are tightening purity disclosure standards across European supply chains. ECHA substance evaluation dossiers now demand comprehensive toxicological profiles for C24-C34 alcohol fractions. Pharmaceutical-grade policosanol destined for EU markets faces extended registration timelines, pushing suppliers toward pre-registered feedstock sourcing.
Practitioner channel deconsolidation is fragmenting historical gatekeeper control over cholesterol-management recommendations. Functional medicine clinics and telehealth platforms are displacing traditional pharmacy counseling as primary education touchpoints. This shift concentrates most visibly in U.S. metropolitan markets where direct-to-consumer brands build prescriber affiliate networks.
Policosanol Market Segmentation
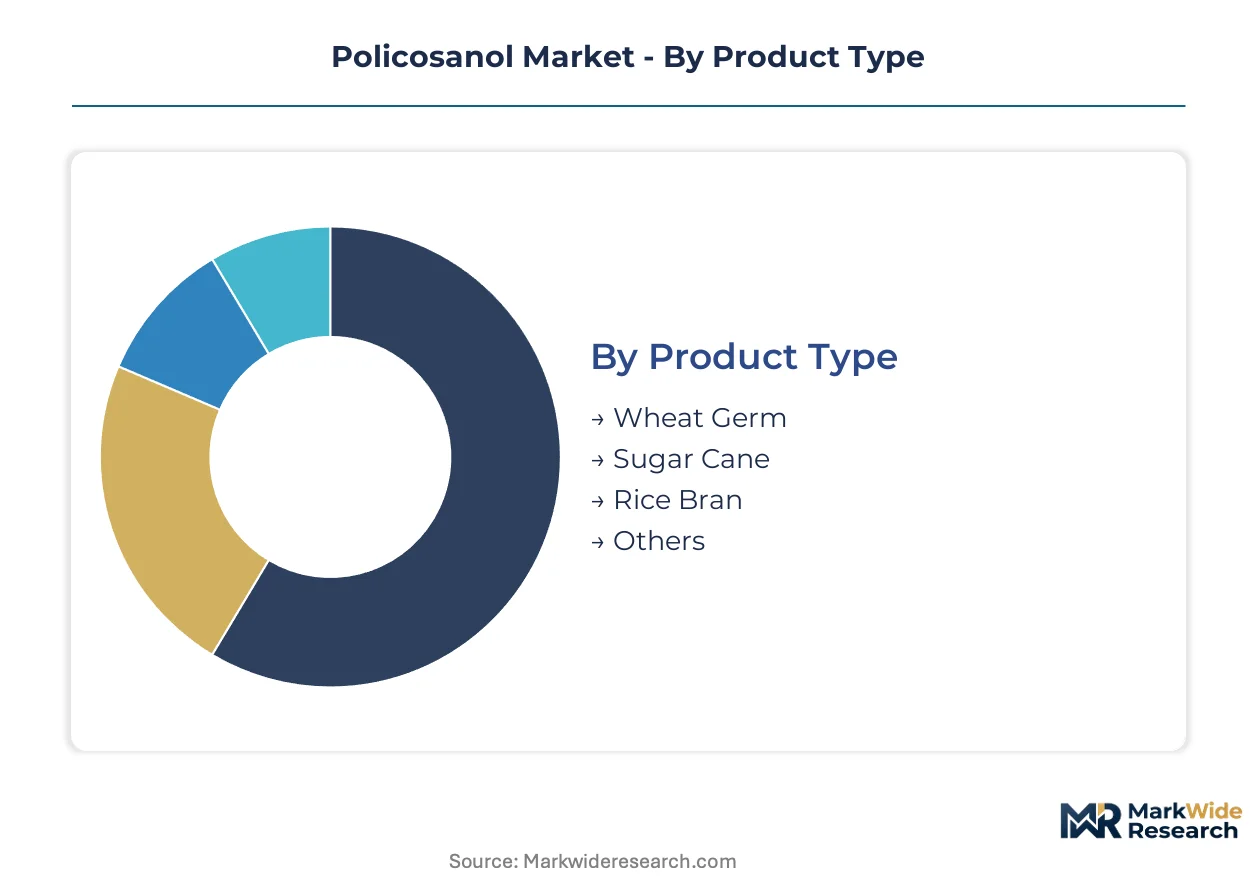
Policosanol's commercial structure fragments across extraction source, end-use application, and delivery format, with each axis commanding distinct margin profiles and regulatory compliance burdens. Manufacturers configure production assets around specific segment combinations rather than pursuing horizontal coverage.
Product Type:
Sugar cane wax grades turn inventory fastest through standardized bulk contracts, while wheat germ variants sit longer due to organic certification verification cycles.
- Sugar Cane:Long-chain aliphatic alcohols extracted from Saccharum officinarum wax yield 60-70% octacosanol content through saponification. Brazilian processors supply North American nutraceutical manufacturers seeking cholesterol-management formulations with consistent batch-to-batch purity.
- Wheat Germ:Triticum aestivum-derived fractions contain broader C24-C34 alcohol distributions with higher tocopherol co-extracts. German and French pharmaceutical compounders source this grade for cosmeceutical applications demanding organic certification and lower pesticide residue thresholds.
- Rice Bran:Oryza sativa wax fractions from Asian milling operations serve cost-sensitive functional food fortification in India and Southeast Asia.
- Others:Beeswax and yucca-derived policosanol occupy niche pharmaceutical applications requiring specific carbon chain distributions.
Sugar cane dominates installed base. Wheat germ is where expansion concentrates.
End User:
Cost tier stratification separates pharmaceutical-grade extraction investments from nutraceutical contract manufacturing economics.
- Nutraceuticals:Dietary supplement tablets and capsules drive volume through direct-to-consumer subscription platforms. U.S. cGMP compliance costs favor established contract manufacturers with validated analytical methods for aliphatic alcohol quantification.
- Pharmaceuticals:Prescription-grade formulations require FDA NDI notifications or EMA drug master file submissions for cardiovascular indications. European manufacturers face EFSA health claims authorization gaps that constrain cholesterol-reduction labeling.
- Food Industry:Functional food integration proceeds through FSSAI novel food approvals in India and GRAS self-affirmation pathways in the United States.
- Cosmetics:Emollient applications in premium skincare leverage wheat germ policosanol's tocopherol content for antioxidant positioning.
Pharmaceuticals capture premium pricing. Nutraceuticals are climbing the fastest.
Formulation:
Customer type preferences bifurcate between convenience-driven tablet demand and bioavailability-focused liquid formulations.
- Tablets:Compressed dosages with standardized 5-10mg policosanol content dominate U.S. and German direct-to-consumer channels. Manufacturers optimize for disintegration time and tablet hardness to meet USP dissolution specifications.
- Capsules:Gelatin and vegetarian shell formulations accommodate lipid-soluble delivery with co-formulated omega-3 or phytosterol combinations.
- Powders:Bulk active pharmaceutical ingredient supply serves contract manufacturers blending multi-ingredient cardiovascular stacks.
- Liquid:Emulsified suspensions target pediatric and geriatric populations with swallowing difficulties, primarily in Japanese and South Korean functional food applications.
Tablets anchor current revenue. Capsules show steepest expansion trajectory.
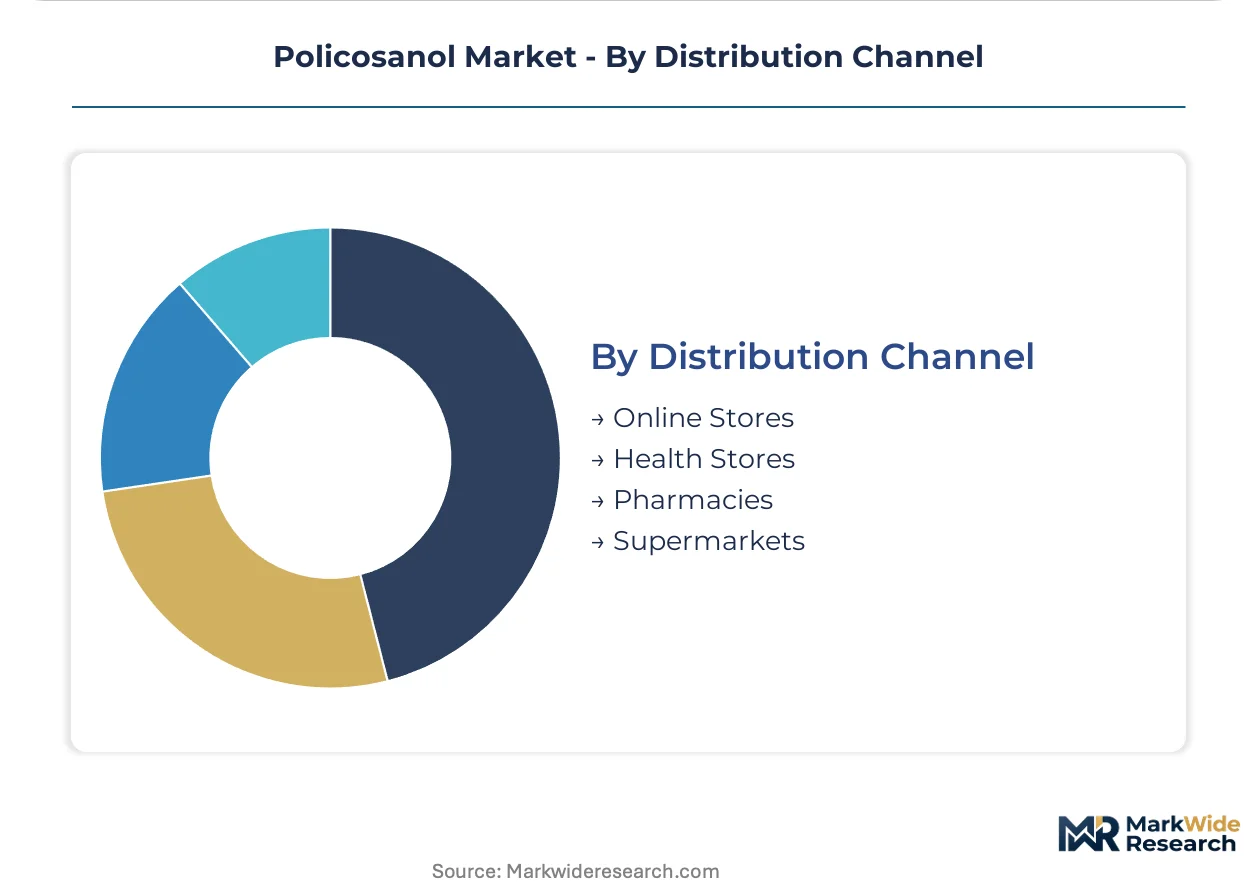
Distribution Channel:
Supply concentration in online infrastructure is displacing traditional pharmacy gatekeepers across metropolitan U.S. and German markets.
- Online Stores:Direct-to-consumer platforms bypass wholesale markups through automated replenishment algorithms. Amazon and specialized nutraceutical sites capture repeat purchase behavior for cholesterol-management regimens.
- Health Stores:GNC and independent supplement retailers provide education-intensive touchpoints for first-time policosanol purchasers seeking alternatives to statin therapy.
- Pharmacies:CVS, Walgreens, and Boots locations stock policosanol adjacent to red yeast rice and plant sterol competitors, with pharmacist counseling influencing selection.
- Supermarkets:Mass-market retail placement remains limited due to shelf-space competition and lower consumer recognition compared to established lipid modifiers.
Online stores command fastest inventory velocity. Health stores retain highest conversion rates for new category entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in Brazil anchors Atlantic supply chains for sugar cane wax feedstock, with dedicated bulk liquid terminals handling molasses-derived extraction inputs. German chemical processors at the Port of Hamburg receive refined policosanol intermediates through Rhine barge distribution networks.
United States
Direct-to-consumer nutraceutical channels drive formulation demand through Miami and Los Angeles distribution hubs. FDA cGMP enforcement and NDI notification requirements shape compliance investments for domestic supplement manufacturers. The Dallas-Fort Worth metroplex clusters contract manufacturing facilities serving subscription-based replenishment platforms.
Germany
EFSA health claims authorization gaps constrain cholesterol-reduction labeling for pharmaceutical-grade formulations. REACH registration requirements for C24-C34 alcohol fractions extend approval timelines for novel plant wax derivatives. The Frankfurt-Rhine-Main region concentrates supercritical CO2 extraction technology adopters serving cosmeceutical applications.
Brazil
Sugar cane wax supply dominates through São Paulo state milling operations with improved saponification methods lowering octacosanol production costs. ANVISA regulates import purity standards for botanical lipid modifiers entering pharmaceutical channels. The Campinas industrial corridor hosts biomass processors achieving higher alcohol purity yields.
India
FSSAI novel food approval pathways enable policosanol integration into fortified edible oils and dairy alternatives. CDSCO import regulations govern active pharmaceutical ingredient quality standards for cardiovascular formulations. Maharashtra and Gujarat house rice bran extraction facilities serving cost-sensitive functional food fortification across Southeast Asian markets.
Japan
PMDA pharmacovigilance requirements scrutinize cardiovascular benefit substantiation for botanical cholesterol modifiers. METI standards guide process analytical technology adoption in botanical extraction workflows. The Kansai region around Osaka maintains emulsified suspension production for pediatric and geriatric liquid formulations.
Policosanol Market Competitive Landscape
On the supply side, the industry is fragmented across extraction specialists, contract manufacturers, and integrated nutraceutical compounders with no dominant volume leader. Tiered competitive positioning separates premium wheat germ processors from cost-optimized sugar cane extractors. Two strategic archetypes define competitive posture: backward-integrated biomass processors controlling raw material sourcing, and technology-focused purification specialists leveraging supercritical extraction platforms. Capacity expansion and geographic licensing agreements constitute the dominant competitive moves as firms seek regulatory-compliant manufacturing footprints.
Within the integrated processor tier, ZXCHEM Group and Bioriginal Food & Science Corp exemplify supply chain control strategies, while Sabinsa occupies a position representing botanical extraction infrastructure scaled across multiple geographies. These three entities anchor the competitive landscape through distinct archetype representation rather than convergent strategic postures.
| Leading Market Players |
|---|
| ZXCHEM Group |
| Sabinsa |
| Sunpure Extracts Pvt Ltd. |
| Bioriginal Food & Science Corp |
| Ambe Phytoextracts Pvt. Ltd. |
| Manus Aktteva Biopharma LLP |
| BOC Sciences |
| Huzhou Shengtao Biotech LLC |
| Botanic Healthcare |
| Others |
Value Network & Pricing Analysis
São Paulo state milling operations anchor Atlantic feedstock capacity, with improved saponification yields at Brazilian biomass processors compressing octacosanol production costs and transmitting downstream pricing power to North American nutraceutical compounders negotiating long-term offtake agreements.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade wheat germ extracts from bulk sugar cane wax grades, with organic certification and FDA cGMP compliance acting as primary price differentiation drivers. Cost compression in standard-grade sugar cane policosanol is intensifying because Brazilian processors are achieving higher alcohol purity through digitized extraction workflows. Nutraceutical contract manufacturers exhibit highest price sensitivity due to thin margin absorption in direct-to-consumer channels, while cosmeceutical formulators demonstrate lowest sensitivity given tocopherol co-extract premiums in wheat germ variants.
Supply Chain Analysis
Contract manufacturing concentration sits with German supercritical CO2 extraction adopters and U.S. cGMP-validated facilities serving subscription-based replenishment platforms. Raw material supply draws from Brazilian sugar cane wax, German wheat germ, and Indian rice bran milling operations. Single-source vulnerability concentrates in tropical sugar cane harvest zones exposed to climate-induced disruption. Distribution runs through Miami and Los Angeles hubs for U.S. direct-to-consumer channels, with Rhine barge networks feeding European pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA NDI notification requirements and EFSA health claims authorization frameworks erect substantial compliance barriers against unvalidated entrants.
For Market Incumbents: Harden analytical chemistry capabilities in aliphatic alcohol chromatography to defend against phytochemical standardization expertise shortages slowing quality control scaling. Deepen backward integration into Brazilian sugar cane wax sourcing to secure captive supply of high-octacosanol feedstock against climate-induced harvest volatility threatening input security.
For New Entrants and Emerging Players: Pursue white-space positioning in Indian functional food fortification through FSSAI novel food approval pathways enabling policosanol integration into edible oils and dairy alternatives. Target cosmeceutical emollient applications in European premium skincare as the most penetrable segment given wheat germ policosanol's tocopherol content and organic certification premiums. Lead with practitioner affiliate networks in U.S. functional medicine clinics as the go-to-market angle bypassing traditional pharmacy gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors supercritical CO2 extraction specialists with digitized batch record documentation and continuous manufacturing economics. Long-term viability hinges on regulatory-compliant manufacturing footprints spanning FDA, EFSA, and FSSAI jurisdictions. Acquire targets with validated analytical methods and established cGMP certifications. Watch FDA inspection backlog resolution as the inflection signal indicating commercial launch schedule normalization for new manufacturing entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive supply of Brazilian sugar cane wax secures octacosanol yield consistency against harvest volatility. |
| Supercritical CO2 Extraction Technology Adoption | German contract manufacturers reduce residual solvent risks while digitizing batch record documentation workflows. |
| FSSAI Novel Food Approval Pathway Navigation | Indian functional food integration into fortified edible oils opens cost-sensitive volume expansion corridors. |
| Subscription Direct-to-Consumer Platform Buildout | Automated replenishment algorithms capture lifetime value through compliance-driven repeat purchase behavior. |
| EFSA Health Claims Authorization Investment | European cholesterol-reduction labeling unlocks pharmaceutical-grade premium positioning currently blocked by regulatory gaps. |
Research Methodology
Initial hypotheses were tested against primary input from nutraceutical formulation scientists, botanical extraction plant managers, regulatory affairs leads at supplement manufacturers, and procurement directors at contract manufacturing organizations, then refined through secondary validation against FDA NDI notification databases, EFSA health claims authorization registers, FSSAI novel food approval filings, and Brazilian agricultural export statistics, with bottom-up volume builds triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across extraction source, end-use application, formulation format, and distribution channel dimensions. CAGRs were derived from normalized growth trajectory analysis incorporating sugar cane wax yield improvements, cGMP facility certification timelines, and direct-to-consumer channel velocity shifts as industry-specific forecast inputs.
Sensitivities concentrate around FDA inspection backlog durations, EFSA health claims authorization resolution timelines, and tropical climate disruption severity affecting Brazilian sugar cane harvests. Quarterly review of NDI notification approval rates, supercritical CO2 extraction capacity additions, and practitioner channel deconsolidation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Omega-3 Products Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Global Digestive Enzymes Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Throat Lozenges Market
Nutritional Supplements
Direct Fed Microbials Market