
 Complete Nutrition Products Market | 2026-2036
Complete Nutrition Products Market Size, Share, and Industry Trends Forecast 2026-2036
Complete Nutrition Products Market Intelligence
Active aging consumers seeking clinical-grade meal replacements is rotating demand away from purely recreational protein buyers. Abbott Laboratories anchors its position through hospital and home-care channel control. Nestlé S.A. leverages extensive pediatric and adult medical nutrition R&D infrastructure across multiple continents. Danone S.A. specializes in dairy-derived and plant-based complete nutrition formats for institutional buyers.
Complete nutrition products are formulated meal systems delivering macro- and micronutrient profiles equivalent to standard dietary intake, typically manufactured via spray-drying, extrusion, or cold-blending processes to preserve bioactive compounds. Protein powders occupy the largest revenue pool due to entrenched gym-channel penetration, while meal replacements capture the fastest structural expansion as healthcare providers integrate them into post-surgical and chronic-disease protocols. Pea protein isolates are gaining ingredient share as manufacturers reformulate to reduce allergen load and satisfy clean-label procurement criteria.
The FDA governs medical food labeling and health claims under Orphan Drug Act provisions, while the EMA and national European regulators enforce Novel Food authorizations for emerging protein sources. China's SAMR mandates formula registration and clinical substantiation for domestically marketed complete nutrition products. Stakeholders must monitor evolving reimbursement codes and protein-source approval timelines to align portfolio investments with regulatory access pathways.
Market Dynamics
Hospital procurement consolidation and Medicare Advantage reimbursement expansion are compressing distribution margins while accelerating volume concentration among formulary-approved suppliers. This structural force favors manufacturers with integrated clinical evidence generation and direct-to-patient fulfillment infrastructure.
Growth Catalysts
- SAMR formula registration:China's tightened domestic marketing requirements for complete nutrition products are filtering out low-substantiation competitors and elevating clinical-grade suppliers with hospital trial data.
- Post-surgical recovery protocols:US health systems are embedding prescribed meal replacements into bundled payment models for bariatric and oncology procedures, creating institutional pull-through.
- Pea protein extraction yields:Advances in aqueous fractionation are reducing isolate production costs and enabling allergen-free formulations that qualify for clean-label hospital procurement.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity swings expose margin pressure for manufacturers without long-term supply contracts or backward integration into milk processing.
- Novel Food authorization timelines:EMA's 18-24 month assessment windows for emerging protein sources delay European launch schedules and tie up R&D capital.
- Enteral nutrition substitution:Tube-feeding formulations prescribed for identical clinical indications capture reimbursement codes that meal replacements cannot access in some markets.
Strategic Opportunities
- Germany's Diätverordnung reform:Proposed updates to medical food reimbursement criteria could expand pharmacy channel access for adult complete nutrition beyond current pediatric-focused codes.
- Home health monitoring convergence:Integration of continuous glucose tracking with personalized meal delivery is opening subscription models for diabetes management protocols.
- Southeast Asia hospital buildouts:Greenfield medical infrastructure in Vietnam and Indonesia lacks entrenched supplier relationships, creating first-mover positioning for clinical evidence holders.
Industry Challenges
- Medical affairs talent scarcity:The intersection of clinical nutrition science and health economics expertise remains thinly staffed across mid-tier manufacturers.
- ISO 22000 certification bottlenecks:Third-party audit capacity constraints are extending food safety management system validation timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complete Nutrition Products Market |
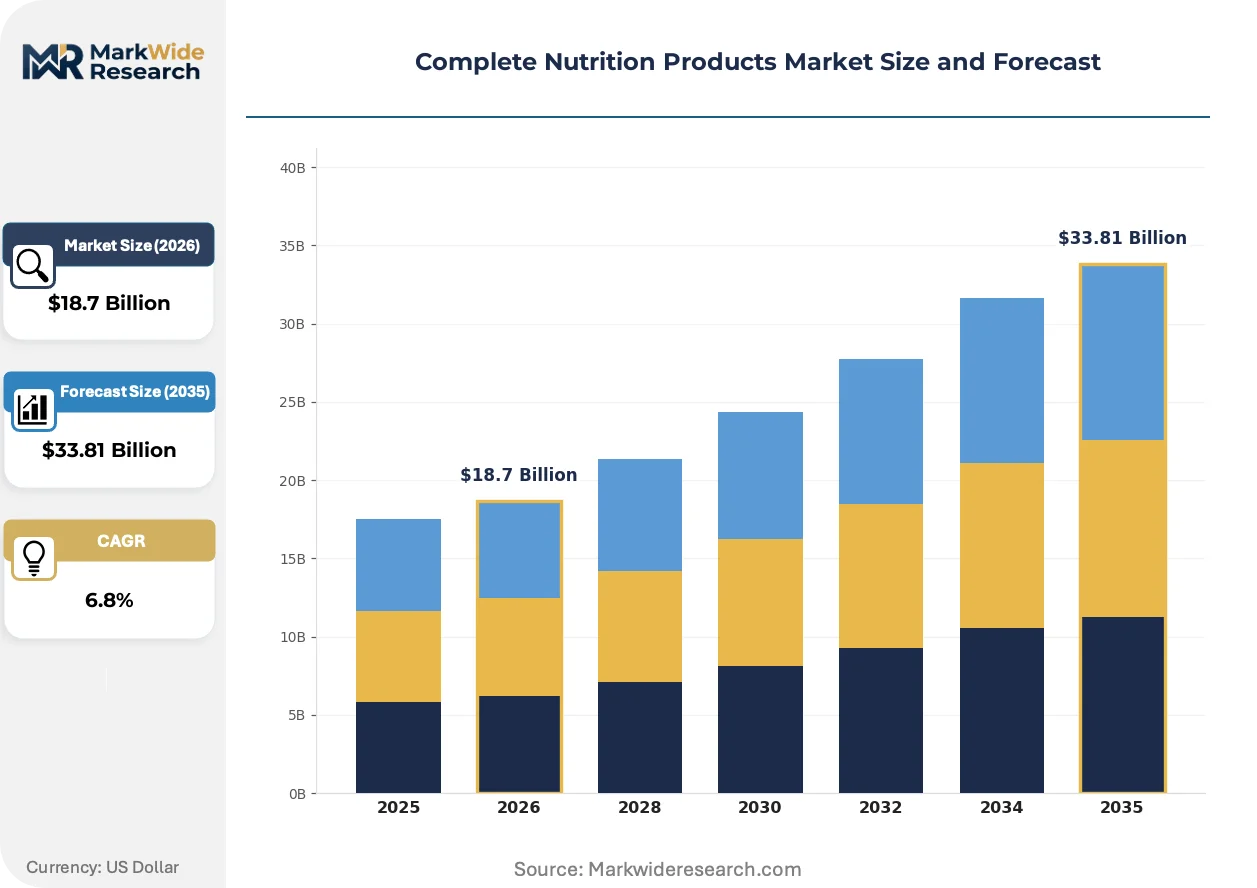
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Meal Replacements, Nutritional Bars, Fortified Beverages Ingredient: Whey, Casein, Soy, Pea Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies Customer Type: Fitness Enthusiasts, Athletes, Weight Loss Seekers, General Consumers |
| Companies Covered | Danone S.A., Abbott Laboratories, Nestlé S.A., Amway Corporation, Herbalife Nutrition Ltd., Huel Limited, Soylent, SlimFast, MuscleBlaze, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complete Nutrition Products Market Strategic Shifts & Innovations
Formulation science and distribution architecture are diverging along clinical-versus-consumer lines, with separate R&D investments and channel strategies now required to serve each pathway profitably.
Spray-drying technology is bifurcating between high-temperature throughput systems serving commodity protein powders and low-temperature vacuum processes preserving heat-sensitive bioactives for medical-grade applications. Hospital formulary committees are prioritizing the latter for immunonutrition protocols. This technical split is compressing mid-tier manufacturers unable to fund dual production lines.
REACH authorization requirements for novel protein hydrolysates are extending European launch timelines and forcing reformulation around established ingredient suppliers. The industrial consequence is a two-tier supply base: incumbents with grandfathered substances versus challengers awaiting toxicology dossier approval. Pediatric complete nutrition products face the tightest constraints, as EFSA demands stricter allergenicity data for vulnerable populations.
Direct-to-patient subscription models are displacing traditional durable medical equipment distributor relationships for home-based chronic disease management. Hospital discharge planners are piloting these channels for congestive heart failure and COPD populations in Germany and the United States. This channel shift concentrates fulfillment risk with manufacturers previously shielded by distributor inventory buffers.
Complete Nutrition Products Market Segmentation
Channel access determines margin capture in complete nutrition products. Hospital formulary committees, pharmacy benefit managers, and direct-to-consumer platforms each demand distinct formulation specifications and evidence packages. Segmentation strategy must align product architecture with these divergent procurement pathways.
Product Type:
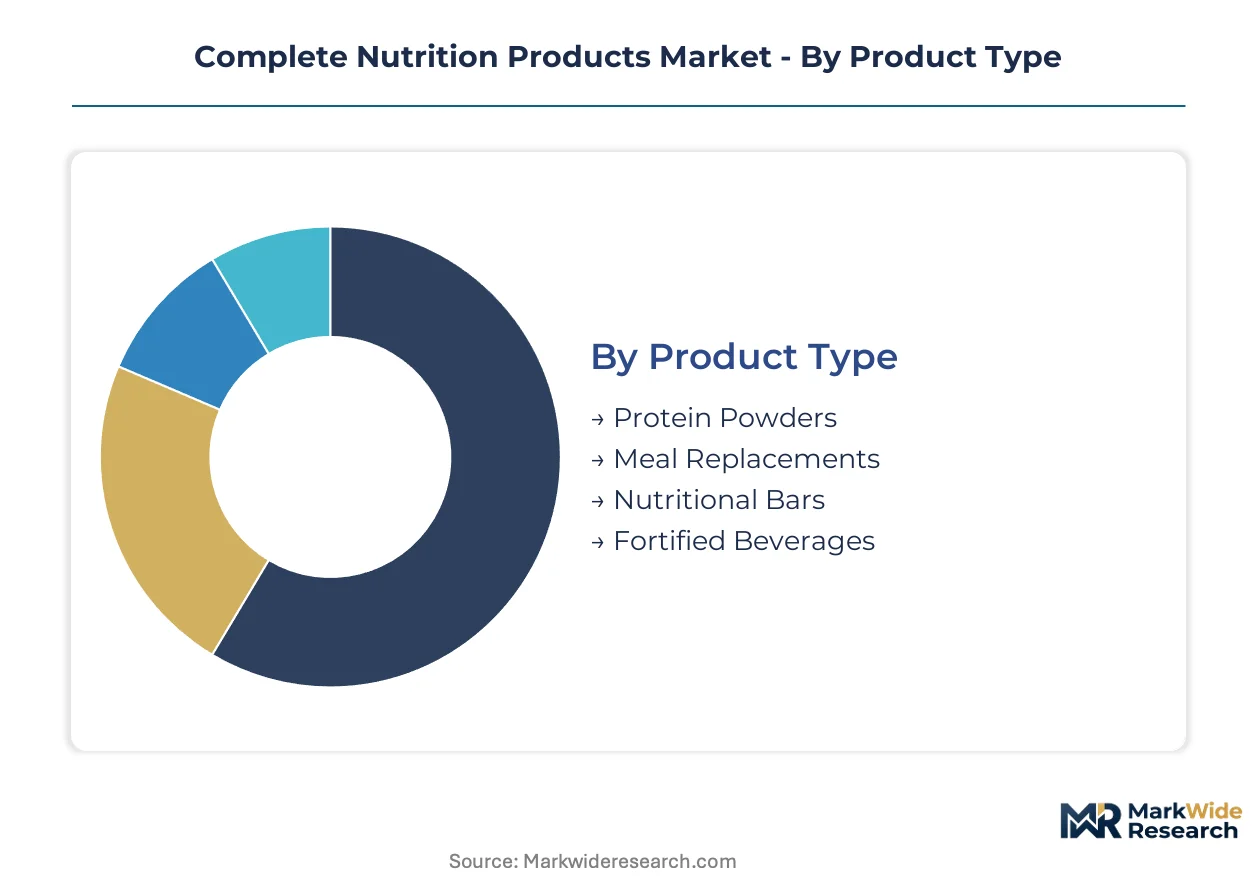
Channel-mix variation separates commodity gym-floor sales from institutional procurement. Protein powders flow predominantly through mass retail and e-commerce, while meal replacements penetrate healthcare channels requiring clinical substantiation.
- Protein Powders:Spray-dried or instantized concentrates and isolates formulated for solubility in water or milk. Demand concentrates in United States gym chains and German fitness retail, where whey-derived variants face margin pressure from dairy commodity volatility.
- Meal Replacements:Complete macro- and micronutrient systems manufactured via low-temperature processing to preserve bioactive compounds. United States hospital bundled payment models for bariatric and oncology recovery are accelerating formulary adoption fastest.
- Nutritional Bars:Extruded or cold-pressed formats combining protein with carbohydrate matrices for shelf-stable portability.
- Fortified Beverages:Ready-to-drink liquid nutrition with emulsified lipid and protein suspensions.
Protein powders dominate installed base. Meal replacements are where expansion concentrates.
Ingredient:
Cost tier and allergen profile shape procurement decisions across customer segments. Premium formulations command price multiples through clinical-grade certification, while commodity tiers compete on extraction efficiency.
- Whey:Dairy-derived complete protein with high leucine content and rapid absorption kinetics. Sports nutrition channels in Germany and United States sustain volume concentration, though manufacturers without backward integration into milk processing face margin compression from commodity swings.
- Pea:Legume-sourced isolate processed via aqueous fractionation to achieve neutral flavor and reduced allergen load. China's SAMR formula registration requirements are filtering demand toward suppliers with hospital trial data.
- Casein:Slow-digesting milk protein for sustained amino acid release.
- Soy:Plant-based complete protein with established GRAS status.
Whey anchors current formulation share. Pea is climbing the fastest.
Distribution Channel:
Customer acquisition economics diverge sharply between high-touch institutional selling and scalable digital fulfillment. Channel selection locks in margin structure and evidence requirements.
- Online Retail:Direct-to-consumer and marketplace platforms with subscription mechanics for chronic disease management. United States home health monitoring convergence is opening diabetes protocol subscriptions.
- Pharmacies:Professional counseling environments with reimbursement code access. Germany's Diätverordnung reform could expand adult complete nutrition access beyond pediatric-focused codes.
- Supermarkets:Mass-market shelf placement for commodity protein and convenience formats.
- Health Food Stores:Specialty retail with clean-label curation and practitioner referral networks.
Pharmacies dominate reimbursement-accessible volume. Online retail is gaining share fastest.
Customer Type:
Application context dictates formulation specification, from performance optimization to clinical intervention. Each segment presents distinct evidence requirements and price elasticity profiles.
- Fitness Enthusiasts:Recreational consumers prioritizing taste, mixability, and brand signaling. Volume concentrates in United States and China urban centers with high gym penetration.
- Weight Loss Seekers:Consumers pursuing calorie-controlled nutrition with satiety engineering. United States Medicare Advantage reimbursement expansion is compressing distribution margins while accelerating volume concentration.
- Athletes:Performance-focused users with batch-testing and certification requirements.
- General Consumers:Maintenance-oriented buyers seeking convenience and nutritional insurance.
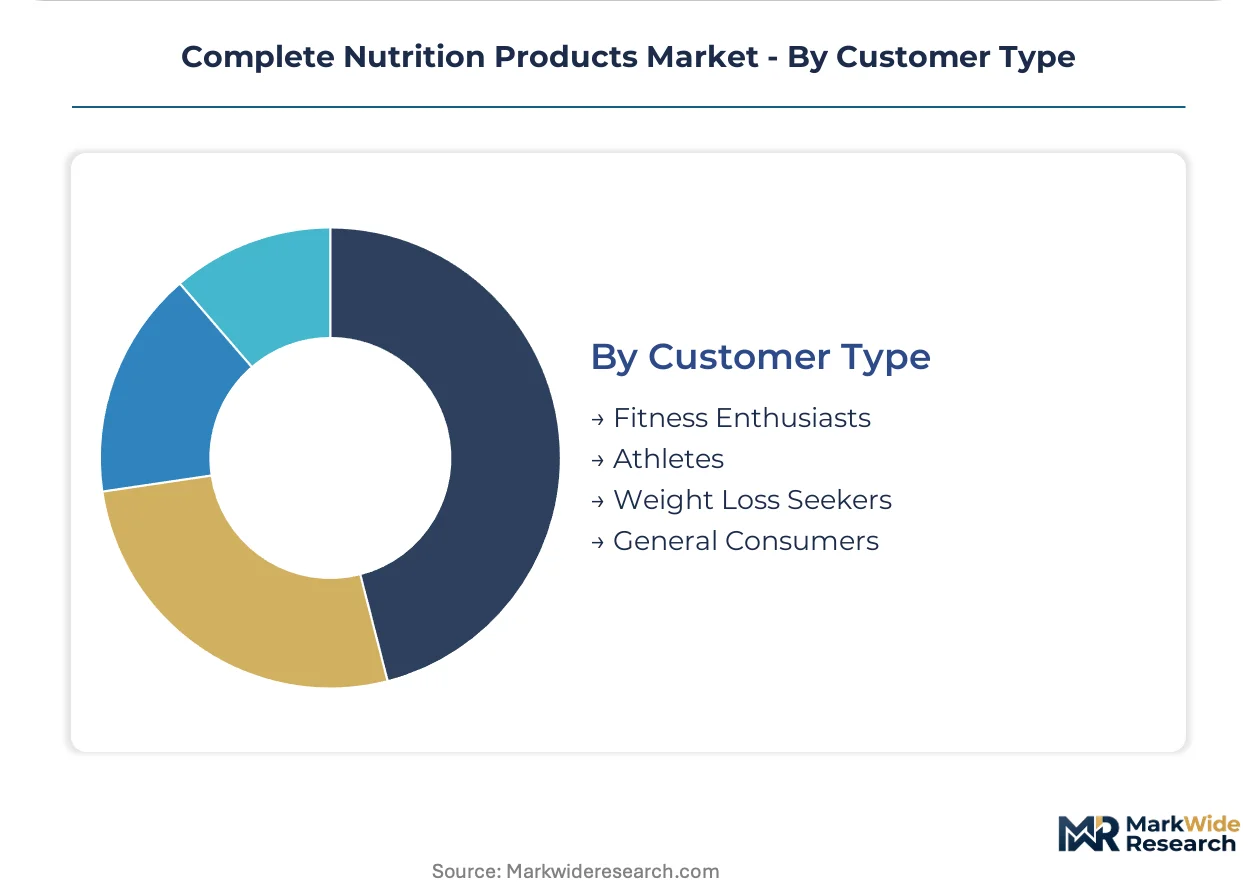
Fitness enthusiasts dominate current consumption base. Weight loss seekers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geriatric consumers seeking clinical-grade meal replacements cluster in reimbursement-rich markets. Hospital procurement consolidation and Medicare Advantage expansion in mature economies are compressing margins while accelerating volume concentration among formulary-approved suppliers.
United States
Post-surgical recovery protocols and bundled payment models for bariatric and oncology procedures drive institutional demand. The FDA governs medical food labeling under Orphan Drug Act provisions. Hospital discharge planners in Texas and Florida are piloting direct-to-patient subscription channels for congestive heart failure populations.
Germany
Proposed Diätverordnung reforms could expand pharmacy channel access for adult complete nutrition beyond pediatric-focused reimbursement codes. EMA Novel Food authorizations enforce 18-24 month assessment windows for emerging protein sources. The Rhine-Ruhr industrial corridor hosts spray-drying facilities serving medical-grade production lines.
China
SAMR formula registration requirements are filtering out low-substantiation competitors and elevating clinical-grade suppliers with hospital trial data. The regulator mandates clinical substantiation for domestically marketed complete nutrition products. Yangtze River Delta manufacturing clusters are scaling aqueous fractionation capacity for pea protein isolates.
Japan
Aging demographics and home-care infrastructure expansion sustain demand for prescribed meal replacements. METI oversees functional food claims and manufacturing standards. Kanto region pharmaceutical distributors are integrating continuous glucose monitoring with personalized nutrition delivery for diabetes protocols.
Australia
Private health insurance coverage for medical nutrition products supports premium formulation uptake. The TGA regulates therapeutic goods including complete nutrition for clinical indications. Sydney and Melbourne hospital networks are consolidating procurement around suppliers with ISO 22000 certification and direct-to-patient fulfillment infrastructure.
Complete Nutrition Products Market Key Industry Players
Player mix skews toward multinational nutrition conglomerates with medical affairs infrastructure and mid-tier specialists pursuing clean-label differentiation. Market structure concentrates around three to five integrated suppliers controlling hospital formulary access. Strategic archetypes include clinical evidence generators, commodity protein processors, and direct-to-consumer subscription operators. Competitive moves center on backward integration into milk processing and capacity expansion in aqueous fractionation for plant-protein isolates.
Among European and North American nutrition conglomerates, Danone S.A., Abbott Laboratories, and Nestlé S.A. occupy positions spanning dairy-derived and plant-based complete nutrition formats. These firms exemplify the clinical evidence generator archetype through hospital and home-care channel control. Their extensive pediatric and adult medical nutrition R&D infrastructure across multiple continents anchors formulary positioning in reimbursement-accessible markets. Mid-tier challengers represent the clean-label specialist vector, competing on allergen-free formulations and subscription-based fulfillment models.
| Leading Market Players |
|---|
| Danone S.A. |
| Abbott Laboratories |
| Nestlé S.A. |
| Amway Corporation |
| Herbalife Nutrition Ltd. |
| Huel Limited |
| Soylent |
| SlimFast |
| MuscleBlaze |
| Others |
Cost & Logistics Intelligence
Pea protein isolate substitution for whey concentrates is redrawing procurement geography toward Yangtze River Delta fractionation facilities while compressing premium tier pricing power as allergen-free formulations achieve clinical-grade certification parity.
Pricing Analysis
Cost-plus contracts with dairy commodity indexation anchor whey-derived product pricing, exposing manufacturers without backward integration into milk processing to margin compression during feed cost spikes. Three-tier pricing structure across premium clinical-grade, standard medical food, and economy sports nutrition levels separates buyers by certification intensity and reimbursement code access. Pricing pressure stems from hospital procurement consolidation favoring formulary-approved suppliers with direct-to-patient fulfillment infrastructure. Weight loss seekers accessing Medicare Advantage reimbursement demonstrate highest price sensitivity, while post-surgical protocol buyers exhibit lowest elasticity due to bundled payment model integration.
Supply Chain Analysis
China and Germany anchor spray-drying capacity for medical-grade production lines, with the Rhine-Ruhr corridor hosting low-temperature vacuum systems and the Yangtze Delta scaling aqueous fractionation for pea protein isolates. Raw material flows draw from dairy cooperatives in Wisconsin and Bavaria, legume processors in Manitoba, and lipid emulsion suppliers in the Netherlands. Single-source vulnerability concentrates in novel protein hydrolysate suppliers awaiting EMA REACH authorization. Distribution runs through hospital formulary committees, pharmacy benefit managers, and direct-to-patient subscription platforms with divergent evidence requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Complete nutrition products trace a cyclical recovery pattern as hospital discharge volumes rebound from pandemic-depressed baselines and Medicare Advantage reimbursement expansion unlocks institutional channel access.
For Market Incumbents: Consolidate formulary positioning through backward integration into milk processing and capacity expansion in aqueous fractionation for plant-protein isolates. Defend against mid-tier clean-label specialists by accelerating ISO 22000 certification timelines and deepening clinical evidence generation for immunonutrition protocols. Hospital procurement consolidation represents the primary threat to distributor-dependent margin structures. For New Entrants and Emerging Players: Lead with Southeast Asia hospital buildouts in Vietnam and Indonesia where greenfield medical infrastructure lacks entrenched supplier relationships. Target pharmacy channel access in Germany pending Diätverordnung reform for adult reimbursement codes. Deploy direct-to-patient subscription models with continuous glucose monitoring integration for diabetes management protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clinical evidence generators possessing hospital trial data but lacking direct-to-patient fulfillment infrastructure. Long-term viability centers on formulary-approved suppliers with integrated manufacturing and distribution across reimbursement-accessible markets. Monitor SAMR formula registration approval timelines as inflection indicator for China market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Processing | Captive whey supply insulates Abbott and Nestlé from dairy commodity volatility. |
| Aqueous Fractionation Capacity Expansion | Yangtze Delta pea protein scale enables allergen-free clinical-grade formulation at cost parity. |
| Direct-to-Patient Subscription Launch | Texas and Florida hospital discharge pilots bypass distributor margin compression for CHF populations. |
| ISO 22000 Certification Acceleration | Third-party audit prioritization compresses validation timelines for formulary committee access. |
| Clinical Evidence Generation Investment | Hospital trial data satisfies SAMR registration requirements and EFSA pediatric allergenicity standards. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, formulary directors, clinical nutrition specialists, and medical affairs executives; and secondary validation through FDA medical food registrations, EMA Novel Food authorization databases, SAMR formula filings, and CMS Medicare Advantage reimbursement code updates. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Forecast boundaries span the analysis window with segmentation across product type, ingredient source, distribution channel, and customer application context. CAGRs derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific inputs incorporated hospital discharge rate patterns, protein extraction yield curves, and reimbursement code expansion schedules.
Forecasts assume regulatory continuity in FDA Orphan Drug Act provisions, EMA Novel Food timelines, and SAMR formula registration requirements; material policy shifts would require re-modeling. Specific risks include dairy commodity volatility, REACH authorization delays for novel hydrolysates, and enteral nutrition substitution capturing restricted reimbursement codes. Recalibration cycles align with material shifts in hospital procurement consolidation and Medicare Advantage expansion trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Maternity Vitamins and Supplements Market
Nutritional Supplements
Royal Jelly Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Calcium Malate Market