
 Gum Lift Market | 2026-2036
Gum Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Lift Market Intelligence
CE marking under the EU Medical Device Regulation is consolidating compliance costs for gum lift device manufacturers entering European clinical markets. Straumann Holding AG leverages its implantology heritage to anchor premium positioning across periodontal aesthetics portfolios. Dentsply Sirona sustains broad channel control through integrated CAD/CAM and soft-tissue management workflows. Zimmer Biomet Holdings competes on manufacturing scale, extending its orthopedic biomaterials expertise into dental regenerative applications.
A gum lift comprises periodontal plastic surgery procedures that reshape gingival tissue to expose more tooth structure, typically performed with diode lasers, electrosurgical units, or microsurgical blades at tissue depths of 0.5–2.0 mm to achieve biologic width preservation and aesthetic contouring. Crown lengthening dominates procedure volume as the foundational indication, while laser surgery captures the fastest-growing technique segment due to reduced postoperative morbidity and chair-time compression. Soft tissue fillers command concentrated margin pools within materials, driven by cross-linked collagen and hyaluronic acid formulations that command premium pricing in cosmetic periodontal applications.
FDA 510(k) clearance pathways govern laser and electrosurgical devices in the United States, while the EU MDR and CE marking impose strengthened clinical evidence requirements for soft-tissue modification equipment. The EU AI Act introduces emerging scrutiny for algorithm-assisted surgical planning tools entering periodontal workflows. Stakeholders must monitor evolving biocompatibility standards for resorbable membranes and synthetic graft matrices as regulatory convergence between medical device and pharmaceutical frameworks accelerates compliance complexity.
Market Dynamics
Diode laser protocols are compressing chair-time and recovery windows, forcing electrosurgical and scalpel-based workflows into defensive repositioning across periodontal aesthetics practices.
Growth Catalysts
- EU MDR CE marking pathways:Strengthened clinical evidence requirements for soft-tissue modification equipment are filtering marginal device manufacturers, concentrating procurement among validated suppliers with robust technical documentation.
- Millennial aesthetic demand:Elective smile enhancement procedures among 25-40 year-old demographics are expanding addressable patient pools beyond traditional periodontal therapeutic indications.
- Cross-linked hyaluronic acid formulations:Soft tissue fillers with extended residence times are commanding premium pricing in cosmetic gingival contouring applications.
Market Restraints
- Biologic width preservation complexity:Tissue depths of 0.5–2.0 mm require precise surgical execution; violations trigger recession, bone loss, and litigation exposure.
- Diode laser capital intensity:Equipment procurement and maintenance contracts strain solo practitioner cash flows, favoring multi-chair group practices with centralized technology investment.
- Reimbursement asymmetry:FDA-cleared laser devices face elective procedure classification in US commercial insurance frameworks, limiting patient access financing.
Strategic Opportunities
- Algorithm-assisted surgical planning:EU AI Act scrutiny is creating first-mover advantage for periodontal software developers with pre-certified clinical decision support modules.
- Resorbable membrane convergence:Synthetic graft matrices and collagen barriers are opening regenerative-cosmetic hybrid procedures previously segmented between periodontal and implantology specialists.
- Teledentistry triage channels:Remote gingival assessment protocols are expanding initial patient touchpoints, compressing specialist referral funnels.
Industry Challenges
- Soft-tissue engineering skill scarcity:Microsurgical blade proficiency and laser parameter optimization require extended fellowship training; workforce pipeline lags demand expansion.
- ISO 13485 quality system timelines:Device manufacturers face 18-24 month certification cycles for biocompatibility validation of novel graft materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Lift Market |
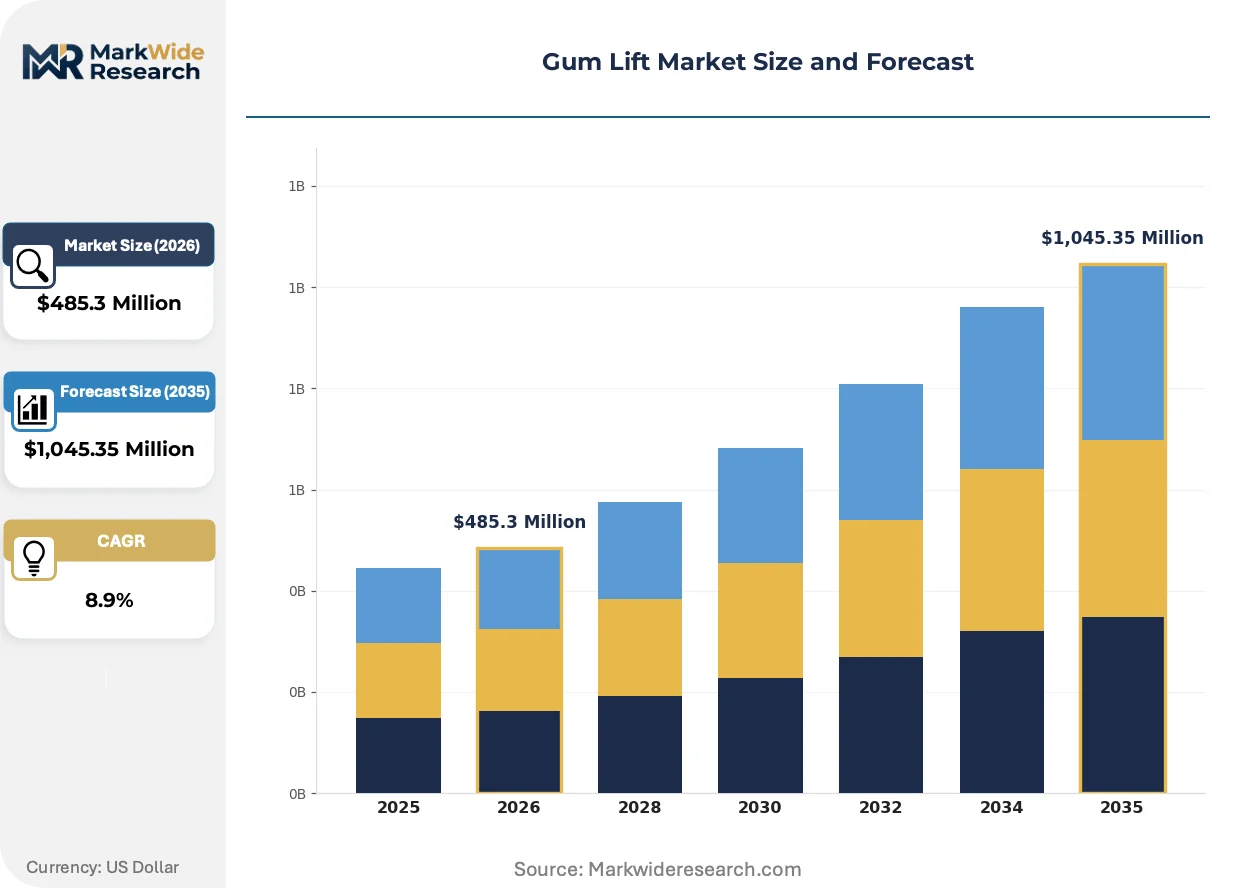
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,045.35 Million |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Crown Lengthening, Gingivoplasty, Gingival Grafting, Socket Preservation Technique: Laser Surgery, Electrosurgery, Traditional Surgery, Micro-Tissue Engineering End User: Dental Clinics, Cosmetic Surgeons, Hospitals, Orthodontic Practices Material: Bone Grafts, Soft Tissue Fillers, Sutures, Membranes |
| Companies Covered | Straumann Holding AG, Dentsply Sirona, Zimmer Biomet Holdings, Colgate-Palmolive Company, Den-Mat Holdings, Dental Arche, Advanced Cosmetic and Implant Dentistry, CENTER for Advanced Periodontal & Implant Therapy, Dental Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Lift Market Strategic Shifts & Innovations
Periodontal aesthetics is bifurcating between precision laser workflows and regenerative tissue engineering, with regulatory convergence between device and pharmaceutical frameworks accelerating compliance investment thresholds.
Diode laser systems with integrated real-time tissue feedback are modularizing surgical protocol standardization across dental group practices. Multi-site operators in Texas and Florida are deploying uniform laser parameter libraries, compressing training variance and enabling centralized procurement. This standardization is modularizing equipment vendor relationships into platform-ecosystem configurations rather than discrete device transactions.
EU MDR clinical evidence requirements for soft-tissue modification equipment are extending pre-market authorization timelines for electrosurgical unit manufacturers. Class IIa device reclassifications demand expanded biocompatibility testing and post-market surveillance infrastructure. Straumann and Dentsply Sirona subsidiaries with existing MDR technical file competencies are absorbing compliance costs more efficiently than mid-tier competitors.
Millennial patients are prioritizing same-day consultation-to-treatment completion, compressing traditional multi-visit periodontal plastic surgery pathways. Cosmetic-focused practices in California and New York are unbundling diagnostic imaging from surgical scheduling, converting radiography suites into revenue centers. This consumption-pattern shift is forcing conventional periodontal referral networks to adopt direct-to-consumer marketing or cede volume to retail dental chains.
Gum Lift Market Segmentation
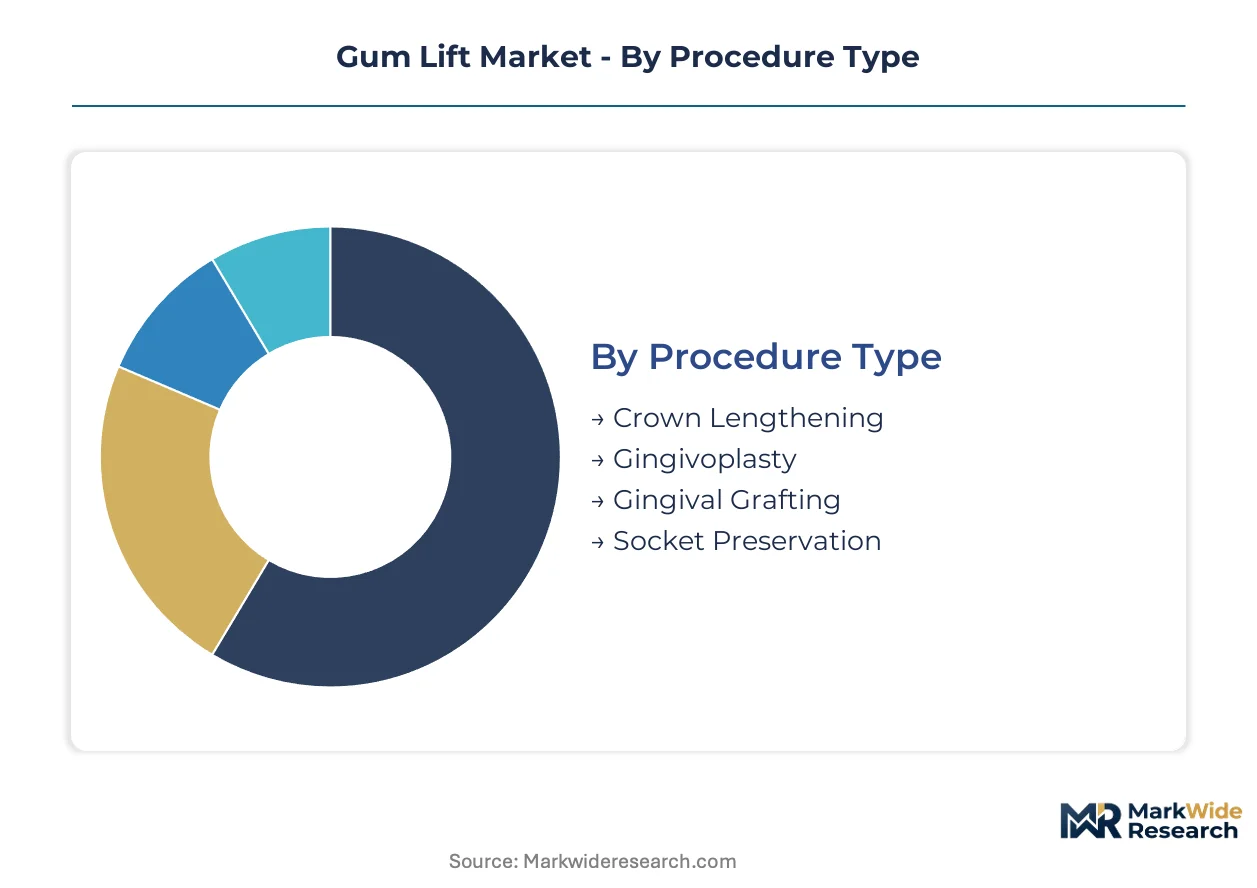
Gum lift segmentation reveals distinct clinical workflows where procedure complexity, technique invasiveness, and material biocompatibility requirements determine purchasing patterns. Each category reflects divergent margin structures and regulatory exposure that shape vendor positioning across periodontal aesthetics.
Procedure Type:
Customization intensity varies from standardized crown lengthening protocols to highly individualized grafting reconstructions requiring case-by-case surgical planning.
- Crown Lengthening:Foundation procedure exposing additional tooth structure through gingival resection and selective osseous reduction. Demand concentrates in California and Florida cosmetic practices where same-day smile transformation drives patient acquisition.
- Gingivoplasty:Contouring of gingival margins to correct asymmetry or gummy smile presentation. Elective aesthetic demand from millennial demographics in New York and Texas metropolitan corridors propels volume expansion.
- Gingival Grafting:Connective tissue or free graft harvest for recession coverage and root protection.
- Socket Preservation:Post-extraction ridge maintenance procedures bridging periodontal and implantology workflows.
Most installed capacity flows through Crown Lengthening. Expansion is steepest in Gingivoplasty.
Technique:
Cost tier stratification separates capital-intensive laser platforms from lower-barrier electrosurgical and manual instrument alternatives.
- Laser Surgery:Diode laser protocols at 810-980 nm wavelengths enable bloodless tissue ablation with real-time thermal feedback. Group practices in Texas and Florida deploy standardized parameter libraries to compress training variance and enable centralized procurement.
- Electrosurgery:Radiofrequency current delivery for rapid tissue cutting and coagulation. Solo practitioners facing diode laser capital intensity retain electrosurgical workflows despite slower healing profiles.
- Traditional Surgery:Microsurgical blade and scalpel techniques requiring extended fellowship training.
- Micro-Tissue Engineering:Soft-tissue manipulation integrating resorbable matrices and growth factor delivery.
Revenue concentration sits with Laser Surgery. Volume expansion is climbing the fastest in Micro-Tissue Engineering.
End User:
Customer type fragmentation spans independent operators, multi-site dental service organizations, and hospital-based surgical centers with divergent technology procurement authority.
- Dental Clinics:General and periodontal practices performing elective aesthetic procedures. Cosmetic-focused operators in California unbundle diagnostic imaging from surgical scheduling, converting radiography suites into revenue centers.
- Cosmetic Surgeons:Facial aesthetic specialists integrating gingival contouring into comprehensive smile design protocols.
- Hospitals:Academic medical centers managing complex reconstructive cases with interdisciplinary coordination.
- Orthodontic Practices:Alignment specialists addressing gingival asymmetry before or following bracket therapy.
Procedure volume concentrates in Dental Clinics. Patient acquisition investment is expanding most quickly in Orthodontic Practices.
Material:
Margin tier differentiation separates premium biologics from commodity sutures and synthetic barriers with compressed pricing power.
- Soft Tissue Fillers:Cross-linked collagen and hyaluronic acid formulations with extended residence times. Premium pricing in cosmetic gingival contouring applications drives concentrated margin pools.
- Bone Grafts:Xenograft, allograft, and synthetic matrices for osseous regeneration. FDA 510(k) clearance pathways and biocompatibility validation requirements govern supplier qualification.
- Sutures:Resorbable and non-resorbable wound closure materials with established commoditization pressure.
- Membranes:Collagen and synthetic barriers for guided tissue regeneration procedures.
Procurement spend concentrates in Soft Tissue Fillers. Regulatory filing activity is gaining share fastest in Bone Grafts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Periodontal plastic surgery originated in Swiss and German university clinics during the 1980s, establishing the biologic width protocols that now govern aesthetic gingival contouring standards worldwide.
United States
Elective smile enhancement demand from millennials in California and New York metropolitan corridors drives procedure volume expansion. FDA 510(k) clearance pathways govern laser and electrosurgical device commercialization, with recent guidance tightening biocompatibility documentation requirements. Dallas-Fort Worth dental service organizations deploy standardized diode laser parameter libraries across multi-chair practices, compressing training variance and enabling centralized procurement at scale.
Germany
Academic medical centers in Baden-Württemberg and Bavaria anchor regenerative periodontal research pipelines, with university hospitals integrating soft-tissue engineering into interdisciplinary reconstructive protocols. EU MDR CE marking requirements filter marginal device manufacturers from European clinical markets, concentrating procurement among validated suppliers. Frankfurt's dental technology cluster hosts specialized biocompatibility testing laboratories serving mid-tier manufacturers facing extended technical file preparation timelines.
Switzerland
Implantology heritage from Basel and Zurich research institutions positions domestic manufacturers at premium price tiers across periodontal aesthetics portfolios. Swissmedic maintains alignment with EU MDR standards while preserving streamlined market access for Class IIa soft-tissue modification devices. The Lake Geneva corridor concentrates headquarters operations for firms leveraging biomaterials expertise from adjacent pharmaceutical and orthopedic device industries.
Japan
Metropolitan Tokyo and Osaka periodontal specialists emphasize minimally invasive laser protocols, with PMDA marketing authorization pathways requiring extended clinical evidence packages for novel tissue engineering materials. Aging demographic profiles expand therapeutic indications beyond cosmetic applications into functional recession coverage procedures. Yokohama dental equipment distributors maintain exclusive relationships with domestic manufacturers, limiting penetration of European and North American laser platform vendors.
Brazil
São Paulo's cosmetic dentistry market absorbs premium-priced soft tissue fillers and resorbable membranes despite reimbursement limitations on elective procedures. ANVISA registration pathways for imported dental devices impose extended lead times, favoring local distributors with established regulatory affairs capabilities. Rio de Janeiro aesthetic dental chains unbundle diagnostic imaging from surgical scheduling, converting radiography suites into standalone revenue centers targeting upper-middle-class patient segments.
Gum Lift Market Key Industry Players
The competitive structure tilts toward integrated dental technology conglomerates with cross-portfolio bundling power. Device manufacturers with implantology heritage anchor premium positioning across periodontal aesthetics, while standalone laser equipment vendors compete on capital intensity and service contract flexibility. Three archetypes dominate: full-spectrum dental technology platforms, specialized periodontal device manufacturers, and regional dental service organizations with captive procurement authority. Competitive moves concentrate on M&A absorption of soft-tissue engineering startups and strategic partnerships between equipment vendors and dental group practices seeking standardized protocol deployment.
Within the premium-tier vector, Straumann Holding AG occupies a position exemplifying implantology-to-aesthetics portfolio extension, while Dentsply Sirona represents integrated CAD/CAM and soft-tissue workflow control. Zimmer Biomet Holdings anchors the orthopedic-biomaterials crossover archetype, extending manufacturing scale into dental regenerative applications. These three firms collectively illustrate how heritage in adjacent dental or medical device categories shapes competitive positioning in periodontal aesthetics procurement channels.
| Leading Market Players |
|---|
| Straumann Holding AG |
| Dentsply Sirona |
| Zimmer Biomet Holdings |
| Colgate-Palmolive Company |
| Den-Mat Holdings |
| Dental Arche |
| Advanced Cosmetic and Implant Dentistry |
| CENTER for Advanced Periodontal & Implant Therapy |
| Dental Solutions |
| Others |
Cost & Logistics Intelligence
Collagen raw material indices from bovine and porcine sources cascade through three distinct pricing tiers in periodontal aesthetics, with cross-linked hyaluronic acid formulations commanding premium positioning while electrosurgical consumables face commoditization pressure from generic entrants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs gum lift materials and devices. Price differentiation rests on FDA 510(k) clearance tier and biocompatibility certification grade, with MDR-compliant European suppliers extracting brand premiums from risk-averse procurement committees. Cost compression in diode laser maintenance contracts is intensifying because multi-chair dental service organizations centralize vendor negotiations. Solo practitioners in Texas and Florida exhibit highest price sensitivity, while hospital-based surgical centers absorb premium positioning for regenerative matrices.
Supply Chain Analysis
Single-source vulnerability sits with Swiss collagen processors and German electrosurgical component foundries. Manufacturing gravity centers on Switzerland, Germany, and the United States for precision laser platforms, while South Korean diode arrays and Japanese optical sensors feed into upstream assembly. Supply chain risk manifests as EU MDR technical file bottlenecks extending lead times for novel graft materials. Distribution runs through specialized dental distributors in North America and direct hospital contracts in European academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gum lift market functions as a regulatory compounder where EU MDR CE marking pathways filter marginal competitors and concentrate procurement among validated suppliers with robust clinical evidence packages.
For Market Incumbents: Lock in group practice procurement relationships through standardized laser parameter libraries and captive maintenance contracts. Consolidate soft-tissue engineering startups before MDR compliance costs escalate acquisition multiples. Absorb ISO 13485 certification timelines for resorbable membranes to preempt mid-tier competitors from closing biocompatibility gaps.
For New Entrants and Emerging Players: Teledentistry triage platforms offer the most penetrable entry vector for algorithm-assisted surgical planning tools. Target orthodontic practices in California and New York where gingival contouring demand outpaces specialist supply. Deploy direct-to-consumer marketing bypassing traditional periodontal referral networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act scrutiny creates first-mover advantage for pre-certified clinical decision support modules. Five-to-ten year viability favors firms with implantology heritage extending into periodontal aesthetics. Acquisition target archetype: mid-tier laser device manufacturers with MDR technical files but lacking channel scale. Watch FDA guidance tightening on biocompatibility documentation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Investment | CE marking pathways filter competitors and concentrate procurement among validated suppliers. |
| Diode Laser Platform Standardization | Multi-chair dental service organizations compress training variance through centralized parameter libraries. |
| Soft-Tissue Engineering Acquisition | Implantology heritage firms absorb startups to anchor premium positioning across periodontal portfolios. |
| Algorithm-Assisted Surgical Planning | EU AI Act scrutiny creates first-mover advantage for pre-certified clinical decision support modules. |
| Teledentistry Triage Channel Buildout | Remote gingival assessment protocols expand initial patient touchpoints and compress specialist referral funnels. |
Research Approach
Direct dialogue with periodontal specialists, dental service organization procurement directors, biomedical engineers, and GPO contracts managers anchored qualitative grounding. Secondary validation drew from FDA 510(k) filings, EU MDR technical file databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down equipment shipment data underwent cross-triangulation to resolve variance.
Segment-level outputs across procedure type, technique, end user, and material categories were generated over the projection horizon. CAGRs were derived from fitted growth curves incorporating millennial demographic penetration rates, laser adoption velocity in group practices, and regulatory filing activity timelines. Forecast inputs included diode laser installation base expansion, cross-linked filler formulation launches, and MDR transition completion rates.
EU AI Act enforcement timing, FDA biocompatibility guidance revisions, and collagen raw material supply disruptions are the dominant revision risks. Forecasts reflect assumptions about elective procedure demand elasticity and reimbursement framework stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market