
 South Korea Cloud OSS BSS Market | 2026-2036
South Korea Cloud OSS BSS Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Cloud OSS BSS Market Insights
Direct carrier-to-vendor procurement channels are being redrawn as multi-cloud orchestration is reshaping how South Korean telecoms acquire operations software. Amdocs leverages its longstanding presence in Asia-Pacific billing systems to sustain enterprise relationships across the peninsula. SK Telecom anchors domestic innovation through its proprietary cloud-native network functions developed in-house and with partners. Huawei Technologies competes aggressively on price-performance for core network management layers despite geopolitical headwinds.
Cloud OSS BSS denotes the integrated software layer governing service fulfillment, assurance, and billing for telecommunications providers, now architected on containerized microservices with API-first design patterns enabling real-time subscriber provisioning. The primary commercial purpose centers on replacing legacy on-premise stacks with elastic infrastructure that reduces capex cycles from years to months. Deployment model segmentation shows hybrid cloud configurations capturing the dominant share as operators balance latency-sensitive network functions against elastic analytics workloads, while solution type dynamics reveal revenue assurance modules outpacing billing in growth velocity due to 5G usage pattern complexity. Service tier differentiation increasingly stratifies around premium offerings with embedded AI-driven anomaly detection versus basic tiers for regional ISPs.
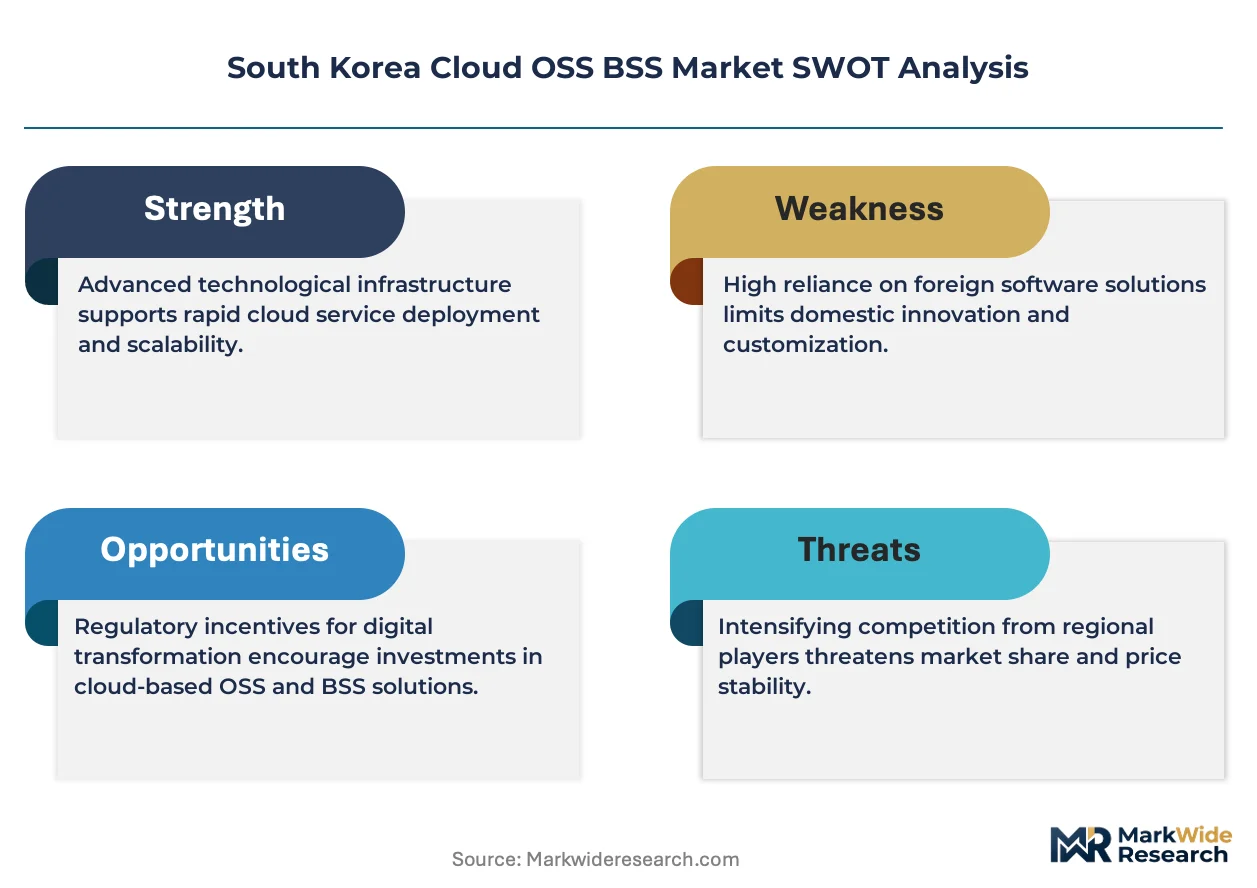
MFDS data localization guidelines intersect with KISA cybersecurity certification requirements to mandate sovereign cloud residency for subscriber records, effectively filtering foreign SaaS providers without domestic infrastructure. The Personal Information Protection Act enforcement by PIPC further tightens cross-border data governance, compelling vendors to establish Korean availability zones. Stakeholders must monitor how upcoming amendments to the Telecommunications Business Act reshape interoperability mandates between incumbent operators and MVNOs.
Market Dynamics
Mobile network operators across South Korea are accelerating cloud-native migration of their operations support systems under pressure from the K-Cloud Initiative and data sovereignty requirements under the Personal Information Protection Act. This regulatory-technology intersection is compressing procurement cycles and forcing vendors to establish domestic availability zones.
Growth Catalysts
- K-Cloud Initiative:The government's sovereign cloud mandate is channeling public and private telecom investment toward domestic-hosted solutions, creating guaranteed demand for local infrastructure providers.
- 5G network expansion:Complex usage patterns from massive IoT and ultra-reliable low-latency services are driving replacement of legacy billing stacks with real-time charging systems.
- Pangyo Techno Valley:Concentrated R&D activity in this Gyeonggi-do cluster is spawning specialized OSS BSS engineering talent and vendor development centers.
Market Restraints
- Input cost volatility:Specialized telco-grade server hardware and GPU acceleration for AI-driven analytics face supply concentration from Taiwan and US semiconductor fabricators.
- Geopolitical friction:Export control regimes on advanced cloud infrastructure components create procurement uncertainty for certain foreign vendor relationships.
- Technical debt accumulation:Decades-old COBOL and proprietary middleware in incumbent operator stacks resist containerization, delaying full cloud-native transitions.
Strategic Opportunities
- Busan-Ulsan corridor:Underpenetrated regional ISPs and industrial 5G private networks in Korea's southeast manufacturing belt represent greenfield deployment prospects.
- AI-embedded assurance:Convergence of machine learning anomaly detection with network operations is opening premium service tiers for enterprise SLA management.
- MVNO interoperability mandates:Upcoming Telecommunications Business Act amendments will force incumbent operators to expose standardized APIs, creating systems integration demand.
Industry Challenges
- Container orchestration expertise:Kubernetes and service mesh specialization remains scarce in Korea's traditional telecom engineering workforce, inflating implementation timelines.
- PIPC certification timelines:Personal Information Protection Commission audits for subscriber data handling in multi-tenant cloud environments extend vendor onboarding by quarters.
- Legacy integration complexity:API-first microservices must coexist with SS7 and Diameter protocol stacks, requiring costly protocol translation layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Cloud OSS BSS Market |
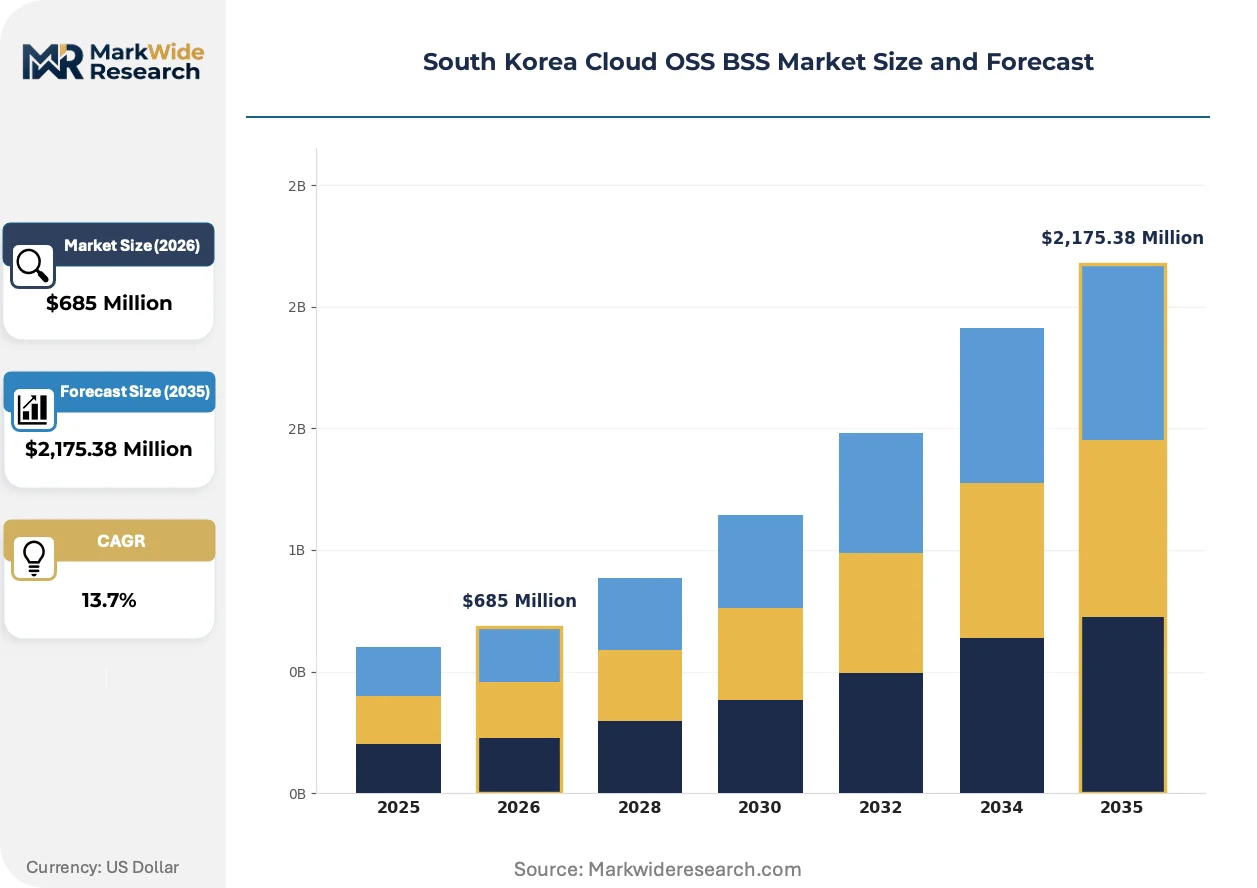
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $2,175.38 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Billing, Provisioning, Customer Management, Revenue Assurance Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Telecom Operators, Internet Service Providers, Managed Service Providers, Large Enterprises Service Tier: Basic, Advanced, Premium, Customized |
| Companies Covered | Amdocs, Huawei Technologies, SK Telecom, Nokia, Ericsson, KT Corporation, Oracle, Netcracker Technology, LG Uplus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Cloud OSS BSS Market Trends and Innovations
Cloud OSS BSS architecture is undergoing fundamental restructuring as Korean operators balance latency-sensitive network functions against elastic analytics workloads. Three convergent developments are compressing vendor selection criteria and reshaping procurement patterns.
Containerized microservices with API-first design patterns are hybridizing deployment topologies across South Korean telecoms. SK Telecom and KT are adopting Kubernetes-orchestrated network functions for non-real-time billing and assurance while retaining bare-metal edge nodes for subscriber authentication. This bifurcation is compressing vendor consolidation timelines as operators demand single-pane orchestration across both domains.
MFDS data localization guidelines intersecting with KISA cybersecurity certification requirements are mandating sovereign cloud residency for all subscriber records. The enforcement regime filters foreign SaaS providers lacking domestic infrastructure, compelling established vendors to establish Korean availability zones. Tier-2 regional ISPs face the steepest compliance burden as they lack capital for multi-region redundancy.
Carrier procurement patterns are pivoting from perpetual licenses toward consumption-based SaaS arrangements with embedded professional services. Mobile virtual network operators and enterprise private 5G deployers are bypassing traditional systems integrators to contract directly with cloud-native specialists. This disintermediation is most visible in Seoul's digital infrastructure cluster where Pangyo-based vendors maintain direct sales engineering presence.
South Korea Cloud OSS BSS Market Segmentation
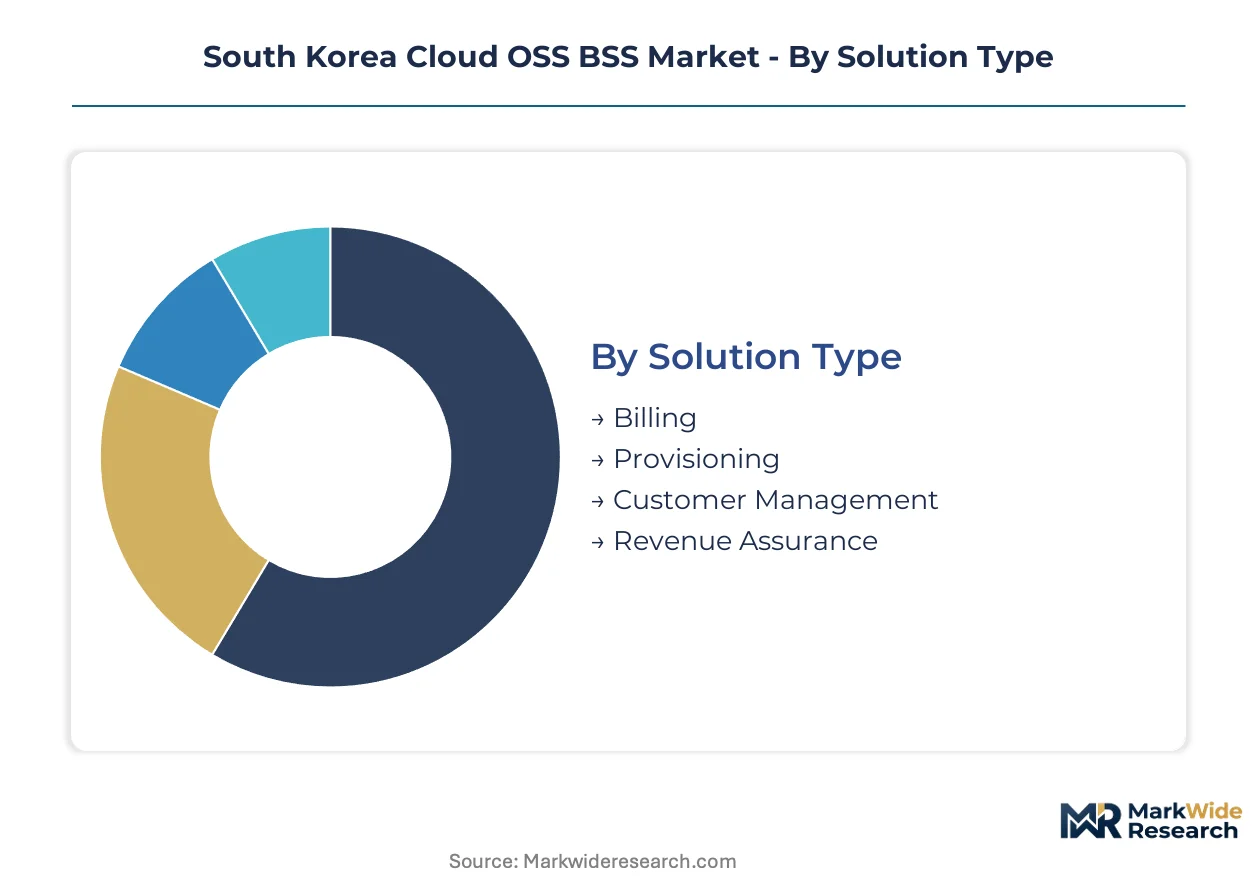
Cloud OSS BSS procurement patterns diverge sharply across solution types and deployment models. Korean operators segment their vendor selection by compliance posture, latency requirements, and integration complexity with legacy stacks.
Solution Type:
After-sales service intensity peaks in revenue assurance modules where real-time anomaly detection demands continuous algorithmic tuning. SK Telecom and KT prioritize vendors offering embedded Korean-language support engineering.
- Billing:Real-time charging engines process 5G usage events with millisecond latency requirements. Seoul-based mobile network operators dominate demand as they migrate from batch-oriented postpaid systems to convergent charging for IoT and enterprise slices.
- Revenue Assurance:AI-embedded modules detect usage pattern anomalies across complex 5G service bundles. Pangyo Techno Valley vendors concentrate development here due to premium pricing and recurring service attach rates.
- Provisioning:Automated subscriber lifecycle management with API-first orchestration.
- Customer Management:Unified subscriber profiles integrating CRM with network operations data.
Billing holds the largest share; momentum sits with revenue assurance.
Deployment Model:
Cost tier stratification separates capital-intensive private cloud builds from operational expenditure models. Regional ISPs in Busan-Ulsan corridor gravitate toward lower upfront commitments.
- Hybrid Cloud:Kubernetes-orchestrated microservices for billing coexist with bare-metal edge nodes for authentication. KT's deployment architecture exemplifies this bifurcation, balancing MFDS data localization mandates against elastic analytics scaling.
- Multi-Cloud:Workload portability across domestic and hyperscaler availability zones mitigates vendor lock-in. Large enterprises with private 5G networks demand this flexibility for disaster recovery compliance.
- Private Cloud:Sovereign infrastructure for subscriber records under PIPC enforcement.
- Public Cloud:Development and testing environments with consumption-based economics.
Hybrid cloud dominates current procurement; multi-cloud configurations are climbing the fastest.
End User:
Application requirements diverge between mass-market service providers and specialized industrial deployers. Each vertical imposes distinct latency, customization, and certification demands.
- Telecom Operators:SK Telecom and KT drive complexity with convergent charging for consumer, enterprise, and wholesale segments. Their procurement specifications mandate KISA-certified encryption and domestic availability zone residency.
- Large Enterprises:Manufacturing conglomerates in Gyeonggi-do deploy private 5G networks with embedded OSS BSS for quality-of-service enforcement. Hyundai Motor and Samsung Electronics anchor this demand with campus-scale deployments.
- Internet Service Providers:Regional fiber operators with simpler subscriber management needs.
- Managed Service Providers:Systems integrators serving MVNOs and niche verticals.
Telecom operators command the largest share; large enterprises are expanding most quickly.
Service Tier:
Margin structure separates commodity basic tiers from premium offerings with embedded professional services. Pricing power concentrates in customized implementations for complex multi-domain orchestration.
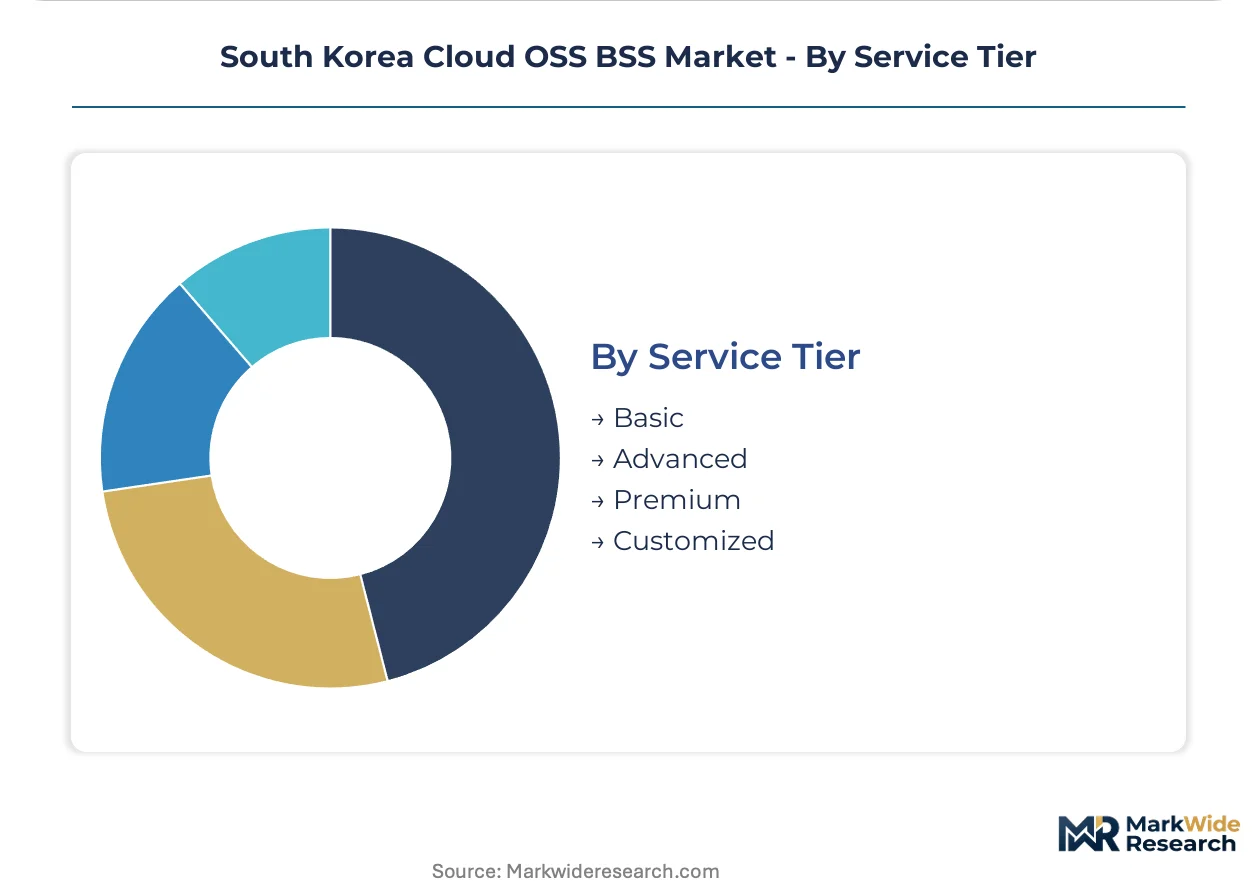
- Premium:AI-driven anomaly detection, dedicated Korean-speaking engineering support, and guaranteed response time SLAs. KT's enterprise private network deployments specify this tier for manufacturing quality assurance integration.
- Customized:Bespoke protocol adapters for legacy SS7 and Diameter coexistence with cloud-native microservices. Incumbent operators with decades of technical debt require extensive professional services attachment.
- Advanced:Pre-configured templates with limited customization and standard support.
- Basic:Standardized SaaS with self-service configuration for regional ISPs.
Premium tier captures highest margins; customized engagements are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Seoul's digital infrastructure cluster while Busan-Ulsan corridor operators absorb compliance premiums without scale efficiencies. This asymmetry shapes vendor deployment strategies and service tier stratification across South Korean sub-regions.
Seoul Capital Area
SK Telecom and KT drive convergent charging complexity for consumer, enterprise, and wholesale segments. MFDS data localization guidelines intersect with KISA cybersecurity certification requirements to mandate sovereign cloud residency for subscriber records. Pangyo Techno Valley anchors specialized OSS BSS engineering talent and vendor development centers with direct sales engineering presence.
Busan-Ulsan
Regional ISPs and industrial 5G private networks in Korea's southeast manufacturing belt represent greenfield deployment prospects. Hyundai Motor anchors campus-scale private network demand with embedded OSS BSS for quality-of-service enforcement. Technical debt accumulation in decades-old COBOL stacks resists containerization, delaying full cloud-native transitions.
Daegu-Gyeongbuk
Electronics manufacturing supply chains generate demand for industrial IoT connectivity management platforms. The region's textile and machinery sectors deploy private 5G networks with simplified subscriber lifecycle management needs. Container orchestration expertise scarcity inflates implementation timelines for Kubernetes and service mesh specialization.
Daejeon-Sejong
Government research institutes and public sector cloud migration create demand for K-Cloud Initiative compliant infrastructure. KISA cybersecurity certification requirements filter foreign SaaS providers without domestic availability zones. Public procurement specifications mandate hybrid cloud configurations balancing latency-sensitive functions against elastic analytics.
Gwangju-Honam
Agricultural technology and regional fiber operators concentrate demand for basic-tier standardized SaaS with self-service configuration. PIPC certification timelines for subscriber data handling extend vendor onboarding by quarters. Tier-2 regional ISPs face the steepest compliance burden as they lack capital for multi-region redundancy.
South Korea Cloud OSS BSS Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper protocol expertise. The vendor base separates into consolidated multinational platforms, domestic telecom-affiliated developers, and cloud-native specialists. Three archetypes dominate: legacy billing system modernizers, sovereign cloud infrastructure builders, and API-first microservices vendors. Competitive moves concentrate on establishing Korean availability zones and acquiring KISA certification credentials.
Within the domestic telecom-affiliated tier, SK Telecom anchors proprietary cloud-native network functions developed in-house and with partners. Amdocs occupies a position representing legacy billing system modernizers leveraging longstanding Asia-Pacific enterprise relationships. Huawei Technologies exemplifies the price-performance competitive vector for core network management layers despite procurement uncertainty from export control regimes.
| Leading Market Players |
|---|
| Amdocs |
| Huawei Technologies |
| SK Telecom |
| Nokia |
| Ericsson |
| KT Corporation |
| Oracle |
| Netcracker Technology |
| LG Uplus |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Kubernetes-certified engineering pools across the Seoul Capital Area compresses vendor deployment timelines while simultaneously inflating professional services premiums. This scarcity dynamic forces buyers toward longer contract lock-ins and accelerates supplier consolidation around established domestic infrastructure providers.
Pricing Analysis
The customization-premium spread separates configured-to-order private cloud deployments from standardized SaaS tiers across South Korean telecom procurement. Subscription-based SaaS arrangements with embedded professional services dominate as carriers pivot from perpetual licenses, with price differentiation anchored in KISA cybersecurity certification grade and domestic availability zone residency. Pricing pressure stems from MVNOs and regional ISPs demanding consumption-based economics without upfront capex commitment. Tier-2 regional operators in Gwangju-Honam exhibit highest price sensitivity, while SK Telecom and KT absorb premium tier costs for AI-embedded assurance modules.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers and supply-chain finance facilities from domestic semiconductor distributors shape working capital structures for OSS BSS vendors. Taiwan, the United States, and South Korea concentrate supply for telco-grade GPU acceleration hardware and specialized server components. Raw material dependencies center on advanced node semiconductors, high-bandwidth memory modules, and precision networking equipment. Single-source vulnerability from Taiwan semiconductor fabricators creates procurement uncertainty under export control regimes. Distribution runs through direct carrier-to-vendor channels in Seoul's Pangyo Techno Valley cluster, with systems integrator disintermediation accelerating for cloud-native specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's Cloud OSS BSS market sits in early-cycle expansion as 5G network slicing and private industrial networks drive replacement demand beyond traditional billing modernization. The K-Cloud Initiative guarantees sovereign infrastructure demand through the projection horizon.
For Market Incumbents: Harden domestic availability zone footprints against emerging cloud-native specialists by accelerating KISA certification acquisition and embedding Korean-language support engineering directly into revenue assurance modules. Threat from API-first microservices vendors disintermediating traditional systems integrators demands defensive consolidation through backward integration into container orchestration tooling. Priority lever rests on exclusive partnerships with Pangyo-based R&D talent pools. For New Entrants and Emerging Players: The Busan-Ulsan corridor offers underpenetrated greenfield prospects among regional ISPs and Hyundai Motor's campus-scale private 5G deployments. Manufacturing conglomerates in Gyeonggi-do present adjacent demand for quality-of-service embedded OSS BSS with simplified subscriber lifecycle management. Go-to-market angle should emphasize consumption-based SaaS economics without legacy integration burden, bypassing incumbent procurement committees through direct sales engineering presence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native specialists with embedded AI-driven anomaly detection and guaranteed SLA response times. Long-term viability over a multi-year horizon favors vendors with established Korean availability zones and PIPC audit completion rather than foreign SaaS providers facing data localization mandates. Acquisition target archetype: Pangyo-based engineering teams with Kubernetes specialization and existing KT or SK Telecom reference deployments. Signal to watch is amendment timing to the Telecommunications Business Act forcing incumbent API interoperability.| Strategic Initiative | Industry Significance |
|---|---|
| K-Cloud Availability Zone Establishment | MFDS data localization guidelines and PIPC enforcement mandate sovereign infrastructure residency for subscriber records. |
| AI-Embedded Assurance Module Development | SK Telecom and KT prioritize real-time anomaly detection for 5G usage pattern complexity in convergent charging. |
| Kubernetes Certification Pipeline Investment | Container orchestration expertise scarcity inflates implementation timelines across Korean telecom engineering workforce. |
| MVNO API Standardization Preparation | Upcoming Telecommunications Business Act amendments force incumbent operators to expose standardized integration interfaces. |
| Busan-Ulsan Direct Sales Expansion | Regional ISPs and industrial private networks in Korea's southeast manufacturing belt absorb compliance premiums without scale efficiencies. |
Research Methodology
Operator-level perspectives from network operations executives, cloud procurement officers, KISA certification auditors, and Pangyo-based vendor engineering leads anchored the qualitative base for this study. Primary interviews combined with secondary validation from MFDS regulatory filings, KISA cybersecurity certification databases, hyperscaler capex disclosures, and Telecommunications Business Act amendment drafts. Bottom-up deployment modeling across hybrid, multi-cloud, private, and public configurations triangulated against top-down market sizing from carrier procurement cycle analysis.
Scenario-bracketing around K-Cloud Initiative funding continuity, 5G private network adoption velocity, and export control regime stringency bounded the projection range. Segmentation dimensions modeled encompass solution type, deployment model, end user vertical, and service tier stratification across the analysis window. CAGRs derived from elasticity-adjusted replacement cycle timing and sovereign cloud infrastructure buildout schedules. Industry-specific inputs included containerization readiness assessments for legacy COBOL stacks and PIPC audit timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in semiconductor supply availability, won-dollar exchange volatility, or K-Cloud Initiative budget allocation would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and 5G network expansion pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Global Web Push Notification Software Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
AQI App Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Document Management System Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Social Networking App Market
Digital Solutions
Digital Manufacturing Market