
 Cybersecurity in Robotics Market | 2026-2036
Cybersecurity in Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Cybersecurity in Robotics Market Outlook
The global pool of robotics security engineers is collapsing faster than universities can produce replacements. Siemens leverages its industrial automation heritage to anchor European demand for factory-floor cyber-physical protection. Shield AI competes in defense robotics by sustaining classified-grade encryption on unmanned platforms.
Cybersecurity in robotics encompasses the hardware, firmware, and software safeguards that protect robotic systems from unauthorized access, data exfiltration, and operational sabotage across connected environments. These protections integrate intrusion detection thresholds below 50-millisecond response windows to prevent kinetic harm during autonomous operation. Endpoint security dominates product-type revenue as robot controllers and sensors constitute the most exposed attack surfaces. Network security grows fastest among technology layers because fleet-connected robots multiply lateral movement risks for threat actors. Industrial automation anchors end-user application spending, though drone operations now attract specialized vendor attention for beyond-visual-line-of-sight missions.
The EU AI Act, NIS2 Directive, and ISO/IEC 27001 framework collectively mandate conformity assessments for autonomous systems processing operational data in critical infrastructure. FDA cybersecurity guidance for medical robots and FAA unmanned aircraft rules in the United States add parallel compliance burdens for cross-border vendors. Stakeholders must monitor whether national regulators harmonize robot certification requirements or fragment them into incompatible technical barriers.
Market Dynamics
Ransomware attacks on manufacturing production lines have triggered mandatory firmware hardening requirements, compressing procurement cycles for cyber-physical protection systems and forcing vendors to pre-certify controllers before factory deployment.
Growth Catalysts
- EU AI Act Conformity Mandates:The European Union's risk-based classification system for autonomous systems compels robot manufacturers to embed intrusion detection below 50-millisecond thresholds, creating baseline demand for hardened controllers across safety-critical installations.
- Automotive OEM Robot Density:German automotive manufacturers operate the densest clusters of connected industrial robots globally, concentrating procurement volume for endpoint security solutions that protect welding and assembly line controllers from lateral movement attacks.
- Fleet-Connected Architecture:Beyond-visual-line-of-sight drone operations for infrastructure inspection multiply network attack surfaces, accelerating investment in encrypted mesh networking protocols for unmanned aerial platforms.
Market Restraints
- Specialized Engineering Talent Collapse:The global supply of robotics security engineers is contracting faster than university programs can replenish qualified graduates, inflating implementation costs for firmware hardening projects.
- Cross-Border Certification Fragmentation:Parallel FDA cybersecurity guidance for medical robots and FAA unmanned aircraft rules create incompatible technical barriers that extend time-to-market for multi-jurisdiction vendors.
- Legacy Controller Vulnerability:Decades-old industrial automation hardware lacks memory capacity for modern encryption stacks, forcing expensive hardware refresh cycles or accepting residual risk in brownfield installations.
Strategic Opportunities
- Medical Robotics Compliance Gap:FDA cybersecurity guidance for surgical and diagnostic robots remains less prescriptive than EU MDR requirements, creating a window for vendors to establish compliant platforms before harmonization tightens.
- Defense-Class Encryption Downscaling:Classified-grade encryption protocols developed for unmanned military platforms are migrating to commercial drone operations, opening premium pricing tiers for hardened civilian systems.
- ISO/IEC 27001 Convergence:The international information security management framework is absorbing robot-specific annexes, enabling vendors to certify once and access multiple national procurement regimes through mutual recognition.
Industry Challenges
- Real-Time Detection Engineering:Sub-50-millisecond intrusion response windows for kinetic harm prevention exceed conventional IT security tool capabilities, demanding custom silicon and firmware architectures that few vendors have mastered.
- Brownfield Integration Complexity:Retrofitting cyber-physical safeguards into operational technology environments without disrupting continuous production requires specialized system integrators whose availability constrains deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cybersecurity in Robotics Market |
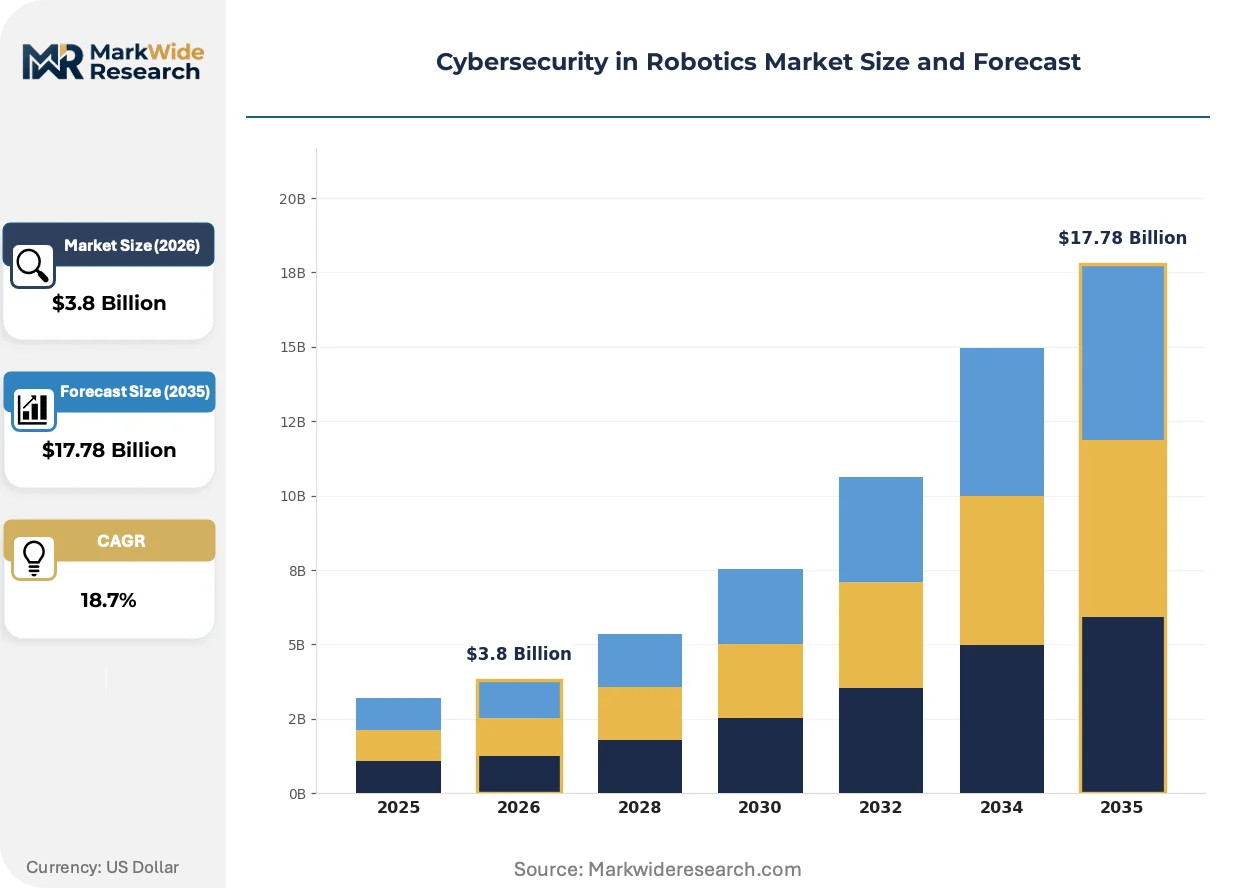
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Security, Network Security, Application Security, Cloud Security Technology: Firewalls, Intrusion Detection Systems, Encryption, Antivirus Software End User: Manufacturing, Healthcare, Defense, Logistics Application: Industrial Automation, Surveillance, Autonomous Vehicles, Drone Operations |
| Companies Covered | Worldline, Airia, Shield AI, WitnessAI, Aurascape, Siemens, Red Alert Labs, 7AI, DEVITY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cybersecurity in Robotics Market Strategic Shifts
Robot security architecture is splitting between hardened edge controllers and cloud-dependent fleet management, with diverging technical requirements reshaping vendor specialization and buyer procurement criteria.
Hardware security modules for robot controllers are bifurcating the endpoint protection market. Automotive OEMs in Germany and Japan are adopting tamper-resistant silicon for welding line robots within 18-month procurement cycles. This technology compression is eliminating software-only security vendors from safety-critical factory floor competitions.
The EU NIS2 Directive's expanded scope to robotics OEMs is mandating incident reporting and supply chain risk management for connected autonomous systems. Industrial automation vendors must now document third-party firmware provenance or face exclusion from critical infrastructure procurement. German automotive clusters are responding fastest, embedding compliance documentation into tender requirements ahead of 2024 implementation deadlines.
Buying committees for robot security are consolidating from distributed IT-OT silos into centralized procurement functions with dedicated cyber-physical specialists. System integrators and value-added distributors are displacing component vendors from direct enterprise relationships. This channel compression is most visible in United States manufacturing regions where private equity consolidation has created multi-site robot fleets with standardized security procurement policies.
Cybersecurity in Robotics Market Segmentation
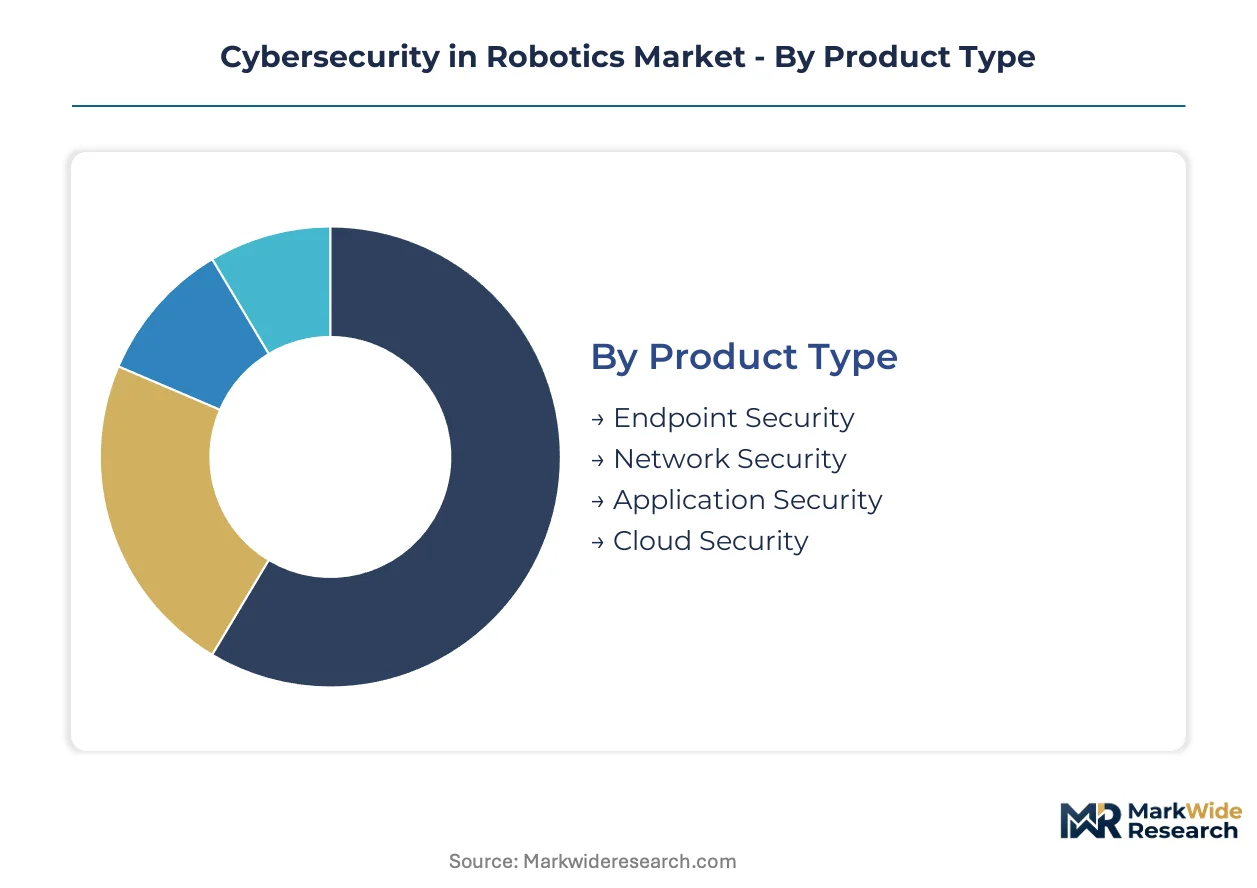
Segmentation in cybersecurity for robotics reveals where protection investments concentrate and which system layers face the most acute threat exposure. Distinct procurement patterns emerge across product architectures, defensive technologies, operational domains, and mission applications.
Product Type:
Network Security faces the most intense substitution pressure as encrypted mesh protocols displace legacy VPN architectures in fleet-connected deployments.
- Endpoint Security:Hardware and firmware safeguards protecting robot controllers, sensors, and actuators from direct compromise. German automotive OEMs concentrate procurement here for welding line robots exposed to lateral movement attacks through dense factory floor connectivity.
- Network Security:Encrypted communication protocols and segmentation controls for fleet-connected architectures. Beyond-visual-line-of-sight drone operations for infrastructure inspection multiply attack surfaces and accelerate demand for hardened mesh networking.
- Application Security:Code-level protections for robot operating systems and mission planning software. Medical device manufacturers embed these controls to satisfy FDA cybersecurity guidance for surgical platforms.
- Cloud Security:Data protection and access controls for centralized fleet management platforms. Logistics operators deploying warehouse robot swarms prioritize these safeguards for multi-tenant cloud environments.
Endpoint Security anchors the volume base while Network Security gains share at the steepest rate.
Technology:
Cost tier differentiation separates custom silicon solutions for safety-critical environments from software-only deployments in less regulated settings.
- Firewalls:Perimeter and internal network barriers filtering traffic between robot subsystems and external networks. Industrial automation vendors pre-configure these for brownfield controller retrofits where memory constraints limit encryption stack deployment.
- Intrusion Detection Systems:Real-time monitoring engines triggering alerts or autonomous responses within sub-50-millisecond windows. Defense robotics applications demand these for kinetic harm prevention during unmanned platform operation.
- Encryption:Cryptographic protocols protecting data at rest and in transit across robot communication channels. Classified-grade implementations are migrating from military to commercial drone operations.
- Antivirus Software:Signature and behavioral scanning tools for robot controller operating systems. Manufacturing facilities with legacy Windows-based automation layers rely on these for malware containment.
Encryption commands premium pricing tiers while Intrusion Detection Systems expand most quickly through EU AI Act conformity mandates.
End User:
Application maturity varies sharply, with Defense and Healthcare operating under prescriptive regulatory frameworks while Manufacturing and Logistics navigate evolving compliance landscapes.
- Manufacturing:Production line protection spanning welding robots, assembly systems, and quality inspection platforms. Ransomware attacks on operational technology networks have compressed procurement cycles for hardened firmware.
- Healthcare:Surgical robot and diagnostic system safeguards meeting FDA cybersecurity guidance and EU MDR requirements. Compliance documentation for third-party firmware provenance is becoming mandatory in tender specifications.
- Defense:Unmanned platform protection sustaining classified-grade encryption for aerial, ground, and maritime systems. Shield AI and similar vendors compete on cryptographic resilience for contested electromagnetic environments.
- Logistics:Warehouse automation and last-mile delivery robot security. Fleet-connected architecture multiplies lateral movement risks across decentralized fulfillment networks.
Manufacturing anchors the volume base while Healthcare climbs the fastest on regulatory tightening.
Application:
Supply concentration in Industrial Automation creates procurement gravity that shapes vendor specialization and technical roadmaps for adjacent segments.
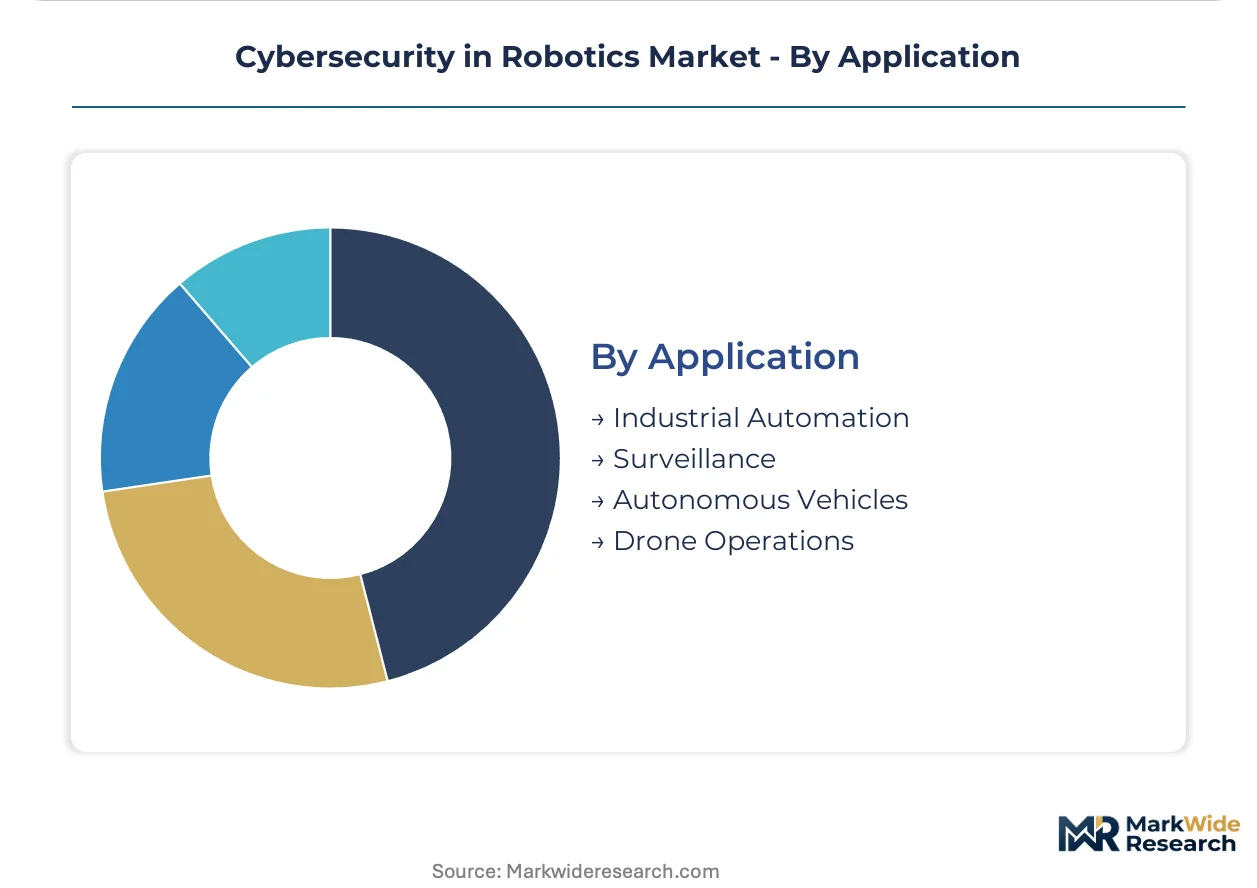
- Industrial Automation:Factory floor robot protection encompassing welding, painting, material handling, and assembly operations. German automotive clusters embed compliance documentation into tender requirements ahead of NIS2 Directive implementation.
- Surveillance:Security robot and fixed sensor platform protection for perimeter monitoring and facility patrol. Data residency requirements constrain cloud-dependent architectures in government and critical infrastructure deployments.
- Autonomous Vehicles:Self-driving car and truck cybersecurity spanning perception systems, decision engines, and vehicle-to-infrastructure communication. NHTSA guidance and state-level regulations create fragmented certification requirements.
- Drone Operations:Unmanned aerial system protection for beyond-visual-line-of-sight missions in infrastructure inspection, agriculture, and emergency response. Encrypted mesh networking protocols are displacing point-to-point radio links.
Industrial Automation anchors the volume base while Drone Operations gains share on fleet-connected architecture proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs deploy endpoint security at densities unmatched elsewhere, while US defense contractors prioritize classified-grade encryption for unmanned platforms. Japanese industrial automation clusters favor hardware-anchored protection over software-only solutions.
United States
FAA unmanned aircraft rules and FDA cybersecurity guidance for medical robots create parallel compliance burdens for cross-border vendors. Defense robotics procurement concentrates in California and Virginia corridors, where Shield AI competes on cryptographic resilience for contested electromagnetic environments. Beyond-visual-line-of-sight drone operations for infrastructure inspection accelerate demand for encrypted mesh networking protocols.
Germany
Automotive manufacturers operate the densest clusters of connected industrial robots globally, welding and assembly line controllers requiring sub-50-millisecond intrusion detection. EU NIS2 Directive implementation deadlines compress procurement cycles for hardened firmware documentation. Bavarian industrial automation vendors embed compliance specifications into tender requirements ahead of 2024 enforcement.
Japan
METI industrial security guidelines drive adoption of tamper-resistant silicon for factory floor deployments. Hardware security modules for robot controllers eliminate software-only vendors from safety-critical competitions. Nagoya and Osaka manufacturing belts prioritize firmware hardening over cloud-dependent fleet management architectures.
United Kingdom
Post-Brexit regulatory divergence from EU AI Act creates uncertainty for robotics OEMs serving both markets. London-based system integrators consolidate procurement functions for multi-site manufacturing fleets. Midlands automotive suppliers retrofit legacy controllers with memory-constrained encryption stacks.
South Korea
MFDS medical device cybersecurity rules and KISA industrial protection standards shape dual compliance frameworks for surgical and factory robots. Seoul Capital Area electronics manufacturers demand pre-certified controllers for export to European markets. Busan-Ulsan shipbuilding clusters adopt defense-class encryption downscaled from military unmanned platforms.
Cybersecurity in Robotics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with industrial automation heritage separating factory-floor protectors from unmanned platform specialists. Siemens leverages its European installed base to anchor endpoint security procurement, while defense-class vendors compete on cryptographic certification depth. Strategic moves concentrate on compliance pre-certification partnerships and hardware-software integration to compress deployment timelines.
Among the integrated tier, Siemens exemplifies industrial automation incumbents extending cyber-physical protection from existing controller relationships. Shield AI occupies a position representing defense-grade encryption specialists migrating protocols to commercial drone operations. Worldline sits within the financial-technology crossover segment, anchoring payment-secure robotics applications.
| Leading Market Players |
|---|
| Worldline |
| Airia |
| Shield AI |
| WitnessAI |
| Aurascape |
| Siemens |
| Red Alert Labs |
| 7AI |
| DEVITY |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German automotive controller foundries anchors price floors for hardened firmware modules, compressing margins for second-tier vendors unable to match Siemens-scale procurement leverage across EU NIS2 compliance documentation.
Pricing Analysis
Long-term offtake contracts dominate procurement for automotive OEMs, while spot purchasing persists in logistics drone deployments. Three-tier pricing structure across premium, standard, and economy levels separates defense-class encryption vendors from software-only providers and legacy antivirus resellers. Cost compression in the standard tier intensifies because brownfield retrofit demand outpaces qualified systems integrator availability. Logistics operators exhibit highest price sensitivity due to thin fleet-management margins, whereas defense contractors prioritize cryptographic certification depth over unit cost.
Supply Chain Analysis
Inventory lead times for tamper-resistant silicon stretch 26-32 weeks, constraining deployment velocity for safety-critical factory floor projects. Manufacturing concentrates in Germany, Japan, and Taiwan, with controller assembly drawing from South Korean memory modules and Dutch lithography equipment. Single-source vulnerability concentrates in EUV-dependent chip fabrication, where ASML equipment access gates production scale. Distribution runs through system integrators and value-added distributors that have displaced component vendors from direct enterprise relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from defense-class encryption vendors downscaling military protocols to commercial drone markets, eroding the premium positioning of software-only security providers.
For Market Incumbents: Shield installed-base relationships through pre-certification partnerships with German automotive clusters ahead of NIS2 enforcement deadlines. Deepen backward integration into custom silicon design to eliminate dependency on external hardware security module suppliers. Channel control through exclusive systems integrator alliances defends against Shield AI-style entrants migrating classified-grade encryption to civilian markets.
For New Entrants and Emerging Players: Post-breach forensic services for ransomware-compromised manufacturing lines represent the most penetrable gap, as incumbent automation vendors lack incident response capabilities. Target United States multi-site manufacturing fleets consolidated by private equity ownership, where standardized security procurement policies bypass traditional IT-OT silos. Go-to-market through regional system integrators with existing FDA compliance expertise accelerates medical robotics penetration before harmonization tightens.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among endpoint security vendors with automotive OEM controller relationships, where firmware subscription models displace perpetual licenses over the projection horizon. Acquisition targets should display EU AI Act conformity assessment capabilities and documented third-party firmware provenance systems. Watch for NIS2 Directive enforcement consistency as the inflection signal distinguishing compliant vendors from excluded suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Partnership | Automotive OEMs embed NIS2 compliance documentation into tender requirements ahead of enforcement. |
| Custom Silicon Development | Tamper-resistant hardware security modules eliminate software-only vendors from safety-critical competitions. |
| Defense Protocol Downscaling | Classified-grade encryption migration to commercial drones opens premium pricing tiers for hardened civilian systems. |
| Systems Integrator Alliance | Channel compression displaces component vendors from direct enterprise relationships in consolidated fleets. |
| Medical Robotics Compliance Buildout | FDA cybersecurity guidance gaps create window for compliant platform establishment before harmonization tightens. |
Study Parameters
Operator-level perspectives from robotics security engineers, automotive OEM procurement directors, medical device regulatory affairs leads, and defense unmanned platform program managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA cybersecurity guidance documents, EU NIS2 Directive implementation notices, FAA unmanned aircraft rulemakings, and ISO/IEC 27001 framework annexes. Bottom-up segment sizing across product types, technologies, and end-user applications converged with top-down market boundary validation.
Sensitivity analysis tested forecast robustness across regulatory enforcement timing scenarios and talent supply elasticity assumptions. Segmentation dimensions modeled encompassed product architecture layers, defensive technology categories, operational domain maturity, and mission application criticality. CAGRs derived from install-base penetration curves for fleet-connected architectures and compliance-driven replacement cycles for legacy controllers. Industry-specific inputs included German automotive robot density metrics and defense encryption certification pipeline data.
Underlying assumptions cover EU AI Act risk-classification stability and NIS2 Directive harmonization progress, with deviation risk concentrated in cross-border certification fragmentation and specialized engineering talent replenishment rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
United Kingdom Cloud Robotics Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Global Autonomous Mobile Robot Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
Delta Robots Market