
 US Tableware Market | 2026-2036
US Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
US Tableware Market Insights
Southeast Asia is rewriting supply chain economics for US tableware importers as Vietnamese and Thai ceramic capacity expands. Corelle Brands LLC leverages its laminated glass-ceramic technology to sustain domestic manufacturing scale against Asian imports. Lifetime Brands, Inc. anchors multi-channel distribution through mass retail partnerships and e-commerce platforms. The Fiesta Tableware Company differentiates through heritage vitrified china production and bold glaze formulations that command specialty retail positioning.
US tableware encompasses plates, bowls, cups, and cutlery manufactured from ceramic, glass, plastic, or stainless steel substrates, with specifications including thermal shock resistance, glaze durability, and dishwasher-safe performance thresholds. These products serve commercial foodservice operators and residential consumers requiring sanitary, durable vessels for food presentation and consumption. Ceramic tableware occupies the premium tier in US hospitality procurement due to perceived quality and tabletop aesthetics, while stainless steel formats gain traction in high-volume casual dining segments where breakage costs dominate operational decisions. The disposable form category faces structural compression from municipal single-use bans, whereas reusable and stackable configurations attract institutional buyers seeking total cost-of-ownership reductions.
The FDA governs food-contact surface safety through 21 CFR standards that dictate lead and cadmium leaching limits for ceramic glazes, directly constraining material formulations and supplier qualification pathways. California's Department of Toxic Substances Control enforces Proposition 65 warning requirements on tableware containing detectable heavy metals, creating compliance cost differentials between domestic and imported products. OSHA workplace safety standards influence manufacturing automation investments at US-based producers. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could restructure material recovery obligations and reshape competitive economics across the value chain.
Market Dynamics
California's SB 54 mandates phased reductions in single-use food serviceware, redirecting procurement toward reusable stainless steel and tempered glass formats while reshaping supplier qualification pathways across the value chain.
Growth Catalysts
- Experiential Dining Rebound:Fine dining establishments are expanding ceramic and porcelain purchases as post-pandemic experiential dining recovers, creating sustained demand for premium vitrified china.
- SB 54 Compliance Deadlines:California's phased single-use reduction mandates are forcing foodservice operators to accelerate reusable tableware procurement cycles ahead of enforcement milestones.
- Texas Hospitality Construction:Metropolitan corridors in Texas are clustering new hospitality builds and corporate catering hubs, concentrating demand for durable stainless steel and tempered glass formats.
Market Restraints
- Alumina and Silica Input Volatility:Ceramic manufacturers face structural margin pressure from energy-intensive kiln operations and raw material cost swings in feldspar and kaolin supply.
- Southeast Asian Supply Concentration:Vietnamese and Thai ceramic capacity expansion has created import dependency risks for US distributors seeking laminated glass-ceramic alternatives.
- Lead Leaching Compliance Friction:FDA 21 CFR standards and California Proposition 65 warning requirements create dual-track testing burdens that favor domestic producers with established certification pathways.
Strategic Opportunities
- Texas Corporate Catering Hubs:Underpenetrated institutional procurement in Dallas-Fort Worth and Houston offers white space for stackable stainless steel configurations targeting total cost-of-ownership buyers.
- FDA-Compliant Glaze Innovation:Heavy-metal-free ceramic formulations that exceed 21 CFR thresholds can capture premium positioning in California's regulated environment.
- E-Commerce Platform Convergence:Multi-channel distribution partnerships combining mass retail presence with direct-to-consumer fulfillment are compressing traditional wholesale markups.
Industry Challenges
- Automation Engineering Talent Scarcity:OSHA-compliant manufacturing investments require skilled technicians for kiln automation and quality control systems that US producers struggle to source.
- Dual Certification Timeline Compression:Simultaneous FDA lead-cadmium testing and California DTSC Proposition 65 compliance extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tableware Market |
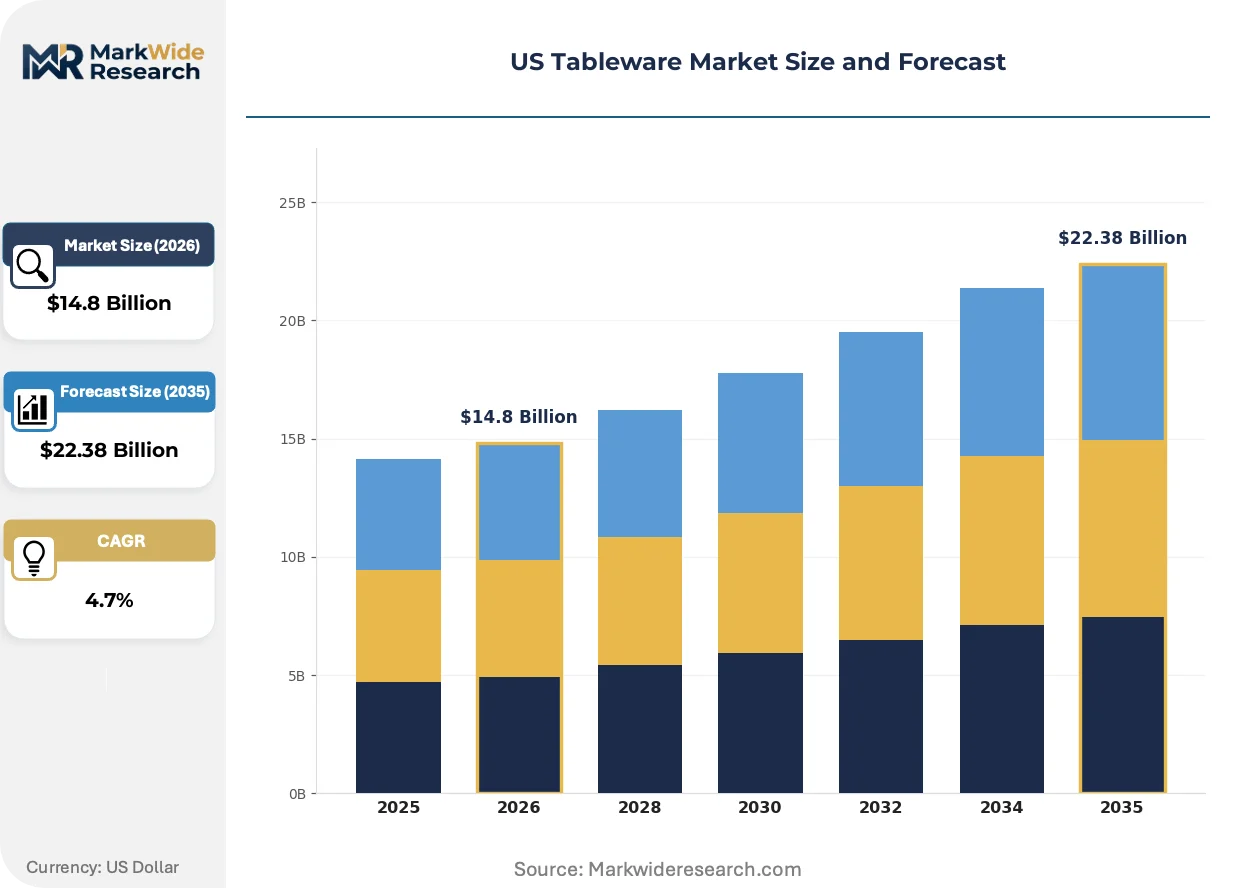
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.38 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cups, Cutlery Material: Ceramic, Glass, Plastic, Stainless Steel Form: Disposable, Reusable, Stackable, Customizable End User: Restaurants, Households, Catering Services, Hotels |
| Companies Covered | Corelle Brands LLC, Steelite International, Libbey Inc., Lifetime Brands, Inc., The Fiesta Tableware Company, Lenox Corporation, HF Coors, Tuxton China Inc., Oneida Hospitality Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tableware Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape competitive positioning across ceramic, glass, and metal substrate categories.
Laminated glass-ceramic technology is hybridizing thermal shock resistance with lightweight durability, enabling oven-to-table performance that vitrified china cannot match. Casual dining chains are adopting these formats at accelerated rates to reduce breakage replacement costs. The technology is hybridizing premium aesthetics with operational economics previously reserved for disposable alternatives.
FDA 21 CFR standards for lead and cadmium leaching limits are tightening enforcement pathways for imported ceramic glazes, forcing supplier qualification restructuring. Domestic producers with captive testing laboratories are capturing compliance cost advantages. California's Proposition 65 warning requirements are compressing demand for detectable heavy-metal tableware in West Coast foodservice procurement.
Corporate catering procurement is consolidating vendor relationships around stackable, dishwasher-safe configurations that reduce storage footprint and labor handling. National account buyers are displacing fragmented local supplier networks with centralized national distribution agreements. This concentration is most visible in Texas metropolitan corridors where hospitality construction and catering hub expansion overlap.
US Tableware Market Segmentation
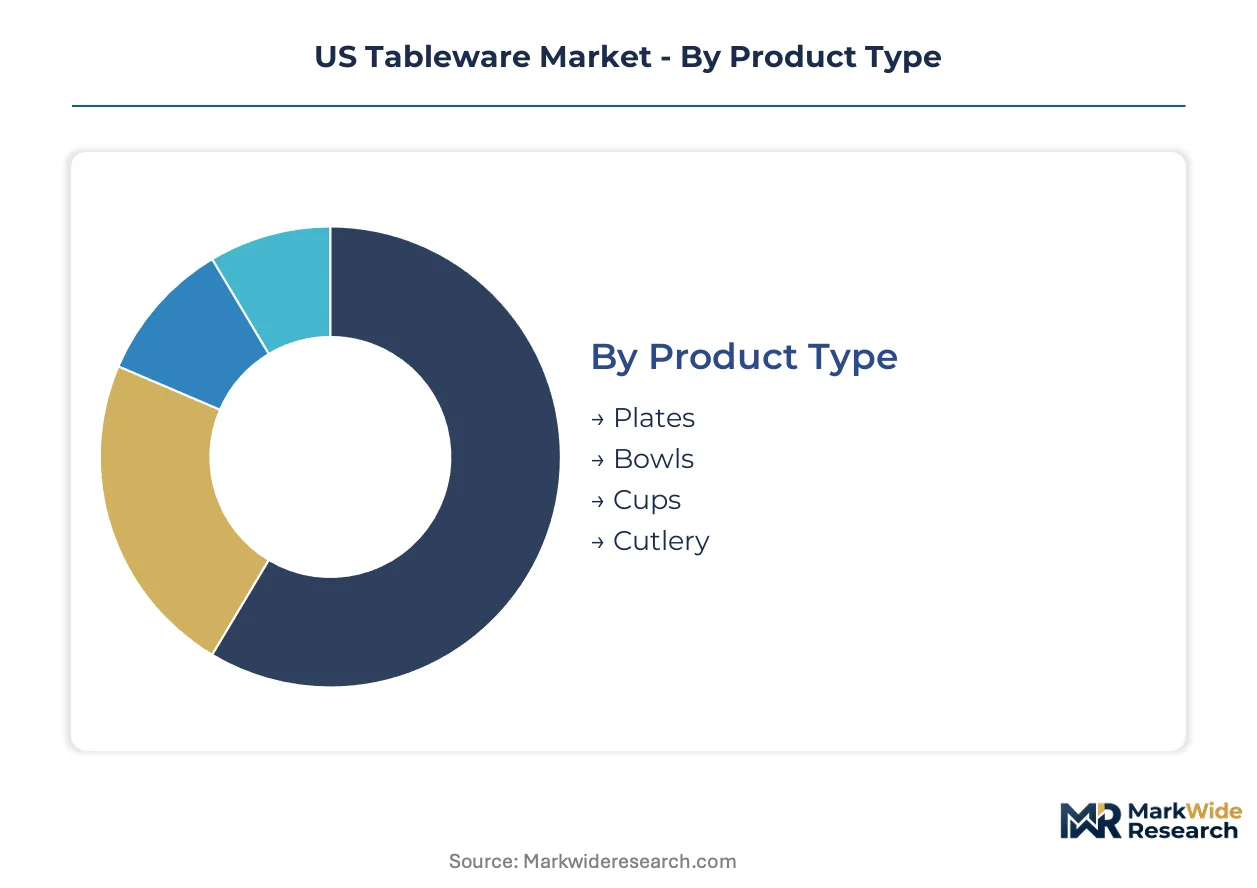
US tableware procurement splits across material specifications, operational formats, and end-use requirements that dictate durability standards, compliance burdens, and total cost-of-ownership calculations. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape supplier qualification pathways.
Product Type:
Application context determines structural specifications across vessel categories, from flatware thermal shock thresholds to cutlery edge retention requirements.
- Plates:Flatware specifications center on diameter-to-weight ratios and glaze durability for high-temperature commercial dishwashing. Fine dining establishments in California drive demand for vitrified china formats that satisfy FDA 21 CFR leaching thresholds and Proposition 65 warning exemptions.
- Bowls:Depth-to-rim strength ratios define performance for soup and pasta service formats. Texas corporate catering hubs concentrate procurement of stackable stainless steel configurations that reduce storage footprint in high-volume institutional kitchens.
- Cups:Handle attachment integrity and thermal insulation properties vary by beverage service application. Double-walled ceramic and tempered glass formats target specialty coffee operators seeking extended heat retention.
- Cutlery:Edge geometry and corrosion resistance differentiate flatware tiers across casual and fine dining segments. Forged stainless steel patterns command premium positioning in hospitality procurement.
Plates command the established base. The steepest expansion runs through bowls as bowl-centric menu formats proliferate across fast-casual concepts.
Material:
Substrate selection governs compliance pathways, breakage economics, and lifecycle cost calculations across procurement tiers.
- Ceramic:Vitrified and stoneware compositions offer glaze customization and tabletop aesthetics prized in experiential dining. California's SB 54 implementation timeline accelerates inquiries for reusable ceramic alternatives to disposable formats, though lead-cadmium testing burdens favor domestic producers with captive laboratories.
- Glass:Tempered and laminated glass-ceramic technologies hybridize thermal shock resistance with reduced weight. Casual dining chains adopt these formats to compress breakage replacement costs while maintaining oven-to-table versatility.
- Plastic:Melamine and polypropylene formats face structural compression from municipal single-use bans and California's phased reduction mandates. Remaining demand concentrates in healthcare and institutional segments with specialized sanitation protocols.
- Stainless Steel:Austenitic and ferritic grades deliver durability for high-volume operations where breakage cost dominates operational decisions. Texas hospitality construction clusters drive procurement of 18/8 and 18/10 compositions for corporate catering and hotel banquet applications.
Ceramic retains the volume anchor. Stainless steel climbs the fastest as operational durability priorities displace aesthetic considerations in institutional procurement.
Form:
Operational format determines reuse cycles, storage density, and regulatory exposure across foodservice segments.
- Disposable:Single-use formats face accelerated displacement from California SB 54 compliance deadlines and municipal ban expansions. Surviving demand concentrates in healthcare isolation protocols and emergency foodservice operations.
- Reusable:Durable formats capture procurement share as operators amortize acquisition costs against reduced per-use waste fees. National account buyers consolidate vendor relationships around dishwasher-safe configurations with standardized handling protocols.
- Stackable:Nesting geometries reduce cubic footage requirements in high-rent urban kitchens and mobile catering operations. Texas metropolitan corridors show concentrated adoption for corporate catering hub configurations.
- Customizable:Branded and color-matched formats support chain identity programs and hospitality concept differentiation. Vitrified china glaze matching and laser-etched stainless steel patterns serve this tier.
Reusable formats hold the established position. Stackable configurations gain share fastest as real estate costs and labor efficiency drive storage optimization priorities.
End User:
Customer type dictates volume scale, specification stringency, and vendor relationship structure across the value chain.
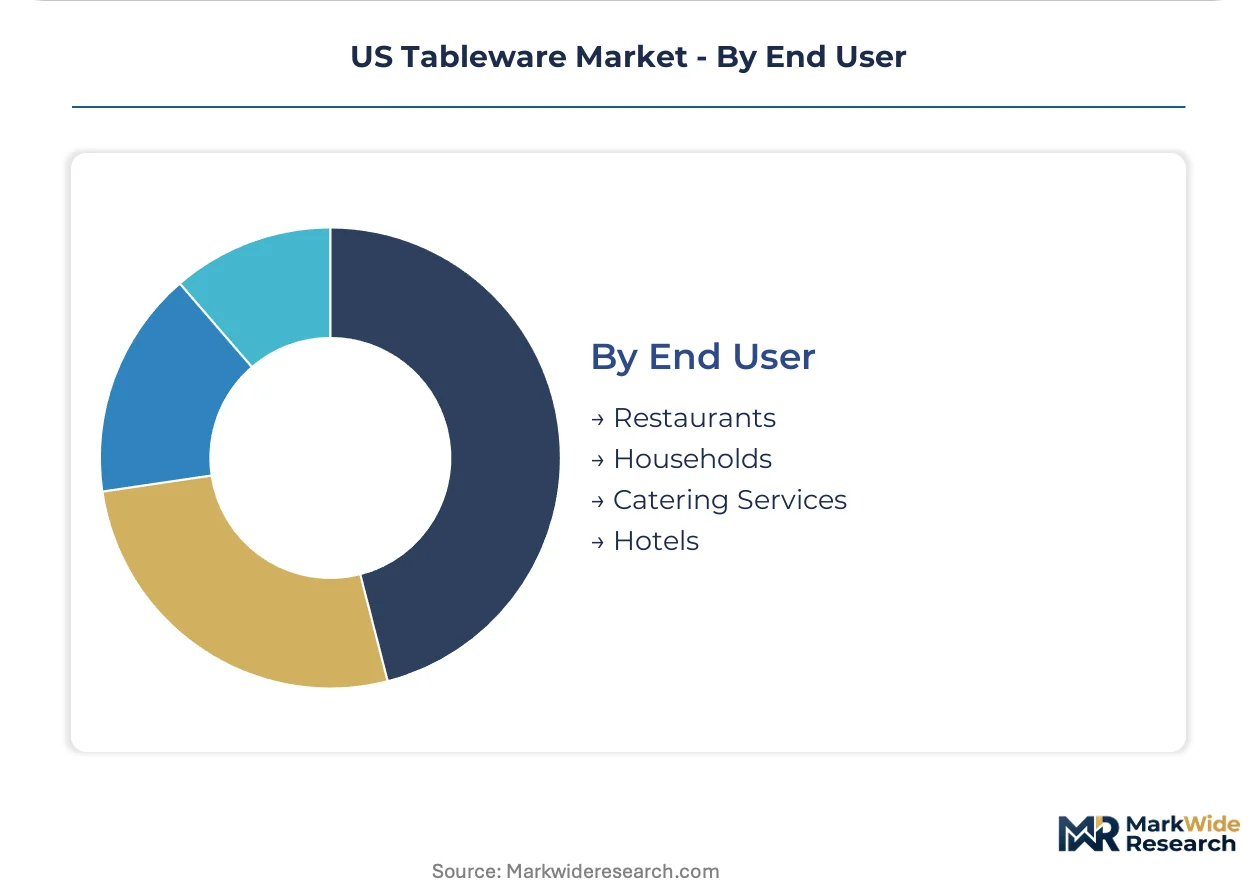
- Restaurants:Full-service and limited-service operators balance breakage costs against tabletop presentation requirements. Fine dining segments prioritize vitrified china and forged flatware, while casual concepts adopt laminated glass-ceramic and stamped stainless steel formats.
- Households:Residential procurement flows through mass retail and e-commerce channels with dishwasher-safe performance as the primary filter. Open stock and boxed set configurations serve replacement and gifting occasions.
- Catering Services:Mobile and institutional caterers prioritize stackability, transport durability, and rapid turnaround compatibility. National account consolidation displaces fragmented local supplier networks in this segment.
- Hotels:Lodging operators coordinate banquet, room service, and restaurant specifications across property portfolios. Brand standards programs drive centralized procurement with compliance documentation requirements.
Restaurants anchor volume concentration. Catering services expand most quickly as corporate hub construction and national account consolidation reshape vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material sourcing for ceramic substrates concentrates in southeastern clay deposits, while finished goods distribution networks radiate from Texas logistics corridors. State-level regulatory divergence is fragmenting procurement standards across domestic markets.
California
Fine dining establishments in Los Angeles and San Francisco are expanding vitrified china purchases as experiential dining rebounds post-pandemic. The state's Department of Toxic Substances Control enforces Proposition 65 warning requirements on tableware containing detectable heavy metals. Sacramento's regulatory cluster is accelerating supplier qualification restructuring for FDA 21 CFR compliance.
Texas
Metropolitan corridors in Dallas-Fort Worth and Houston are clustering new hospitality builds and corporate catering hubs, concentrating demand for durable stainless steel formats. Municipal procurement guidelines in Austin favor reusable tableware for city-contracted foodservice operations. San Antonio's distribution infrastructure is expanding cold-chain capacity for tempered glass logistics.
New York
Manhattan's restaurant density sustains premium ceramic and porcelain procurement despite compressed kitchen footprints. The state's environmental conservation regulations restrict single-use serviceware in state-owned facilities. Buffalo's manufacturing heritage anchors specialty glaze production for hospitality-grade vitrified china.
Illinois
Chicago's corporate headquarters concentration drives institutional catering procurement for stackable, dishwasher-safe configurations. Cook County's waste reduction ordinances mandate reusable alternatives for large-scale foodservice contracts. Peoria's logistics nodes are consolidating Midwest distribution for laminated glass-ceramic products.
Florida
Orlando's tourism and hospitality construction pipeline sustains bulk procurement of breakage-resistant tempered glass formats. Miami-Dade County's single-use reduction initiatives redirect beachfront and hotel procurement toward reusable substrates. Tampa's port infrastructure is expanding import handling capacity for Southeast Asian ceramic shipments.
US Tableware Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and glaze supply. The US tableware market structures around three tiers: mass-market distributors with multi-channel reach, specialty producers with captive manufacturing, and import-dependent wholesalers with Southeast Asian supply relationships. Strategic archetypes include laminated glass-ceramic technology holders, heritage vitrified china specialists, and stainless steel fabricators with institutional scale. Consolidation through national account partnerships and vertical integration into raw material processing are displacing fragmented local supplier networks.
Among domestic technology holders, Corelle Brands LLC and The Fiesta Tableware Company exemplify divergent competitive positions. Corelle Brands LLC represents the laminated glass-ceramic archetype with sustained domestic manufacturing scale against import pressure. The Fiesta Tableware Company anchors the heritage vitrified china tier through bold glaze differentiation and specialty retail positioning. Lifetime Brands, Inc. sits within the multi-channel distribution archetype, leveraging mass retail partnerships and e-commerce platform convergence.
| Leading Market Players |
|---|
| Corelle Brands LLC |
| Steelite International |
| Libbey Inc. |
| Lifetime Brands, Inc. |
| The Fiesta Tableware Company |
| Lenox Corporation |
| HF Coors |
| Tuxton China Inc. |
| Oneida Hospitality Group |
| Others |
Pricing and Supply Chain Analysis
Vietnamese ceramic clusters around Binh Duong province anchor global capacity expansion, feeding cost-competitive vitrified china into US distribution channels while compressing margin structures for domestic producers lacking comparable scale economics.
Pricing Analysis
California's Proposition 65 dictates the pricing tier structure by imposing dual-track compliance burdens that separate domestic FDA-certified producers from import-dependent distributors facing extended testing timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification completeness, with captive-laboratory domestic producers commanding premium positioning. Pricing pressure stems from Southeast Asian ceramic capacity expansion flooding mid-market channels. Institutional buyers in Texas corporate catering hubs exhibit highest price sensitivity, while California fine dining establishments prioritize compliance assurance over unit cost.
Supply Chain Analysis
Extended payment terms from Southeast Asian suppliers now stretch to 120 days for US distributors, straining working capital and favoring larger wholesalers with supply-chain finance facilities. Manufacturing concentrates in Vietnam, Thailand, and China for ceramic substrates, while domestic production clings to laminated glass-ceramic and specialty vitrified china. Raw material dependencies center on feldspar from Turkey, kaolin from Georgia and Brazil, and alumina from Australia. Tariff exposure on Chinese ceramic imports constitutes the primary structural risk. Distribution runs through Texas logistics corridors radiating to national foodservice accounts and mass retail consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable advantages—incumbents with captive FDA testing laboratories and established California DTSC compliance pathways face substitution threats that new entrants cannot easily replicate.
For Market Incumbents: Insulate core positioning by deepening backward integration into Georgia kaolin processing and expanding captive laboratory capacity to compress Proposition 65 certification cycles. Threats from Vietnamese ceramic capacity expansion intensify margin pressure in mid-market channels. Channel control through national account partnerships with Texas hospitality construction clusters offers the strongest defensive lever. For New Entrants and Emerging Players: Build out white-space presence in stackable stainless steel configurations for Texas corporate catering hubs, where durability requirements and total cost-of-ownership calculations favor new supply relationships over entrenched ceramic vendors. The most penetrable segment sits in institutional procurement for Dallas-Fort Worth and Houston construction pipelines. A direct-to-foodservice-operator go-to-market angle bypasses wholesale markups and accelerates trial. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because FDA 21 CFR compliance infrastructure and California DTSC certification relationships compound over time into defensible competitive positions. Target acquisition archetypes include domestic ceramic producers with captive testing laboratories and established West Coast distributor relationships. The signal to watch is acceleration in Texas hospitality construction permitting as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Processing | Captive kaolin and feldspar supply from Georgia and Turkey deposits insulates margin structures from commodity volatility. |
| FDA-Compliant Glaze Innovation | Heavy-metal-free formulations exceeding 21 CFR thresholds capture premium positioning in California's regulated procurement environment. |
| National Account Partnership Consolidation | Centralized vendor relationships with Texas corporate catering hubs displace fragmented local supplier networks and compress competitor access. |
| Multi-Channel Distribution Convergence | Mass retail presence combined with direct-to-consumer fulfillment reduces wholesale dependency and captures margin expansion. |
| Automation Engineering Investment | OSHA-compliant kiln automation addresses technician scarcity and sustains domestic manufacturing scale against import pressure. |
Research Methodology
The analysis maps ceramic, glass, plastic, and stainless steel substrate categories, each validated through foodservice procurement directors, hospitality supply chain managers, ceramic manufacturing plant engineers, and mass retail category buyers. Primary interview insights triangulate against customs import records, FDA 21 CFR compliance filings, California DTSC Proposition 65 enforcement data, and hospitality construction permitting databases. Bottom-up demand modeling from end-user segments converges with top-down supply capacity assessments across Vietnamese, Thai, and domestic manufacturing clusters.
Assumptions held fixed include California SB 54 phased reduction timelines and FDA 21 CFR enforcement intensity, while variables tested include Southeast Asian capacity expansion rates and Texas hospitality construction velocity. Segmentation dimensions span material substrate, operational form, and end-user category, with regional regulatory clusters modeled separately. CAGRs derive from installed base turnover analysis and replacement cycle compression across commercial foodservice operators. Industry-specific inputs incorporate kiln energy cost trajectories and alumina-silica raw material price indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Vietnamese ceramic producers or accelerated FDA enforcement tightening would shift outcomes. Macroeconomic deviation in hospitality construction lending, regulatory expansion of single-use bans beyond California, or breakthrough advances in biodegradable substrate performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
UK Ceramic Tableware Market