
 Non-Alcoholic Steatohepatitis Clinical Trials Market | 2026-2036
Non-Alcoholic Steatohepatitis Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Steatohepatitis Clinical Trials Market Intelligence
Adaptive trial design and decentralized clinical trial technology is reshaping how NASH studies are executed, enabling remote patient monitoring and reducing site burden. Pfizer Inc. leverages its global site network to accelerate enrollment in fibrosis-targeting programs. Novartis AG anchors its NASH portfolio through deep R&D investment in combination therapies. Gilead Sciences Inc. dominates the hepatology trial landscape with extensive investigator relationships across academic medical centers.
Non-Alcoholic Steatohepatitis clinical trials constitute regulated research studies evaluating investigational therapies for progressive fatty liver disease characterized by hepatocellular ballooning, lobular inflammation, and varying degrees of fibrosis staged from F0 to F4, with liver biopsy and non-invasive biomarkers serving as primary efficacy endpoints. These trials generate safety and efficacy data required for regulatory submission and subsequent commercial authorization of therapies addressing unmet need in metabolic liver disease. Trial phase segmentation reveals Phase 2 studies capturing the largest share of current investigator activity, driven by intensive dose-ranging and biomarker validation requirements. Intervention type segmentation shows biologics and combination therapies representing the fastest-expanding categories, as monotherapy limitations in NASH push sponsors toward multi-target approaches. Study design segmentation indicates randomized controlled trials maintaining primacy for registrational programs, though open-label extensions proliferate for long-term safety collection.
FDA breakthrough therapy designation and EMA PRIME eligibility frameworks compress development timelines and intensify competition for eligible NASH assets. The European Medicines Agency applies stringent benefit-risk standards for liver safety signals, while the FDA's draft NASH guidance on surrogate endpoints shapes primary endpoint selection across sponsor pipelines. Sponsors must monitor evolving regulatory acceptance of non-invasive biomarkers as potential alternatives to liver biopsy in pivotal trials.
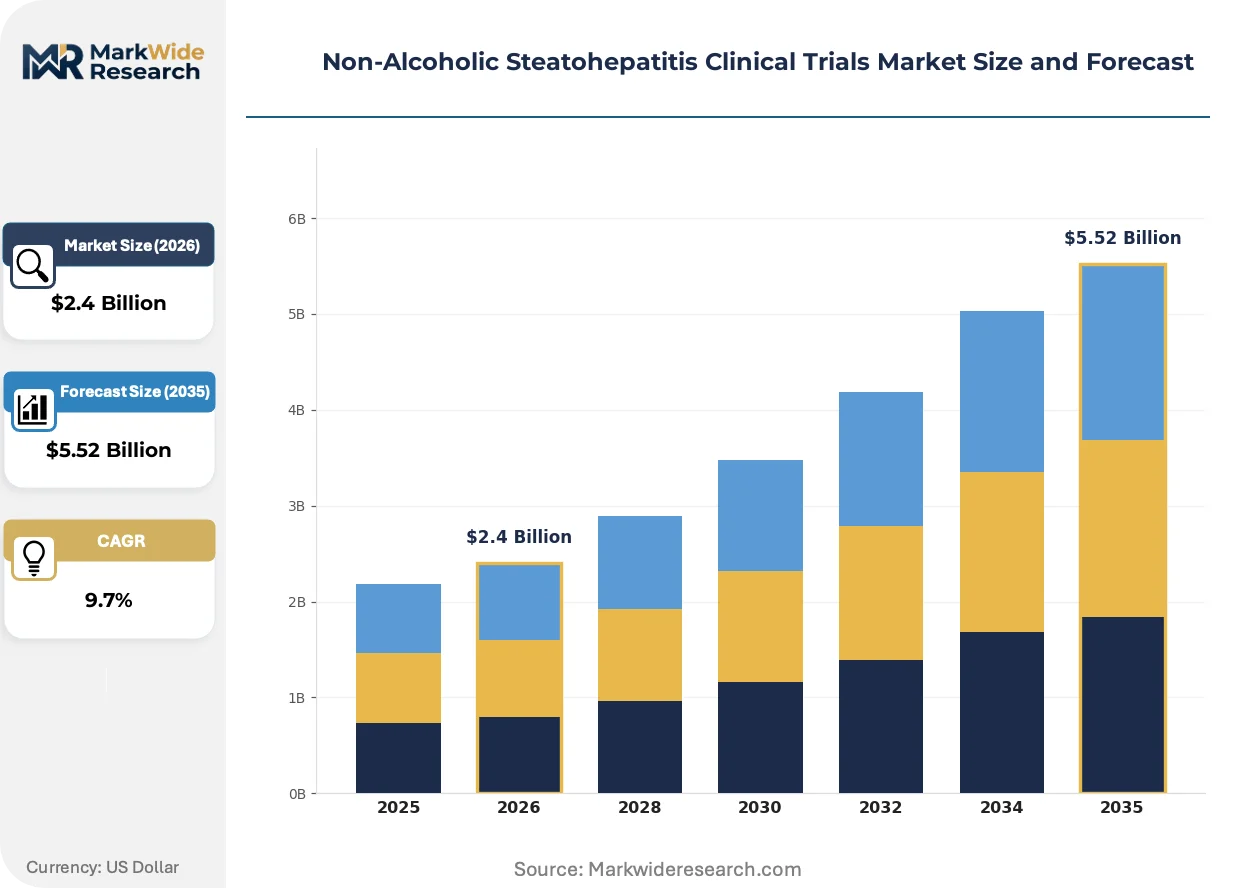
Market Dynamics
FDA accelerated approval pathways for breakthrough NASH therapies compress development timelines and intensify sponsor competition for eligible assets. Biopharmaceutical sponsors now prioritize adaptive trial designs integrating non-invasive biomarkers alongside traditional liver biopsy endpoints.
Growth Catalysts
- FDA Breakthrough Therapy Designation:This regulatory pathway compresses Phase 2 to Phase 3 transitions for NASH assets demonstrating substantial improvement over available therapy. Sponsors prioritize enrollment velocity to capture designation benefits.
- Decentralized Clinical Trial Platforms:Remote patient monitoring technologies reduce site burden and expand geographic recruitment reach. Metabolic disease specialist sites in the United States leverage these tools to accelerate fibrosis-staging cohort assembly.
- EMA PRIME Eligibility Framework:European priority medicines status enhances scientific dialogue and accelerates marketing authorization assessment for NASH therapies addressing unmet medical need.
Market Restraints
- Biopsy Dependency:Persistent regulatory requirement for histologic endpoints maintains invasive procedure costs and patient recruitment friction. Liver biopsy sampling variability introduces noise that inflates required trial sample sizes.
- Site Concentration Risk:Investigator expertise clusters at academic medical centers in the United States and Western Europe. This geographic concentration creates enrollment bottlenecks and site activation delays.
- Biomarker Validation Gaps:Non-invasive alternatives to liver biopsy lack harmonized regulatory acceptance across FDA and EMA jurisdictions. Sponsors must maintain dual endpoint strategies that inflate protocol complexity.
Strategic Opportunities
- Asia-Pacific Enrollment Expansion:Underserved patient populations in Japan and South Korea present untapped recruitment potential for fibrosis-targeting programs. PMDA and MFDS regulatory harmonization initiatives reduce multi-regional trial friction.
- Combination Therapy Development:Convergence of metabolic and anti-fibrotic mechanisms enables novel multi-target protocols. Sponsors exploit mechanistic synergies that monotherapy approaches cannot address.
- Real-World Evidence Integration:Open-label extension designs and patient registries generate long-term safety datasets. Post-marketing commitments transform into competitive differentiation tools.
Industry Challenges
- Specialized Investigator Scarcity:Hepatology expertise with metabolic disease focus concentrates at select academic medical centers. Sponsors compete intensely for qualified principal investigators capable of managing complex NASH protocols.
- Cross-Functional Integration Complexity:Adaptive trial designs require seamless coordination between biomarker laboratories, imaging core facilities, and data monitoring committees. Operational silos generate protocol amendment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Steatohepatitis Clinical Trials Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase 1, Phase 2, Phase 3, Phase 4 Intervention Type: Drug, Biologic, Nutraceutical, Combination Therapy Study Design: Randomized Controlled Trial, Open Label, Cohort Study, Cross-Sectional Study Patient Demographic: Aged 18-65, Aged 66+, Pediatric, Comorbid Conditions |
| Companies Covered | Pfizer Inc., Novartis AG, Icon Plc, Laboratory Corporation of America, AbbVie Inc., Gilead Sciences Inc., Novo Nordisk, Eli Lilly, Intercept Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Steatohepatitis Clinical Trials Market Strategic Shifts & Innovations
Non-invasive biomarker technologies are displacing traditional liver biopsy as the central efficacy measurement paradigm in NASH trials. Artificial intelligence-enabled imaging analysis and circulating biomarker panels reshape endpoint selection and patient monitoring workflows.
Magnetic resonance imaging-proton density fat fraction (MRI-PDFF) and magnetic resonance elastography (MRE) are digitizing fibrosis staging workflows across Phase 2 and Phase 3 protocols. Mid-cap biopharmaceutical sponsors adopt these platforms to reduce screen failure rates and accelerate enrollment timelines. This technology compression enables remote efficacy assessment that reduces site visit burden.
EMA's evolving benefit-risk standards for liver safety signals now require enhanced pharmacovigilance planning in NASH development programs. Sponsors must pre-specify hepatic adverse event adjudication committees and accelerated safety reporting triggers. European trial designs increasingly incorporate these requirements from protocol inception rather than amendment.
Patient advocacy group engagement is restructuring recruitment channel strategies for NASH studies. Traditional physician referral networks face displacement from direct-to-patient digital outreach and community-based screening programs. This behavioral shift concentrates in the United States where metabolic disease awareness campaigns activate undiagnosed populations.
Non-Alcoholic Steatohepatitis Clinical Trials Market Segmentation
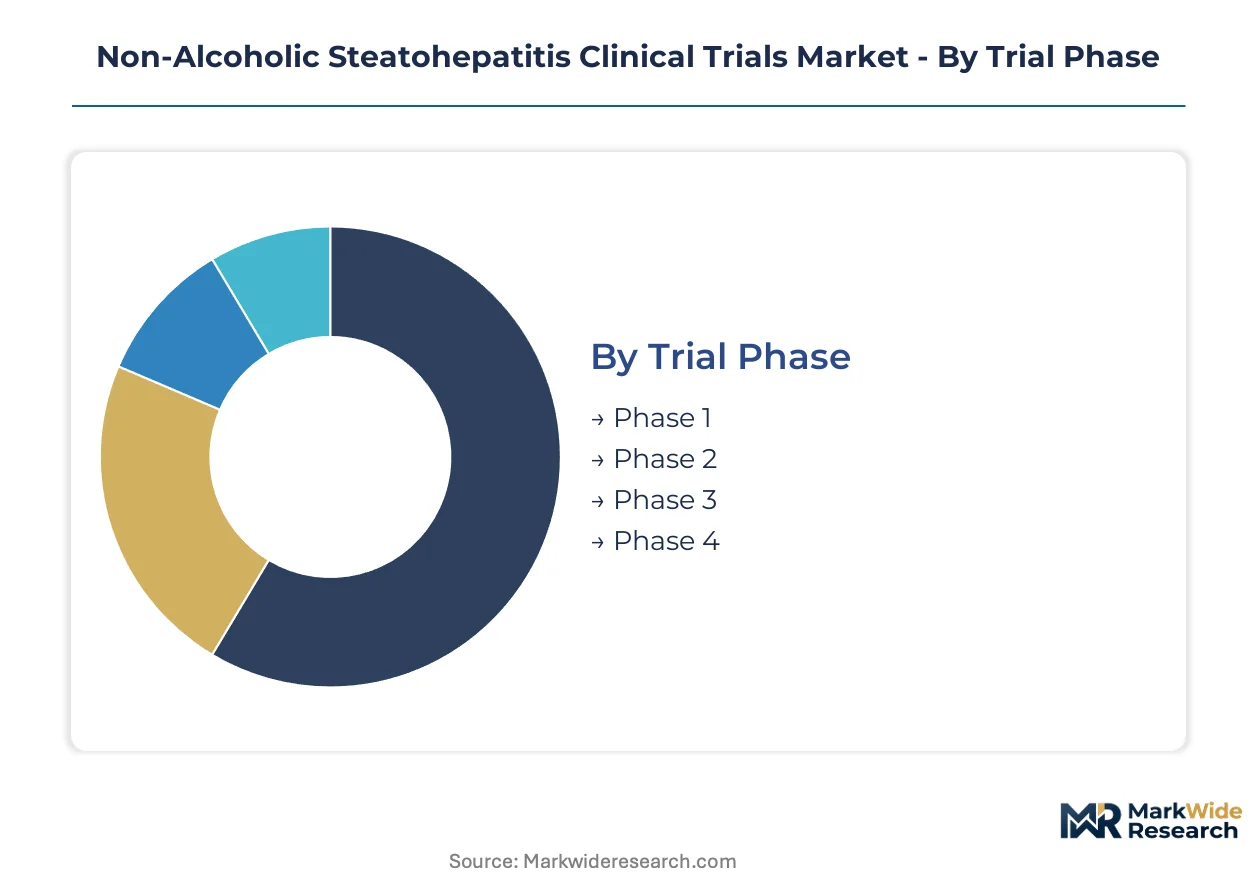
NASH trial segmentation reveals distinct operational and commercial profiles across development stages, therapeutic modalities, and patient populations. Each dimension shapes site selection, endpoint design, and regulatory strategy differently.
Trial Phase:
Development stage determines enrollment scale, endpoint rigor, and regulatory interaction intensity. Early-phase trials concentrate at academic medical centers with specialized hepatology infrastructure.
- Phase 2:Dose-ranging studies with intensive biomarker validation requirements dominate current investigator activity. Fibrosis-staging cohorts assemble across United States metabolic disease specialist sites where non-invasive imaging platforms reduce screen failure rates.
- Phase 3:Registrational trials deploy randomized controlled designs with histologic endpoints for FDA submission. Liver biopsy requirements sustain high per-patient costs and prolong recruitment timelines at academic medical centers.
- Phase 1:First-in-human safety studies in healthy volunteers establish pharmacokinetic profiles.
- Phase 4:Post-marketing commitments generate real-world safety datasets for label expansion.
Phase 2 holds installed capacity. Phase 3 is rotating up the share rankings.
Intervention Type:
Therapeutic modality shapes manufacturing complexity, regulatory pathway, and combination protocol feasibility. Biologics and multi-target approaches command premium development investment.
- Combination Therapy:Multi-target protocols exploit mechanistic synergies between metabolic and anti-fibrotic mechanisms. Sponsors prioritize these approaches as monotherapy limitations in NASH push toward integrated interventions.
- Biologic:Monoclonal antibodies and peptide therapeutics target specific inflammatory pathways. Development concentrates at sponsors with established biologics manufacturing infrastructure.
- Drug:Small-molecule candidates dominate historical NASH pipelines with established oral delivery profiles.
- Nutraceutical:Dietary supplement interventions address lifestyle modification endpoints in exploratory studies.
Drug holds installed capacity. Combination Therapy is rotating up the share rankings.
Study Design:
Methodological architecture determines evidentiary strength, patient burden, and regulatory acceptance. Randomized designs maintain primacy for marketing authorization.
- Randomized Controlled Trial:Double-blind placebo-controlled designs generate definitive efficacy evidence for FDA and EMA submission. These protocols require extensive site training and centralized imaging adjudication.
- Open Label:Unmasked extensions collect long-term safety data following controlled treatment periods. Patient registries transform these datasets into competitive differentiation tools.
- Cohort Study:Prospective observational designs characterize natural history progression.
- Cross-Sectional Study:Prevalence surveys establish baseline disease burden for trial planning.
Randomized Controlled Trial holds installed capacity. Open Label is rotating up the share rankings.
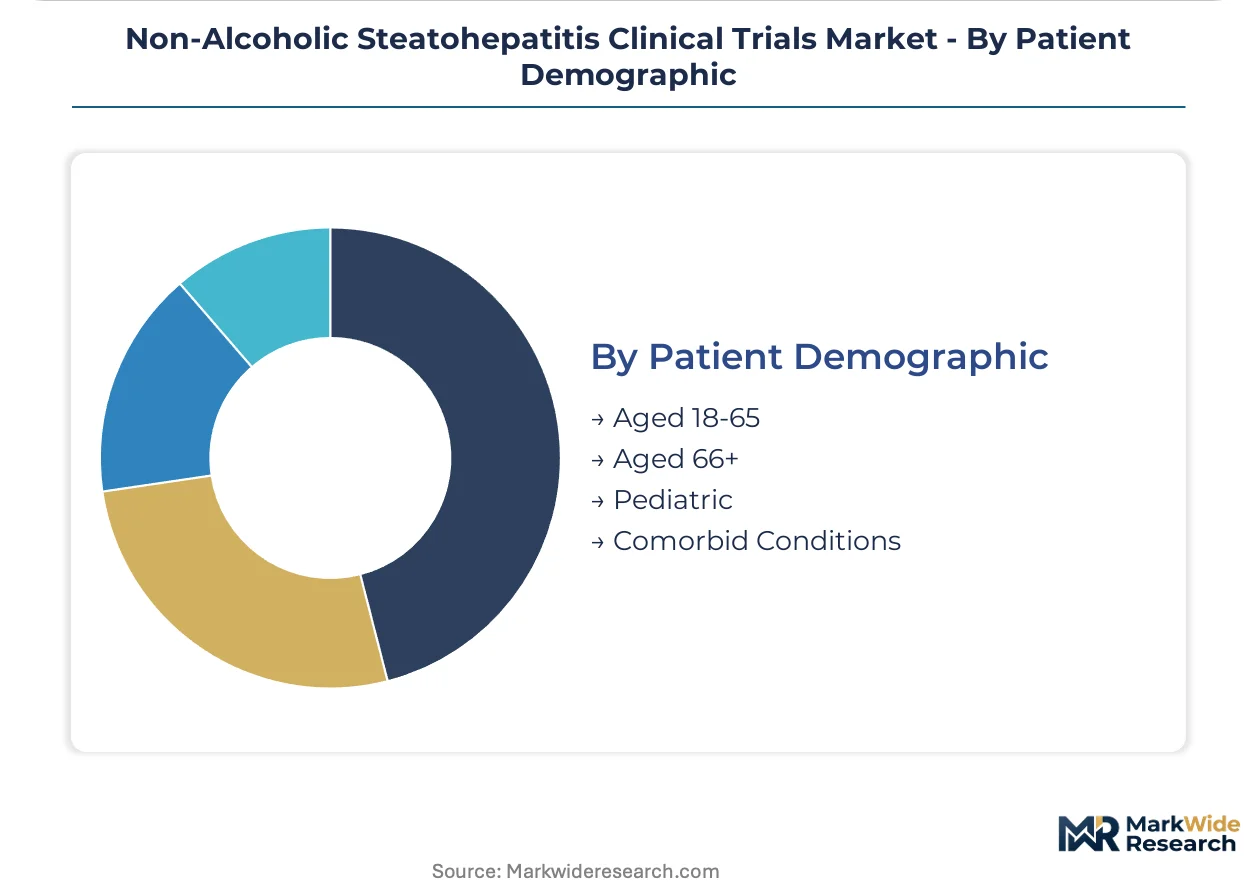
Patient Demographic:
Age distribution and comorbidity profile influence endpoint selection, exclusion criteria, and site recruitment strategy. Metabolic disease clustering shapes geographic targeting.
- Aged 18-65:Core working-age population exhibits highest NASH prevalence with type 2 diabetes comorbidity. United States recruitment concentrates in Southern and Midwestern states where metabolic syndrome rates exceed national averages.
- Comorbid Conditions:Type 2 diabetes, obesity, and cardiovascular disease subpopulations demonstrate accelerated fibrosis progression. These patients populate enrichment strategies for faster event accumulation.
- Aged 66+:Elderly cohorts face competing mortality risks that complicate long-term endpoint assessment.
- Pediatric:Adolescent NASH studies address rising childhood obesity prevalence with modified dosing protocols.
Aged 18-65 holds installed capacity. Comorbid Conditions is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical sponsors concentrate trial investment where metabolic disease specialist sites cluster and regulatory pathways compress development timelines. The United States, Germany, United Kingdom, Japan, and South Korea anchor this geographic deployment.
United States
FDA breakthrough therapy designation attracts sponsor investment toward fibrosis-targeting programs. The agency's draft NASH guidance on surrogate endpoints shapes primary endpoint selection across development pipelines. Academic medical centers in Boston, San Francisco, and Houston maintain dense concentrations of hepatology investigators capable of managing complex biopsy-intensive protocols.
Germany
EMA PRIME eligibility frameworks accelerate marketing authorization assessment for therapies addressing unmet medical need in metabolic liver disease. The country's national pharmaceutical regulator applies stringent benefit-risk standards for liver safety signals that sponsors must address in protocol design. The Rhine-Main and Munich clusters host specialized hepatology units that support multi-center European enrollment.
United Kingdom
MHRA post-Brexit regulatory autonomy enables streamlined trial approvals for adaptive designs integrating non-invasive biomarkers. The national health system's centralized patient registries facilitate rapid cohort identification for fibrosis-staging studies. London and Cambridge academic medical centers maintain investigator networks that span Phase 2 through Phase 3 execution.
Japan
PMDA regulatory harmonization initiatives reduce multi-regional trial friction for sponsors expanding Asia-Pacific enrollment. The ministry's priority review designation compresses assessment timelines for NASH therapies demonstrating substantial improvement over available therapy. Tokyo and Osaka metabolic disease specialist sites leverage MRI-PDFF platforms to reduce screen failure rates in fibrosis cohort assembly.
South Korea
MFDS accelerated approval pathways for breakthrough therapies reshape trial design complexity for sponsors targeting underserved patient populations. The regulator's evolving acceptance of non-invasive biomarkers as alternatives to liver biopsy influences endpoint selection. Seoul-based academic medical centers anchor investigator expertise for combination therapy protocols requiring intensive biomarker validation.
Non-Alcoholic Steatohepatitis Clinical Trials Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered competitive structure. Large-cap biopharmaceutical sponsors dominate Phase 3 registrational programs through extensive site networks and established hepatology investigator relationships. Mid-cap sponsors concentrate on Phase 2 dose-ranging studies with intensive biomarker validation requirements. Contract research organizations and laboratory services providers compete for central laboratory and imaging core facility contracts. Dominant competitive moves include strategic site network expansion and adaptive platform technology licensing.
Among large-cap biopharmaceutical developers, Pfizer Inc., Novartis AG, and Gilead Sciences Inc. occupy positions within the channel-controlling tier. Pfizer exemplifies global site network deployment for enrollment acceleration. Novartis anchors combination therapy development through deep R&D investment. Gilead represents extensive hepatology trial infrastructure across academic medical centers. These three entities sit within the sponsor archetype that shapes competitive dynamics for investigative site access and principal investigator recruitment.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Icon Plc |
| Laboratory Corporation of America |
| AbbVie Inc. |
| Gilead Sciences Inc. |
| Novo Nordisk |
| Eli Lilly |
| Intercept Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Contract research organization concentration in the United States and Western Europe anchors margin capture downstream at sponsor procurement desks, where adaptive trial platform licensing fees and biomarker laboratory services command premium pricing against standardized site management contracts.
Pricing Analysis
Cost-plus contracts with consumer price indexation dominate investigator site agreements, where academic medical centers negotiate pass-through costs for liver biopsy procedures and MRI-PDFF imaging. Price differentiation rests on fibrosis-staging expertise certification and geographic site density. Cost compression in standardized site services is intensifying because decentralized trial technology vendors compete on platform licensing. Small-cap biopharmaceutical sponsors exhibit highest price sensitivity; large-cap sponsors with established hepatology networks demonstrate lowest.
Supply Chain Analysis
Laboratory Corporation of America, Icon Plc, and PPD hold central laboratory and imaging core facility capacity across the United States, Germany, and United Kingdom. The supply chain draws from specialized biomarker assay reagents, MRI-PDFF software licenses, and liver histopathology slide digitization equipment. Single-source vulnerability concentrates in proprietary non-invasive biomarker algorithm providers. Distribution runs through sponsor-direct contracting with preferred site networks rather than wholesale channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive trial platform interoperability is restructuring competitive economics around ecosystem control, as sponsors that integrate decentralized monitoring, biomarker laboratories, and imaging adjudication into unified workflows capture procurement preference.
For Market Incumbents: Harden site network exclusivity through long-term investigator affiliation agreements at Boston, San Francisco, and Houston academic medical centers. Lock in MRI-PDFF platform partnerships to preempt competitor access. Vertical integration into biomarker laboratory services defends against mid-cap sponsor disintermediation.
For New Entrants and Emerging Players: Pursue Asia-Pacific site activation partnerships in Japan and South Korea where PMDA and MFDS regulatory harmonization reduces trial friction. Target Phase 2 dose-ranging studies with intensive biomarker validation requirements as the most penetrable segment. Lead with adaptive platform technology licensing as the go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across combination therapy development programs requiring multi-mechanism manufacturing infrastructure. Long-term viability centers on sponsors with demonstrated FDA breakthrough therapy designation capture. Acquisition target archetype: mid-cap biopharmaceutical developers with Phase 2 NASH assets and established hepatology investigator relationships. Watch FDA draft guidance finalization on surrogate endpoints as the inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Platform Licensing | Decentralized technology vendors secure multi-year sponsor contracts spanning biomarker integration and remote monitoring. |
| Investigator Network Expansion | Site activation at Tokyo and Osaka metabolic disease specialist sites reduces Asia-Pacific enrollment timelines. |
| Combination Therapy Pipeline Development | Multi-target protocols exploit mechanistic synergies that monotherapy approaches cannot address in fibrosis progression. |
| Biomarker Laboratory Acquisition | Central laboratory capacity captures recurring revenue from longitudinal sample processing across Phase 2 and Phase 3 protocols. |
| Regulatory Consultancy Partnership | EMA PRIME eligibility and FDA breakthrough therapy designation expertise compresses development timelines for sponsor clients. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, principal investigators at academic medical centers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up enrollment projections and top-down sponsor R&D expenditure analysis were triangulated.
Forecast inputs considered trial phase segmentation, intervention type, study design architecture, patient demographic clustering, and regional regulatory pathway differentiation across the projection horizon. CAGRs were derived from enrollment velocity modeling and sponsor pipeline investment trajectories. Industry-specific inputs included FDA breakthrough therapy designation capture rates and EMA PRIME eligibility assessment timelines.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical R&D expenditure cycles and regulatory review staffing levels would shift the trajectory. Forecasts reflect assumptions about continued histologic endpoint requirements and biomarker validation progress. Quarterly review of FDA guidance finalization and EMA benefit-risk standard evolution is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
HIV Clinical Trials Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
Clinical Data Analytics Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market