
 HIV Clinical Trials Market | 2026-2036
HIV Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
HIV Clinical Trials Market Intelligence
Market Context
Phase III long-acting injectable standards are redrawing competitive benchmarks across the HIV clinical trials landscape. Gilead Sciences leverages its nucleoside reverse transcriptase inhibitor portfolio to anchor large-scale randomized controlled programs across multiple continents. ViiV Healthcare specializes in integrase strand transfer inhibitor development and sustains one of the industry's deepest long-acting formulation pipelines. IQVIA Inc. dominates clinical trial execution services and controls site networks that compress patient recruitment timelines for complex infectious disease protocols.
Technical Definition and Structural Segments
HIV clinical trials constitute regulated research protocols evaluating safety, efficacy, and pharmacokinetic profiles of therapeutic or preventive interventions against human immunodeficiency virus, typically requiring viral load suppression below 50 copies per milliliter as a primary functional endpoint. These studies generate evidence for regulatory submission, reimbursement negotiation, and treatment guideline revision across public and private health systems. Phase III studies represent the largest value pool given their extended duration, substantial patient counts, and pivotal role in marketing authorization decisions. Antiretroviral therapy areas command dominant trial volume, while preventive vaccine segments attract concentrated government grant funding despite higher technical risk profiles.
Regulatory Framework
FDA's breakthrough therapy designation and EMA's priority medicines scheme both accelerate HIV trial timelines by enabling rolling review and enhanced agency dialogue. WHO prequalification standards shape demand in low- and middle-income countries by determining procurement eligibility for donor-funded programs. Stakeholders must monitor evolving endpoint harmonization between FDA, EMA, and national regulators in high-burden African markets to avoid protocol fragmentation and redundant study designs.
Market Dynamics
Long-acting injectable antiretroviral formulations are compressing dosing intervals from daily pills to monthly or quarterly administration, forcing trial sponsors to redesign efficacy endpoints and patient retention protocols around extended pharmacokinetic monitoring windows.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Rolling review protocols compress regulatory submission timelines for novel HIV therapies, enabling earlier patient access in high-burden US markets.
- Community-based trial sites:Decentralized recruitment networks in South Africa and Brazil reduce patient dropout rates through localized retention support and transportation subsidies.
- Lenacapavir mechanism expansion:First-in-class capsid inhibitor technology opens new target classes for treatment-experienced patients with multidrug resistance.
Market Restraints
- Cold chain distribution requirements:Long-acting injectable formulations demand uninterrupted -20°C to -80°C storage, constraining trial expansion into rural African sites with unreliable power infrastructure.
- Investigator site concentration:Top-tier infectious disease centers in the United States, South Africa, and Brazil control access to treatment-experienced patient pools, creating enrollment bottlenecks.
- PrEP substitution dynamics:Oral tenofovir-emtricitabine generics at sub-dollar daily costs undermine willingness-to-pay assessments for injectable prevention candidates in donor-funded programs.
Strategic Opportunities
- Pediatric formulation gaps:Weight-band dosing studies for adolescents remain underenrolled, creating first-mover advantage for sponsors with palatable dispersible tablet technologies.
- EMA Priority Medicines scheme:Accelerated assessment pathways for HIV therapies reduce time-to-market in European reimbursement negotiations.
- Real-world evidence integration:Hybrid trial designs combining randomized controlled data with electronic health record extraction from Brazil's unified health system compress confirmatory study costs.
Industry Challenges
- Virology assay standardization:Discordant viral load thresholds between central laboratories and point-of-care platforms in South African township sites generate endpoint adjudication disputes.
- Community advisory board alignment:Competing stakeholder expectations between activist networks in the United States and national ethics committees in Brazil delay protocol amendment approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIV Clinical Trials Market |
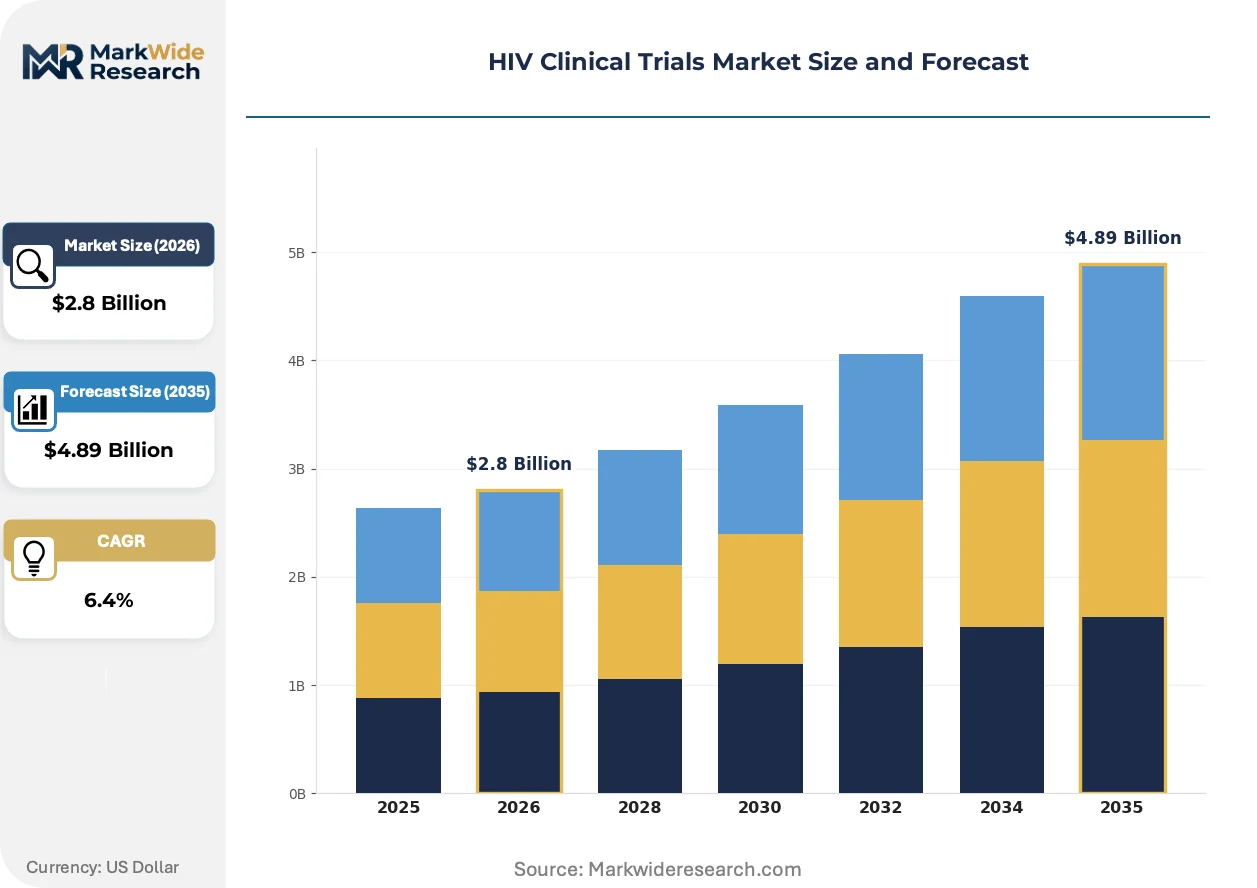
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Study Phase: Phase I, Phase II, Phase III, Phase IV Therapy Area: Antiretrovirals, Immune Modulators, Vaccines, Preventive Therapies Study Design: Randomized Controlled Trials, Observational Studies, Open-Label Studies, Cross-Sectional Studies Funding Source: Government Grants, Pharmaceutical Companies, Non-Profits, Academic Institutions |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Johnson & Johnson, Merck & Co., IQVIA Inc., Parexel International Corporation, GSK plc, AbbVie Inc., Syneos Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIV Clinical Trials Market Strategic Shifts & Innovations
Digital biomarker capture and decentralized trial execution are displacing site-centric monitoring models, enabling continuous pharmacokinetic sampling through wearable devices while reducing geographic barriers to patient participation.
Implantable antiretroviral delivery systems are miniaturizing drug-eluting rod geometries from matchstick-scale to sub-dermal micro-implants. Investigators in the United States and European Union are adopting these platforms for six-month dosing extension studies. This technology is miniaturizing surgical insertion requirements and expanding candidacy to patients with needle phobia or injection site reactions.
WHO prequalification standards are tightening stability data requirements for heat-sensitive biologics, forcing reformulation investments in lipid nanoparticle encapsulation. Manufacturers targeting procurement eligibility in low- and middle-income countries must now submit 36-month accelerated degradation studies. African national regulatory authorities are responding by harmonizing inspection protocols with WHO benchmarks to avoid duplicate facility audits.
Direct-to-patient shipment models are disrupting traditional site-based drug dispensing for stable maintenance-phase participants. Courier networks in Brazil's metropolitan corridors now handle temperature-controlled antiretroviral delivery to home addresses, displacing monthly clinic visits. This channel shift concentrates in São Paulo and Rio de Janeiro state health systems where pharmacy benefit managers have integrated logistics platforms.
HIV Clinical Trials Market Segmentation
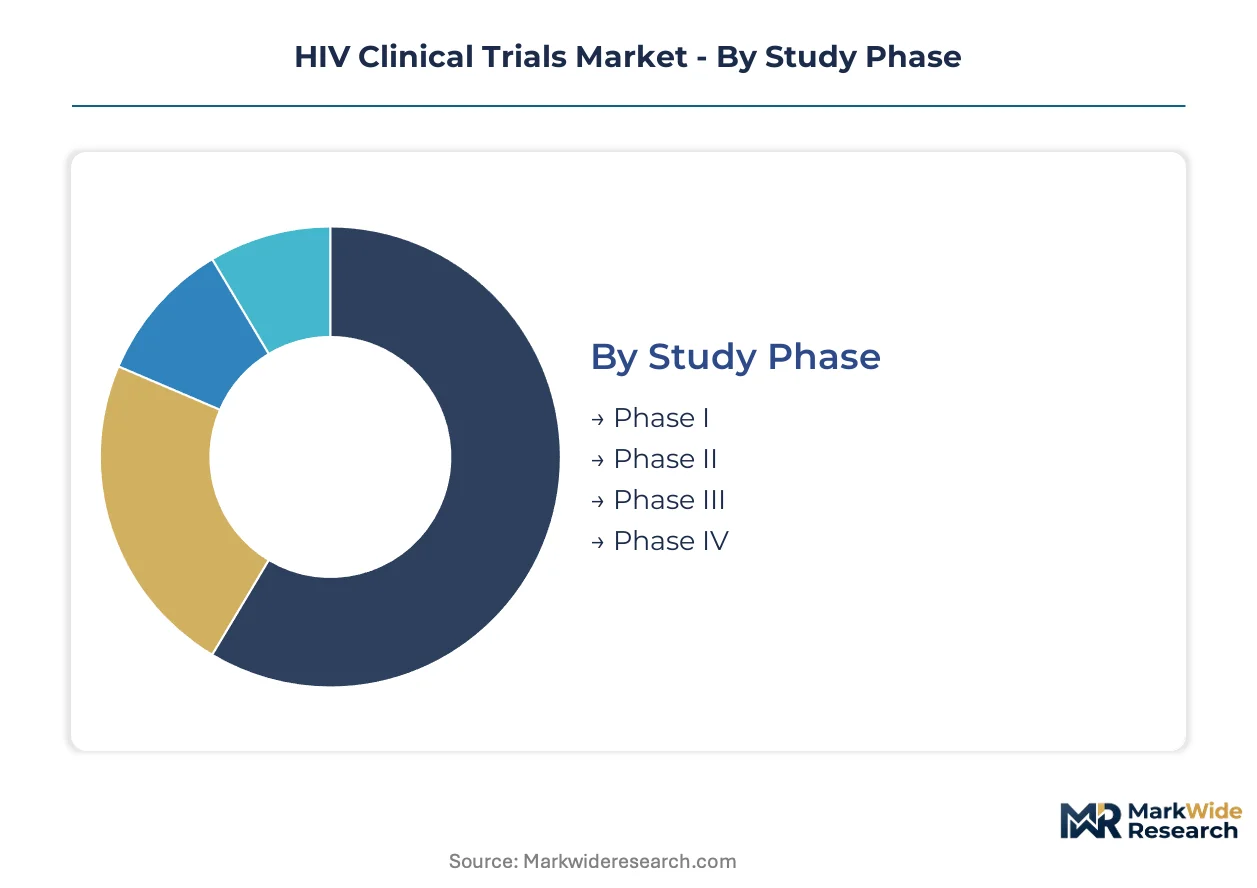
Study phase distribution determines capital allocation intensity and regulatory engagement cadence across HIV clinical trials. Therapy area segmentation reveals divergent risk-return profiles between established antiretroviral development and higher-uncertainty vaccine platforms.
Study Phase:
FDA breakthrough therapy designation and EMA priority medicines scheme compress timelines most dramatically for Phase II and Phase III protocols, while Phase I and Phase IV operate under standard assessment windows.
- Phase III:Pivotal efficacy studies enrolling hundreds to thousands of participants establish viral suppression benchmarks for marketing authorization. Demand concentrates in the United States, South Africa, and Brazil where treatment-experienced patient pools and established site infrastructure align. Phase III commands dominant capital allocation due to extended duration and regulatory consequence.
- Phase I:First-in-human safety and pharmacokinetic assessments establish dosing ranges for novel mechanisms like capsid inhibitors. Healthy volunteer recruitment in the United States and European Union proceeds through specialized phase I units with rapid turnaround capabilities. Phase I expansion accelerates as sponsors pursue multiple long-acting formulation candidates simultaneously.
- Phase II:Proof-of-concept efficacy studies in small HIV-positive cohorts refine dosing regimens before pivotal trials.
- Phase IV:Post-marketing surveillance studies track long-term safety and real-world effectiveness across diverse populations.
Established volume favors Phase III; emerging adoption favors Phase I as novel mechanism classes multiply.
Therapy Area:
Cost tier stratification separates premium-priced long-acting injectables from generic oral maintenance therapies, reshaping sponsor investment priorities and trial design complexity.
- Antiretrovirals:Nucleoside reverse transcriptase inhibitors, integrase strand transfer inhibitors, and protease inhibitors constitute the functional backbone of HIV treatment. Development concentrates on long-acting injectable and implantable formulations that extend dosing intervals from daily to monthly or quarterly administration. Antiretroviral trials generate the largest patient enrollment volumes and most extensive site network utilization.
- Vaccines:Preventive immunization candidates targeting HIV envelope proteins attract concentrated government grant funding despite repeated efficacy disappointments. NIH and Bill & Melinda Gates Foundation backing sustains early-phase programs in the United States and sub-Saharan Africa where incidence rates justify large-scale efficacy trial investment. Vaccine development carries the highest technical risk profile among therapy areas.
- Immune Modulators:Therapeutic vaccines and immune checkpoint approaches aim to achieve functional cure through reservoir reduction.
- Preventive Therapies:Pre-exposure prophylaxis candidates compete against established oral tenofovir-emtricitabine regimens in willingness-to-pay assessments.
Revenue concentration favors antiretrovirals; pipeline expansion favors preventive therapies as long-acting PrEP formulations advance.
Study Design:
Application requirements vary sharply between registration-enabling randomized controlled trials and real-world evidence generation protocols, driving divergent site capability investments.
- Randomized Controlled Trials:Double-blind, placebo-controlled or active-comparator studies provide the evidentiary foundation for FDA and EMA marketing authorization decisions. Viral load suppression below 50 copies per milliliter serves as the primary functional endpoint across all major regulatory jurisdictions. Randomized controlled trials demand the most intensive monitoring infrastructure and longest patient retention protocols.
- Observational Studies:Non-interventional cohort analyses extract treatment patterns and outcomes from electronic health records and registry databases. Brazil's unified health system enables particularly efficient retrospective data aggregation for comparative effectiveness research. Observational study growth reflects payer pressure for real-world evidence to support reimbursement negotiations.
- Open-Label Studies:Single-arm or unblinded protocols assess long-term safety and patient-reported outcomes in treatment-experienced populations.
- Cross-Sectional Studies:Single-timepoint prevalence assessments support epidemiological characterization and healthcare resource planning.
Regulatory submission requirements favor randomized controlled trials; cost compression favors observational studies as hybrid designs gain acceptance.
Funding Source:
Customer type segmentation separates commercial sponsors pursuing proprietary assets from public funders prioritizing access and equity objectives across geographic markets.
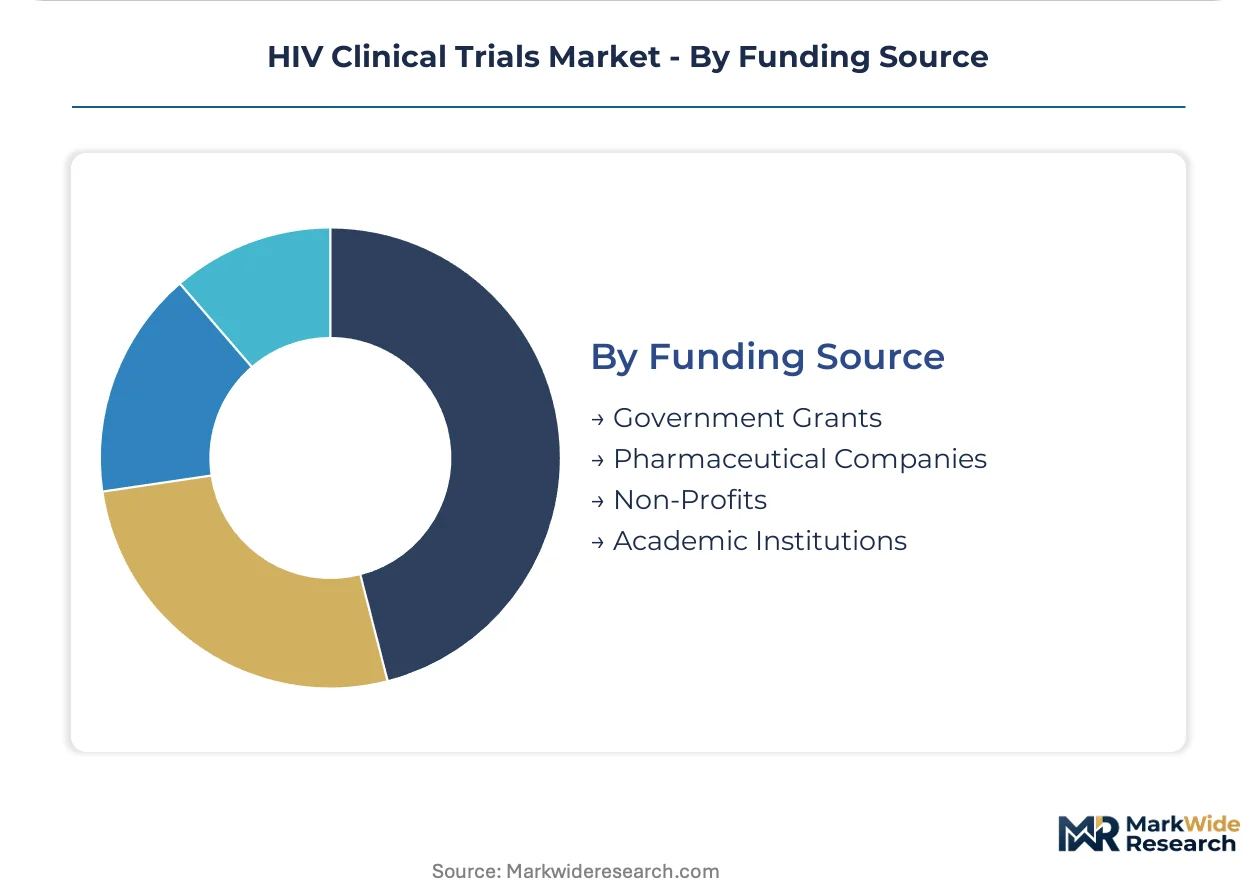
- Pharmaceutical Companies:Biopharmaceutical sponsors including Gilead Sciences and ViiV Healthcare deploy internal R&D budgets toward Phase III programs for long-acting formulations with blockbuster revenue potential. Commercial investment concentrates on treatment-experienced and maintenance populations in high-income markets with favorable reimbursement. Pharmaceutical funding drives the majority of late-stage trial execution.
- Government Grants:NIH, European Commission Horizon programs, and national research councils sustain early-phase vaccine and cure-directed research with limited near-term commercial viability. Government funding prioritizes sites in South Africa, Kenya, and Thailand where epidemic burden and research infrastructure align. Grant funding maintains essential capacity for high-risk, high-impact science outside proprietary development paths.
- Non-Profits:Foundation and philanthropic backing fills gaps in pediatric formulation development and implementation science.
- Academic Institutions:University-affiliated investigators lead mechanistic studies and biomarker discovery with limited commercial sponsorship.
Capital scale favors pharmaceutical companies; mission alignment favors government grants for vaccine and cure-directed platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Donor-funded programs in sub-Saharan Africa exhibit extreme price elasticity for preventive therapies, while private payers in the United States absorb premium pricing for long-acting formulations with minimal volume response.
United States
FDA breakthrough therapy designation accelerates rolling review timelines for novel antiretroviral mechanisms. NIH grant funding sustains early-phase vaccine programs at academic medical centers in Boston and Bethesda. The Research Triangle Park corridor in North Carolina anchors contract research organization concentration for infectious disease protocol execution.
South Africa
Community-based trial sites in Gauteng and KwaZulu-Natal reduce patient dropout through localized retention support. The national health department aligns regulatory inspection protocols with WHO prequalification benchmarks. Cape Town's clinical research infrastructure supports multinational Phase III programs for treatment-experienced cohorts.
Brazil
ANVISA harmonizes endpoint standards with FDA and EMA to prevent protocol fragmentation. The unified health system enables efficient real-world evidence extraction from electronic health records. São Paulo state health systems integrate courier networks for direct-to-patient antiretroviral delivery in metropolitan corridors.
United Kingdom
EMA priority medicines scheme reduces time-to-market for HIV therapies entering European reimbursement negotiations. The Medical Research Council sustains academic investigator-led programs for cure-directed research. London's Imperial College and University College Hospital cluster anchors Phase I/II execution for novel mechanisms.
India
CDSCO streamlined approval pathways attract contract manufacturing organizations for active pharmaceutical ingredient supply. Generic oral tenofovir-emtricitabine production at sub-dollar daily costs constrains willingness-to-pay for injectable prevention candidates. Hyderabad and Mumbai pharmaceutical corridors concentrate formulation development capabilities for dispersible pediatric dosing technologies.
HIV Clinical Trials Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the HIV clinical trials landscape. Large-cap biopharmaceutical sponsors command proprietary antiretroviral portfolios and internal Phase III execution capabilities. Mid-tier contract research organizations compete on site network density and patient recruitment velocity in high-burden infectious disease markets. Strategic moves concentrate on long-acting formulation partnerships and decentralized trial platform licensing.
Among vertically integrated biopharmaceutical developers, Gilead Sciences and ViiV Healthcare exemplify archetypes with deep nucleoside reverse transcriptase inhibitor and integrase strand transfer inhibitor portfolios respectively. IQVIA Inc. occupies a position representing site network scale advantages for complex infectious disease protocols. These three entities anchor distinct competitive vectors: proprietary asset development, mechanism class specialization, and clinical execution infrastructure.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Johnson & Johnson |
| Merck & Co. |
| IQVIA Inc. |
| Parexel International Corporation |
| GSK plc |
| AbbVie Inc. |
| Syneos Health |
| Others |
Cost & Logistics Intelligence
WHO prequalification standards gate both supplier eligibility and price tiering in HIV clinical trials, compressing margins for manufacturers lacking 36-month stability data while enabling premium positioning for sponsors with accelerated regulatory pathways. Cold chain compliance costs and site certification requirements stratify contract research organization pricing across United States, South African, and Brazilian markets.
Pricing Analysis
Post-trial data licensing and real-world evidence subscriptions generate recurring revenue that offsets upfront protocol execution costs. Three-tier pricing structure across premium, standard, and economy levels separates full-service Phase III management from modular site support and standalone regulatory consulting. Cost compression in donor-funded African markets intensifies as oral tenofovir-emtricitabine generics approach sub-dollar daily costs. Government grant recipients exhibit extreme price sensitivity; private biopharmaceutical sponsors absorb premium long-acting formulation trial costs with minimal volume response.
Supply Chain Analysis
Strategic stockpiling of -80°C cold chain capacity dominates sponsor preferences over just-in-time logistics for long-acting injectable stability requirements. Active pharmaceutical ingredient production concentrates in India, China, and the United States, with Hyderabad and Mumbai corridors anchoring dispersible pediatric formulation capabilities. Lipid nanoparticle encapsulation materials and viral load assay reagents constitute critical input dependencies. Single-source vulnerability in specialized central laboratory networks threatens endpoint adjudication timelines. Distribution runs through courier-integrated pharmacy benefit managers in São Paulo and Rio de Janeiro metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA breakthrough therapy designation and EMA priority medicines scheme compress development timelines, creating a high-growth disruption window for sponsors with novel capsid inhibitor and long-acting formulation platforms.
For Market Incumbents: Secure exclusive site network partnerships in Gauteng and KwaZulu-Natal to lock out competitor access to treatment-experienced patient pools. Deepen backward integration into cold chain logistics capabilities to neutralize rural African infrastructure gaps as a competitive wedge for mid-tier contract research organizations. For New Entrants and Emerging Players: Decentralized trial execution technology gaps in community-based South African township sites offer white-space entry points where incumbents under-serve localized retention support needs. Target Brazil's unified health system real-world evidence extraction services as the most penetrable segment, leveraging existing courier network infrastructure for direct-to-patient delivery integration. For Investors and Strategic Acquirers: EMA priority medicines scheme acceleration reshapes the acquisition landscape toward European-registered assets with compressed time-to-market profiles. Long-term viability over the five-to-ten year horizon favors contract research organizations with validated infectious disease site networks over standalone technology platform plays. Watch FDA rolling review acceptance rates for novel mechanism classes as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Partnership | ViiV Healthcare's integrase strand transfer inhibitor pipeline validates quarterly dosing extension as a revenue driver. |
| Decentralized Trial Platform Licensing | IQVIA's site network compression capabilities reduce patient recruitment timelines for complex infectious disease protocols. |
| Real-World Evidence Integration | Brazil's unified health system enables hybrid trial designs that slash confirmatory study costs for maintenance populations. |
| Pediatric Formulation Development | Weight-band dosing studies for adolescents remain underenrolled, creating first-mover advantage for palatable dispersible technologies. |
| WHO Prequalification Alignment | African national regulatory authorities harmonizing inspection protocols with WHO benchmarks eliminate duplicate facility audit burdens. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient enrollment modeling and top-down sponsor budget allocation analysis were triangulated to reconcile volume and value estimates.
Variance decomposition across study phase, therapy area, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory blending across the modeling period. Forecast inputs incorporated viral load suppression endpoint standardization trends and long-acting formulation adoption curves in treatment-experienced populations.
Forecasts assume regulatory continuity in FDA breakthrough therapy designation and EMA priority medicines scheme regimes; material policy shifts would require re-modeling. Revision becomes warranted when WHO prequalification stability requirements or African national regulatory harmonization progress crosses thresholds that alter procurement eligibility timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Clinical Trials Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Clinical Trial Logistics Market
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
US Virtual Clinical Trials Market