
 Healthy Snacks Market | 2026-2036
Healthy Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Healthy Snacks Market Analysis
Plant-based proteins are decoupling healthy snacks from traditional dairy and soy dependencies, reducing input cost volatility for manufacturers. Nestlé S.A. leverages its global R&D network to accelerate clean-label reformulations across multiple categories. PepsiCo, Inc. sustains category leadership through direct-to-retail distribution control in North American convenience channels. Mondelēz International differentiates via premium dark chocolate and nut-based portfolios targeting European and Latin American palates.
Healthy snacks comprise minimally processed, nutrient-dense food products formulated with whole grains, legumes, seeds, fruits, or vegetables, typically containing fewer than 200 calories per serving with controlled sodium and added sugar levels, designed for between-meal consumption without compromising dietary goals. The organic ingredient segment anchors premium pricing power as consumers prioritize pesticide-free sourcing and non-GMO verification. Gluten-free formulations occupy a maturing but defensible niche among celiac and wellness-oriented buyers. Resealable pouch packaging leads format innovation by extending shelf stability and supporting on-the-go consumption patterns among working adults and student populations.
FDA nutrition labeling mandates and USDA organic certification requirements shape formulation transparency and supply chain documentation burdens for domestic producers. The EU Green Deal's Farm to Fork strategy and EFSA health claim regulations influence export-oriented manufacturers reformulating for transatlantic market access. Stakeholders must monitor evolving front-of-package warning systems in multiple jurisdictions and calibrate portfolio mixes between indulgence-positioned and function-positioned sub-brands before regulatory thresholds tighten further.
Market Dynamics
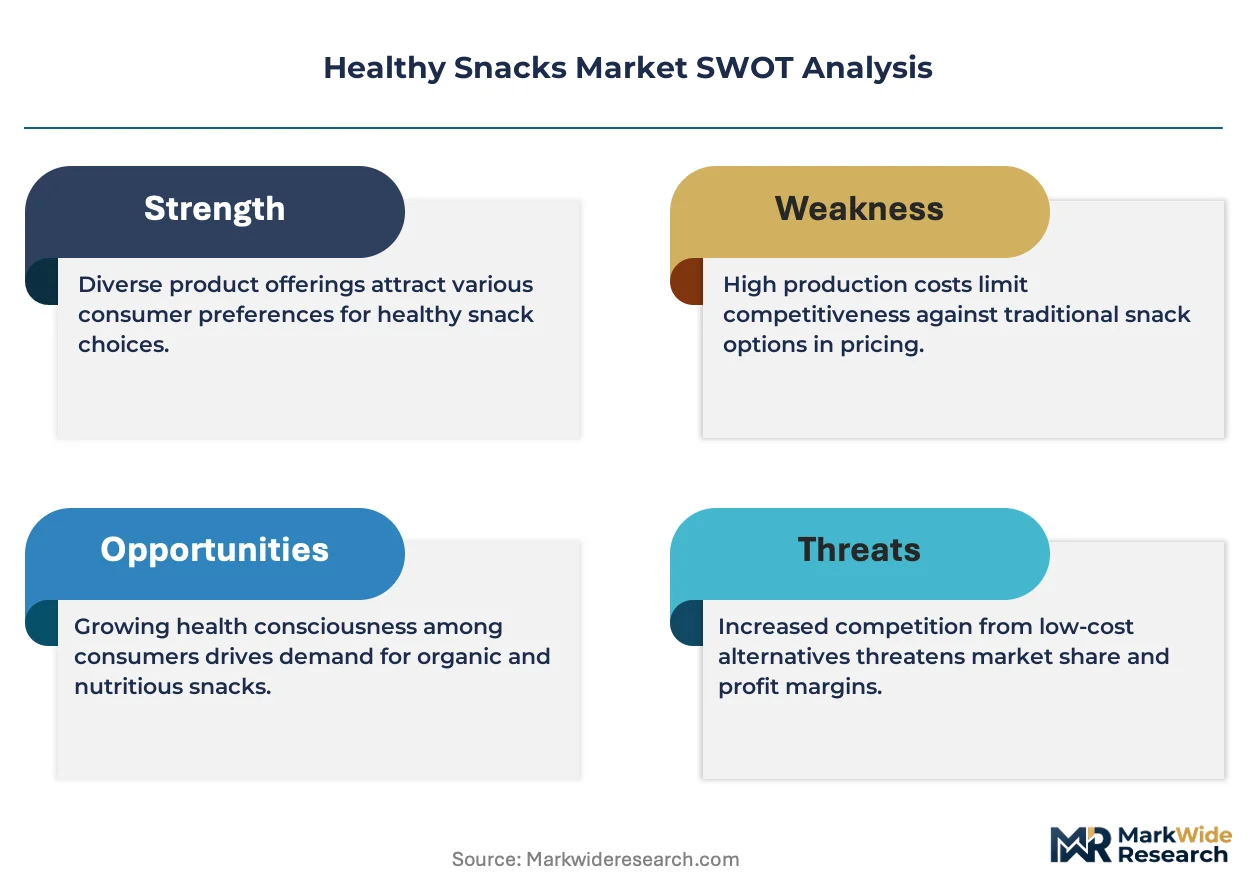
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to rebuild supply chains around whole-food ingredients while eliminating artificial preservatives, creating a structural cost premium that smaller brands struggle to absorb.
Growth Catalysts
- Portable nutrition demand:Corporate millennials in urban centers sustain between-meal consumption through resealable formats designed for desk-based and transit-oriented eating patterns.
- FDA Nutrition Facts modernization:Updated labeling requirements for added sugars and serving sizes push manufacturers toward transparent formulation, accelerating consumer trust in verified low-sodium and low-sugar claims.
- Plant-protein processing advances:Novel extrusion technologies for pea and fava protein concentrates reduce dependency on dairy and soy inputs, insulating margins from commodity volatility.
Market Restraints
- Organic input cost volatility:Pesticide-free grain and nut sourcing faces weather-driven yield fluctuations that compress gross margins for premium-positioned SKUs.
- Supply concentration in North American packaging:Domestic flexible-film converter capacity constraints create lead-time bottlenecks for resealable pouch innovations.
- Clean-label shelf-life trade-offs:Elimination of synthetic preservatives limits distribution radius for refrigerated and ambient-stable formats without cold-chain investment.
Strategic Opportunities
- EU Green Deal Farm to Fork alignment:Export-oriented manufacturers capturing organic certification equivalence can access premium European retail placement ahead of 2030 sustainability targets.
- Functional ingredient convergence:Probiotic and adaptogenic integration into savory formats opens white space beyond traditional sweet-snack functionalization.
- Direct-to-retail convenience channel bypass:Warehouse club and e-commerce fulfillment models reduce slotting-fee burdens imposed by traditional grocery distributors.
Industry Challenges
- Reformulation talent scarcity:Food scientists skilled in natural preservation and texture optimization without synthetic additives command premium compensation, constraining R&D throughput.
- Dual certification timelines:Simultaneous USDA Organic and Non-GMO Project verification processes extend product-launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthy Snacks Market |
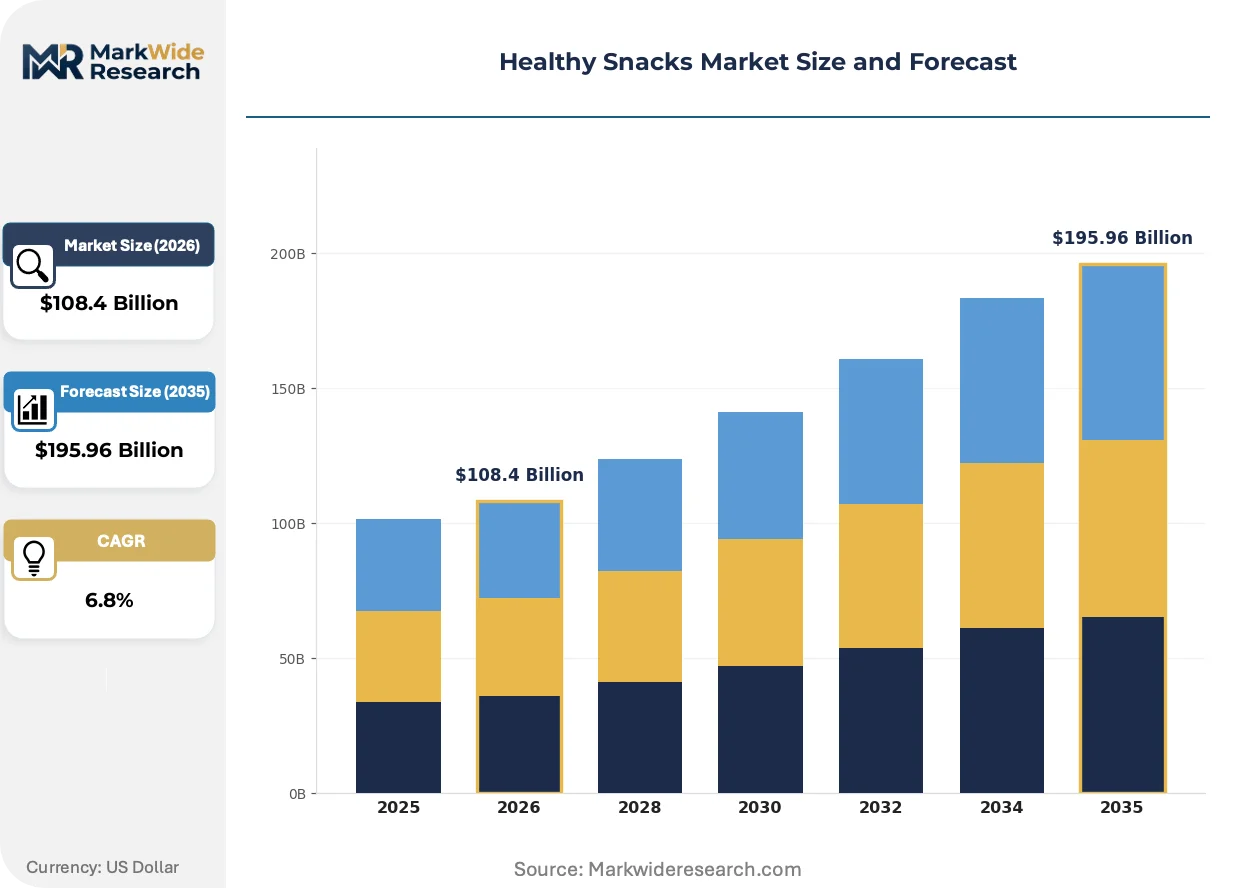
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $195.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Dried Fruits, Nuts, Vegetables Ingredient Type: Organic, Gluten-Free, Low-Calorie, No Added Sugar End User: Children, Adults, Diabetics, Athletes Packaging Type: Pouches, Boxes, Cans, Resealable Bags |
| Companies Covered | Nestlé S.A., PepsiCo, Inc., Mondelēz International, Kellanov (The Kellogg Company), Unilever plc, Danone S.A., General Mills, Hormel Foods Corporation, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthy Snacks Market Emerging Trajectories
High-pressure processing and precision fermentation are reshaping how manufacturers deliver shelf-stable nutrition without synthetic additives, while front-of-package warning systems in multiple jurisdictions force portfolio restructuring.
High-pressure processing technology is automating pathogen reduction in raw nut and vegetable-based snacks without thermal degradation of heat-sensitive vitamins. Mid-size manufacturers in California and Texas are adopting HPP lines at twice the 2019 rate to support clean-label positioning. This automation is compressing the competitive gap between artisanal startups and scaled producers by standardizing safety outcomes without capital-intensive aseptic packaging investments.
The EU Green Deal's Farm to Fork strategy is mandating 25% organic agriculture land use by 2030, tightening import documentation requirements for non-EU snack ingredients. European manufacturers reformulating for transatlantic access must now trace pesticide residues through tier-2 suppliers. Dark chocolate and nut-based portfolios targeting German and French retail face accelerated reformulation timelines to maintain shelf placement under EFSA health claim scrutiny.
Corporate procurement departments are consolidating snack vending and pantry contracts through national foodservice distributors, displacing fragmented local supplier relationships. This concentration favors manufacturers with SQF or BRC certification and direct distribution infrastructure. The shift is most visible in United States tech corridor campuses where facilities managers prioritize single-source accountability over product variety.
Healthy Snacks Market Segmentation
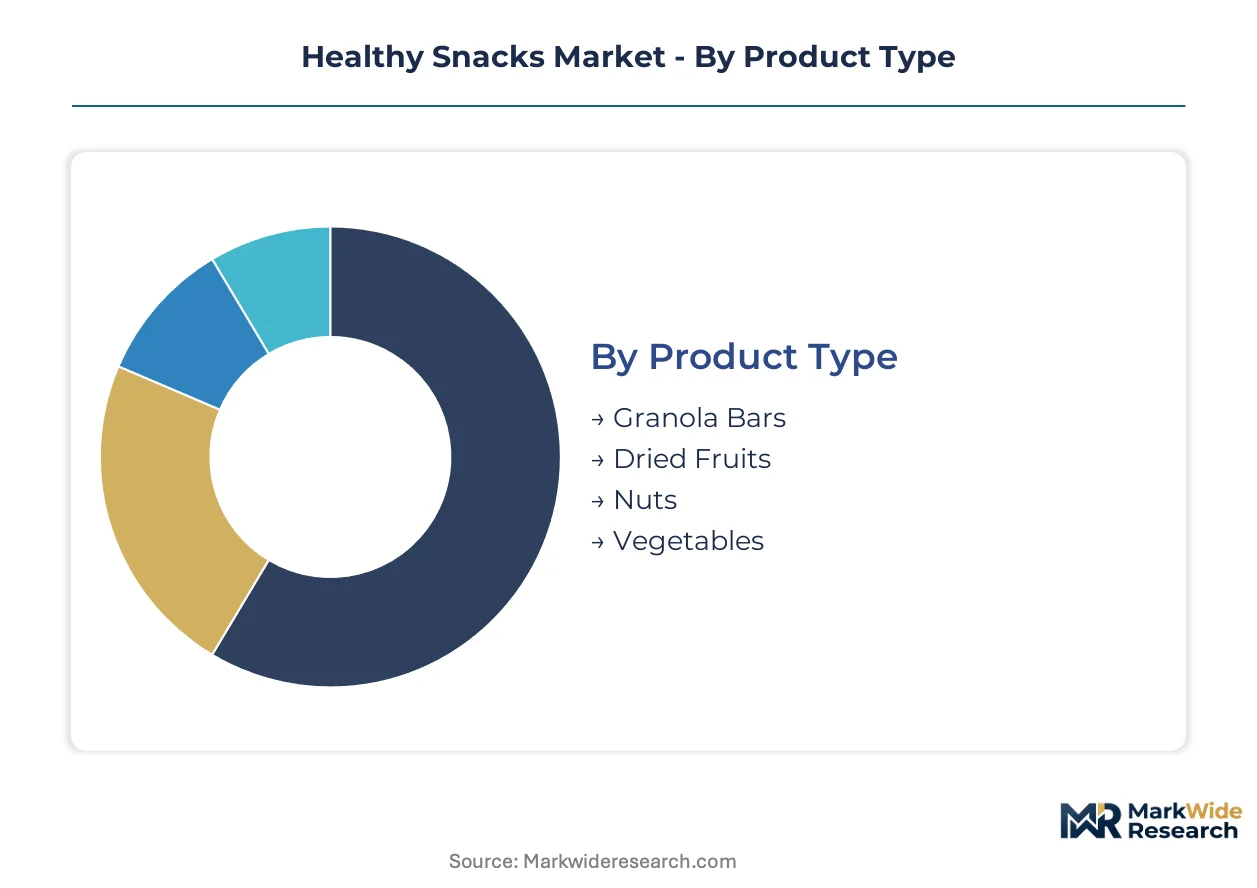
Healthy snack purchasing decisions cascade through ingredient preferences, dietary restrictions, consumption occasions, and format requirements. Manufacturers must align R&D investment and packaging innovation across these intersecting dimensions to capture premium placement in fragmented retail channels.
Product Type:
Consumers select formats based on satiety expectations and eating context rather than nutritional content alone.
- Granola Bars:Baked or cold-pressed oat and grain matrices with binding syrups or nut butters, typically 150-200 calories per serving. Demand concentrates in United States corporate pantries where desk-based eating favors single-hand consumption without crumb dispersion.
- Dried Fruits:Dehydrated whole fruits or fruit leathers with no added sweeteners, preserving fiber and micronutrient density. European procurement contracts for school feeding programs are driving sulfate-free and unsulfured apricot and mango specifications.
- Nuts:Raw, dry-roasted, or seasoned tree nuts and legumes delivering protein and healthy fat profiles.
- Vegetables:Dehydrated, baked, or air-fried root and leafy vegetable chips and crisps.
Granola bars lead on scale; vegetable-based formats lead on momentum.
Ingredient Type:
Certification premiums separate price tiers more sharply than functional differences in base formulations.
- Organic:USDA or EU organic certified ingredients grown without synthetic pesticides or GMOs, requiring full supply chain traceability. United States natural channel retailers command 25-40% shelf price premiums over conventional equivalents, justifying the dual certification investment for scaled manufacturers.
- Gluten-Free:Formulations excluding wheat, barley, and rye with cross-contamination controls below 20 ppm. Celiac disease prevalence in Germany and diagnostic rates in United Kingdom are expanding the addressable population beyond lifestyle choosers.
- Low-Calorie:Portion-controlled products engineered below 100 calories per serving through bulk density reduction.
- No Added Sugar:Sweetness derived exclusively from fruit concentrates, monk fruit, or allulose without refined sucrose or corn syrup.
Organic commands the highest absolute margin per unit; no added sugar is expanding most quickly.
End User:
Life stage and physiological condition dictate nutrient density requirements and portion architecture.
- Children:Age-appropriate portion sizes with choking-resistant textures and school-compliant allergen exclusions. United States K-12 school nutrition standards are reshaping permissible sodium and sugar thresholds for vending and cafeteria placement.
- Adults:General population targeting satiety management and between-meal energy without meal replacement positioning. Office-based consumption in United States tech corridors favors resealable formats supporting intermittent grazing.
- Diabetics:Glycemic index-controlled formulations with documented glucose response data for medical nutrition therapy.
- Athletes:Macronutrient ratios optimized for pre-workout energy or post-exercise recovery with protein content above 10g per serving.
Adult targeting dominates absolute volume; diabetic-positioned products show steepest expansion trajectory.
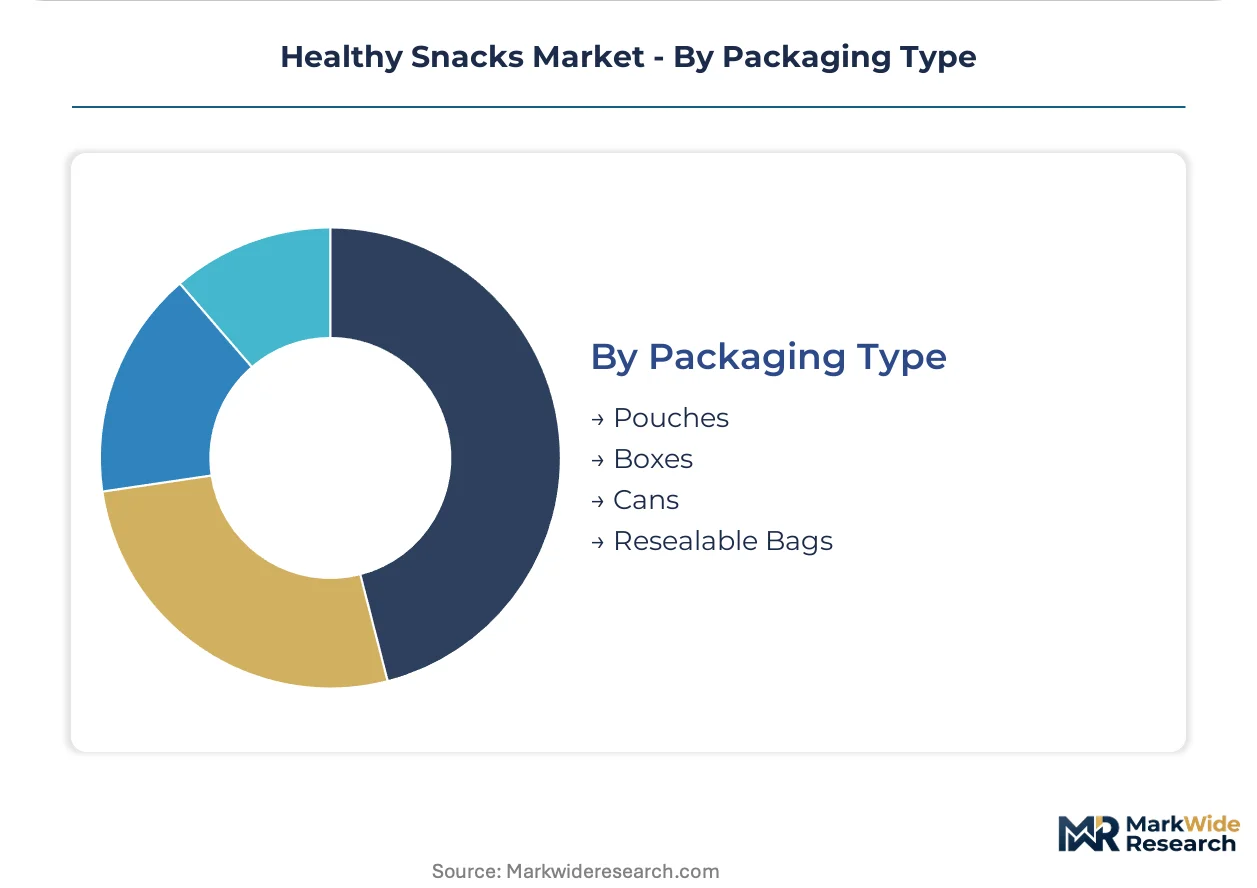
Packaging Type:
Format selection determines shelf stability, portion control, and channel access simultaneously.
- Pouches:Flexible laminated films with high barrier properties against oxygen and moisture ingress, supporting ambient distribution. Japanese convenience store chains specify stand-up pouch configurations with tear-notch ergonomics for single-handed opening.
- Boxes:Paperboard cartons containing multiple single-serve units for pantry stock-up purchasing. Warehouse club formats in United States favor 12-24 count boxes reducing per-unit packaging cost and supporting bulk price positioning.
- Cans:Rigid metal or composite containers for nut and trail mix assortments requiring crush resistance.
- Resealable Bags:Zipper or press-to-close mechanisms extending consumption windows across multiple days.
Pouches capture the highest production volume; resealable bags deliver the strongest velocity per SKU.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate campuses in the United States anchor healthy snack innovation, with FDA labeling mandates and resealable pouch adoption spreading outward to manufacturing clusters in Germany, China, Brazil, and Japan.
United States
Tech corridor facilities managers in Austin, Seattle, and San Francisco consolidate vending contracts through national distributors, favoring SQF-certified manufacturers with direct distribution infrastructure. FDA Nutrition Facts modernization drives transparent formulation investments. California's Central Valley processes organic nut and dried fruit inputs for premium snack brands.
Germany
Diagnostic rates for celiac disease expand gluten-free addressable populations beyond lifestyle consumers into medical nutrition therapy. EFSA health claim scrutiny accelerates reformulation timelines for dark chocolate and nut-based portfolios. Bavarian food technology clusters develop precision fermentation capabilities for clean-label protein concentrates.
China
Urban middle-class consumers in Shanghai and Beijing adopt portable nutrition formats for subway commutes and office grazing. SAMR nutrition labeling requirements tighten added sugar disclosure thresholds. Yangtze River Delta manufacturing hubs scale high-pressure processing lines for ambient-stable vegetable crisps.
Brazil
School feeding program procurement contracts drive sulfate-free dried fruit specifications from domestic processors. ANVISA front-of-package warning systems pressure manufacturers to reduce sodium and added sugar before regulatory thresholds tighten. São Paulo state clusters integrate Amazon-sourced açaí and Brazil nut ingredients into export-oriented formulations.
Japan
Convenience store chains specify stand-up pouch ergonomics for single-handed opening by commuting office workers. METI sustainability guidelines incentivize packaging material reduction and supply chain carbon disclosure. Kanto region R&D facilities pioneer probiotic integration into savory snack formats beyond traditional sweet applications.
Healthy Snacks Market Vendor Landscape
Global majors compete with regional champions across distribution infrastructure and clean-label certification depth, producing a tiered structure where scale advantages in slotting fees clash with agility in organic supply chain sourcing. Three archetypes dominate: multinational CPG conglomerates with direct-to-retail control, mid-size organic specialists with dual certification capabilities, and private-label manufacturers serving warehouse club channels. Competitive intensity concentrates on M&A for organic ingredient sourcing and strategic partnerships for flexible-film packaging capacity.
Within the multinational tier, Nestlé S.A., PepsiCo, Inc., and Mondelēz International exemplify divergent geographic and portfolio strategies. The Swiss-domiciled conglomerate leverages global R&D networks for cross-category reformulation. The New York-based beverage and snack giant sustains North American convenience channel dominance through captive distribution infrastructure. The Illinois-headquartered company targets European and Latin American premium placement through dark chocolate and nut-based positioning.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo, Inc. |
| Mondelēz International |
| Kellanov (The Kellogg Company) |
| Unilever plc |
| Danone S.A. |
| General Mills |
| Hormel Foods Corporation |
| Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Captive sourcing of organic nut and grain inputs anchors both supply security and premium pricing power for scaled manufacturers navigating FDA and USDA certification requirements. This backward integration into California Central Valley and Midwest organic acreage insulates margin structures from commodity volatility while supporting the dual certification timelines that command shelf price premiums in United States natural channel retail.
Pricing Analysis
Organic input cost pass-through determines tiered pricing structures across premium, standard, and economy levels in healthy snack portfolios. Price differentiation rests on USDA Organic and Non-GMO Project certification depth alongside resealable pouch format innovation. Cost compression in mid-tier SKUs is intensifying because domestic flexible-film converter capacity constraints elevate packaging premiums. Corporate procurement departments show lowest price sensitivity for SQF-certified direct-distribution suppliers, while warehouse club buyers demand bulk-format economy positioning.
Supply Chain Analysis
Freight cost elevation from California Central Valley processing hubs to East Coast distribution centers compresses margins for ambient-stable formats lacking cold-chain infrastructure. Supply concentration centers on United States organic grain and nut sourcing, German precision fermentation technology clusters, and Chinese Yangtze River Delta high-pressure processing equipment manufacturing. Raw material dependencies include organic pea protein concentrates, flexible laminated film barriers, and sulfate-free dried fruit inputs. Single-source vulnerability in domestic flexible-film converter capacity creates lead-time bottlenecks for resealable pouch innovations. Distribution runs through national foodservice distributors consolidating corporate campus vending contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA Nutrition Facts modernization and EFSA health claim scrutiny accelerate transparent formulation investments across manufacturer tiers.
For Market Incumbents: Deploy direct-to-retail distribution infrastructure to defend against slotting-fee compression from consolidating national foodservice distributors. Deepen backward integration into organic acreage in California and Midwest growing regions to secure dual certification supply chains. Accelerate clean-label reformulation through captive R&D networks before EFSA front-of-package warning systems tighten further.
For New Entrants and Emerging Players: Enter via probiotic and adaptogenic integration into savory snack formats, a white space beyond traditional sweet functionalization. Target diabetic-positioned products with glycemic index-controlled formulations for medical nutrition therapy channels. Pursue warehouse club e-commerce fulfillment models to bypass grocery distributor slotting-fee structures.
For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification capabilities intersect with constrained organic supply chain access. Long-term viability favors mid-size organic specialists with USDA Organic and Non-GMO Project verification depth over pure-play private-label manufacturers. Watch for inflection where EU Green Deal Farm to Fork import documentation requirements trigger transatlantic reformulation capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FDA and EFSA mandates force synthetic additive elimination across entire SKU portfolios. |
| Backward Integration into Organic Supply | Captive acreage in California Central Valley secures dual certification input security. |
| High-Pressure Processing Scale-Up | California and Texas adoption rates automate pathogen reduction without thermal degradation. |
| Direct-to-Retail Channel Expansion | Corporate campus vending consolidation favors SQF-certified manufacturers with captive distribution. |
| Functional Ingredient Convergence | Probiotic savory format integration opens white space beyond traditional sweet applications. |
Methodological Framework
Direct dialogue with brand managers, category buyers at natural channel retailers, supply planners, and channel sales heads grounded qualitative findings in operational reality. Secondary validation drew from FDA labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and EFSA health claim registers. Bottom-up SKU-level volume builds triangulated against top-down category expenditure models to produce convergent estimates.
Bottom-up segmentation modeling across product type, ingredient certification tier, end-user life stage, and packaging format generated volume and value outputs across the analysis window. CAGRs were derived from trend extrapolation of per-capita consumption intensity, regulatory compliance cost trajectories, and channel shift elasticity parameters. Forecast inputs incorporated organic acreage expansion rates, flexible-film packaging capacity utilization, and corporate procurement contract consolidation velocity.
Inputs from regulatory filing databases and retail scanner panels were available through the study window; gaps in real-time organic commodity price series introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding certification timeline stability and converter capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Cookies Market
Snacks
North America Extruded Snack Food Market
Snacks
Europe Snacks Market
Snacks
Crispy Fruit Chips Market
Snacks
Vegan Snacks Market
Snacks
Better for You Snacks Market
Snacks
North America Baked Savory Snacks Market
Snacks
South America Frozen Snacks Market
Snacks
Europe Nuts and Cereal Snacks Bar Market
Snacks
Protein Crisps Market
Snacks
Spain Energy Bar Market
Snacks
North America Frozen Snacks Market
Snacks
Fat Free Snacks Market
Snacks
Asia Pacific Snack Food Market
Snacks
Cheese Snacks Market
Snacks
No-Fat Peanut Butter Market