
 Asia-Pacific Popcorn Market | 2026-2036
Asia-Pacific Popcorn Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Popcorn Market Insights
A capital-intensity divergence between microwaveable bag manufacturers and artisanal ready-to-eat specialists is reorganizing competitive tiers across the Asia-Pacific Popcorn Market. PepsiCo Inc. leverages its pan-Asian distribution infrastructure to dominate modern trade shelf space in tier-one cities. Intersnack Group GmbH & Co. KG sustains regional production flexibility through localized contract manufacturing partnerships. The Hershey Company anchors premium positioning via controlled chocolate-caramel flavor collaborations with cinema circuits.
Asia-Pacific popcorn comprises Zea mays everta kernels expanded through hot-air or oil-popped thermal processing, typically seasoned and packaged for immediate consumption with moisture content below 5% to preserve crunch integrity. Its primary commercial purpose spans cinema concession supply, retail snack aisles, and food-service portion packs. Caramel popcorn and spicy popcorn command disproportionate margin pools as flavor-innovation leaders, while butter popcorn occupies volume-dominant shelf space across supermarket channels. Online retail represents the fastest-expanding distribution vector, though convenience stores continue to capture impulse-purchase frequency in Japan and South Korea.
FSSAI in India, FSANZ across Australia and New Zealand, and China's SAMR collectively enforce escalating standards around trans-fat disclosure, artificial additive restrictions, and microwaveable bag chemical safety. These frameworks compel manufacturers to reformulate oil blends and migrate toward paper-based or compostable packaging substrates. Stakeholders must monitor regulatory divergence between harmonized ASEAN standards and country-specific additive schedules when configuring regional SKU portfolios.

Market Dynamics
India's FSSAI labeling mandates are forcing rapid reformulation across pre-packaged popcorn portfolios, compressing product development cycles and elevating compliance costs for manufacturers serving urban retail channels.
Growth Catalysts
- Multiplex expansion:Cinema chains across Southeast Asia are scaling concession infrastructure, creating dedicated popcorn supply contracts with volume guarantees.
- Clean-label mandates:FSSAI's tightened disclosure rules for artificial additives are accelerating migration toward minimal-ingredient product lines in Indian supermarkets.
- Hot-air popping technology:Oil-free thermal processing systems are reducing fat content claims and opening placement in health-positioned retail aisles.
Market Restraints
- Palm oil price volatility:Fluctuations in edible oil input costs compress margin stability for oil-popped product lines.
- Single-supplier bag substrate concentration:Microwaveable packaging films rely heavily on concentrated chemical suppliers, creating vulnerability to SAMR safety directive changes.
- Fresh snack substitution:Roasted nuts and baked chip alternatives capture similar impulse occasions in Japanese convenience stores.
Strategic Opportunities
- Indonesia's underpenetrated tier-two cities:Modern trade expansion outside Jakarta creates first-mover shelf space for ready-to-eat brands.
- Compostable packaging tailwind:Australia's National Plastics Plan incentives are accelerating paper-based bag adoption across premium segments.
- Direct-to-consumer subscription:Online retail channels enable flavor-customization models bypassing traditional distributor markups.
Industry Challenges
- Food technologist scarcity:Formulation expertise for clean-label shelf-stable products remains concentrated in Australia and Japan.
- Dual certification timelines:Simultaneous FSSAI and FSANZ approval processes delay regional SKU launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Popcorn Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter Popcorn, Cheese Popcorn, Caramel Popcorn, Spicy Popcorn Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Service Flavor Profile: Sweet, Savory, Spicy, Exotic Packaging Type: Bulk Packaging, Snack Bags, Microwaveable Bags, Cans |
| Companies Covered | The Hershey Company, Intersnack Group GmbH & Co. KG, PepsiCo Inc., JOLLY TIME, PROPER Snacks, Conagra Brands, Inc., Campbell Soup Company, Quinn Foods LLC, Weaver Popcorn, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Popcorn Market Trends and Innovations
Flavor architecture and thermal processing methods are diverging sharply between cinema-service and retail-packaged channels, creating distinct equipment and formulation competency requirements.
Hot-air popping systems are displacing traditional oil-popped production lines in Australian and Japanese manufacturing facilities. Health-positioned retail buyers specify sub-3% fat content thresholds that oil-based processes cannot economically achieve. The technology is displacing legacy kettle equipment in new facility investments across premium snack corridors.
FSSAI's 2024 artificial additive disclosure amendments mandate front-of-pack warning labels for synthetic flavor carriers. Manufacturers reformulating natural caramel and cheese seasonings face 15-20% raw material cost premiums. India's urban retail chains are responding by delisting non-compliant SKUs ahead of enforcement deadlines.
Cinema circuit procurement is consolidating toward exclusive supply partnerships with volume-commitment clauses. Australia's Event Cinemas and India's PVR-Inox chains now specify multi-year contracts with penalty structures for supply interruption. This pattern is most visible in tier-one metropolitan clusters where multiplex density supports dedicated logistics infrastructure.
Asia-Pacific Popcorn Market Segmentation

Segmentation across the Asia-Pacific Popcorn Market reveals divergent growth trajectories shaped by channel infrastructure maturity and regulatory pressure points. Product formulation and packaging specifications vary sharply between cinema concession supply and retail shelf placement, creating distinct margin structures and compliance burdens for manufacturers.
Product Type:
Domestic consumption patterns dominate butter and cheese variants across Indian and Australian retail channels, while caramel and spicy formats increasingly serve export-oriented premium positioning in Southeast Asian cinema circuits.
- Butter Popcorn:Oil-popped kernels coated with butter-flavored seasoning systems, typically achieving 4-6% fat content through palm oil or sunflower oil carriers. Volume concentrates in Australian supermarket aisles and Indian multiplex concessions where FSSAI labeling scrutiny on artificial flavor carriers is intensifying.
- Caramel Popcorn:Sugar-syrup coated kernels hardened through controlled thermal processing, commanding premium price positioning. Demand clusters in Japanese department store gift corridors and cinema chains across Bangkok and Singapore where portion-pack margins exceed standard savory alternatives.
- Cheese Popcorn:Powdered cheese seasoning applied via tumble-coating systems, prevalent in Australian and New Zealand retail.
- Spicy Popcorn:Chili, masala, or wasabi-based heat profiles targeting Southeast Asian and South Korean palates.
Butter popcorn holds the largest share; momentum sits with caramel varieties as cinema circuits expand across tier-one Southeast Asian metros.
Distribution Channel:
Channel cost structures range from high-touch food service logistics to automated e-commerce fulfillment, with margin capture varying threefold across the spectrum.
- Online Retail:Direct-to-consumer and marketplace platforms enabling flavor customization and subscription models. Australia's premium snacking corridors and India's urban centers show steepest expansion trajectory as microwaveable bag formats bypass traditional distributor markups through warehouse-direct fulfillment.
- Supermarkets:Modern trade shelf space in Coles, Woolworths, Reliance Retail, and Aeon chains. Placement depends on slotting fee negotiations and clean-label certification compliance.
- Convenience Stores:Impulse-purchase frequency leaders in Japan's Lawson and 7-Eleven networks, plus South Korean CU and GS25 chains.
- Food Service:Cinema concession supply, stadium vending, and hotel minibars requiring portion-controlled packaging and volume-commitment contracts.
Supermarkets dominate volume throughput; online retail is climbing fastest as logistics infrastructure matures across Australian and Indian urban corridors.
Flavor Profile:
Consumer palate segmentation tracks regional taste preferences and health-positioning trends, with formulation complexity varying by thermal processing method.
- Sweet:Caramel, toffee, and honey-based coatings. Concentrated in cinema circuits and gift-pack channels across Japan and Australia.
- Savory:Butter, cheese, and sea salt profiles occupying mass-market shelf space. Australian manufacturing facilities prioritize this segment for retail export into Southeast Asian markets.
- Spicy:Chili, sriracha, and wasabi heat levels. Indian urban centers and South Korean convenience stores drive specification requirements.
- Exotic:Truffle, matcha, and yuzu infusions targeting premium positioning. Tokyo and Sydney specialty retailers anchor demand.
Savory profiles command the largest installed base; exotic variants are gaining share fastest among premium-positioned direct-to-consumer channels.
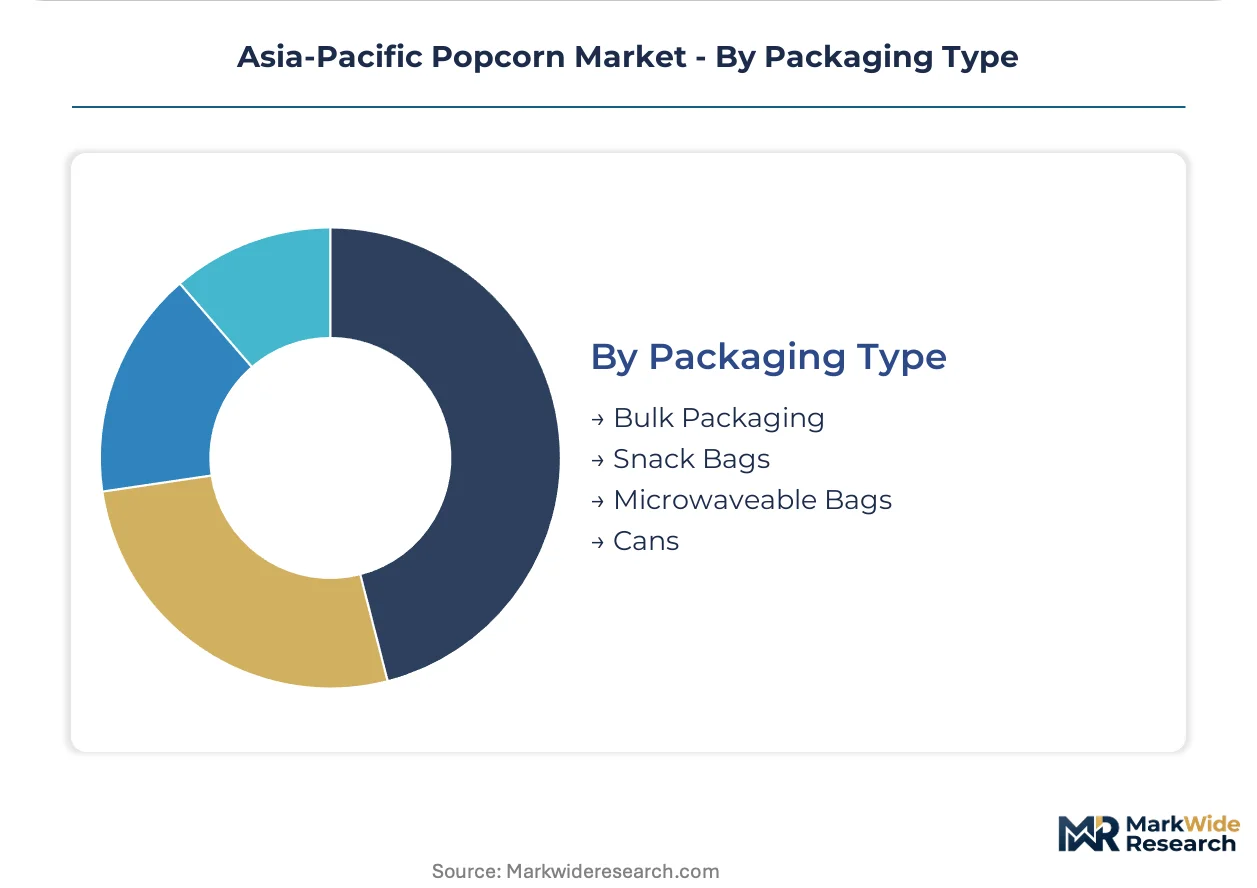
Packaging Type:
Substrate selection determines shelf-life extension, microwave safety compliance, and sustainability credentials across regulatory jurisdictions.
- Microwaveable Bags:Metallized film or susceptor-equipped paper constructions for home popping. FSSAI and SAMR chemical safety directives are forcing substrate migration toward PFAS-free alternatives, compressing supplier options for Indian and Chinese manufacturers.
- Snack Bags:Pre-popped ready-to-eat formats in metallized or compostable films. Australia's National Plastics Plan incentives are accelerating paper-based adoption across premium segments in Sydney and Melbourne retail corridors.
- Bulk Packaging:Cinema concession and food-service totes holding 5-20 kilograms. Logistics infrastructure concentrates supply contracts with Event Cinemas and PVR-Inox chains.
- Cans:Airtight metal containers for extended shelf-life gifting, prevalent in Japanese seasonal retail.
Snack bags hold the largest share; microwaveable formats are expanding most quickly as home-popping occasions proliferate across Indian and Australian households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across the Asia-Pacific Popcorn Market reveal Australia's manufacturing facilities supplying Southeast Asian cinema circuits, while India's domestic production serves both local multiplex demand and regional ready-to-eat export flows. China maintains net import dependency for premium flavor formulations, constraining regional trade balance.
India
Urban multiplex expansion in Mumbai and Delhi-NCR drives concession volume growth, with PVR-Inox chains consolidating supply contracts. FSSAI's 2024 artificial additive disclosure amendments mandate front-of-pack warning labels, accelerating clean-label reformulation timelines. Maharashtra's manufacturing clusters near Pune host contract production facilities serving both domestic retail and export-ready-to-eat segments.
Australia
Premium snacking corridors in Sydney and Melbourne anchor demand for compostable-packaged artisanal formats, with Event Cinemas specifying multi-year exclusive supply agreements. The National Plastics Plan incentivizes paper-based substrate migration, elevating compliance costs for microwaveable bag producers. Victoria's food manufacturing zones concentrate hot-air popping equipment investments displacing legacy kettle systems.
China
SAMR chemical safety directives on microwaveable bag substrates force PFAS-free material transitions, compressing supplier options for domestic manufacturers. Tier-one cities including Shanghai and Beijing exhibit growing home-popping occasion frequency through e-commerce channels. Yangtze River Delta production facilities face dual certification timelines delaying regional SKU launches.
Japan
Convenience store networks Lawson and 7-Eleven capture impulse-purchase frequency for portion-controlled formats, though fresh snack substitution pressures persist. METI standards on food-contact materials influence packaging substrate specifications for imported ready-to-eat products. Tokyo department store gift corridors anchor seasonal demand for caramel varieties in airtight metal containers.
South Korea
CU and GS25 convenience chains drive specification requirements for spicy flavor profiles targeting local palate preferences. MFDS additive regulations constrain synthetic flavor carrier usage in pre-packaged snack formulations. Seoul-based manufacturing facilities supply both domestic retail and limited export flows into Southeast Asian cinema circuits.
Asia-Pacific Popcorn Market Competitive Landscape
Concentration sits with multinational FMCG conglomerates leveraging pan-Asian distribution infrastructure to dominate modern trade shelf space. Mid-cap regional specialists sustain production flexibility through localized contract manufacturing partnerships. Three archetypes define competitive positioning: scale-driven conglomerates with integrated snack portfolios, regional specialists optimizing production flexibility, and premium-positioned players anchoring cinema circuit exclusivity. Dominant competitive moves include strategic partnerships for volume-commitment supply contracts and portfolio diversification into clean-label flavor architectures.
Within the multinational conglomerate tier, PepsiCo Inc. and The Hershey Company exemplify scale-driven positioning across tier-one metropolitan retail corridors. Intersnack Group GmbH & Co. KG occupies a specialist position, with its German corporate structure indicating European-origin regional production flexibility. These three entities represent divergent strategic anchors: integrated snack portfolio breadth, premium flavor-cinema circuit alignment, and contract-manufacturing regional adaptation respectively.
| Leading Market Players |
|---|
| The Hershey Company |
| Intersnack Group GmbH & Co. KG |
| PepsiCo Inc. |
| JOLLY TIME |
| PROPER Snacks |
| Conagra Brands, Inc. |
| Campbell Soup Company |
| Quinn Foods LLC |
| Weaver Popcorn, Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Australian hot-air popping facilities runs above regional averages, compressing per-unit fixed costs and establishing price floors that smaller kettle-based competitors in India and Indonesia cannot match without margin sacrifice. This scale concentration shapes procurement leverage for palm oil and packaging substrates while anchoring tier-one cinema contract pricing across Southeast Asian multiplex corridors.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through multi-year volume commitments with PVR-Inox and Event Cinemas chains. Three-tier pricing structure across premium caramel gift formats, standard butter retail SKUs, and economy microwaveable bags reflects fat-content thresholds and clean-label certification status. Pricing pressure stems from FSSAI-mandated reformulation costs elevating raw material premiums for natural flavor carriers. Price-sensitive mass-market consumers in Indian tier-two cities resist premium migration, while Australian gift-channel buyers exhibit inelastic demand for compostable-packaged artisanal varieties.
Supply Chain Analysis
Port congestion at Melbourne and Sydney terminals elevates inbound logistics costs for metallized film substrates sourced from Chinese chemical suppliers. Manufacturing gravity centers on Australia, India, and Japan, with Maharashtra's Pune cluster and Victoria's food zones hosting concentrated production assets. Raw material dependencies include Zea mays everta kernel supply from Argentina and the United States, palm oil from Indonesia and Malaysia, and susceptor-equipped packaging films. Single-source vulnerability concentrates in PFAS-free microwaveable bag substrates following SAMR safety directive changes. Distribution runs through cinema circuit direct delivery, modern trade distributor networks, and warehouse-direct e-commerce fulfillment.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific popcorn sits in early-cycle expansion as multiplex penetration in Indonesian tier-two cities and Indian urban corridors accelerates concession infrastructure deployment. Clean-label regulatory tailwinds in India and Australia are compressing legacy formulation timelines while opening premium positioning for compliant entrants.
For Market Incumbents: Consolidate supply contract exclusivity with expanding cinema chains through dedicated logistics infrastructure investments. Lock in multi-year kernel offtake agreements with Argentine and U.S. suppliers to buffer palm oil price volatility. Prioritize backward integration into hot-air popping equipment manufacturing to sustain technology differentiation against kettle-based regional competitors.
For New Entrants and Emerging Players: FSSAI clean-label certification fast-tracks shelf placement in Indian modern trade channels ahead of enforcement deadlines. Target Indonesia's underpenetrated Surabaya and Bandung corridors for first-mover ready-to-eat positioning. Pursue direct-to-consumer subscription models bypassing distributor markups through flavor-customization platforms.
For Investors and Strategic Acquirers: Regional contract manufacturers with localized FSSAI-FSANZ dual certification capabilities offer consolidation targets as approval timelines stretch to 8-14 months. Long-term viability hinges on compostable packaging transition execution and cinema circuit relationship depth. Monitor Australia's National Plastics Plan incentive disbursement velocity as inflection indicator for substrate migration economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSSAI front-of-pack warning mandates accelerate natural flavor carrier adoption across Indian retail SKUs. |
| Compostable Packaging Migration | Australia's National Plastics Plan incentives elevate paper-based bag economics in Sydney premium corridors. |
| Cinema Circuit Exclusivity | Multi-year volume-commitment contracts with PVR-Inox and Event Cinemas lock out competitor shelf space. |
| Hot-Air Popping Capacity Expansion | Oil-free thermal processing systems enable sub-3% fat claims for health-positioned retail placement. |
| Direct-to-Consumer Channel Launch | Subscription customization models bypass traditional distributor markups in Australian and Indian urban centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cinema procurement directors, FSSAI compliance officers, modern trade category buyers, and hot-air popping equipment manufacturers; and secondary validation through FSSAI additive disclosure amendments, FSANZ food standards codes, Australian National Plastics Plan documentation, and customs records for kernel import flows. Bottom-up volume modeling triangulated against top-down category spend estimates from retail audit databases.
Across the analysis window, the forecasting framework modeled product type, distribution channel, flavor profile, and packaging substrate dimensions alongside thermal processing method segmentation. CAGRs derived from trend extrapolation of multiplex expansion rates, regulatory compliance cost trajectories, and e-commerce logistics maturity curves. Kernel supply elasticity and palm oil futures volatility fed scenario-based price projections.
Decision-makers should treat outputs as directional under assumptions of sustained multiplex construction in Southeast Asian tier-one cities and stable FSSAI enforcement timelines; material deviation would warrant model refresh. Forecasts reflect base-case assumptions for clean-label adoption velocity and compostable packaging cost parity achievement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
India Energy Bar Market
Snacks
South Korea Snack Bar Market
Snacks
Low Calorie Crackers Market
Snacks
Marshmallow Market
Snacks
Potato Chips Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
RTE Popcorn Market
Snacks
Australia Snack Bar Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
High Carb Low Fat Snack Market
Snacks
Meat Snacks Market
Snacks
Global Rice Snacks Market
Snacks
United States Popcorn Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Salty Puffed Snacks Market
Snacks
Candy and Snack Food Pouches Market