
 Crock Meter Market | 2026-2036
Crock Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Crock Meter Market Outlook
Digital colorimetry integration is reconfiguring how crock meters interface with laboratory information management systems. SDL Atlas leverages its North American distribution network to sustain premium positioning in automated textile testing. James Heal & Co. anchors European demand through specialized service contracts with industrial labs. TESTEX competes on certification-aligned instrumentation for export-oriented manufacturers.
A crock meter measures color fastness to rubbing by applying standardized mechanical friction to dyed or printed textiles under controlled pressure and stroke parameters, quantifying color transfer via grayscale or spectrophotometric assessment. Digital crock meters command the widest deployment in high-throughput quality control labs, while portable units address field verification needs at dye houses and coating facilities. Laboratory-grade systems retain the deepest margin pools due to calibration traceability requirements and recurring consumables revenue.
FDA textile contact regulations, EU REACH restrictions on azo dyes, and ISO 105-X12 standards collectively shape product specifications and market access protocols for instrument vendors. The EU AI Act's emerging conformity requirements for automated testing systems will add compliance layers to digital crock meter software modules. Stakeholders must weigh certification breadth against regional regulatory divergence when configuring product portfolios for multi-jurisdiction textile supply chains.
Market Dynamics
Digital colorimetry integration is compressing testing cycles across textile quality control labs, forcing incumbent instrument vendors to reconfigure hardware-software architectures around laboratory information management system connectivity.
Growth Catalysts
- EU REACH azo dye restrictions:Export-oriented manufacturers in Bangladesh and Vietnam are expanding quality control budgets to meet compliance requirements for fabrics entering European markets.
- ISO 105-X12 standardization:Certification-aligned instrumentation demand is rising as third-party testing labs seek traceable calibration protocols for cross-border textile shipments.
- Digital automation:High-throughput quality control labs are replacing manual rubbing tests with automated crock meters to reduce operator variability and accelerate batch release decisions.
Market Restraints
- Optical sensor supply concentration:Precision photodetector manufacturing concentrates in German and Japanese component suppliers, exposing instrument assemblers to single-source procurement risk.
- Calibration consumables cost structure:Laboratory-grade systems require recurring purchases of certified reference materials and grayscale standards, elevating total cost of ownership for mid-sized dye houses.
- Portable unit technical limitations:Field verification devices lack spectrophotometric resolution, restricting their use to preliminary screening rather than final certification.
Strategic Opportunities
- EU AI Act conformity layers:Automated testing systems will require updated software modules for algorithmic transparency, creating first-mover advantage for vendors with embedded compliance engineering.
- Coating facility field verification:Portable crock meter deployment is underpenetrated at automotive leather finishing plants and upholstery coating operations outside traditional textile hubs.
- Cloud-connected instrumentation:Remote calibration monitoring and predictive maintenance subscriptions offer recurring revenue streams beyond hardware sales to distributed manufacturing networks.
Industry Challenges
- Spectrophotometric technician skill gaps:Digital crock meter operation requires training in colorimetric theory and software interface management that legacy manual test operators often lack.
- Multi-jurisdiction certification complexity:Instrument vendors must maintain parallel calibration traceability chains for FDA textile contact regulations, EU REACH protocols, and ISO standards simultaneously.
- Legacy system integration friction:Laboratory information management system connectivity demands custom API development for installed base equipment that predates digital automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crock Meter Market |
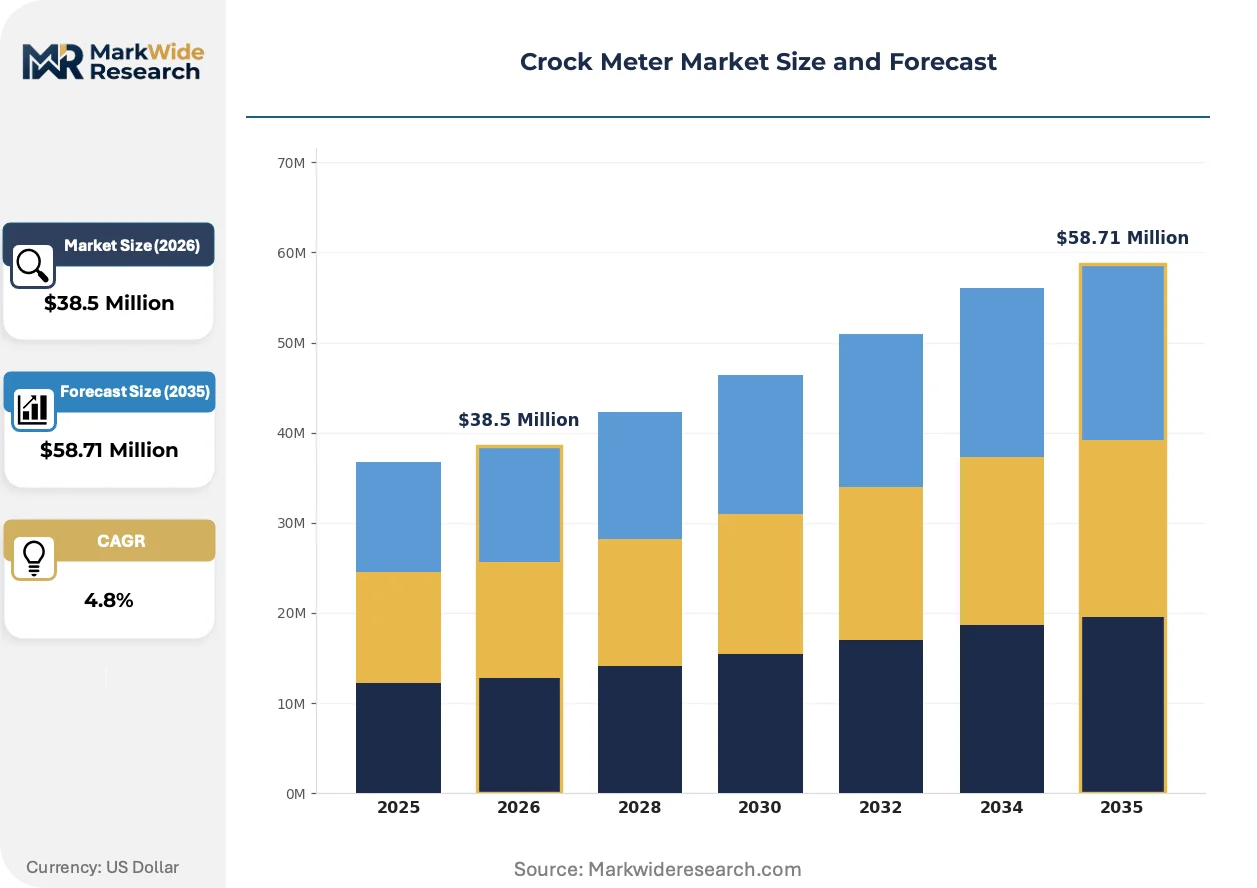
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $58.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Crock Meter, Manual Crock Meter, Portable Crock Meter, Laboratory Crock Meter End User: Textile Manufacturers, Quality Control Labs, Educational Institutions, Research Organizations Technology: Automatic, Manual, Analog, Digital Application: Textiles, Fabrics, Coatings, Paints |
| Companies Covered | SDL Atlas, Presto Group, TESTEX, James Heal & Co., Qualitest, Fanyuan Instrument, Paramount Instruments, Mesdan Lab, Unuo Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crock Meter Market Strategic Shifts
Spectrophotometric assessment modules are replacing grayscale visual evaluation as the default color transfer quantification method, compressing subjective interpretation out of compliance documentation workflows.
Integrated spectrophotometric detection arrays are rendering obsolete manual grayscale comparison methods in high-throughput quality control environments. Premium textile testing labs in Germany and Switzerland are adopting these systems to eliminate operator-to-operator variation in color fastness grading. The shift is compressing certification timelines from days to hours for export batch releases.
REACH restrictions on azo dyes and their metabolites are mandating more stringent color fastness verification for all dyed textiles entering European Union markets. Dye houses serving EU-bound apparel brands must now document crock fastness at multiple rubbing cycles rather than single-point testing. This regulatory tightening is concentrating demand for automated multi-cycle testing systems in Bangladesh and Vietnam export zones.
Service unbundling is separating hardware procurement from calibration maintenance contracts in laboratory equipment purchasing. Industrial dye houses in South Asia are increasingly sourcing crock meters through capital expenditure budgets while outsourcing traceable calibration to third-party metrology providers. This bifurcation is compressing instrument vendor margins on initial sales while expanding recurring service addressability for specialized calibration laboratories.
Crock Meter Market Segmentation
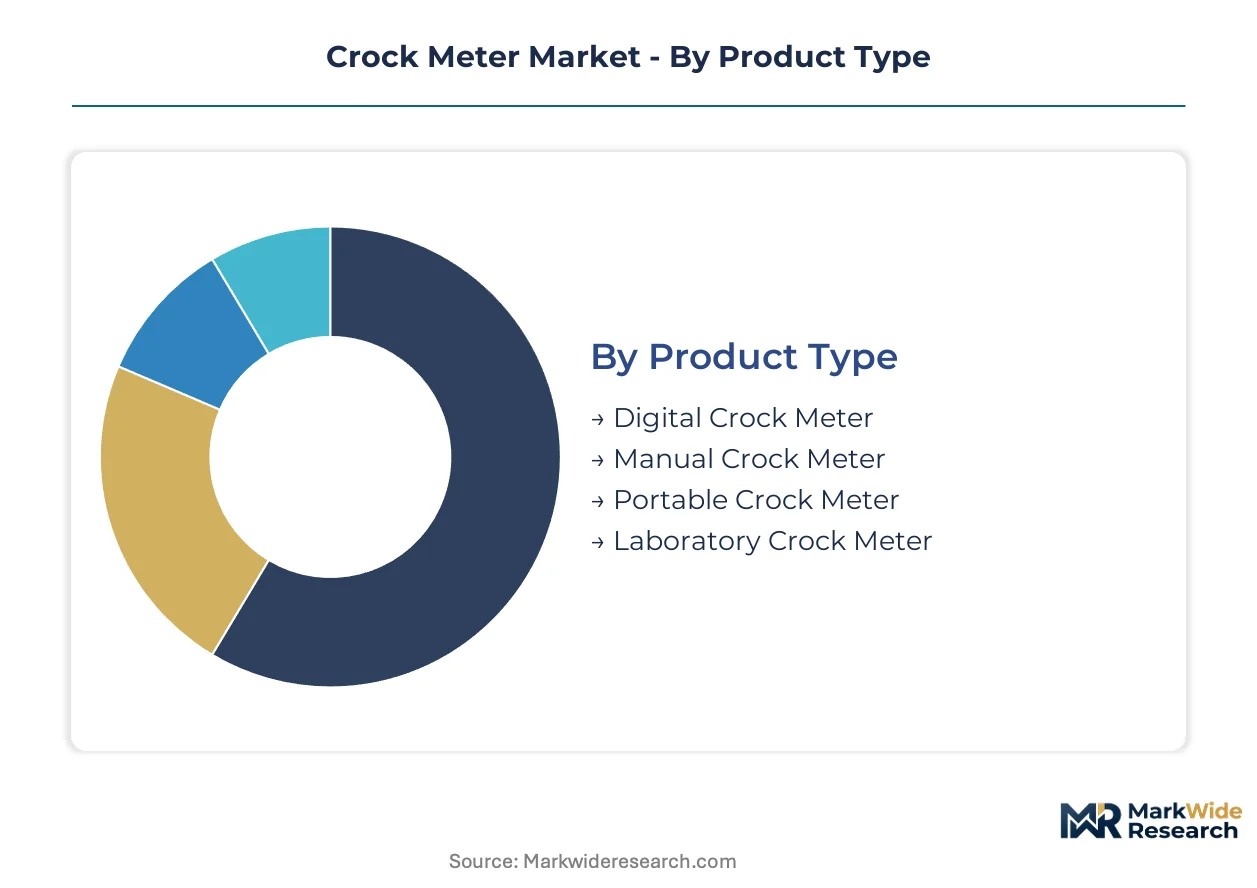
Crock meter segmentation reveals divergent equipment requirements between high-throughput certification labs and field-based quality verification. Product architecture, end-user sophistication, and integration depth separate premium laboratory systems from portable screening devices.
Product Type:
Mature laboratory-grade systems anchor revenue stability while emerging portable formats unlock underpenetrated field applications.
- Digital Crock Meter:Integrated spectrophotometric detection arrays automate color transfer quantification, eliminating operator-dependent grayscale interpretation. Demand concentrates in German and Swiss textile certification labs where ISO 105-X12 traceability requirements compress batch release timelines from days to hours.
- Manual Crock Meter:Mechanical friction apparatus with standardized pressure weights and stroke parameters requires trained operators for consistent results. Bangladesh and Vietnam dye houses deploy these units for preliminary screening before outsourcing final certification to third-party labs, constraining margin capture for instrument vendors.
- Portable Crock Meter:Battery-powered field verification units sacrifice spectrophotometric resolution for deployment flexibility at coating facilities and remote dye houses.
- Laboratory Crock Meter:Fixed-installation systems with LIMS connectivity and automated multi-cycle testing protocols serve regulatory documentation workflows.
Digital crock meters retain volume leadership; portable units hold the steepest expansion curve.
End User:
Customer sophistication tiers separate capital-intensive certification infrastructure from budget-constrained educational procurement.
- Textile Manufacturers:Export-oriented dye houses in Bangladesh and Vietnam deploy automated crock meters to document EU REACH azo dye compliance across multiple rubbing cycles, replacing single-point testing protocols. Calibration traceability requirements and recurring consumables purchases generate the deepest recurring revenue pools for instrument vendors.
- Quality Control Labs:Third-party certification facilities require multi-jurisdiction calibration chains spanning FDA textile contact regulations, EU REACH protocols, and ISO standards simultaneously. Service unbundling trends separate hardware procurement from outsourced metrology contracts, compressing initial sale margins while expanding addressable service revenue.
- Educational Institutions:University textile programs purchase manual and analog systems for student training in colorimetric theory fundamentals.
- Research Organizations:Materials science institutes acquire laboratory-grade systems with customizable friction parameters for experimental protocols.
Quality control labs command the highest equipment specifications; textile manufacturers represent the broadest addressable base.
Technology:
Automation intensity separates premium positioning from commodity substitution risk across the technology spectrum.
- Automatic:Servo-controlled pressure application, programmable stroke counts, and integrated spectrophotometric readout eliminate operator variability in high-throughput environments. EU AI Act conformity requirements for algorithmic transparency are forcing software architecture updates that favor vendors with embedded compliance engineering capabilities.
- Manual:Hand-cranked or weight-driven friction mechanisms with visual grayscale assessment persist in budget-constrained dye houses and educational settings.
- Analog:Electromechanical systems with dial gauges and analog output predominate in installed base equipment requiring LIMS integration through custom API development.
- Digital:Microprocessor-controlled units with software-configurable test parameters and data export capabilities bridge automatic and manual categories.
Automatic systems capture premium pricing tiers; digital platforms are gaining share fastest among mid-cap dye houses upgrading from manual methods.
Application:
Material substrate requirements dictate friction parameter ranges and contact surface specifications.
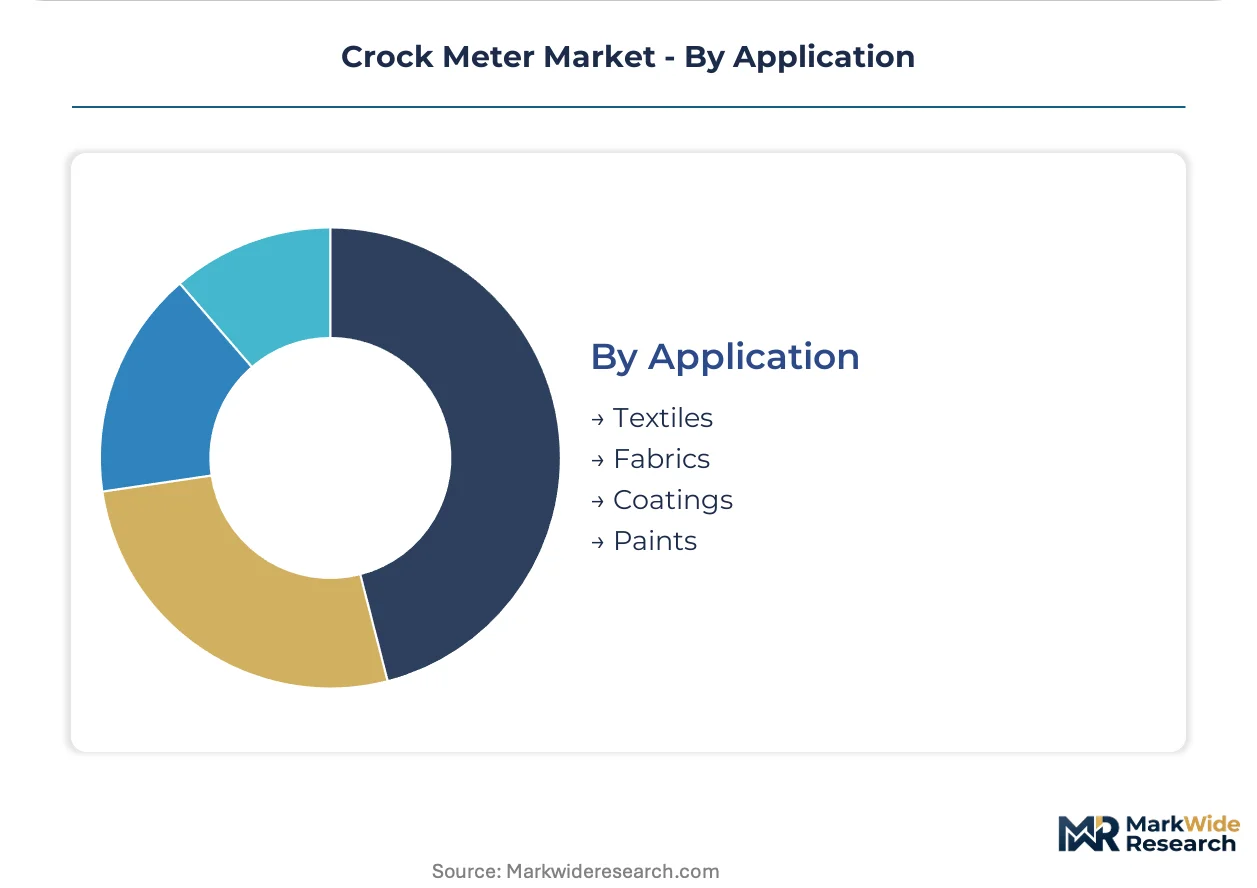
- Textiles:Woven and knitted fabric testing dominates unit volume, with wet and dry crock fastness assessment mandatory for EU-bound apparel shipments. REACH restrictions on azo dye metabolites are mandating expanded testing protocols across natural and synthetic fiber categories.
- Fabrics:Non-woven and technical textile applications require specialized test heads and pressure configurations for geotextile and medical fabric certification.
- Coatings:Automotive leather finishing plants and upholstery coating operations outside traditional textile hubs represent underpenetrated demand for portable field verification.
- Paints:Surface coating abrasion resistance testing employs modified crock meter configurations with alternative contact geometries.
Textile applications anchor installed base volumes; coatings represent the most underpenetrated expansion frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import asymmetries are redistributing crock meter demand toward manufacturing hubs serving EU and US textile markets. Import-dependent consuming regions maintain smaller installed bases concentrated in certification laboratories rather than production facilities.
Bangladesh
Garment exporters in Dhaka and Chittagong are expanding automated testing capacity to document EU REACH azo dye compliance across multiple rubbing cycles. The Bangladesh Garment Manufacturers and Exporters Association reports rising capital expenditure on laboratory-grade instrumentation. Dhaka-based dye houses are displacing manual crock meters with servo-controlled systems to accelerate batch release timelines for European apparel brands.
Germany
Textile certification laboratories in Baden-Württemberg and North Rhine-Westphalia anchor European demand for spectrophotometric crock meters with ISO 105-X12 traceability. ECHA enforcement of REACH metabolite restrictions drives multi-cycle testing protocols. Stuttgart-area testing facilities are integrating LIMS-connected instrumentation to eliminate operator-dependent grayscale interpretation from compliance workflows.
Vietnam
Export-oriented manufacturers in Ho Chi Minh City and Binh Duong province are automating quality control lines to meet EU market access requirements. The Ministry of Industry and Trade's technical barrier notification system aligns domestic standards with REACH protocols. Southern Vietnam textile parks are deploying cloud-connected crock meters to enable remote calibration monitoring across distributed dye house networks.
United States
FDA textile contact regulations govern instrument specifications for medical fabric producers in North Carolina and California apparel clusters. The Consumer Product Safety Commission maintains flammability and chemical safety standards that cascade into testing equipment procurement. Los Angeles-area technical textile manufacturers are upgrading from analog systems to digital platforms with software-configurable test parameters.
Switzerland
Premium textile testing laboratories in Zurich and Basel command the highest equipment specifications for colorimetric traceability. Swissmedic-aligned quality systems extend into industrial testing protocols for medical textile certification. St. Gallen-region technical textile institutes are adopting integrated spectrophotometric detection arrays to compress certification timelines from days to hours.
Crock Meter Market Competitive Environment
On the supply side, the industry is moderately consolidated around instrumentation specialists with differentiated geographic footprints and certification-aligned service capabilities. European and North American vendors maintain premium positioning through calibration traceability chains, while Asian fabricators compete on capital cost efficiency for budget-constrained dye houses. Three archetypes dominate: laboratory-grade system integrators with LIMS connectivity, portable field verification specialists, and regional component assemblers serving price-sensitive educational markets. Competitive dynamics center on strategic partnerships with third-party metrology providers and geographic expansion into underpenetrated coating facility segments.
Among UK-based laboratory equipment specialists, James Heal & Co. exemplifies the premium-tier archetype anchored in European certification workflows. SDL Atlas occupies a position within the North American distribution-focused segment, leveraging established channel relationships for automated textile testing penetration. TESTEX represents the certification-aligned instrumentation model, serving export-oriented manufacturers in South Asian garment hubs with compliance-engineered product configurations. Zhengzhou Shuli Machinery Co., Ltd. and Paramount Instruments sit within the regional fabricator tier, addressing capital expenditure constraints in emerging market dye houses through cost-optimized mechanical platforms.
| Leading Market Players |
|---|
| SDL Atlas |
| Presto Group |
| TESTEX |
| James Heal & Co. |
| Qualitest |
| Fanyuan Instrument |
| Paramount Instruments |
| Mesdan Lab |
| Unuo Instruments |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Singapore container corridor's freight volatility transmits directly into landed cost spreads between German precision component suppliers and Bangladeshi dye house buyers, compressing margin buffers for mid-tier instrument vendors while amplifying price premiums on laboratory-grade systems with embedded calibration traceability.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with laboratory-grade automated systems commanding substantial premiums due to ISO 105-X12 certification alignment and LIMS connectivity. Price differentiation stems from calibration traceability grade and after-sales service bundling intensity. Cost compression in economy-tier manual units is intensifying because Asian fabricators are scaling electromechanical production capacity. Small dye houses in Vietnam exhibit highest price sensitivity, while Swiss certification laboratories demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Contract manufacturing for precision photodetectors concentrates in German and Japanese optical component specialists, with final instrument assembly distributed across China, Germany, and the United States. Supply chains draw from specialized glass substrates, servo motor assemblies, and spectrophotometric sensor arrays. Single-source vulnerability in photodetector procurement exposes assemblers to allocation risk during demand surges. Distribution runs through direct technical sales for laboratory systems and regional distributor networks for portable field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The crock meter market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. Calibration traceability requirements and multi-jurisdiction certification complexity erect substantial switching costs against displacement.
For Market Incumbents: Entrench through backward integration into precision photodetector sourcing partnerships and embedded compliance engineering for EU AI Act algorithmic transparency mandates. Threat from Asian cost-optimized fabricators necessitates defending premium positioning via exclusive service contracts with third-party metrology providers. Capacity addition in Vietnam and Bangladesh anchors geographic proximity to fastest-expanding dye house demand. For New Entrants and Emerging Players: Pursue underpenetrated coating facility segments at automotive leather finishing plants and upholstery operations outside traditional textile manufacturing clusters. Portable field verification devices for remote dye house networks represent the most penetrable product category. Go-to-market execution should leverage cloud-connected instrumentation with predictive maintenance subscriptions to bypass incumbent calibration service relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial instrumentation conglomerates where textile testing represents non-core revenue exposure. Long-term viability centers on recurring consumables revenue streams and software module upgrade cycles rather than hardware replacement demand. Watch for inflection signals in EU AI Act implementation timelines affecting automated testing system compliance requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Compliance Engineering Investment | EU AI Act algorithmic transparency mandates force software architecture updates favoring prepared vendors. |
| Cloud-Connected Instrumentation Launch | Remote calibration monitoring subscriptions unlock recurring revenue from distributed dye house networks. |
| Backward Integration into Photodetector Sourcing | Mitigates single-source concentration risk with German and Japanese optical component suppliers. |
| Calibration Service Unbundling Partnership | Third-party metrology outsourcing trends expand addressable service revenue beyond hardware margins. |
| Portable Unit Geographic Expansion | Automotive leather finishing plants in Mexico and Eastern Europe represent underpenetrated field verification demand. |
Study Parameters
The analysis maps digital crock meter, manual crock meter, portable field unit, and laboratory-grade system segments, each validated through instrument vendor sales directors, textile manufacturer quality control managers, third-party metrology laboratory technicians, and regulatory compliance officers. Primary intelligence combines structured interviews with secondary validation against ISO standard documentation, ECHA REACH enforcement records, FDA textile contact regulation filings, and customs trade data for precision optical component flows. Bottom-up unit demand modeling triangulates against top-down market sizing from instrumentation industry associations.
Assumptions hold EU REACH azo dye enforcement intensity, ISO 105-X12 standardization adoption curves, and digital automation replacement rates within observed historical patterns across the projection horizon. Segmentation dimensions span product architecture, end-user sophistication tier, automation intensity, and material substrate application. CAGRs derive from regression analysis of capital expenditure trends in export-oriented textile manufacturing hubs. Industry-specific forecast inputs include ECHA metabolite restriction expansion timelines and cloud-connected instrumentation penetration rates in South Asian garment clusters.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by Asian cost-optimized fabricators or accelerated EU AI Act enforcement would shift outcomes substantially. Quarterly review of REACH compliance budget allocations at Bangladesh Garment Manufacturers and Exporters Association member firms and photodetector supplier allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Comparators Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Humidity Testers Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Hour Meter Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market