
 Artificial Grass Turf Market | 2026-2036
Artificial Grass Turf Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Grass Turf Market Analysis
Polyethylene yarn formulation is fragmenting into specialized chemistries as manufacturers respond to heat-resistance and recyclability mandates. TenCate Grass anchors European professional sports installations through its proprietary CoolPlay temperature-management technology. Shaw Industries Group leverages its carpet-industry polymer expertise to dominate North American residential distribution channels. CCGrass competes aggressively on manufacturing scale from its Chinese production base, supplying FIFA-certified pitches across Asia and the Middle East.
Artificial grass turf consists of synthetic fiber tufts—typically polyethylene, polypropylene, or nylon—stitched into porous polyurethane backings and installed over compacted aggregate bases with optional infill layers of sand, rubber, or organic materials. These systems replicate natural grass performance for sports traction, drainage rates, and UV stability while eliminating irrigation and mowing requirements. Polyethylene formulations lead volume due to their softer hand-feel and superior resilience for residential lawns and sports fields, though nylon retains premium positioning for high-frequency commercial landscapes where durability rating demands justify higher material costs. Hybrid installation types are gaining share as facilities seek to balance player safety with reduced maintenance complexity.
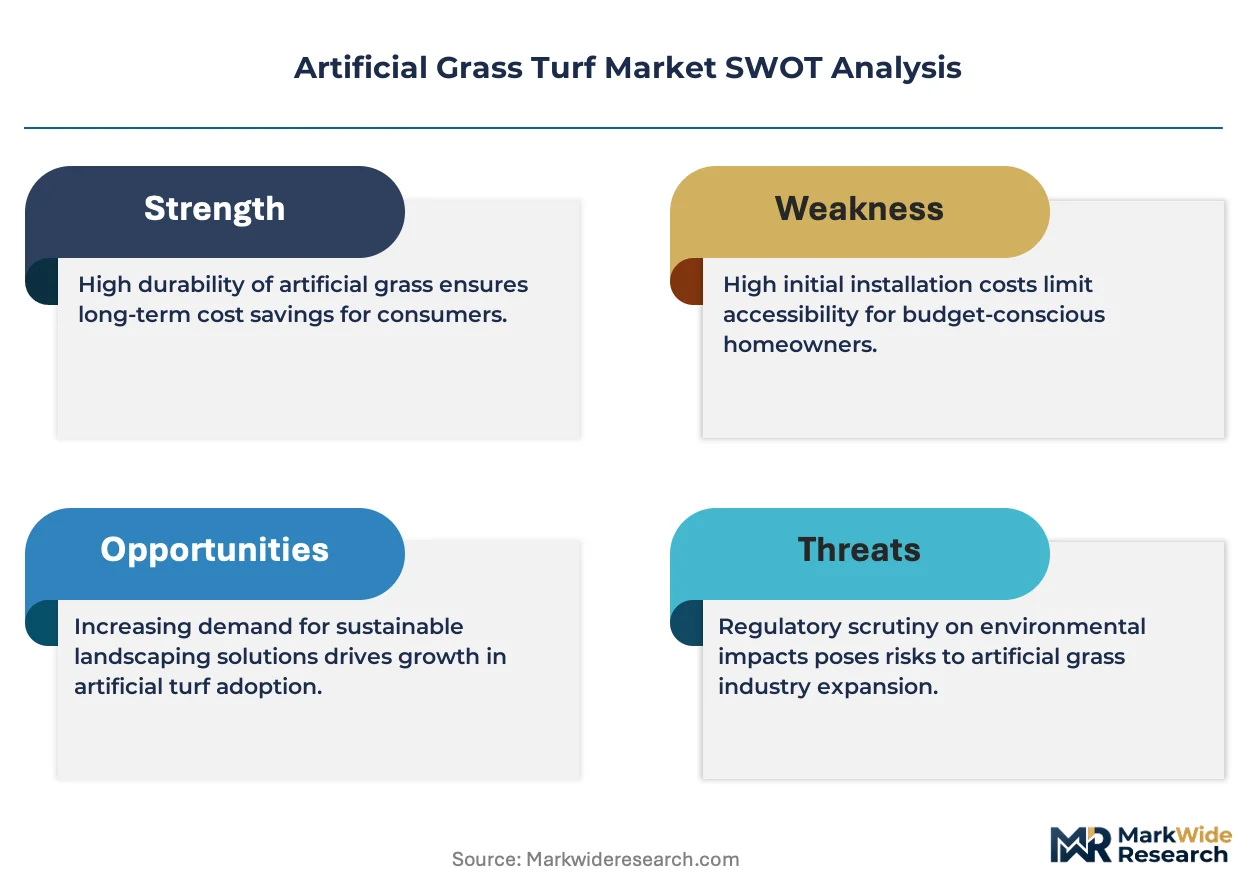
EPA scrutiny of per- and polyfluoroalkyl substances is pressuring U.S. manufacturers to reformulate backings and infill chemistries ahead of anticipated federal restrictions. REACH compliance through ECHA continues to govern European market access, with particular emphasis on heavy-metal limits in colorants and plasticizer migration thresholds. FIFA Quality Programme certification and World Rugby performance standards operate as de facto gatekeepers for professional sports procurement globally. Stakeholders must monitor regulatory divergence between jurisdictions while building polymer recycling partnerships to preempt extended producer responsibility mandates.
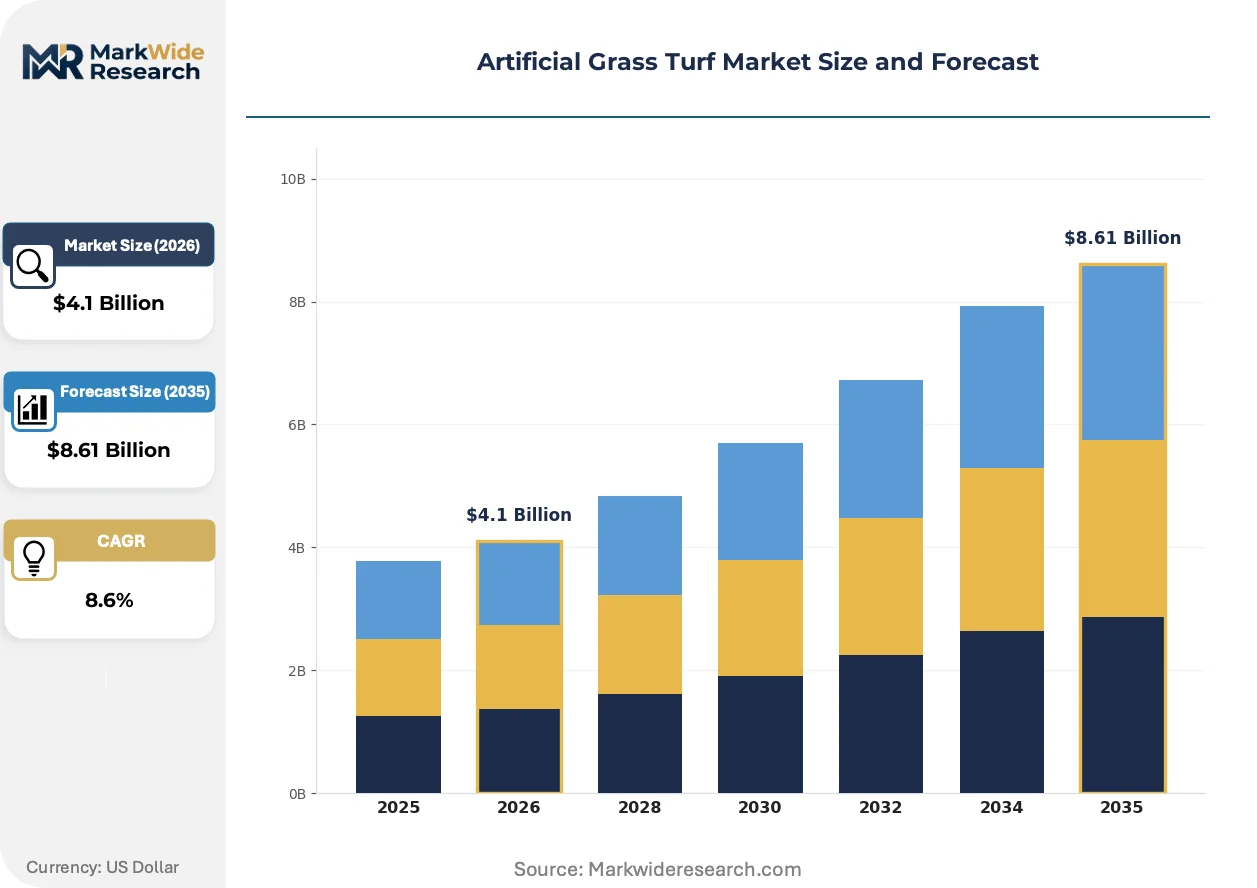
Market Dynamics
PFAS phase-out mandates across multiple jurisdictions are forcing immediate reformulation of polyurethane backings and rubber infill chemistries, compressing product development cycles while elevating compliance costs for manufacturers without captive polymer research capabilities.
Growth Catalysts
- EPA PFAS restrictions:Anticipated federal limits on per- and polyfluoroalkyl substances are accelerating R&D investment in fluorine-free backing adhesives and alternative infill materials ahead of enforcement timelines.
- Municipal sports procurement:City and county governments in water-stressed regions are specifying synthetic surfaces for stadium renovations to eliminate irrigation costs and extend playable hours.
- Cool yarn technology:Advanced infrared-reflective polyethylene formulations reduce surface temperatures, expanding addressable markets in subtropical climates previously excluded from synthetic turf adoption.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress margins on polyethylene and polypropylene yarn production, with limited hedging instruments available to mid-tier manufacturers.
- Chinese production concentration:Three-quarters of global tufting capacity sits in Zhejiang and Jiangsu provinces, creating geopolitical and logistics risk exposure for buyers seeking supply diversification.
- Natural grass restoration:Professional leagues in Germany and England are piloting hybrid grass systems and natural pitch renovation programs that threaten replacement demand in elite sports segments.
Strategic Opportunities
- Extended producer responsibility mandates:Draft EU regulations on synthetic surface end-of-life management create first-mover advantage for manufacturers building closed-loop recycling partnerships with construction waste processors.
- Residential xeriscaping:Homeowner association bans on lawn irrigation in Arizona, Nevada, and California municipalities are opening volume opportunities in premium residential segments previously dominated by natural sod.
- Biopolymer infill convergence:Cork and coconut husk alternatives combined with thermoplastic elastomer engineering are creating specification pathways for LEED-certified commercial landscapes seeking carbon footprint reductions.
Industry Challenges
- FIFA Quality Programme certification timelines:Laboratory testing and field trial requirements for professional pitch accreditation extend 18-24 months, locking working capital and delaying revenue recognition for project-based manufacturers.
- Polymer recycling infrastructure gaps:Separation of mixed-fiber tufts from polyurethane backings requires specialized shredding and solvent recovery equipment that remains concentrated in Northern European processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Grass Turf Market |
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Blended Application: Residential Lawns, Sports Fields, Commercial Landscapes, Playgrounds Installation Type: In-fill, Non-infill, Hybrid, Portable Durability Rating: Light Duty, Medium Duty, Heavy Duty, Ultra Duty |
| Companies Covered | Tarkett, Shaw Industries Group, TenCate Grass, CCGrass, Polytan, Act Global, ForeverLawn, SIS Pitches, Victoria PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Grass Turf Market Emerging Trajectories
Material science breakthroughs and procurement model evolution are compressing traditional product lifecycles while fragmenting buyer segments into performance-tier specialists rather than full-line generalists.
Monofilament polyethylene yarns with engineered cross-sectional geometries are collapsing the temperature-performance trade-off that previously restricted synthetic turf deployment in high-ambient-heat environments. Stadium operators in Qatar, Arizona, and inland Australia are specifying these chemistries for year-round playability without irrigation infrastructure. The technology is collapsing the historical 15-degree Celsius surface temperature penalty versus natural grass, eliminating the primary objection from player unions and safety regulators.
REACH authorization procedures through ECHA are tightening heavy-metal thresholds in colorant masterbatches and plasticizer formulations used in backing adhesives. Manufacturers without in-house toxicology testing capabilities face extended notification periods and reformulation costs that disproportionately burden smaller compounders. Sports federations operating in EU member states are now requiring supply-chain documentation extending to third-tier chemical suppliers, shifting procurement evaluation criteria toward compliance transparency and away from pure unit economics.
Design-build-operate contracts are displacing traditional capital expenditure procurement for municipal sports field installations, transferring performance risk to turf system providers for 10-15 year service terms. Facility managers in Texas, Florida, and Southern California are bundling surface replacement, infill replenishment, and grooming services into single-vendor agreements with guaranteed availability clauses. This reconfiguration concentrates purchasing authority with integrated service providers and marginalizes pure product distributors unable to field maintenance crews.
Artificial Grass Turf Market Segmentation
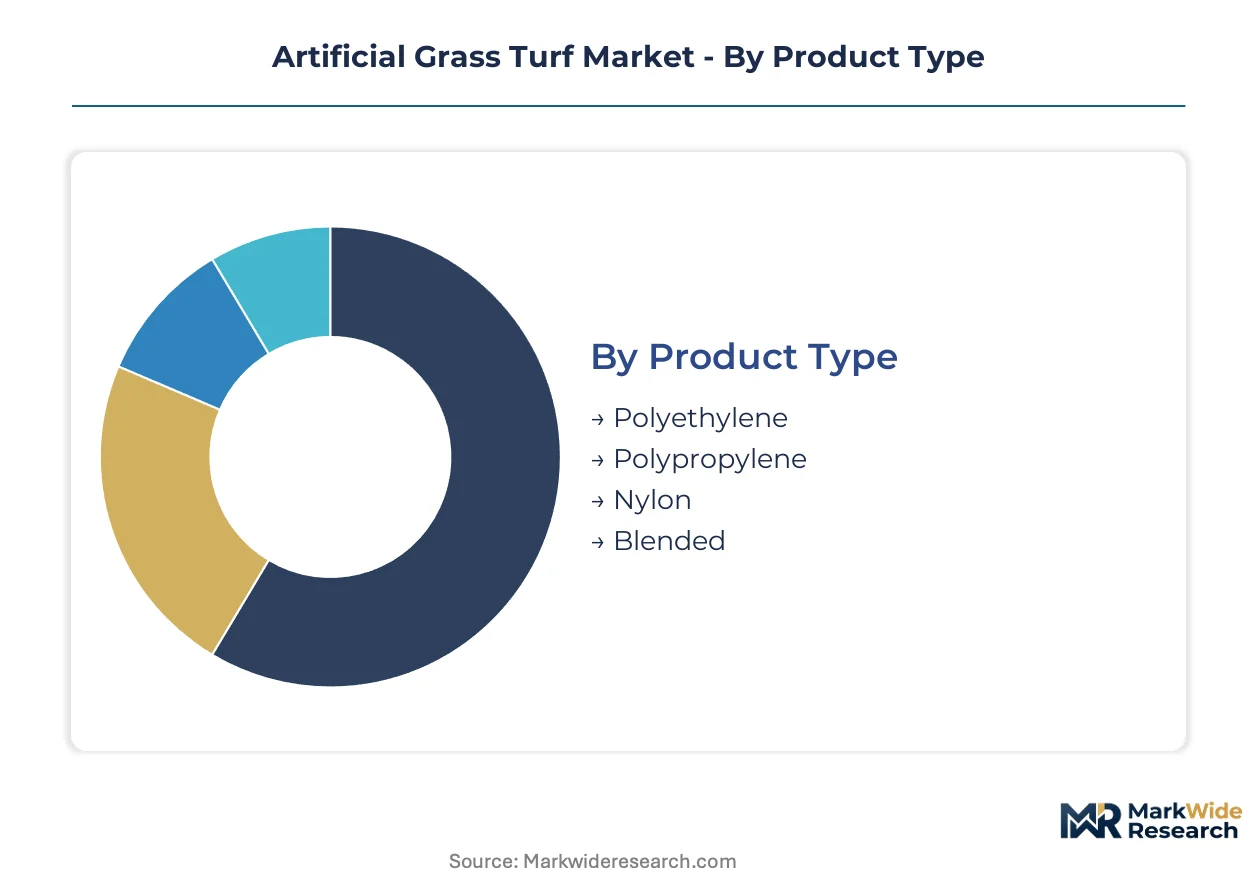
Segmentation in artificial grass turf reveals divergent replacement cycles across product chemistries and installation types. Sports field procurement operates on 8-12 year refresh timelines, while residential lawns extend 15-20 years, creating distinct revenue recognition patterns for manufacturers serving each tier.
Product Type:
Polyethylene yarns turn over fastest in residential replacement cycles, while nylon installations persist longest in commercial landscapes. Polypropylene occupies a mid-cycle position with moderate durability expectations.
- Polyethylene:Soft hand-feel polyethylene dominates volume through superior UV stability and resilience underfoot. Municipal sports procurement in water-stressed U.S. counties specifies polyethylene for stadium renovations eliminating irrigation infrastructure.
- Polypropylene:Stiffer fiber geometry delivers cost-efficient performance for secondary sports applications and budget residential installations. German municipal buyers specify polypropylene for training pitches where FIFA certification is not required.
- Nylon:Premium positioning for high-frequency commercial landscapes justifies extended capital recovery timelines.
- Blended:Hybrid fiber formulations balance cost and performance for mid-market landscape contractors.
Polyethylene anchors the volume base while blended formulations gain share at the steepest rate.
Application:
Cost tiers separate clearly across end-use segments, with sports field installations commanding premium pricing against commoditized residential volume.
- Residential Lawns:Homeowner association irrigation bans in Arizona, Nevada, and California municipalities drive specification shifts. Xeriscaping mandates open volume opportunities in premium segments previously dominated by natural sod.
- Sports Fields:FIFA Quality Programme certification requirements extend procurement cycles 18-24 months. Design-build-operate contracts in Texas and Florida bundle 10-15 year performance guarantees with surface installation.
- Commercial Landscapes:LEED certification pathways favor cork and coconut husk infill alternatives for carbon footprint reductions.
- Playgrounds:Safety surfacing specifications emphasize fall-height ratings and impact attenuation compliance.
Sports fields concentrate margin contribution while residential lawns expand most quickly through drought-driven substitution.
Installation Type:
Volume distribution correlates inversely with complexity, as simpler systems penetrate price-sensitive segments faster.
- In-fill:Sand and rubber infill systems retain dominant share through proven drainage performance and player traction metrics. Stadium operators in Qatar and inland Australia specify advanced infill chemistries for year-round playability.
- Non-infill:Eliminated infill layers reduce maintenance burden for residential and light commercial applications. Chinese manufacturers compete aggressively on non-infill system cost for Middle East distribution.
- Hybrid:Combines synthetic tufts with natural grass root zones for elite sports segments piloting restoration programs.
- Portable:Modular systems serve temporary event infrastructure and rental market applications.
In-fill installations anchor the volume base while non-infill systems climb the fastest through residential penetration.
Durability Rating:
Customer type stratification separates institutional buyers seeking lifecycle cost certainty from residential purchasers prioritizing upfront capital constraints.
- Light Duty:Decorative and occasional-use applications with minimal foot traffic requirements.
- Medium Duty:Standard residential lawns and light commercial landscapes balancing cost with 10-year service expectations.
- Heavy Duty:Municipal sports fields and high-traffic commercial installations requiring sustained performance under intensive use.
- Ultra Duty:Professional stadium installations with FIFA certification and guaranteed availability clauses.
Heavy duty ratings anchor the volume base while ultra duty specifications gain share at the steepest rate through professional sports procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese tufting clusters in Zhejiang and Jiangsu provinces supply the majority of global volume, while import demand concentrates in water-stressed municipalities across the United States, Germany, and Australia. Trade patterns are shifting as European REACH compliance costs and anticipated U.S. PFAS restrictions incentivize regional manufacturing investments.
United States
Municipal stadium renovations in Arizona, Nevada, and California drive procurement volume as irrigation bans eliminate natural grass alternatives. EPA scrutiny of per- and polyfluoroalkyl substances pressures manufacturers to reformulate polyurethane backings ahead of federal enforcement timelines. The Dallas-Fort Worth metroplex anchors Southwest distribution with multiple design-build-operate contractors bundling 10-15 year surface performance guarantees.
Germany
Federal sports infrastructure programs prioritize synthetic pitch installations for municipal training facilities and amateur league stadiums. ECHA REACH authorization procedures tighten heavy-metal thresholds in colorant masterbatches, extending certification timelines for imported systems. The North Rhine-Westphalia industrial corridor hosts specialized compounders developing fluorine-free backing adhesives for EU market access.
China
Domestic stadium construction for international sporting events sustains demand for FIFA-certified pitch systems alongside export manufacturing. National dual carbon goals pressure Zhejiang and Jiangsu producers to decarbonize petrochemical feedstock consumption in yarn extrusion processes. The Yangtze River Delta concentration of tufting capacity creates logistics advantages for Middle East and Southeast Asian distribution contracts.
Australia
Inland municipalities facing extreme heat and drought specify infrared-reflective polyethylene formulations for year-round playability without irrigation infrastructure. State-level environmental regulations in New South Wales and Victoria restrict rubber infill chemistries, accelerating specification shifts toward cork and coconut husk alternatives. Melbourne anchors professional sports procurement with AFL and A-League stadium renovation programs.
United Arab Emirates
Stadium infrastructure for international tournament hosting drives premium-grade synthetic surface imports from European and Chinese suppliers. Dubai and Abu Dhabi municipal specifications emphasize CoolPlay-equivalent temperature management technologies for player safety in ambient conditions exceeding 40 degrees Celsius. The Jebel Ali logistics corridor facilitates re-export distribution across Gulf Cooperation Council markets.
Artificial Grass Turf Market Vendor Landscape
On the supply side, the industry is tiered between integrated polymer specialists, regional installation service providers, and scale-driven Asian manufacturers. European and North American players anchor premium sports certification tiers through proprietary temperature-management and durability technologies, while Chinese producers compete on manufacturing scale and non-certified volume segments. Strategic archetypes include polymer-backward integrated specialists, design-build-operate service bundlers, and export-focused scale manufacturers. Dominant competitive moves center on captive polymer research capabilities for regulatory compliance and long-term municipal service contracts transferring performance risk from facility operators.
Among European specialists, TenCate Grass and Polytan occupy positions within the professional sports certification tier, representing archetypes of technology-differentiated suppliers serving FIFA and World Rugby accreditation pathways. Shaw Industries Group anchors North American residential distribution through carpet-industry polymer expertise. At the scale-driven end, CCGrass exemplifies manufacturing concentration from Chinese production bases supplying volume markets across Asia and the Middle East.
| Leading Market Players |
|---|
| Tarkett |
| Shaw Industries Group |
| TenCate Grass |
| CCGrass |
| Polytan |
| Act Global |
| ForeverLawn |
| SIS Pitches |
| Victoria PLC |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Zhejiang and Jiangsu tufting clusters compresses supplier margins while concentrating pricing power with buyers who can guarantee volume commitments. Utilization rates below break-even thresholds force Chinese manufacturers to accept thinner margins on non-certified residential volume, even as EPA PFAS compliance costs elevate pricing floors for U.S.-bound shipments.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across municipal sports procurement and commercial landscape contracts. Three-tier pricing structure across premium, standard, and economy levels separates FIFA-certified pitch systems from training-grade installations and budget residential rolls. Price differentiation hinges on certification tier and after-sales service bundling, with design-build-operate contracts commanding 15-20% premiums over pure product sales. Cost compression in residential polyethylene yarn is intensifying because Chinese scale manufacturers are dumping excess capacity into Middle East and Southeast Asian distribution channels. Municipal procurement officers exhibit lowest price sensitivity due to lifecycle cost modeling, while residential contractors face acute margin pressure from irrigation-ban-driven demand surges.
Supply Chain Analysis
Contract manufacturing concentration sits with CCGrass, TenCate Grass, and Shaw Industries Group facilities anchoring regional supply bases. Geographic supply concentration centers on China, the United States, and Germany, with Zhejiang province hosting three-quarters of global tufting capacity. Raw material dependencies rest on ethylene and propylene feedstocks for polyethylene and polypropylene yarn extrusion, plus polyurethane precursor chemicals for backing adhesives. Single-source vulnerability from Chinese production concentration creates geopolitical and logistics risk exposure for buyers seeking supply diversification. Distribution runs through specialized landscape contractors in North America, direct municipal procurement in Germany, and re-export hubs in the United Arab Emirates for Gulf Cooperation Council markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer research capabilities for fluorine-free backing formulations represent the critical asset gap separating viable competitors from margin-squeezed assemblers. Manufacturers without captive toxicology testing and REACH certification expertise face extended notification periods that lock working capital and foreclose premium sports procurement opportunities.
For Market Incumbents: Pre-empt regulatory divergence by building backward integration into polyurethane precursor production for PFAS-compliant adhesive formulations. Establish closed-loop recycling partnerships with Northern European construction waste processors ahead of extended producer responsibility mandates. Lock in 10-15 year design-build-operate contracts with Texas and Florida municipal facilities to transfer performance risk and marginalize pure product distributors. For New Entrants and Emerging Players: Build out cork and coconut husk infill supply chains for LEED-certified commercial landscapes in Arizona, Nevada, and California where xeriscaping mandates are opening premium residential segments. Target portable modular systems for temporary event infrastructure and rental market applications where certification requirements are minimal and Chinese competition is weakest. Pursue direct-to-landscape-contractor distribution bypassing traditional distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because REACH and EPA chemical restrictions are permanently elevating barriers to premium sports certification. Acquisition targets should prioritize mid-tier European compounders with ECHA authorization expertise and existing FIFA laboratory relationships. Monitor EPA enforcement timeline announcements as the primary inflection signal for U.S. market restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Backing Development | ECHA REACH authorization and anticipated EPA PFAS restrictions mandate immediate reformulation of polyurethane adhesives. |
| Closed-Loop Recycling Partnership | Draft EU extended producer responsibility regulations create first-mover advantage for end-of-life synthetic surface recovery. |
| Design-Build-Operate Contracting | Texas and Florida municipal bundling transfers 10-15 year performance risk from facility operators to turf system providers. |
| Cool Yarn Technology Scale-Up | Infrared-reflective polyethylene formulations expand addressable markets in Qatar, Arizona, and inland Australia subtropical climates. |
| Biopolymer Infill Convergence | Cork and coconut husk alternatives combined with thermoplastic elastomer engineering unlock LEED certification pathways. |
Methodological Framework
The analysis maps polyethylene yarn formulations, polyurethane backing systems, and infill material alternatives, each validated through plant managers at extrusion facilities, procurement leads at municipal sports authorities, distribution channel partners in residential landscaping, and technical R&D directors at compounders. Primary interviews with FIFA certification laboratory directors and ECHA authorization consultants combined with secondary validation from customs/trade data, SEC 10-K filings from listed manufacturers, and sports federation procurement databases. Bottom-up volume triangulation across product chemistry segments reconciled with top-down market value estimates.
Assumptions held fixed include REACH authorization timelines and EPA PFAS enforcement pathways; variables included ethylene and propylene feedstock price volatility and municipal budget cycles for stadium infrastructure. Segmentation dimensions modeled encompass fiber chemistry, installation type, durability rating, and application vertical across the projection horizon. CAGRs derived from replacement cycle analysis and procurement pipeline tracking, with inputs from drought-driven residential substitution rates and professional sports certification backlogs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese scale manufacturers or accelerated EU recycling mandates would shift outcomes. Quarterly review of EPA regulatory announcements, ECHA authorization publication rates, and municipal procurement pipeline indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Beach Umbrella Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
North America Robotic Lawn Mower Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Singapore Camping Equipment Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Ice Axe Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
China Camping Tent Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Picnic Coolers Market