
 Camping Cooler Market | 2026-2036
Camping Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Cooler Market Analysis
Asset-light leasing models for high-performance outdoor equipment are reshaping competitive dynamics in the camping cooler sector. YETI leverages its premium brand positioning to command direct-to-consumer margins that subsidize selective wholesale distribution. RTIC competes through aggressive value engineering that narrows the performance gap against premium-priced alternatives without matching their price points. Pelican anchors its market presence through rotomolded construction expertise inherited from protective case manufacturing.
A camping cooler is a thermally insulated portable container engineered to maintain sub-ambient temperatures for perishable goods, typically employing polyurethane foam injection between polyethylene or polypropylene walls with gasket-sealed lids to achieve ice retention periods exceeding five days. Its primary commercial purpose spans outdoor recreation, marine applications, and remote worksite provisioning where grid-independent food safety is required. Hard coolers occupy the dominant margin pool due to durability premiums and attachment ecosystem sales, while electric coolers represent the fastest-expanding category as lithium-ion power density improvements enable compressor-based refrigeration in portable form factors. Soft coolers sustain steady demand among ultralight backpackers and day-trip segments where weight minimization overrides multi-day ice retention requirements.
The US Federal Trade Commission's Green Guides constrain environmental marketing claims around insulation performance and recycled content, compelling verified testing protocols before label assertions. California's Title 20 appliance efficiency regulations and the EPA's Energy Star certification pathway for battery-powered cooling devices together elevate compliance costs for electric cooler entrants. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could mandate take-back programs for refrigerant-containing portable units.
Market Dynamics
Electric cooler adoption is compressing the traditional hard cooler margin pool as lithium-ion power density gains enable compressor-based portable refrigeration, forcing incumbent rotomolded manufacturers to defend their ice-retention value proposition through attachment ecosystems and durability premiums.
Growth Catalysts
- Adventure tourism procurement expansion:Backcountry expedition operators are scaling equipment budgets to meet rising participation in remote guided experiences, creating bulk demand for multi-day ice retention systems.
- California Title 20 compliance redesign:Updated energy efficiency standards for portable appliances are pressuring manufacturers to optimize electric cooler power systems, accelerating product refresh cycles.
- Polyurethane foam insulation advances:Next-generation injection molding techniques are extending ice retention periods beyond seven days in hard cooler configurations, reinforcing durability premiums.
Market Restraints
- Rotomolded resin input volatility:Polyethylene and polypropylene feedstock costs fluctuate with petrochemical capacity, compressing margins for construction-intensive hard cooler production.
- EPA refrigerant containment requirements:Electric cooler manufacturers face elevated compliance costs for portable compressor units under evolving refrigerant handling protocols.
- Soft cooler substitution pressure:Ultralight insulated fabric alternatives capture day-trip and ultralight backpacking segments where weight minimization trumps multi-day thermal performance.
Strategic Opportunities
- Asset-light leasing penetration:Subscription-based equipment access models for high-performance outdoor gear are reshaping competitive dynamics and recurring revenue potential.
- Dispersed camping permit growth:United States national park visitation and backcountry permit issuance continue climbing, concentrating demand for grid-independent food safety solutions.
- EU F-Gas Regulation alignment:European refrigerant phase-down schedules create first-mover advantage for compressor-based electric cooler entrants with low-GWP alternatives.
Industry Challenges
- Extended producer responsibility frameworks:State-level mandates for refrigerant-containing portable unit take-back programs are increasing operational complexity for electric cooler distribution networks.
- FTC Green Guides verification protocols:Substantiation requirements for environmental marketing claims around insulation performance and recycled content are lengthening product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Cooler Market |
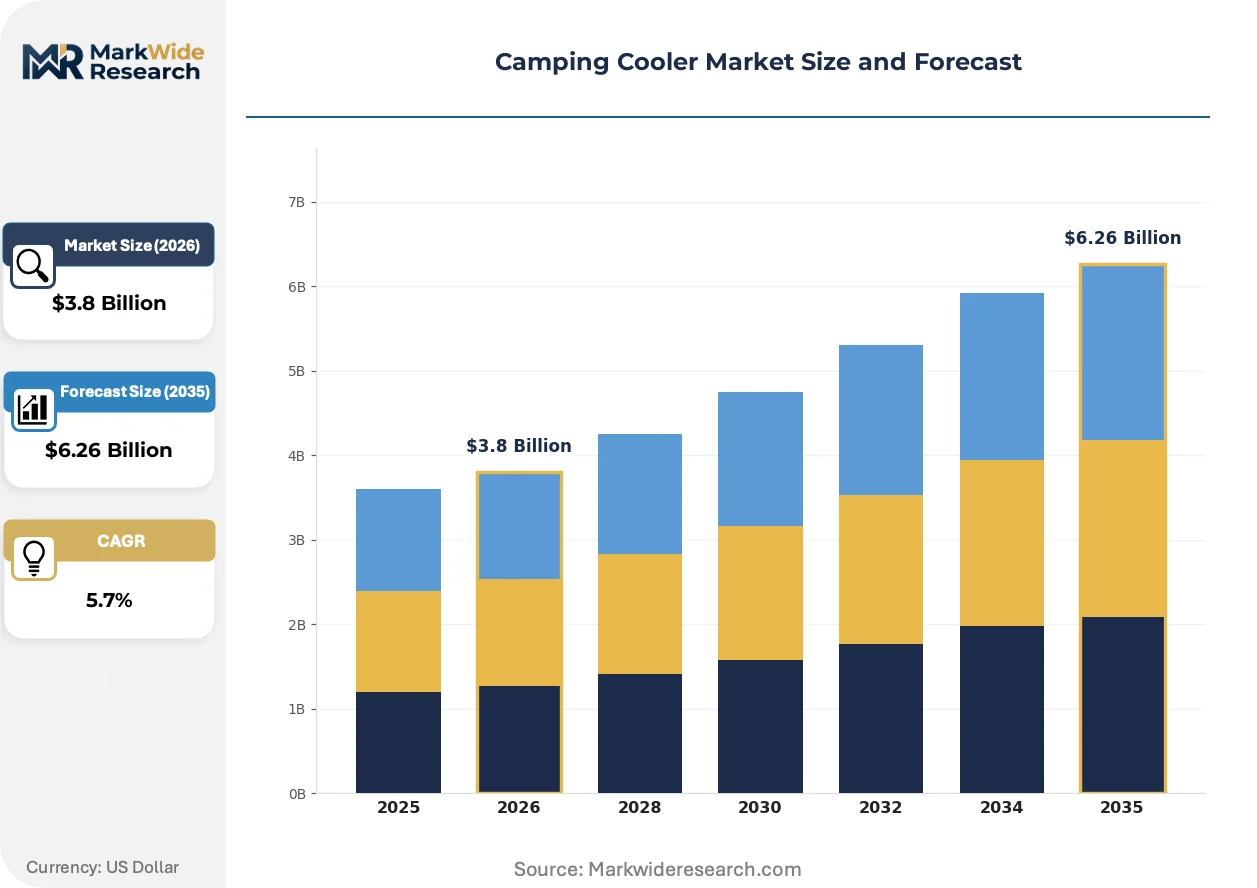
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Cooler, Hard Cooler, Electric Cooler, Insulated Cooler Material: Polyethylene, Aluminum, Stainless Steel, Fabric Capacity: 20 Quart, 50 Quart, 100 Quart, 150 Quart Power Source: Battery-Powered, Manual, Propane, Solar |
| Companies Covered | Igloo, Dometic, YETI, Canyon Coolers, Everich Outdoor, RTIC, RovR, Pelican, Coleman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Cooler Market Emerging Trajectories
Digital thermal management systems are virtualizing traditional passive cooling architectures, enabling real-time temperature monitoring and adaptive power consumption that reshape how outdoor enthusiasts evaluate cooler performance beyond static ice retention metrics.
Smart compressor controllers with Bluetooth-enabled diagnostics are virtualizing conventional thermostat mechanisms, allowing backcountry operators and overland vehicle owners to monitor internal temperatures remotely and optimize battery draw across multi-day expeditions. This capability compresses the perceived value gap between premium hard coolers and electric alternatives by shifting purchase criteria toward connectivity and control precision.
California's Title 20 appliance efficiency regulations and the EPA's Energy Star certification pathway for battery-powered cooling devices are elevating compliance costs for electric cooler entrants while creating technical barriers for import-dependent suppliers. Manufacturers are responding by redesigning power systems around variable-speed compressors and advanced insulation geometries that meet threshold performance standards without sacrificing portability.
Direct-to-consumer channel expansion is displacing traditional outdoor retail distribution for premium cooler brands, with manufacturers investing in owned digital platforms that capture margin previously allocated to wholesale partners. This shift concentrates marketing spend on content-driven community building rather than slotting fees, with the United States market showing the most pronounced channel migration as national park visitation drives online research behavior.
Camping Cooler Market Segmentation
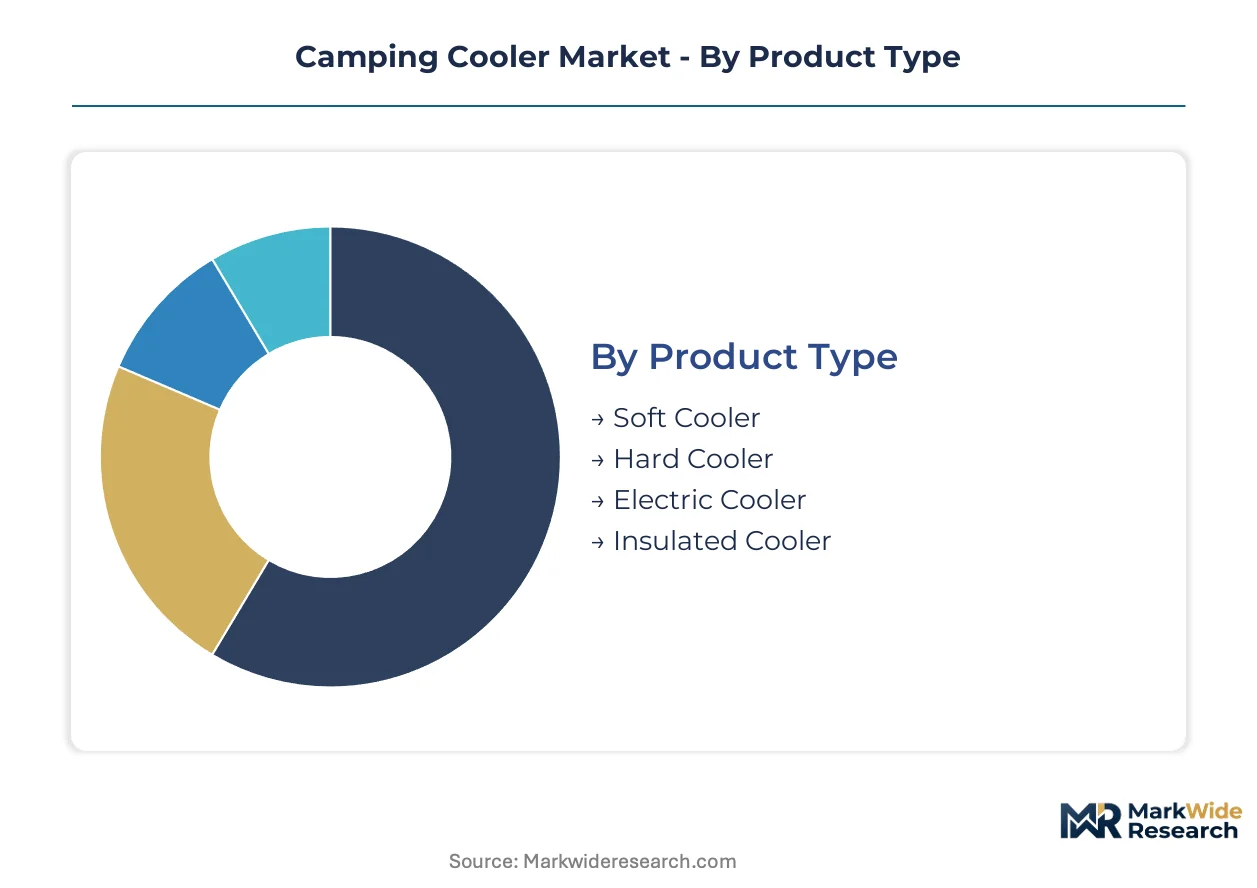
Camping cooler purchasing decisions split across thermal performance requirements, portability constraints, and power availability at destination. Expedition operators, overland vehicle owners, and casual campers each prioritize different segment combinations based on trip duration and access to grid electricity.
Product Type:
Backcountry use-cases span day-trips to multi-week expeditions, driving divergent demands for weight minimization versus ice retention endurance.
- Hard Cooler:Rotomolded polyethylene construction with polyurethane foam injection achieves ice retention exceeding seven days. National park visitation and dispersed camping permit growth in the United States concentrate demand for expedition-grade durability.
- Electric Cooler:Compressor-based refrigeration enabled by lithium-ion power density gains delivers grid-independent cooling without ice replenishment. California's Title 20 appliance efficiency regulations are accelerating product refresh cycles for power system optimization.
- Soft Cooler:Ultralight insulated fabric construction serves ultralight backpackers and day-trip segments where weight minimization overrides multi-day thermal performance.
- Insulated Cooler:Passive thermal retention designs without active cooling components target budget-conscious recreational users with shorter-duration cooling needs.
Established volume favors Hard Cooler; emerging adoption favors Electric Cooler.
Material:
Construction substrate selection trades off durability premiums against weight penalties and manufacturing cost structures.
- Polyethylene:Rotomolded linear low-density formulations dominate hard cooler manufacturing, inheriting protective case construction expertise from adjacent industrial equipment sectors.
- Aluminum:Lightweight metal fabrication serves marine and overland vehicle applications where corrosion resistance and structural rigidity justify material cost premiums.
- Stainless Steel:Premium-grade alloy construction targets commercial foodservice and remote worksite provisioning where sanitation standards and impact resistance are non-negotiable.
- Fabric:Multi-layer insulated textiles with welded seams enable soft cooler form factors that compress for storage and minimize carry weight.
Polyethylene commands current production volumes; aluminum gains share in specialized applications.
Capacity:
Volume requirements scale with group size, trip duration, and resupply access points across dispersed camping destinations.
- 50 Quart:Mid-range capacity serves weekend family camping and small-group backcountry expeditions as the default recreational purchase tier.
- 20 Quart:Compact personal capacity targets solo day-trippers and supplementary beverage storage alongside larger primary units.
- 100 Quart:Extended-duration capacity supports hunting outfitters and multi-week expedition operators with bulk provisioning requirements.
- 150 Quart:Maximum-volume configurations serve commercial marine operators and remote construction crews with centralized food safety responsibilities.
50 Quart dominates household penetration; 100 Quart expands most quickly in commercial procurement.
Power Source:
Energy input modality determines deployment flexibility across grid-connected, vehicle-integrated, and fully off-grid use environments.
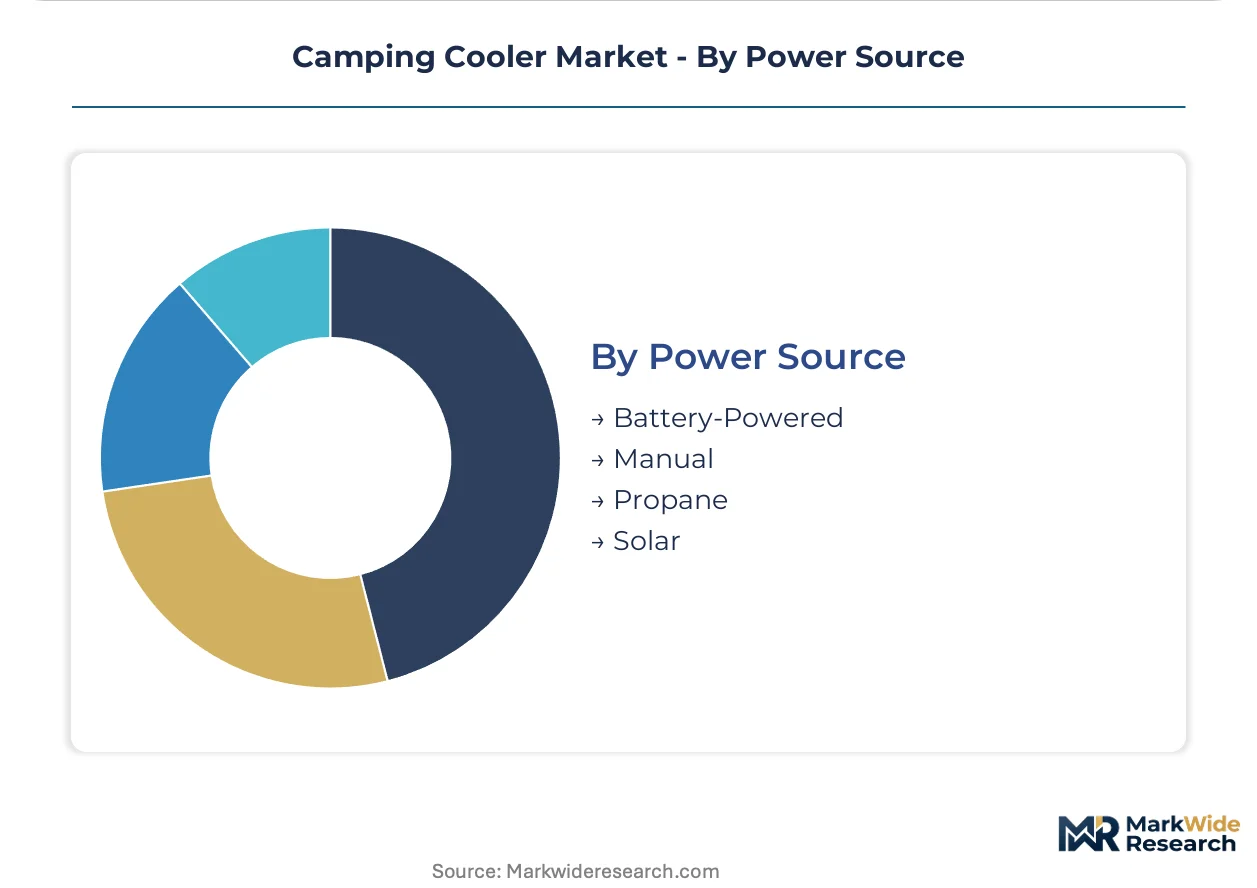
- Battery-Powered:Rechargeable lithium-ion systems with variable-speed compressor controllers enable EPA Energy Star certification pathways and Bluetooth-enabled thermal diagnostics.
- Manual:Zero-energy passive cooling relies entirely on ice replenishment, maintaining relevance in ultralight and emergency preparedness segments.
- Propane:Absorption-cycle refrigeration using portable fuel canisters serves extended off-grid deployments where battery recharging is impractical.
- Solar:Photovoltaic-integrated systems with MPPT charge controllers target overland vehicle owners and basecamp installations with predictable sun exposure.
Battery-Powered systems claim steepest expansion trajectory; Manual retains cost-sensitive entry segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Title 20 appliance efficiency regulations are accelerating electric cooler redesign cycles across North America. Adventure tourism operators in the United States are expanding equipment procurement budgets as national park visitation climbs.
United States
Dispersed camping permit issuance and national park visitation are concentrating demand for grid-independent food safety solutions. The EPA's Energy Star certification pathway for battery-powered cooling devices elevates compliance costs for electric cooler entrants. Austin, Texas hosts a cluster of direct-to-consumer cooler brands investing in owned digital platforms.
Germany
Overland vehicle owners and marine operators are driving demand for compressor-based portable refrigeration with low-GWP refrigerants. The EU F-Gas Regulation phase-down schedule creates technical barriers for import-dependent suppliers. Bavaria's automotive supplier ecosystem is adapting variable-speed compressor controllers from vehicle climate systems for portable cooling applications.
China
Domestic adventure tourism participation is rising as middle-class outdoor recreation spending expands. The country's national standards body is developing efficiency testing protocols for battery-powered cooling appliances aligned with international certification pathways. Guangdong Province's lithium-ion battery manufacturing cluster is enabling supply chain integration for electric cooler power systems.
Canada
Remote worksite provisioning and northern expedition operators require multi-day ice retention systems for off-grid deployments. Health Canada's refrigerant handling protocols impose containment requirements on electric cooler distribution networks. British Columbia's backcountry guiding industry is scaling equipment budgets to meet rising international tourism demand.
Australia
Overland vehicle modification culture and remote camping participation are driving demand for solar-integrated cooling systems. The Therapeutic Goods Administration's quality frameworks influence durability expectations for expedition-grade equipment. Queensland's marine tourism operators are upgrading provisioning systems for extended Great Barrier Reef expeditions.
Camping Cooler Market Vendor Landscape
On the supply side, the industry is tiered across premium heritage brands, value-engineered challengers, and specialized fabricators. Rotomolded construction expertise and compressor-based refrigeration capabilities define the two primary capability clusters. Strategic moves center on direct-to-consumer channel migration and attachment ecosystem expansion to defend margin pools against electric cooler substitution.
Within the premium heritage tier, YETI and Pelican exemplify brand positioning built on durability premiums and protective case manufacturing lineage. RTIC occupies a position in the value-engineered challenger archetype, narrowing performance gaps without matching premium price points. Dometic anchors the specialized fabricator category with European origins and marine application expertise.
| Leading Market Players |
|---|
| Igloo |
| Dometic |
| YETI |
| Canyon Coolers |
| Everich Outdoor |
| RTIC |
| RovR |
| Pelican |
| Coleman |
| Others |
Supply Flow & Price Mechanics
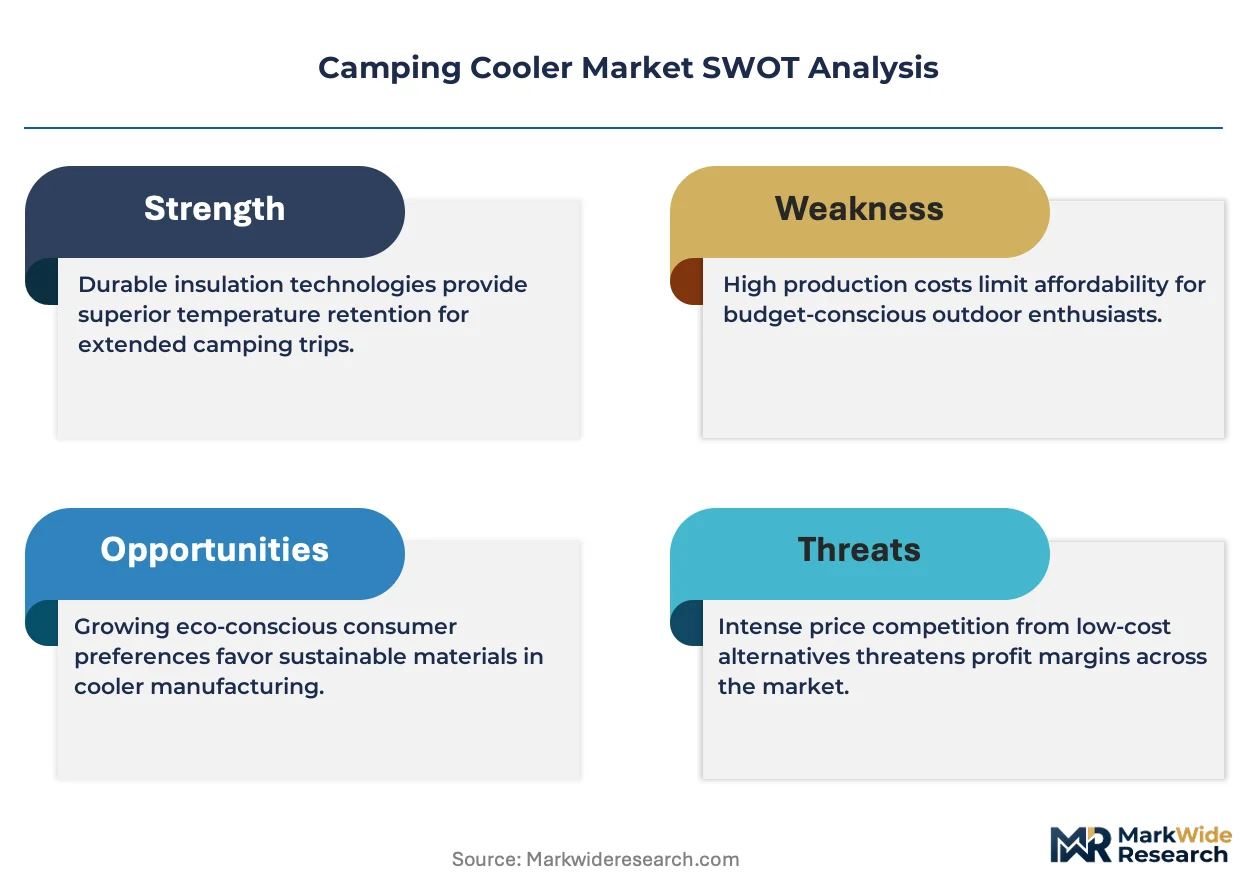
The Port of Long Beach freight corridor transmits resin cost volatility from Guangdong manufacturing clusters directly into rotomolded cooler landed costs, compressing margins for polyethylene-dependent producers while amplifying price spreads between battery-powered electric units and passive insulation alternatives.
Pricing Analysis
Certification level creates the primary spread between premium and value tiers, with EPA Energy Star qualification for electric coolers commanding material premiums over manual alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects durability grade, attachment ecosystem breadth, and compressor efficiency ratings. Cost compression in mid-tier hard coolers intensifies as lithium-ion power density gains narrow the performance gap against passive ice-retention systems. Casual campers exhibit highest price sensitivity, while expedition operators prioritize thermal performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with rotational molding specialists in Mexico and domestic fabricators in Texas, with final assembly increasingly shifting to Guangdong for electric cooler power system integration. Polyethylene resin, lithium-ion battery packs, and variable-speed compressor modules constitute critical input dependencies. Single-source vulnerability concentrates in refrigerant compressor supply from Bavarian automotive climate suppliers. Distribution runs through direct-to-consumer platforms and selective outdoor specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camping cooler market fragmentation creates entry niches as adventure tourism procurement diversifies beyond legacy rotomolded brands toward digitally native electric alternatives.
For Market Incumbents: Pre-empt electric cooler substitution by acquiring compressor controller capabilities from automotive climate suppliers, while hardening attachment ecosystem lock-in through expedition-grade accessory bundles. California Title 20 compliance investment represents the priority defensive lever against import-dependent challengers. For New Entrants and Emerging Players: Australian overland vehicle modification culture offers underpenetrated white-space for solar-integrated cooling systems, with Queensland marine tourism operators as anchor accounts. Target EU F-Gas Regulation alignment as technical differentiation against US-centric competitors. Direct-to-consumer content marketing outperforms wholesale slotting fees for brand building. For Investors and Strategic Acquirers: Carve-out targets emerge from protective case manufacturers with dormant rotomolded expertise and marine equipment divisions seeking outdoor recreation exposure. Five-to-ten year viability hinges on battery chemistry evolution rather than insulation material innovation. Signal to monitor: dispersed camping permit issuance velocity in US national parks.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | YETI's owned digital channel captures margin previously allocated to REI and Bass Pro Shops wholesale partners. |
| Variable-Speed Compressor Integration | Dometic's adaptation of Bavarian automotive climate technology enables California Title 20 compliance pathways. |
| Attachment Ecosystem Expansion | RovR's wheel and dry-bin accessories defend hard cooler margin pools against electric substitution pressure. |
| Low-GWP Refrigerant Transition | EU F-Gas Regulation alignment creates technical barriers for import-dependent Chinese electric cooler suppliers. |
| Asset-Light Leasing Model | Subscription-based equipment access reshapes competitive dynamics toward recurring revenue in expedition operator segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade records, EPA Energy Star certification databases, and national park visitation statistics. Conversations with backcountry expedition operators, outdoor retail category buyers, rotomolded manufacturing plant managers, and lithium-ion battery procurement leads informed demand-side validation. Bottom-up unit economics modeling triangulated against top-down adventure tourism expenditure estimates.
Forecast inputs span product type segmentation across hard, electric, soft, and insulated configurations; capacity tier distribution from 20-quart personal units to 150-quart commercial marine systems; and power source modality including battery-powered, manual, propane, and solar variants. CAGRs derive from interpolation between historical permit issuance trends and projected lithium-ion cost curves across the analysis window. Regional modeling incorporates California Title 20 compliance cost pass-through assumptions and EU F-Gas Regulation phase-down schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated battery manufacturers or protective case diversifiers would shift outcomes beyond modeled ranges. Cross-checking against backcountry guiding industry equipment budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
New Zealand Camping Equipment Market
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
US Backpacks Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Bicycle Bags and Bag Packs Market
Outdoor Gear
Diving Regulator Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
China Camping Equipment Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Japan Camping Tent Market