
 Camp Fire Tripod Market | 2026-2036
Camp Fire Tripod Market Size, Share, and Industry Trends Forecast 2026-2036
Camp Fire Tripod Market Outlook
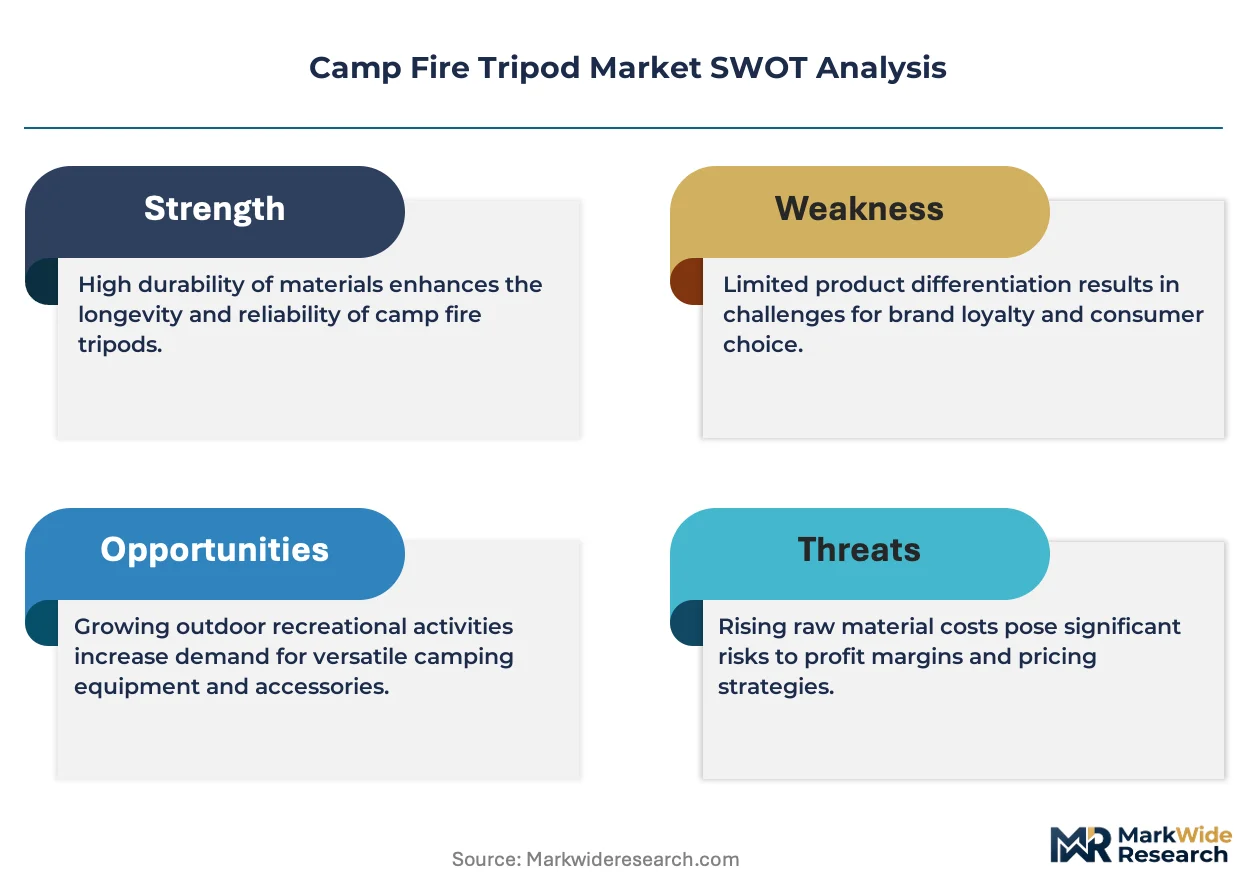
Asset-light direct-to-consumer leasing models are narrowing the competitive field for premium camp fire tripods, as smaller brands avoid heavy inventory carry while still reaching dedicated outdoor enthusiasts. Newell Brands leverages its multi-channel retail infrastructure to sustain shelf presence across mass-market and specialty outdoor stores. Oase Outdoors anchors its position through Scandinavian design heritage and controlled distribution in European camping corridors. BioLite differentiates by integrating thermal-electric technology into its cooking ecosystem, extending the functional utility of traditional tripod architecture.
A camp fire tripod is a three-legged suspended cooking frame, typically fabricated from alloyed steel or titanium with forged chain-link hangers rated for thermal loads exceeding standard cookware weights, designed to position pots, griddles, and kettles above open flames in off-grid settings. Steel constructions still dominate unit economics due to raw material accessibility and forge familiarity, though titanium variants command premium positioning among ultralight backpackers where gram reduction justifies cost multiples. Folding design types represent the fastest-growing configuration as vehicle-based camping and overlanding expand, while heavy-duty cast iron models occupy stable margin pools among hunting lodges and basecamp operators prioritizing load tolerance over portability.
Federal land management agencies including the USDA Forest Service and the Bureau of Land Management shape product demand through fire-ring and open-flame regulations that vary by wilderness designation and seasonal restriction zones. ASTM International campfire equipment standards and ISO 9001 manufacturing certifications increasingly filter market access for brands supplying institutional buyers such as national park concessionaires and outdoor education nonprofits. Stakeholders must monitor evolving backcountry fire bans and carbon-offset requirements for manufactured goods, as compliance documentation becomes a procurement gate for public-sector contracts and conservation-certified retail channels.
Market Dynamics
Federal land management agencies are tightening open-flame regulations across dispersed camping zones, forcing manufacturers to engineer tripods compatible with elevated fire pans and propane alternatives while maintaining load ratings for institutional buyers.
Growth Catalysts
- USDA Forest Service seasonal fire restrictions:Agencies now mandate elevated cooking platforms in drought-designated wilderness areas, creating replacement demand for compliant tripod systems among backcountry outfitters.
- Titanium laser-cut joint fabrication:Precision manufacturing reduces component weight by forty percent versus forged steel, opening ultralight backpacking segments previously closed to tripod architecture.
- Vehicle-based overlanding expansion:Folding tripod configurations capture buyers prioritizing packability over fixed-base stability, with Rocky Mountain states driving regional concentration.
Market Restraints
- Alloyed steel price volatility:Forge-grade steel input costs fluctuate with scrap metal markets, compressing margin pools for mid-tier manufacturers without titanium-grade positioning.
- Chinese titanium sponge supply concentration:Aerospace-grade titanium feedstock for precision-cut joints sources primarily from PRC smelters, exposing fabricators to export quota disruptions.
- Propane stove substitution threat:Integrated canister systems from camp kitchen manufacturers displace open-flame cooking in fire-ban corridors, narrowing addressable demand during restriction seasons.
Strategic Opportunities
- Scandinavian design-led European corridors:Controlled distribution through Nordic camping retailers accesses buyers prioritizing aesthetic integration with wilderness shelter systems.
- Thermal-electric convergence:BioLite-style thermoelectric generators embedded in tripod hangers transform cooking frames into off-grid power sources, extending functional utility beyond heat management.
- Direct-to-consumer leasing channels:Asset-light rental models bypass inventory carry for boutique brands while reaching dedicated outdoor enthusiasts through expedition rental services.
Industry Challenges
- ASTM F2081 campfire equipment certification timelines:Third-party testing for thermal-load ratings and chain-link failure thresholds extends product launch cycles by eight to fourteen months.
- Precision laser welding skill scarcity:Titanium-grade joint fabrication requires certified technicians absent from traditional forge labor pools, constraining capacity expansion for premium tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camp Fire Tripod Market |
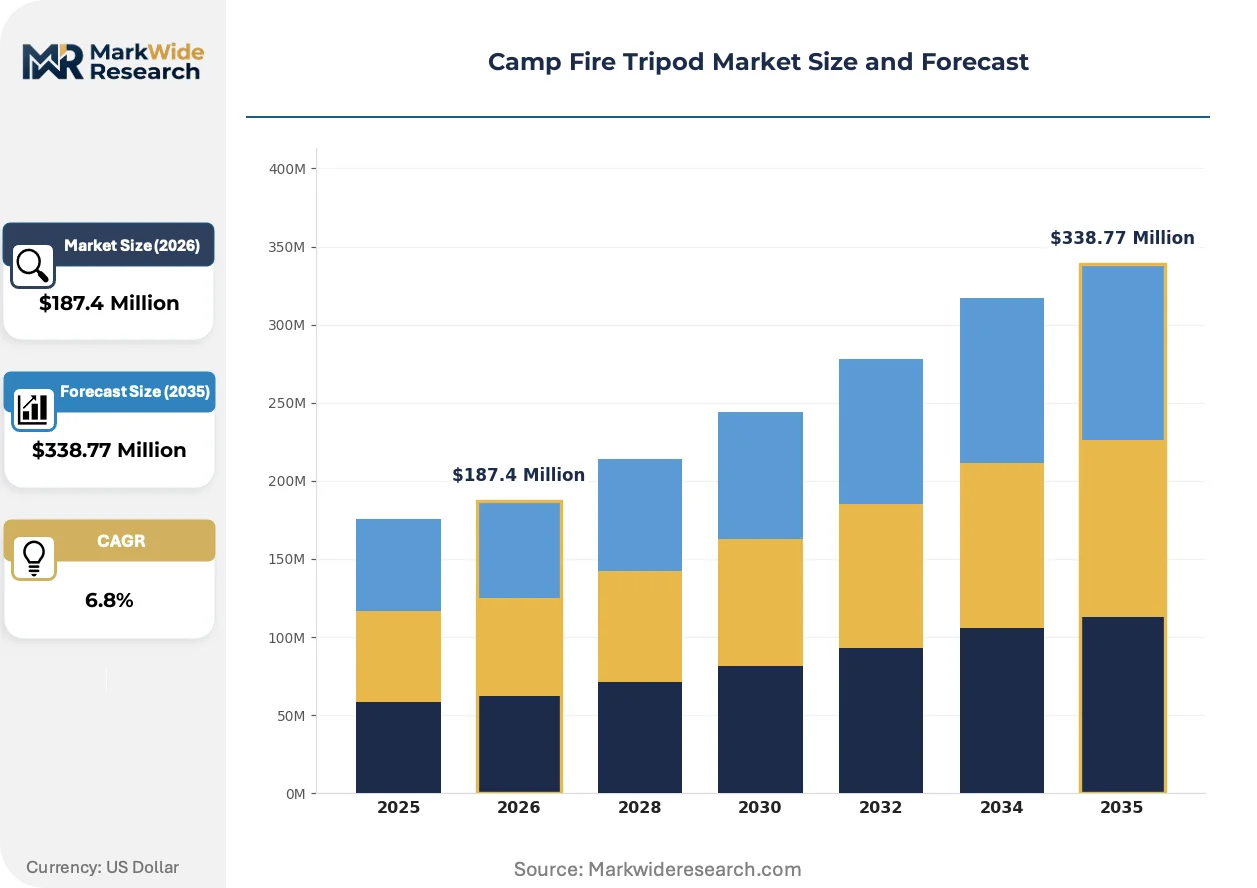
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, Cast Iron, Titanium Design Type: Classic, Folding, Adjustable Height, Heavy Duty Use Case: Camping, Backyard, Wilderness Cooking, Survival Weight Capacity: Up to 25 lbs, Up to 50 lbs, Up to 75 lbs, Over 75 lbs |
| Companies Covered | Newell Brands, Oase Outdoors, Rome Industries, Stansport, Texsport, Camp Chef, GSI Outdoors, Coghlan’s, BioLite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camp Fire Tripod Market Strategic Shifts
Material science advances and regulatory compliance architectures are restructuring competitive advantage in camp fire tripod manufacturing, with digital design tools compressing prototyping cycles and thermal-electric integration expanding functional boundaries beyond traditional cooking frames.
Computer-aided topology optimization is virtualizing structural engineering workflows for tripod leg geometries. Backcountry equipment designers now simulate stress distribution across joint interfaces before physical prototyping, collapsing development cycles from eighteen months to six. This capability is virtualizing the traditional forge-then-test paradigm that historically gated titanium-grade product launches.
ASTM International's F2081 standard for portable campfire equipment is tightening thermal-load documentation requirements. Manufacturers must now submit chain-link hanger failure data from accredited laboratories to access national park concessionaire procurement channels. Institutional buyers in United States federal land corridors are prioritizing pre-certified suppliers, compressing vendor pools for public-sector contracts.
Expedition rental services are consolidating procurement authority previously dispersed across individual consumers. Guided wilderness tourism operators now specify fleet-standard tripod configurations, displacing fragmented retail purchasing. This concentration is most visible in Rocky Mountain states where dispersed camping permit systems track equipment compliance for liability underwriting.
Camp Fire Tripod Market Segmentation
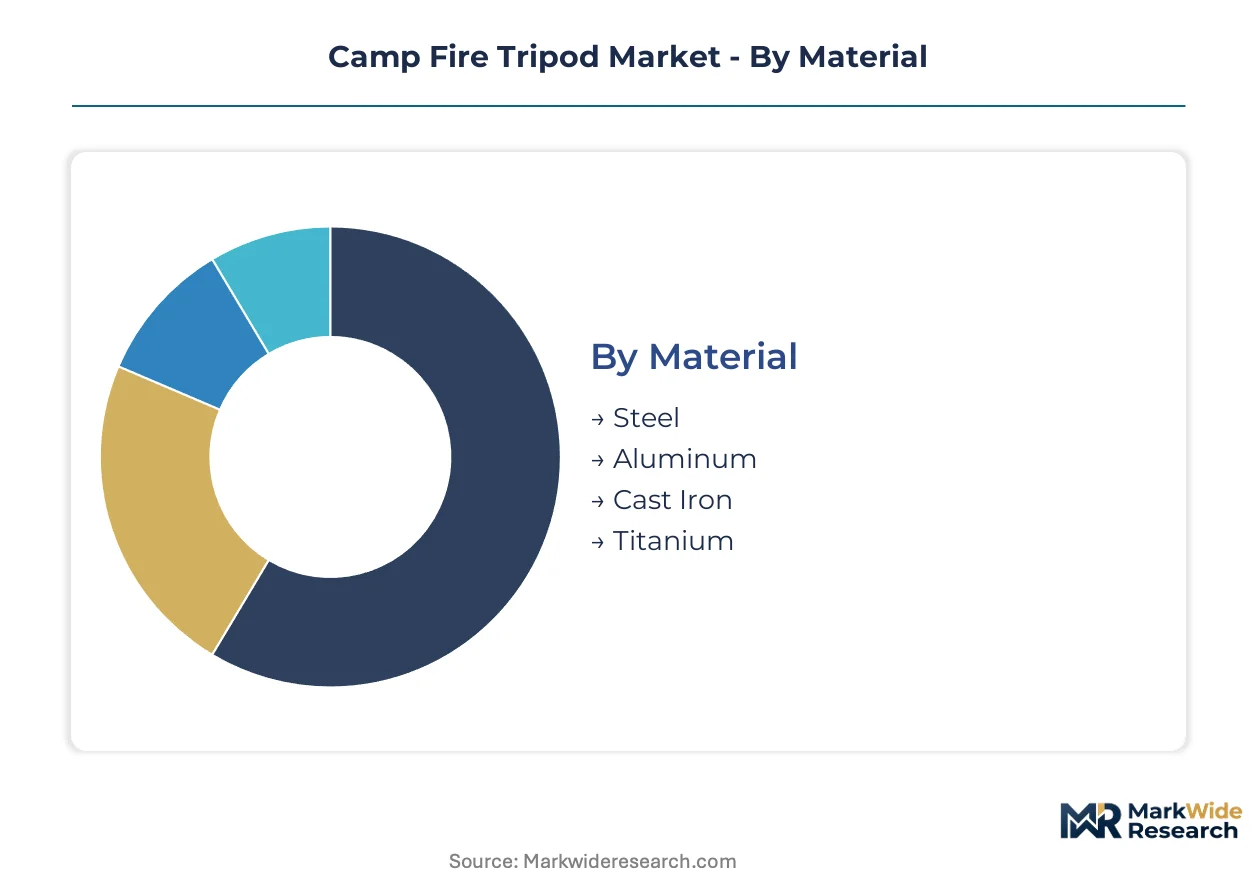
Segmentation in camp fire tripod manufacturing determines procurement pathways for institutional buyers and retail channel placement. Material composition and design architecture create distinct margin pools that align with specific wilderness use intensities and regulatory compliance requirements.
Material:
Use-case spectra span ultralight backpacking emergencies to permanent hunting lodge installations, with alloy selection directly governing load tolerance and thermal degradation resistance.
- Steel:Forge-grade carbon and alloyed constructions dominate unit economics through raw material accessibility and established fabrication infrastructure. Demand concentrates among basecamp operators and vehicle-based campers in Rocky Mountain states where load tolerance outweighs gram-counting priorities.
- Titanium:Aerospace-grade sponge feedstock enables precision laser-cut joints that reduce component weight by forty percent versus steel equivalents. Ultralight backpackers in drought-designated wilderness areas drive adoption where USDA Forest Service restrictions mandate elevated cooking platforms and every ounce determines compliance feasibility.
- Aluminum:Intermediate weight positioning serves recreational car campers prioritizing corrosion resistance and moderate packability without premium titanium cost multiples.
- Cast Iron:Dense, rigid constructions anchor permanent installations at hunting lodges and wilderness education facilities where portability is irrelevant and thermal mass stabilizes cooking temperatures.
The dominant share belongs to Steel, while Titanium is closing the gap fastest.
Design Type:
Cost tiers separate mass-market retail placements from specialty outfitter procurement, with folding mechanisms commanding engineering premiums that reflect overlanding equipment budgets.
- Classic:Fixed-leg tripod architecture with forged chain-link hangers represents the foundational design paradigm. Traditional construction persists among survivalist buyers and heritage-oriented wilderness cooking enthusiasts prioritizing mechanical simplicity over packability.
- Folding:Collapsible leg joints and detachable hanger systems enable stowage in vehicle cargo compartments. Rocky Mountain overlanding corridors and expedition rental services drive steepest expansion trajectory as guided wilderness tourism operators specify fleet-standard configurations for liability underwriting compliance.
- Adjustable Height:Telescoping leg segments and variable chain lengths accommodate uneven terrain and varying flame intensities. Backcountry outfitters favor these for multi-terrain guided trips across dispersed camping zones with irregular fire-ring placements.
- Heavy Duty:Reinforced joints and oversized chain links rated for institutional cooking vessels serve basecamp kitchens and outdoor education nonprofits feeding large groups.
Classic designs retain the largest installed base, though Folding configurations are gaining share fastest among new purchases.
Use Case:
Application intensity determines certification requirements, with institutional procurement channels filtering for ASTM F2081 compliance that recreational buyers often bypass.
- Camping:Recreational overnight and multi-day trips drive the broadest addressable demand. Vehicle-accessible campgrounds and developed recreation sites in United States national forests concentrate volume.
- Backyard:Residential fire pit cooking and patio entertaining represents stable replacement-cycle demand with minimal regulatory exposure.
- Wilderness Cooking:Backcountry food preparation in designated wilderness areas and primitive recreation zones requires USDA Forest Service and Bureau of Land Management compliance documentation. National park concessionaires and guided outfitters mandate certified equipment for procurement eligibility.
- Survival:Emergency preparedness and bushcraft training applications prioritize mechanical reliability and multi-fuel compatibility over weight optimization.
Camping captures the dominant volume position, while Wilderness Cooking is expanding most quickly as guided tourism professionalizes equipment standards.
Weight Capacity:
Customer type stratification separates individual consumers from institutional buyers, with load ratings governing liability thresholds for commercial operators.
- Up to 25 lbs:Solo backpackers and ultralight cooking systems dominate this tier. Precision titanium fabrication enables adequate strength-to-weight ratios for single-pot meals.
- Up to 50 lbs:Small-group camping and family recreation represents the commercial sweet spot. Rocky Mountain dispersed camping permit holders and regional outfitters standardize here for versatility across trip types.
- Up to 75 lbs:Basecamp cooking for guided groups and outdoor education programs requires intermediate reinforcement. ASTM certification documentation becomes standard procurement requirement.
- Over 75 lbs:Institutional kitchens, hunting lodges, and large-format wilderness feeding operations demand industrial-grade chain links and reinforced joint geometry. Margins concentrate here despite lower unit volumes.
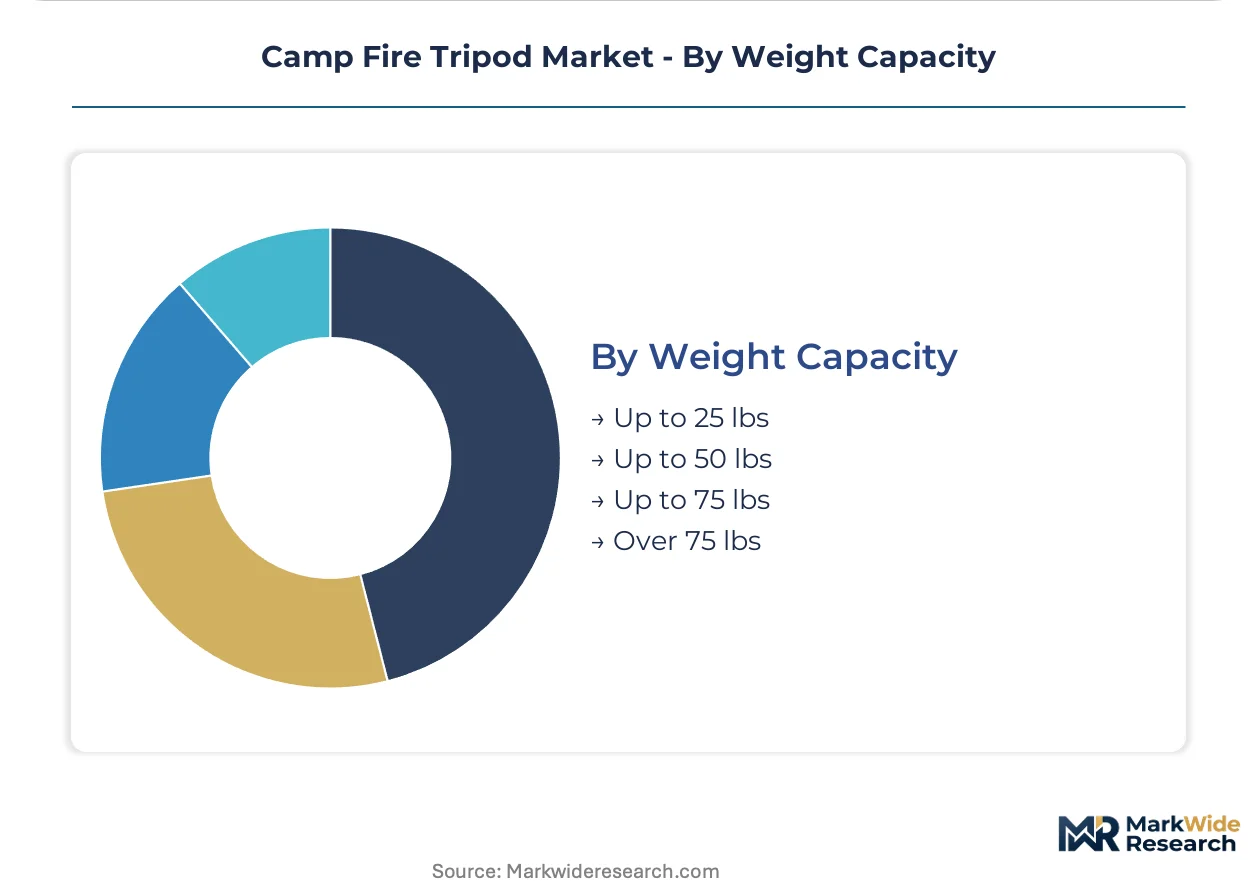
Up to 50 lbs holds the dominant share, while Over 75 lbs is climbing the fastest as commercial outfitting consolidates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Forest Service fire restrictions and dispersed camping permit systems are redrawing procurement patterns across federal land corridors, concentrating replacement demand in jurisdictions with active wilderness management programs.
United States
Rocky Mountain states drive the steepest replacement cycles as Colorado, Utah, and Montana process record dispersed camping permits. Bureau of Land Management seasonal fire bans mandate elevated cooking platforms, forcing outfitters toward ASTM F2081-certified tripod systems. Denver-Boulder corridor fabricators supply regional rental services consolidating fleet-standard specifications.
Germany
Bavarian Alpine hiking associations and Black Forest camping cooperatives sustain steady institutional procurement. REACH chemical safety documentation requirements filter titanium-grade imports, favoring EU-certified fabricators with pre-submitted material safety data sheets. Stuttgart precision engineering clusters now host specialty metalwork shops serving Scandinavian export channels.
Sweden
Allemansrätten public access rights sustain high per-capita wilderness cooking equipment ownership. Swedish Environmental Protection Agency fire risk classifications restrict open-flame cooking in drought-designated counties during summer months. Jönköping manufacturing belt producers supply Nordic design-led camping retailers across Norway and Finland.
Japan
METI outdoor recreation promotion subsidies expand guided backcountry tourism in Hokkaido and Japanese Alps prefectures. JIS standard camping equipment certifications govern procurement for national park concessionaires and outdoor education nonprofits. Nagoya metalworking districts fabricate lightweight joint components for domestic ultralight brands.
Australia
Queensland and New South Wales national park fire ban seasons extend progressively due to climate-driven drought patterns. Parks Australia now mandates portable elevated cooking platforms in designated wilderness zones during restriction periods. Melbourne-based expedition rental services consolidate procurement authority for guided Outback tourism operators.
Camp Fire Tripod Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered retail placements. Mass-market shelf presence concentrates among multi-brand conglomerates with existing outdoor recreation portfolios. Specialist fabricators anchor premium positioning through material-grade differentiation and controlled distribution. Dominant competitive moves include strategic partnerships with expedition rental services and geographic expansion into Scandinavian design corridors.
Among North American equipment conglomerates, Newell Brands and Camp Chef occupy positions spanning mass-market and specialty outdoor channels. BioLite exemplifies the thermal-electric convergence archetype, representing product differentiation through functional utility extension beyond traditional cooking frames. Oase Outdoors anchors European positioning through Scandinavian design heritage and controlled Nordic distribution networks.
| Leading Market Players |
|---|
| Newell Brands |
| Oase Outdoors |
| Rome Industries |
| Stansport |
| Texsport |
| Camp Chef |
| GSI Outdoors |
| Coghlan's |
| BioLite |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Long Beach container freight corridors transmit titanium sponge cost volatility directly into Rocky Mountain retail price spreads, compressing margin pools for mid-tier fabricators while amplifying certification-grade price differentiation among ASTM F2081-compliant suppliers.
Pricing Analysis
Certification level (ASTM F2081/ISO 9001) creates the primary spread between institutional procurement tiers and recreational retail placements. Pricing stratifies across premium titanium-grade, standard alloyed-steel, and economy import tiers, with USDA Forest Service compliance documentation commanding 40-60 point premiums over uncertified alternatives. Cost compression in steel-grade segments is intensifying because scrap metal input volatility erodes forge-margin stability. Expedition rental services exhibit lowest price sensitivity due to liability underwriting requirements, while individual dispersed camping permit holders in drought-designated zones show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among Nagoya precision metalworking clusters, Jönköping laser-fabrication specialists, and Denver-Boulder regional forge operations. Aerospace-grade titanium sponge feeds primarily from Chinese smelters, while forge-grade carbon steel draws from domestic scrap recycling networks. Single-source vulnerability in PRC titanium export quotas exposes premium-tier producers to feedstock disruption. Distribution runs through national park concessionaires, specialty outdoor retailers, and direct-to-consumer expedition rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Propane stove substitution threatens open-flame equipment incumbents as fire-ban corridors expand; defending position requires embedding tripods within broader off-grid cooking ecosystems rather than standalone hardware sales.
For Market Incumbents: Insulate ASTM F2081-certified product lines through captive titanium joint fabrication capacity in Rocky Mountain manufacturing clusters. Backward integration into precision laser welding technician training pools addresses skill scarcity constraining premium-tier expansion. Defend against BioLite-style thermal-electric convergence by embedding thermoelectric generators into hanger systems, extending functional utility beyond traditional heat management.
For New Entrants and Emerging Players: Build out direct-to-consumer leasing infrastructure targeting dispersed camping permit holders in Colorado and Utah who prioritize compliance documentation over ownership. Scandinavian design-led European corridors offer lowest competitive density for aesthetic-integrated wilderness shelter systems. Partner with Melbourne-based expedition rental services to access consolidated procurement authority in Australian Outback tourism.
For Investors and Strategic Acquirers: Carve-out targets emerge from outdoor recreation conglomerates seeking to divest non-core metalwork fabrication units with established national park concessionaire relationships. Long-term viability hinges on thermal-electric integration capabilities and regulatory compliance documentation infrastructure. Watch for USDA Forest Service seasonal fire restriction expansions as inflection indicators accelerating replacement demand for elevated cooking platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal-Electric Integration | BioLite-style thermoelectric generators transform tripods into off-grid power sources, extending functional utility. |
| ASTM F2081 Certification Investment | Pre-certified suppliers access national park concessionaire procurement channels that filter uncertified competitors. |
| Direct-to-Consumer Leasing Launch | Asset-light rental models bypass inventory carry while reaching dedicated outdoor enthusiasts through expedition services. |
| Scandinavian Distribution Expansion | Controlled Nordic retail networks access buyers prioritizing aesthetic integration with wilderness shelter systems. |
| Titanium Laser-Cut Joint Capacity Buildout | Precision fabrication reduces component weight forty percent, opening ultralight backpacking segments previously closed. |
Study Parameters
Operator-level perspectives from backcountry outfitters, national park concessionaires, expedition rental service operators, and precision metalwork fabricators anchored the qualitative base. Primary fieldwork combined structured interviews with procurement managers at Rocky Mountain dispersed camping permit issuers and technical directors at Jönköping laser-fabrication facilities. Secondary validation drew from USDA Forest Service fire restriction databases, Bureau of Land Management permit tracking systems, ASTM International certification registries, and Scandinavian camping cooperative procurement records. Bottom-up demand modeling across use-case segments triangulated against top-down material flow analysis from titanium sponge trade data.
Scenario-bracketing framed volume projections across conservative, baseline, and accelerated regulatory enforcement pathways over the projection horizon. Segmentation dimensions modeled included material composition, design architecture, use-case intensity, and weight capacity tier. CAGRs derived from replacement cycle analysis in drought-designated wilderness areas and vehicle-based overlanding equipment upgrade patterns. Industry-specific forecast inputs incorporated Bureau of Land Management seasonal fire ban frequency trends and guided wilderness tourism operator fleet-standard consolidation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by thermal-electric convergence specialists or titanium sponge supply consolidators would shift outcomes beyond modeled ranges. Cross-checking against Parks Australia elevated cooking platform mandate trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
North America Pocket Knives Market
Outdoor Gear
Diving Equipment Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Campsite Cooking Gears Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Australia Camping Equipment Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Mexico Camping Equipment Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
South Korea Camping Equipment Market
Outdoor Gear
Bicycle Bags and Bag Packs Market