
 North America Robotic Lawn Mower Market | 2026-2036
North America Robotic Lawn Mower Market Size, Share, and Industry Trends Forecast 2026-2036
North America Robotic Lawn Mower Market Analytics
FCC Part 15 certification for unlicensed radio frequency devices is rotating as a gatekeeping standard that filters which manufacturers can distribute connected robotic mowers across the United States. Husqvarna Group leverages its Automower ecosystem to sustain premium positioning through proprietary boundary-wire technology and cloud connectivity infrastructure. Deere & Company anchors its competitive stance through precision agriculture expertise that extends into autonomous turf management systems for golf and commercial landscapes. STIHL Inc. competes through dealer network density, controlling rural and suburban retail channels where hands-on service drives purchase decisions.
A robotic lawn mower constitutes an autonomous ground-based machine equipped with rechargeable battery packs, perimeter detection sensors, and programmable cutting decks typically ranging from 18 to 36 centimeters in width, designed to maintain turf surfaces without human steering intervention. These machines execute systematic or random-path navigation algorithms to trim grass to user-specified heights between 20 and 60 millimeters, serving residential property owners, commercial landscaping contractors, and municipal grounds departments seeking labor reduction. GPS-enabled navigation systems command the highest price tiers and fastest replacement cycles, as real-time kinematic positioning allows centimeter-level boundary mapping that eliminates physical wire installation. Battery-electric power sources dominate unit shipments across all end-user categories, while solar-hybrid configurations remain confined to premium residential and small commercial installations where extended runtime justifies module cost.
The EPA regulates small spark-ignition engine emissions under Phase 3 standards that effectively prohibit gasoline-powered robotic designs, while FCC Part 15 and Industry Canada RSS-210 govern wireless command protocols in the United States and Canada respectively. NHTSA and Transport Canada maintain peripheral oversight over autonomous vehicle classifications that occasionally intersect with commercial-grade mower deployment on public-access properties. OSHA state-plan jurisdictions in California, Michigan, and North Carolina impose additional workplace safety protocols for fleet operators deploying multiple units on commercial grounds. Stakeholders must monitor evolving municipal noise ordinances and pesticide-runoff regulations that could accelerate battery-electric adoption or restrict operating hours in dense suburban markets.
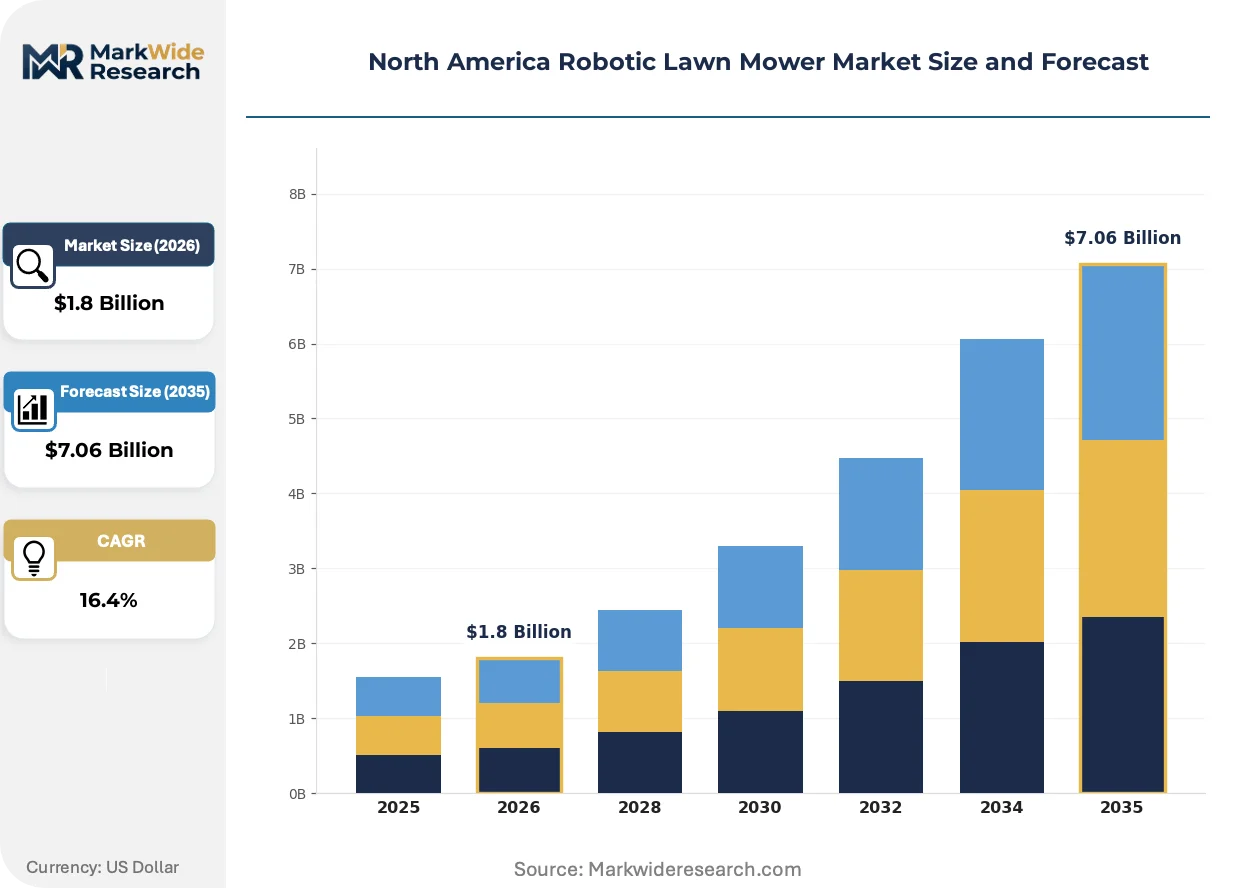
Market Dynamics
EPA Phase 3 emissions standards are compressing the competitive set by eliminating gasoline-powered alternatives, forcing manufacturers to consolidate around battery-electric architectures and wireless connectivity stacks.
Growth Catalysts
- FCC Part 15 Certification:Wireless command protocols for unlicensed RF devices create a technical moat that filters out undercapitalized entrants from the United States distribution network.
- Suburban Homeowner Density:Residential property owners across Texas, Florida, and California metropolitan corridors drive replacement cycles as lot sizes standardize around quarter-acre footprints optimal for autonomous coverage.
- Real-Time Kinematic GPS:Centimeter-level boundary mapping eliminates physical wire installation labor, collapsing deployment friction for landscaping contractors managing multiple residential accounts.
Market Restraints
- Lithium-Ion Cell Volatility:Cathode material costs and supply concentration in East Asian processing facilities compress margin structures for battery pack assembly.
- Perimeter Wire Legacy Infrastructure:Installed base of buried boundary systems creates switching friction that slows GPS-enabled unit penetration among existing robotic mower owners.
- Municipal Noise Ordinances:Operating hour restrictions in dense suburban jurisdictions limit runtime windows and compress effective cutting capacity per unit.
Strategic Opportunities
- Canadian Market Expansion:Industry Canada RSS-210 certification alignment with FCC standards creates near-zero incremental compliance cost for United States manufacturers entering Ontario and British Columbia.
- Golf Course Automation:Precision turf management requirements at private clubs and resort properties open fleet deployment contracts for commercial-grade units with slope-climbing chassis.
- Solar-Hybrid Configurations:Photovoltaic module integration extends runtime for premium residential installations in sun-intensive Southwestern states without grid tethering.
Industry Challenges
- RF Engineering Talent Scarcity:FCC pre-certification testing and antenna design expertise concentrates among a narrow pool of contract engineering firms, extending product development timelines.
- OSHA State-Plan Compliance:Fleet operators in California, Michigan, and North Carolina face divergent workplace safety protocols that fragment standard operating procedures across multi-state landscaping contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Robotic Lawn Mower Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Hybrid, Manual Technology: GPS, Ultrasonic, Bluetooth, LiDAR End User: Residential, Commercial, Industrial, Agricultural Power Source: Electric, Solar, Battery, Gasoline |
| Companies Covered | Husqvarna Group, Robert Bosch GmbH, Deere & Company, Honda Motor Company, STIGA S.p.A., Worx, Robomow, STIHL Inc., Gardena, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Robotic Lawn Mower Market Evolving Landscape
Wireless boundary systems are collapsing the installed cost gap between robotic and manual mowing, while regulatory pressure on emissions accelerates hardware architecture transitions.
RTK-GPS navigation modules are displacing buried perimeter wire as the dominant boundary establishment method across new installations. Suburban homeowners in sunbelt states adopt these systems at accelerated replacement cycles. The shift is compressing aftermarket service revenue streams previously tied to wire maintenance and seasonal reinstallation.
EPA Phase 3 small spark-ignition engine standards have eliminated gasoline-powered robotic designs from the United States market entirely. Manufacturers have consolidated engineering resources exclusively around battery-electric powertrains and thermal management systems. Commercial fleet operators in Texas and Florida now specify all-electric specifications for municipal grounds contracts.
Landscaping contractors are unbundling equipment ownership from service delivery, shifting toward equipment-as-a-service models where dealers retain capital risk. This restructuring concentrates purchasing power among regional dealer networks with fleet financing capabilities. The pattern is most visible across California metropolitan markets where labor cost pressures accelerate outsourcing decisions.
North America Robotic Lawn Mower Market Segmentation
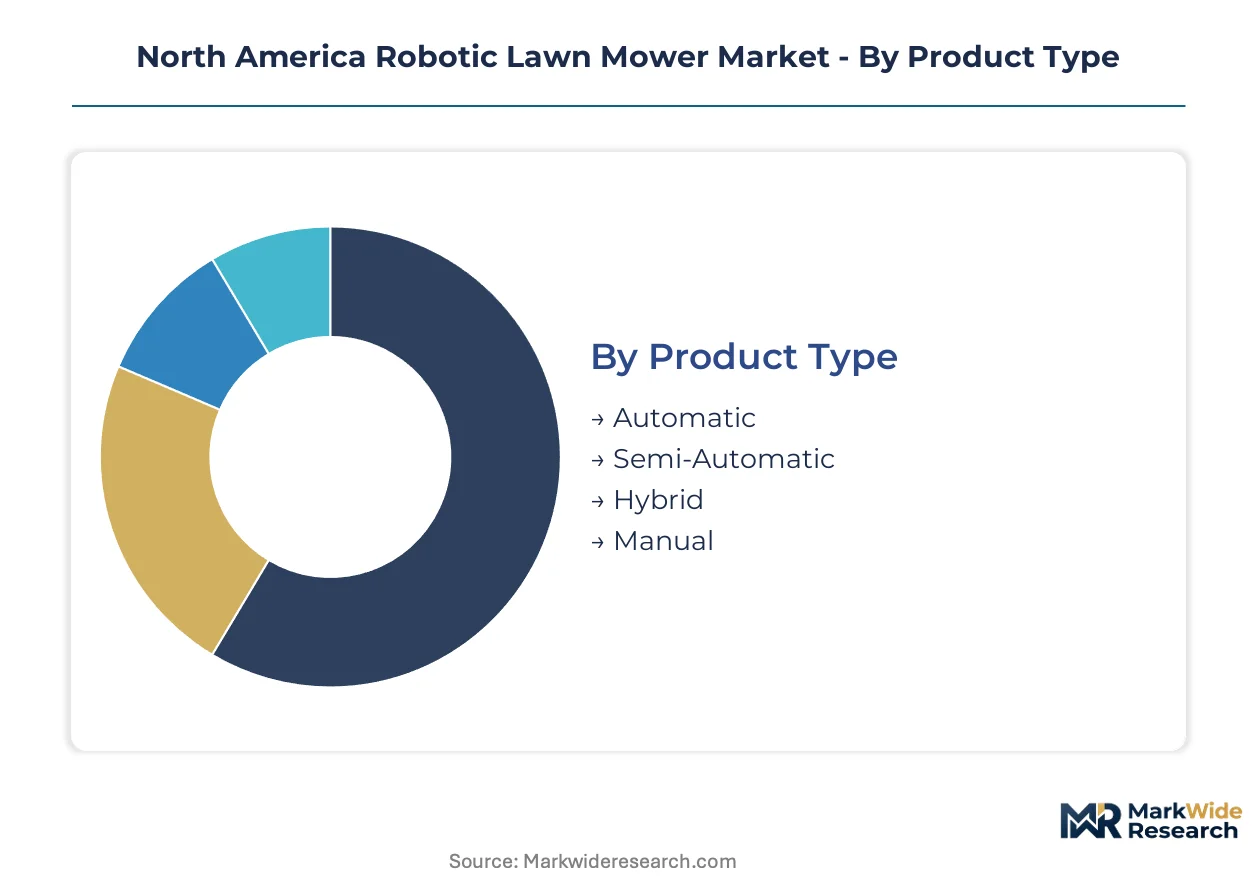
Segmentation in the North America robotic lawn mower market reveals how regulatory frameworks and property characteristics reshape purchasing patterns. EPA Phase 3 emissions standards and FCC Part 15 certification requirements filter viable product configurations, while lot sizes and terrain complexity determine technology adoption rates across buyer categories.
Product Type:
EPA Phase 3 standards and FCC wireless certifications create divergent compliance burdens that separate automatic systems from gasoline-dependent alternatives.
- Automatic:Fully autonomous units with programmable schedules and self-docking capabilities dominate suburban Texas and Florida installations. Residential homeowners with quarter-acre lots drive replacement cycles as wireless boundary systems eliminate installation labor.
- Semi-Automatic:Units requiring manual perimeter setup or supervised operation appeal to price-sensitive buyers in California metropolitan corridors. Landscaping contractors deploy these for multi-property accounts where GPS precision remains secondary to capital cost control.
- Hybrid:Dual-mode systems switch between autonomous and manual control for complex terrain navigation.
- Manual:Remote-controlled units without autonomous capability serve niche agricultural slope applications where operator judgment outweighs automation benefits.
Established volume favors Automatic; emerging adoption favors Semi-Automatic.
Technology:
Cost tier stratification separates premium positioning from mass-market penetration, with navigation precision as the primary price differentiator.
- GPS:Real-time kinematic positioning enables centimeter-level boundary mapping without physical wire installation. Suburban homeowners across sunbelt states adopt these systems at accelerated replacement cycles as dealer financing expands.
- Ultrasonic:Proximity detection systems navigate obstacle-rich environments through echolocation, appealing to commercial landscapers managing properties with irregular hardscaping.
- Bluetooth:Short-range connectivity supports basic command protocols for entry-tier residential units.
- LiDAR:Laser-based spatial mapping commands premium positioning for golf course and resort property applications requiring terrain contour recognition.
Volume concentrates in GPS-enabled configurations; steepest expansion trajectory belongs to LiDAR for commercial slope management.
End User:
Customer type determines fleet scale, service model, and regulatory exposure across deployment scenarios.
- Residential:Single-property owners across Texas, Florida, and California metropolitan corridors represent the primary volume base. Quarter-acre lot standardization and HOA landscaping requirements accelerate autonomous system adoption.
- Commercial:Landscaping contractors and property management firms deploy fleet configurations for multi-account coverage. Equipment-as-a-service restructuring concentrates purchasing power among regional dealer networks with financing capabilities.
- Industrial:Manufacturing facilities and logistics parks deploy perimeter-guard units for grounds maintenance adjacent to security zones.
- Agricultural:Orchard and vineyard operators utilize slope-capable chassis for terrain-mowing applications where labor availability constrains manual alternatives.
Residential commands current volume leadership; Commercial gains share fastest through fleet outsourcing restructuring.
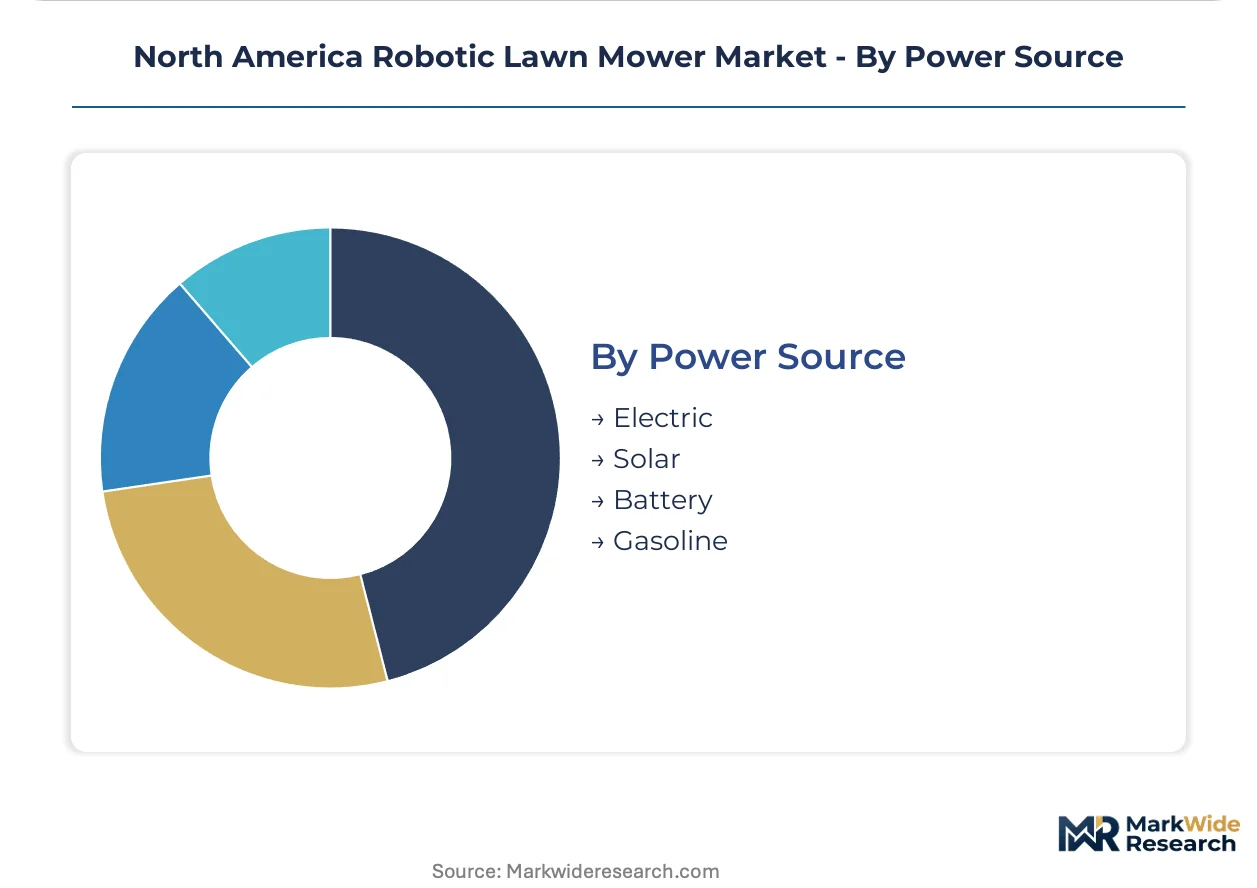
Power Source:
Supply concentration in East Asian battery processing facilities shapes margin structures and sourcing strategies across architecture types.
- Electric:Corded systems tethered to grid power serve small residential installations with reliable outlet access. California municipal noise ordinances and emissions restrictions accelerate specification for grounds contracts.
- Battery:Lithium-ion packs dominate unit shipments across all end-user categories, with thermal management systems as the critical engineering focus. Cathode material cost volatility compresses assembly margins for North American pack integrators.
- Solar:Photovoltaic module integration extends runtime for premium Southwestern installations without grid tethering.
- Gasoline:Small spark-ignition designs face effective prohibition under EPA Phase 3 standards, eliminating this category from new product development.
Battery architectures capture established volume; Solar configurations climb fastest among premium desert-state installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 emissions standards and FCC Part 15 certification requirements concentrate manufacturing and distribution investment within the United States, while Canadian regulatory alignment through Industry Canada RSS-210 opens near-zero incremental compliance pathways for cross-border expansion.
United States
Texas, Florida, and California metropolitan corridors generate the densest suburban homeowner demand as quarter-acre lot standardization accelerates autonomous system replacement cycles. FCC Part 15 certification for unlicensed RF devices filters distribution eligibility, compressing the viable manufacturer set. Dallas-Fort Worth and Houston dealer networks report the fastest fleet financing uptake among landscaping contractors restructuring toward equipment-as-a-service models.
Canada
Ontario and British Columbia residential markets adopt GPS-enabled units at accelerated rates as Industry Canada RSS-210 certification alignment eliminates incremental testing costs for United States manufacturers. Municipal noise ordinances in Toronto and Vancouver accelerate battery-electric specification for grounds maintenance contracts. Calgary and Edmonton metropolitan areas concentrate commercial fleet deployment for multi-property landscaping accounts.
Mexico
Nuevo León and Jalisco manufacturing clusters attract battery pack assembly investment as cathode material sourcing routes consolidate through Pacific port infrastructure. SEMARNAT emissions regulations for small engines lag EPA stringency, preserving gasoline-powered alternatives in price-sensitive segments. Mexico City metropolitan corridor drives residential demand as HOA landscaping requirements standardize across new suburban developments.
North America Robotic Lawn Mower Market Competitive Landscape
Player mix skews toward diversified outdoor power equipment conglomerates with established dealer network infrastructure. Market structure concentrates around three to five vertically integrated manufacturers controlling premium-tier positioning through proprietary navigation technologies and cloud connectivity ecosystems. Strategic archetypes separate wire-perimeter legacy specialists from RTK-GPS navigation innovators and solar-hybrid configuration pioneers. Competitive moves center on dealer financing capability expansion and fleet management software integration rather than hardware specification races.
Within the diversified conglomerate tier, Husqvarna Group and Deere & Company exemplify positioning through precision agriculture expertise extension and autonomous turf management system development. STIHL Inc. anchors rural and suburban retail channel control where hands-on service relationships drive purchase decisions. Robert Bosch GmbH occupies a position representing European engineering integration with battery-electric powertrain consolidation.
| Leading Market Players |
|---|
| Husqvarna Group |
| Robert Bosch GmbH |
| Deere & Company |
| Honda Motor Company |
| STIGA S.p.A. |
| Worx |
| Robomow |
| STIHL Inc. |
| Gardena |
| Others |
Value Network & Pricing Analysis
Dealer network density in suburban Texas and Florida corridors shapes both supply concentration and price floors for robotic mower distribution. Scale advantages at Husqvarna Group and STIHL Inc. compress margin headroom for smaller assemblers while FCC certification costs erect fixed barriers that stratify pricing tiers.
Pricing Analysis
Certification level creates the primary spread between GPS-enabled premium units and entry-tier Bluetooth configurations. Three-tier pricing structure across premium, standard, and economy levels reflects navigation precision, battery capacity, and dealer service bundling. Price erosion runs through semi-automatic segments as landscaping contractors pressure capital costs. Residential homeowners in California metropolitan corridors exhibit highest price sensitivity, while golf course operators accept premium positioning for slope-climbing chassis and centimeter-level turf precision.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells dominates procurement strategy as cathode material volatility disrupts just-in-time preferences common in consumer electronics. Battery pack assembly draws from China, South Korea, and Japan for cathode processing and cell manufacturing. Single-source vulnerability concentrates in East Asian electrode material refining. Distribution runs through regional dealer networks with fleet financing capabilities rather than direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from equipment-as-a-service restructuring that transfers capital risk from landscaping contractors to dealer networks. Manual mowing labor pools and ride-on mower fleets constitute persistent substitute threats.
For Market Incumbents: Compound dealer financing capabilities to capture fleet outsourcing momentum among California and Texas landscaping contractors. Deepen backward integration into battery thermal management systems to offset cathode cost volatility. Defend against RTK-GPS navigation commoditization through proprietary cloud connectivity ecosystems that lock in recurring software revenue.
For New Entrants and Emerging Players: Lead with solar-hybrid configurations targeting Arizona and Nevada premium residential installations where grid independence commands price premiums. Exploit Industry Canada RSS-210 certification alignment to penetrate Ontario and British Columbia with near-zero incremental compliance investment. Position through direct online channels bypassing established dealer networks in price-sensitive semi-automatic segments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors navigation software specialists with RTK-GPS algorithm portfolios over hardware assemblers. Long-term viability hinges on recurring revenue attachment rates through fleet management platforms. Acquisition targets should demonstrate dealer network financing partnerships or proprietary boundary-mapping IP. Watch for inflection when municipal noise ordinances accelerate battery-electric specification in dense suburban jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| FCC Part 15 Certification Investment | Filters distribution eligibility and erects technical moats against undercapitalized competitors. |
| Dealer Network Financing Expansion | Captures equipment-as-a-service restructuring among Texas and California landscaping contractors. |
| RTK-GPS Navigation Module Integration | Eliminates perimeter wire installation labor and collapses deployment friction for fleet operators. |
| Solar-Hybrid Configuration Development | Extends runtime for Southwestern premium installations without grid tethering constraints. |
| Canadian Market Entry Execution | Leverages Industry Canada RSS-210 alignment for near-zero incremental compliance cost expansion. |
Research Methodology
Desk research of EPA regulatory filings, FCC equipment authorization databases, and industry association technical standards preceded structured interviews with dealer network operators, landscaping contractor fleet managers, and robotic mower product engineers. Secondary validation drew from customs import records, outdoor power equipment trade publications, and municipal procurement databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, navigation technology, end-user category, and power source architecture shaped the analytical framework. CAGRs derived from segment-level growth trajectory modeling and replacement cycle analysis throughout the forecast period. Industry-specific inputs included lithium-ion cell cost curves, FCC certification timeline distributions, and suburban lot size standardization patterns across sunbelt metropolitan corridors.
The analysis sits within stated boundaries; outcomes outside sustained EPA Phase 3 enforcement or lithium supply chain stability would require recalibration. Forecasts reflect assumptions regarding dealer financing availability and RTK-GPS module cost reduction curves. Revision becomes warranted when cathode material price volatility crosses thresholds that compress battery pack margins below assembly viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
Global Automatic Mower Market
Outdoor Gear
Germany Camping Equipment Market
Outdoor Gear
Outdoor Camping Toilet Market
Outdoor Gear
Professional Gear Bags Market
Outdoor Gear
Picnic Coolers Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Snow Chain Market
Outdoor Gear
Hunting Boots Market
Outdoor Gear
Japan Camping Tent Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Camp Fire Tripod Market
Outdoor Gear
Crash Pads Market
Outdoor Gear
Shared Umbrella Market
Outdoor Gear
Spain Camping Equipment Market
Outdoor Gear
Cordless Garden Equipment Market
Outdoor Gear
UK Camping Equipment Market