
 Electric Foot Callus Remover Market | 2026-2036
Electric Foot Callus Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Foot Callus Remover Market Insights
Aftermarket consumable revenue is tilting toward replacement roller heads and specialized pedicure attachments as brands pursue recurring income streams. Philips leverages its personal-care ecosystem to bundle callus removers with grooming kits across European retail channels. Scholl anchors its position through pharmacy-exclusive distribution that sustains premium positioning in the United Kingdom and Ireland. Pritech Beauty competes on manufacturing scale, operating Shenzhen-based production that supplies private-label brands across North America and Southeast Asia.
An electric foot callus remover is a motorized personal-care device employing a cylindrical abrasive roller or oscillating file head, typically rotating at 2,000–3,000 RPM, to mechanically debride hyperkeratotic skin from plantar surfaces. The device serves both cosmetic smoothing and preventive podiatric maintenance, particularly for diabetic patients and aging consumers managing reduced skin elasticity. Rechargeable remover units capture the dominant margin pool as lithium-ion configurations command price premiums over disposable battery alternatives. Home care application growth outpaces professional treatment channels, reflecting post-pandemic behavioral shifts toward domestic self-service routines. Online retail distribution leads volume throughput, though specialty stores retain higher attachment rates for premium-tier units with interchangeable heads.
FDA Class I medical device designation for certain diabetic-foot models shapes United States market access requirements and quality documentation burdens. CE marking under the EU Medical Device Regulation and REACH compliance for abrasive roller materials govern European commercialization pathways, while China's NMPA oversees domestic registration of therapeutic-grade units. IPX waterproofing standards and IEC 60335 household appliance safety protocols increasingly influence product development timelines across all major jurisdictions. Stakeholders must monitor whether regulatory bodies reclassify therapeutic callus removers as higher-risk devices, a shift that would reshape certification costs and competitive barriers for new entrants.
Market Dynamics
Rechargeable lithium-ion battery technology is collapsing the price-performance gap between premium and mass-market electric foot callus removers, compressing margin structures while expanding addressable volume across home-care segments.
Growth Catalysts
- Diabetic foot-care protocols:United States Medicare reimbursement guidelines for preventive podiatric devices expand qualified purchaser pools beyond cosmetic users.
- IPX5+ waterproofing standards:Wet-use certification unlocks bathroom-consumption occasions previously blocked by safety concerns.
- German pharmacy distribution:Regulatory endorsement through Apotheken channels validates therapeutic positioning for aging consumers.
Market Restraints
- Lithium carbonate price volatility:Battery input cost swings compress assembler margins on rechargeable units.
- Shenzhen manufacturing concentration:Single-region OEM dependency creates logistics vulnerability and tariff exposure.
- Manual pumice substitution:Low-cost abrasive tools retain price-sensitive segments in emerging markets.
Strategic Opportunities
- Subscription roller-head replenishment:Recurring revenue models lock in lifetime value through proprietary attachment ecosystems.
- CE marking under EU MDR:Therapeutic-grade certification opens pharmacy reimbursement pathways across European markets.
- Telemedicine integration:Remote podiatry consultations create device-prescribing channels for diabetic patient management.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 skin-contact certification extends product launch cycles by 8-14 months.
- Cross-border e-commerce compliance:Divergent electrical safety standards between IEC 60335 and UL 60335 fragment inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Foot Callus Remover Market |
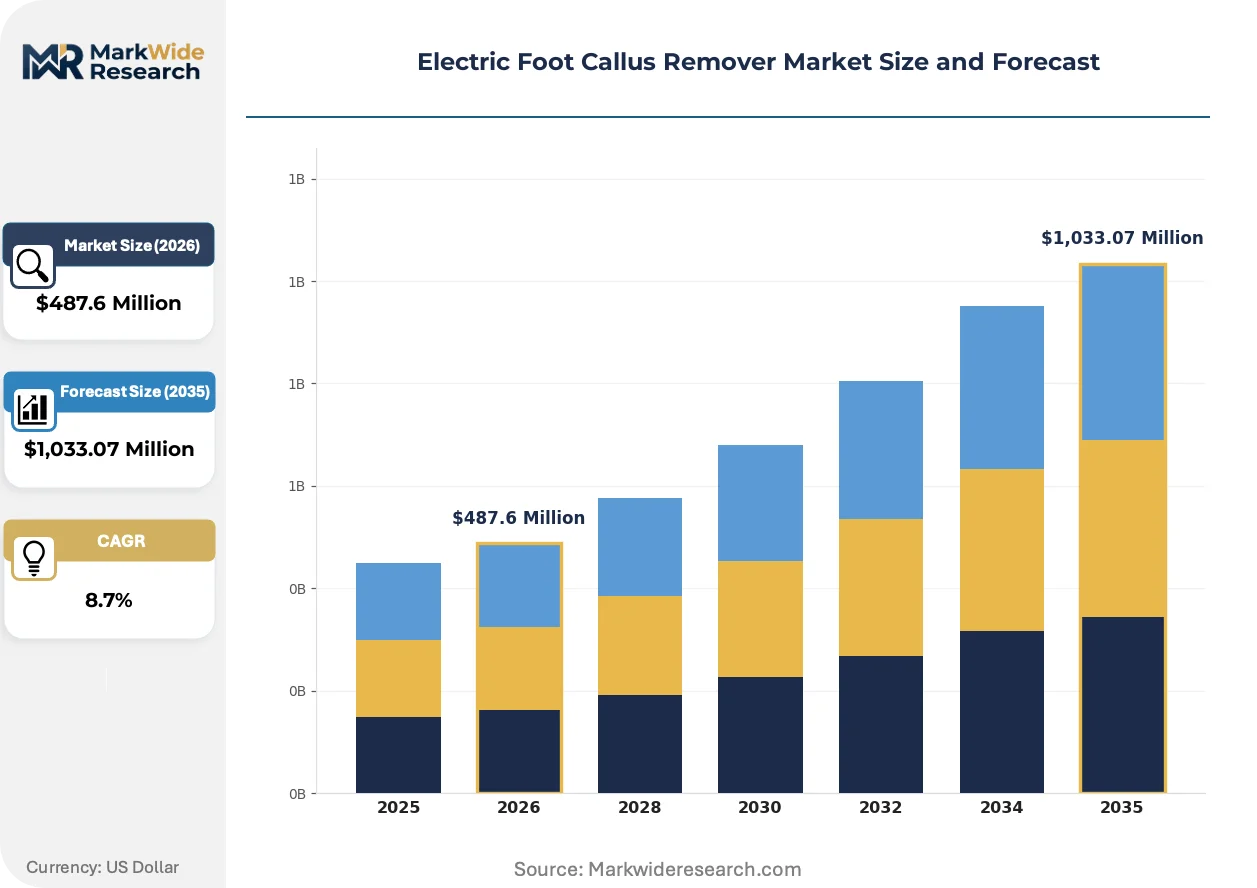
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Remover, Rechargeable Remover, Battery-Operated Remover, Electric Scrubber End User: Cosmetic Stores, Home Users, Salons, Spa Centers Application: Daily Care, Professional Treatment, Spa Treatment, Home Care Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Medisana, Pritech Beauty, Philips, Zoe+Ruth, Own Harmony, Beurer, Amope, Emjoi, Scholl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Foot Callus Remover Market Trends and Innovations
Product development trajectories center on battery chemistry advances, regulatory recalibration of medical-device classifications, and channel migration toward direct-to-consumer subscription models.
Brushless DC motor architecture is collapsing the durability gap between professional salon equipment and home-use devices. Home-care buyers now access 2,000+ hour motor lifespans previously reserved for commercial units. This compression eliminates the repair-replacement cycle that sustained aftermarket service revenue for legacy manufacturers.
EU Medical Device Regulation reclassification deliberations are forcing preemptive quality-system investments across European suppliers. MDR Annex VIII risk-classification reviews threaten to elevate certain therapeutic callus removers from Class I to Class IIa. German and French manufacturers are front-loading clinical documentation to secure notified-body approvals ahead of enforcement deadlines.
Direct-to-consumer subscription bundling is displacing traditional retail replenishment for consumable roller heads. Younger demographics in United States and United Kingdom markets prioritize automated delivery over pharmacy pickup. This behavioral pivot concentrates customer data ownership with device manufacturers, weakening distributor intermediation power.
Electric Foot Callus Remover Market Segmentation
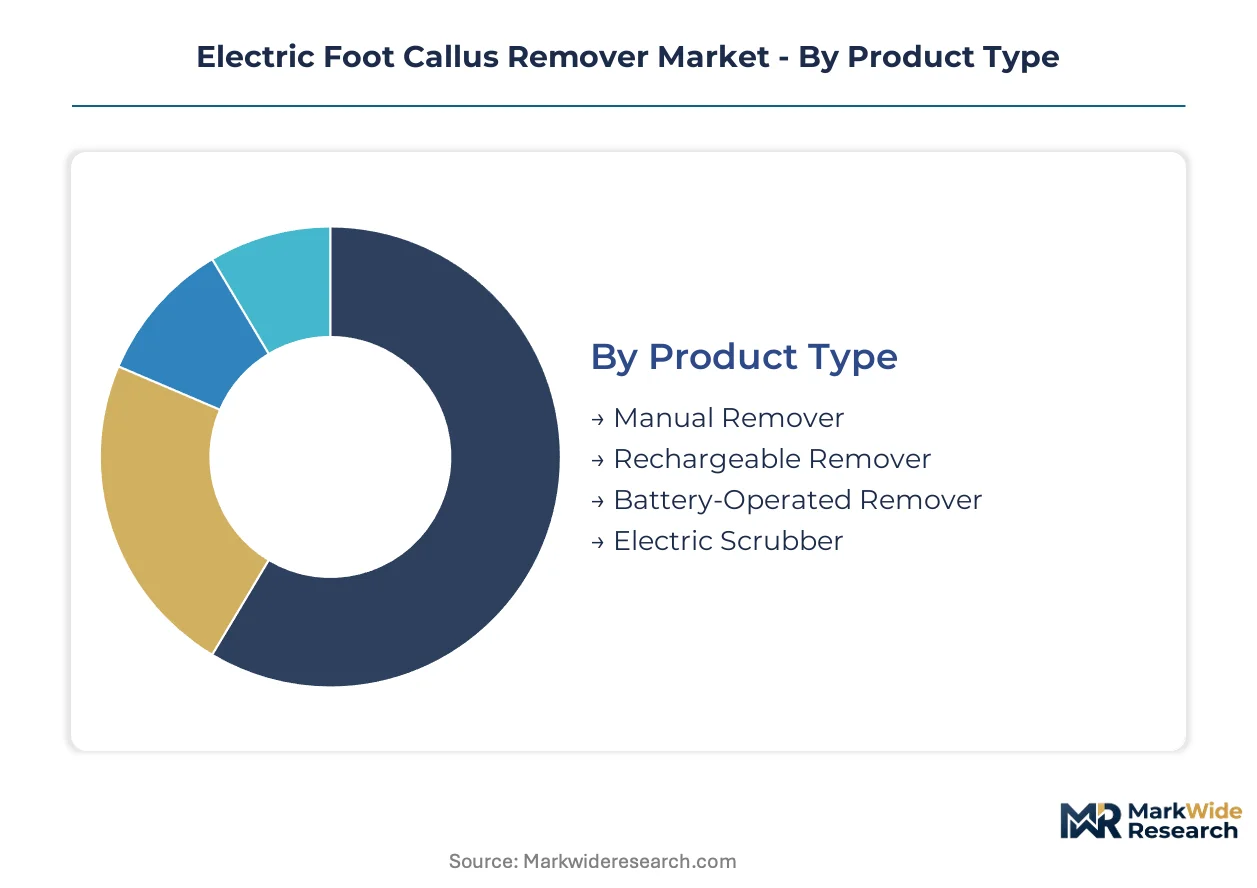
Segmentation in electric foot callus removers reveals how battery chemistry, waterproofing certification, and channel economics partition profit pools. Manufacturers configure product lines around replacement-part revenue intensity rather than unit margins alone.
Product Type:
After-sales-service intensity varies sharply across power-source architectures, with rechargeable units demanding firmware updates and battery-cycle management while manual alternatives require no post-purchase support infrastructure.
- Rechargeable Remover:Lithium-ion configurations rotate abrasive heads at 2,000–3,000 RPM with IPX5+ wet-use certification. Demand concentrates in Germany and the United States where aging consumers prioritize bathroom-safe operation combined with diabetic foot-care protocols expanding qualified purchaser pools.
- Manual Remover:Non-motorized abrasive surfaces rely on user-applied pressure without electrical components. Volume leadership sits in emerging markets where price sensitivity and limited power infrastructure constrain electric adoption, though growth remains flat.
- Battery-Operated Remover:Disposable alkaline or NiMH configurations target entry-level buyers seeking portability without charging logistics. These units carry lower upfront cost but higher lifetime spend on replacement cells.
- Electric Scrubber:Oscillating file-head variants with interchangeable pedicure attachments serve multi-function grooming routines. Shenzhen-based OEMs supply private-label versions across North American discount retail.
By volume, battery-operated units lead in emerging markets. By growth pace, rechargeable lithium-ion configurations are expanding most quickly as waterproofing standards unlock wet-use occasions.
End User:
Procurement authority and replenishment frequency diverge across institutional buyers versus individual consumers, with salons demanding commercial-grade motor durability and home users prioritizing storage convenience.
- Home Users:Individual consumers purchasing for domestic self-care routines represent the steepest expansion trajectory as post-pandemic behavioral shifts solidify. These buyers favor compact storage footprints and subscription roller-head replenishment over pharmacy pickup.
- Salons:Professional nail-care establishments require 2,000+ hour brushless DC motor lifespans and rapid sanitization protocols. Demand clusters in urban United States and Chinese metropolitan centers where service density supports equipment amortization.
- Spa Centers:Wellness-focused facilities integrate callus removal into broader pedicure service menus. Procurement emphasizes aesthetic design and quiet operation over raw abrasion power.
- Cosmetic Stores:Retail channels serving impulse purchasers and gift buyers stock entry-tier units with prominent packaging. These outlets move volume during seasonal gifting periods with minimal attachment sales.
Home users command the dominant addressable expansion. Professional channels capture the highest per-unit spend but flatten as brushless motor durability collapses replacement cycles.
Application:
Clinical indication versus cosmetic positioning splits regulatory pathways and reimbursement eligibility, with therapeutic-grade units navigating FDA and CE marking frameworks that cosmetic alternatives bypass.
- Daily Care:Routine maintenance for non-pathological skin smoothing dominates unit volume. These applications face substitution pressure from manual pumice stones in price-sensitive segments.
- Home Care:Post-pandemic domestic self-service routines concentrate demand in United States and United Kingdom markets where younger demographics favor automated replenishment. IPX5+ certification unlocks bathroom-consumption occasions previously blocked by safety concerns.
- Professional Treatment:Podiatric and nail-service protocols demand higher abrasion precision with adjustable speed settings. Medicare reimbursement guidelines in the United States expand qualified purchaser pools beyond cosmetic users.
- Spa Treatment:Relaxation-oriented consumption emphasizes sensory experience and extended service duration. These applications support premium pricing but limited volume throughput.
Home care application claims the broadest user base. Professional treatment commands pricing power through reimbursement channels.
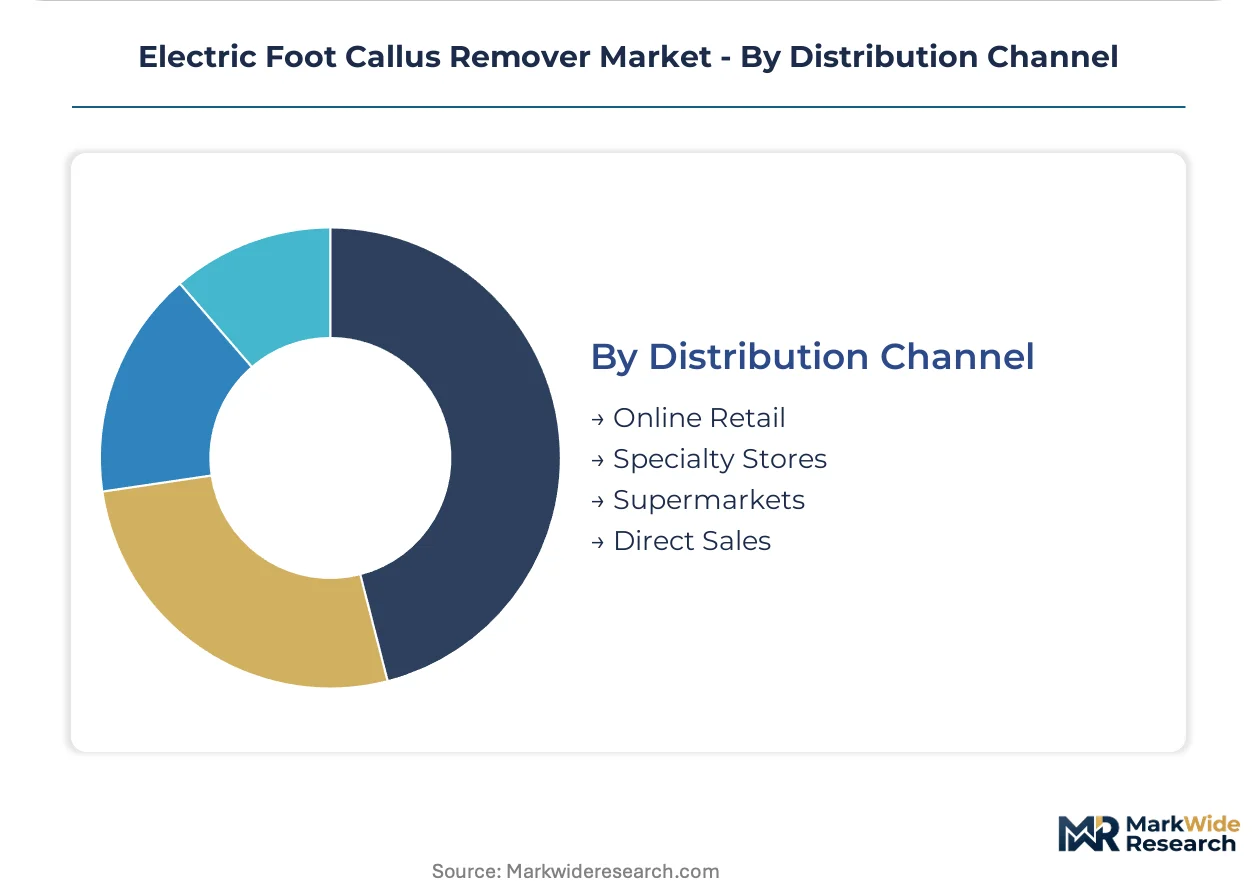
Distribution Channel:
Inventory velocity and attachment-rate economics favor online retail for volume throughput while specialty stores retain higher-margin premium-tier conversions with interchangeable head bundles.
- Online Retail:Direct-to-consumer platforms concentrate customer data ownership with device manufacturers. Subscription bundling for roller-head replenishment displaces traditional retail replenishment in United States and United Kingdom markets.
- Specialty Stores:Beauty and personal-care boutiques deliver higher attachment rates for premium-tier units with demonstration-assisted conversion. German pharmacy distribution through Apotheken channels validates therapeutic positioning.
- Supermarkets:Mass-market retail moves high-volume entry-tier SKUs with limited sales assistance. These channels sacrifice margin for turnover velocity and brand visibility.
- Direct Sales:Manufacturer-owned channels capture full margin stack but require logistics infrastructure investment. Concentration remains limited to established personal-care brands with existing customer databases.
Online retail leads volume throughput. Specialty stores maintain margin superiority through premium-tier attachment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in Shenzhen and Dongguan shapes component sourcing patterns for rechargeable units across all major consumer markets. OEM output from these clusters supplies private-label brands in North America and Europe while domestic Chinese brands capture expanding home-care segments.
United States
Medicare reimbursement guidelines for preventive podiatric devices expand qualified purchaser pools beyond cosmetic users. FDA Class I medical device designation shapes market access requirements and quality documentation burdens for therapeutic-grade units. Demand concentrates in urban metropolitan centers where aging populations and diabetic foot-care awareness drive consistent uptake.
Germany
Apotheken pharmacy distribution channels validate therapeutic positioning for aging consumers seeking clinical-grade home care. CE marking under the EU Medical Device Regulation governs commercialization pathways for therapeutic callus removers. Manufacturing and R&D activity clusters in Bavaria and North Rhine-Westphalia where personal-care device specialists maintain quality-system investments.
China
NMPA registration requirements oversee domestic commercialization of therapeutic-grade units targeting diabetic patient management. Shenzhen-based OEMs supply private-label brands across North America and Southeast Asia through manufacturing scale advantages. Domestic e-commerce platforms concentrate volume throughput for rechargeable lithium-ion configurations.
United Kingdom
Pharmacy-exclusive distribution sustains premium positioning for established personal-care brands. Post-pandemic behavioral shifts toward domestic self-service routines accelerate home-care application growth. London and Southeast England concentrate retail channel headquarters and direct-to-consumer subscription operations.
Japan
PMDA oversight shapes registration pathways for therapeutic-grade devices targeting aging consumers with reduced skin elasticity. METI standards influence household appliance safety protocols for bathroom-safe IPX5+ certified units. Osaka-based personal-care specialists emphasize compact design and quiet operation for domestic storage convenience.
Electric Foot Callus Remover Market Competitive Landscape
Personal-care conglomerates and specialized grooming-device manufacturers split the market along ecosystem-versus-standalone positioning lines. Market structure tilts toward tiered concentration where premium brands leverage pharmacy and specialty retail channels while mass-market players compete through online volume throughput. Three archetypes dominate: integrated personal-care ecosystems, OEM-scale private-label suppliers, and single-category specialists. Competitive moves center on subscription roller-head replenishment models and preemptive quality-system investments ahead of EU MDR reclassification deadlines.
Among integrated personal-care ecosystems, Philips leverages its grooming-kit bundling across European retail channels. Scholl anchors pharmacy-exclusive positioning in the United Kingdom and Ireland through regulatory endorsement. Pritech Beauty exemplifies the OEM-scale archetype with Shenzhen-based production supplying private-label brands across North America.
| Leading Market Players |
|---|
| Medisana |
| Pritech Beauty |
| Philips |
| Zoe+Ruth |
| Own Harmony |
| Beurer |
| Amope |
| Emjoi |
| Scholl |
| Others |
Pricing and Supply Chain Analysis
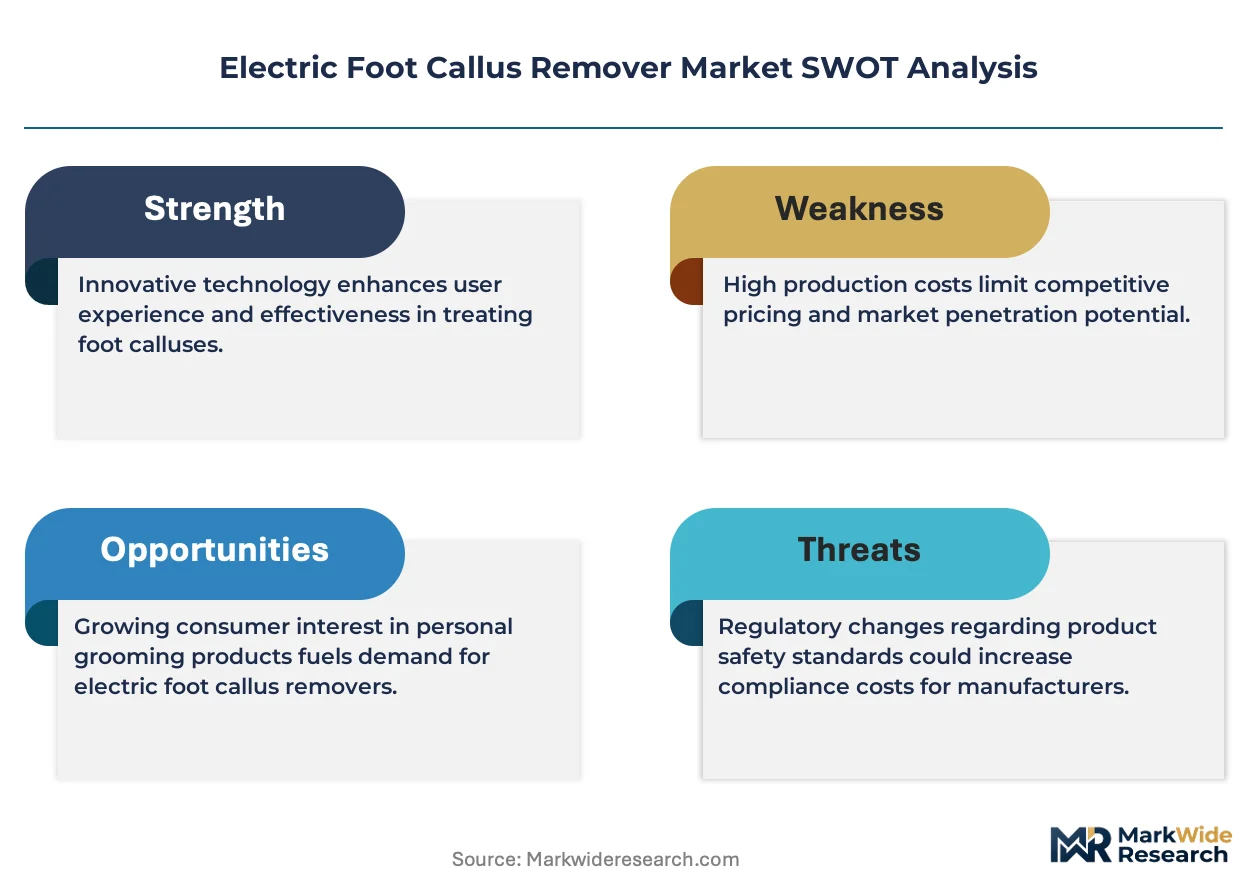
Lithium carbonate price volatility determines both the premium-to-economy pricing spread and the geographic sourcing strategies that assemblers deploy. Battery input cost swings compress margins on rechargeable units while forcing tiered product architectures that segment buyers by waterproofing certification and motor durability.
Pricing Analysis
CE marking under EU MDR dictates the pricing tier structure across European markets, separating pharmacy-distributed therapeutic units from cosmetic-grade retail alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects IPX certification grade and brushless motor longevity. Cost compression in the rechargeable segment intensifies because lithium-ion cell sourcing rests on volatile commodity markets. Home users in Germany and the United States show least price sensitivity for bathroom-safe certified units, while emerging-market buyers gravitate toward battery-operated entry tiers.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculus for brands dependent on Shenzhen and Dongguan OEM output. Manufacturing concentrates in China's Pearl River Delta, with South Korean battery cell suppliers and Japanese brushless motor specialists feeding component pipelines. Raw material dependencies span lithium carbonate, neodymium magnets, and medical-grade ABS housings. Single-region OEM dependency creates logistics vulnerability and tariff exposure. Distribution runs through direct-to-consumer platforms and pharmacy networks, with online retail capturing replenishment velocity for roller-head subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized clinical documentation capabilities for EU MDR and FDA therapeutic-grade pathways represent the scarcest asset in this market, separating pharmacy-positioned brands from commodity competitors.
For Market Incumbents: Insulate pharmacy-channel positioning through preemptive notified-body submissions ahead of MDR reclassification deadlines. Secure captive lithium-ion cell supply through backward integration into South Korean or Chinese battery partnerships. Lock in subscription replenishment revenue through proprietary roller-head attachment ecosystems that block manual-pumice substitution. For New Entrants and Emerging Players: Mid-market rechargeable units with IPX5 certification for United Kingdom and United States home-care buyers represent the most penetrable entry point. Target diabetic foot-care protocols expanding Medicare-qualified purchaser pools beyond cosmetic users. Pursue white-label supply contracts with North American direct-to-consumer brands lacking Shenzhen manufacturing relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-recalibration phase that favors clinical-documentation-ready assets over pure manufacturing scale. Five-to-ten year viability hinges on MDR Class IIa certification capabilities and telemedicine integration pipelines. Acquisition targets should demonstrate existing notified-body relationships and software companion development for remote podiatry platforms. Watch FDA reclassification deliberations for therapeutic callus removers as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Notified-body approval unlocks pharmacy reimbursement across German Apotheken channels. |
| Subscription Roller-Head Replenishment | Automated delivery concentrates customer data ownership with device manufacturers. |
| Backward Integration into Battery Supply | Captive lithium-ion sourcing insulates margins from commodity volatility swings. |
| Telemedicine Platform Integration | Remote podiatry consultations create device-prescribing channels for diabetic patients. |
| IPX6 Waterproofing Upgrade | Wet-use certification expands bathroom-consumption occasions beyond current IPX5 standards. |
Research Methodology
Cross-validation between primary interviews with device manufacturers and secondary regulatory filings anchors the qualitative findings. Stakeholder consultations spanned product development executives at personal-care conglomerates, notified-body certification specialists, pharmacy category buyers in Germany and the United Kingdom, and diabetic foot-care clinicians. Secondary sources included FDA 510(k) premarket notifications, EUDAMED device registrations, EU MDR technical documentation, and customs trade data for lithium-ion powered personal-care appliances. Bottom-up unit shipment estimates from OEM clusters in Shenzhen and Dongguan were triangulated against top-down category spending data.
Calibration against historical pricing trajectories for rechargeable personal-care devices shaped the analytical framework. Segmentation dimensions modeled include power-source architecture, waterproofing certification tier, end-user category, and distribution channel economics across the projection horizon. CAGRs were derived from fitted growth curves applied to unit volume and average selling price evolution. Forecast inputs incorporated Medicare reimbursement guideline expansion rates and EU MDR enforcement timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, trans-Pacific tariff schedules, or EU regulatory enforcement intensity would shift the trajectory. The analysis reflects documented assumptions regarding battery chemistry cost curves and pharmacy-channel expansion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Ear Piercing Guns Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market