
 Robotic Pets Market | 2026-2036
Robotic Pets Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Pets Market Insights
The EU AI Act is shifting procurement criteria for robotic companions across European healthcare networks. Sony Group Corp. leverages its proprietary sensor fusion architecture to sustain premium positioning in companion robots. Ageless Innovation LLC anchors the senior-care channel through purpose-built therapeutic form factors. Tombot Inc. specializes in hyper-realistic breed-specific designs that differentiate its offerings in clinical settings.
Robotic pets are electromechanical systems combining servo-actuated locomotion, tactile sensors, and embedded AI to simulate animal behaviors for emotional engagement, therapeutic intervention, or educational stimulation. Companion robots lead volume deployment in assisted-living environments, while therapy robots command margin concentration through clinical certification requirements. AI Integration represents the fastest-expanding technology dimension as natural-language processing enables more responsive human-device interaction.
The FDA regulates therapeutic robotic devices marketed for cognitive or emotional health claims in the United States, while the EU AI Act imposes risk-classification and transparency obligations on algorithmic companion systems. Japan's METI promotes robotic care device adoption through standardization frameworks and reimbursement alignment. Stakeholders must monitor evolving medical-device classification boundaries as regulators distinguish wellness-oriented companion units from clinically validated therapy platforms.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are compressing deployment timelines for interactive companion devices while METI's reimbursement frameworks in Japan accelerate clinical adoption of therapeutic units.
Growth Catalysts
- Sensor Fusion Architecture:Multi-modal tactile and motion sensing enables responsive behavioral simulation that meets clinical certification thresholds for cognitive therapy applications.
- METI Standardization Frameworks:Japan's reimbursement alignment for robotic care devices reduces procurement friction across senior-care networks and assisted-living facilities.
- Pediatric Therapy Centers:Specialized demand from autism intervention programs and child psychology clinics creates volume pull for certified therapeutic form factors in the United States.
Market Restraints
- Li-ion Battery Supply Concentration:Dependence on East Asian cell manufacturers creates input cost volatility and logistics exposure for portable electromechanical units.
- FDA Medical-Device Classification:Therapeutic claims trigger 510(k) or De Novo pathways that extend commercialization timelines by 18-36 months versus wellness-oriented companions.
- Live Animal Substitution:Traditional pet ownership retains preference elasticity among mobile seniors and households without allergy constraints.
Strategic Opportunities
- German Clinical Networks:EU AI Act compliance infrastructure positions early-certified vendors for procurement preference across Bavarian and North Rhine-Westphalia healthcare systems.
- Natural-Language Processing Convergence:Integration of large language models with affective computing enables conversational companionship that transcends pre-scripted behavioral libraries.
- Direct-to-Consumer Telehealth Channels:Post-pandemic remote therapy delivery creates distribution bypass for prescription-grade companion units.
Industry Challenges
- Embedded Systems Engineering Talent:Scarcity of firmware developers with real-time sensor fusion and motor control expertise constrains product iteration velocity.
- ISO 13485 Certification Timelines:Medical-device quality management implementation demands 12-18 month operational preparation before regulatory submission.
- Legacy Care Facility Infrastructure:Wi-Fi bandwidth limitations and electrical outlet placement in dated assisted-living buildings complicate deployment of cloud-connected units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Pets Market |
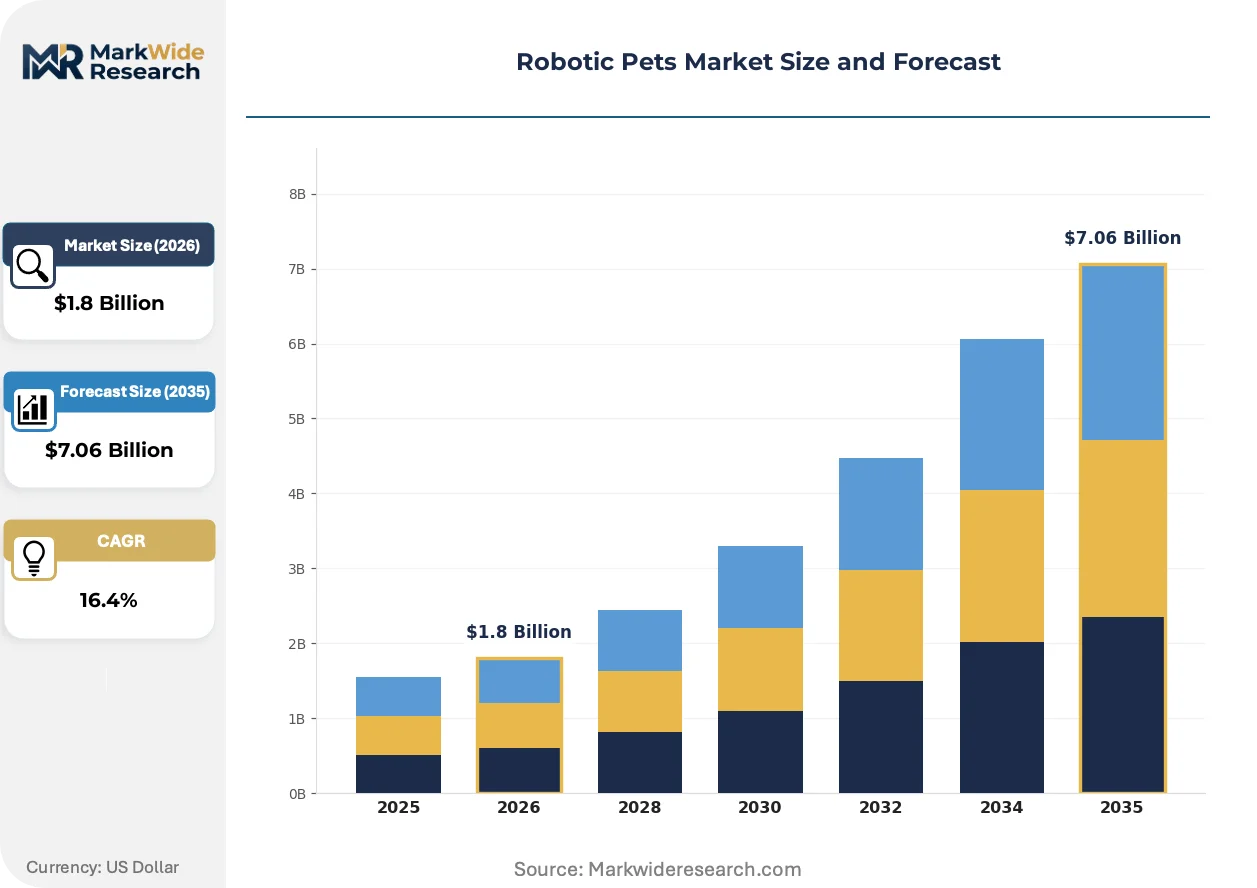
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Companion Robots, Educational Robots, Therapy Robots, Entertainment Robots Target Consumer: Children, Seniors, Disabled Individuals, Animal Lovers Technology: AI Integration, Sensor Technology, Voice Recognition, Connectivity Market Segment: Household, Healthcare, Education, Commercial |
| Companies Covered | Ageless Innovation LLC, RobotShop Inc., Sony Group Corp., Silverlit Toys Manufactory Ltd., SoundOriginal Electronics Co. Ltd., WowWee Group Ltd., BIRANCO Ltd., Consequential Robotics Ltd., Tombot Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Pets Market Trends and Innovations
Behavioral simulation algorithms and regulatory classification boundaries are simultaneously expanding functional capabilities and narrowing permissible market claims for robotic companion devices.
Advanced haptic feedback arrays incorporating pressure-sensitive artificial skin and temperature modulation are automating the calibration of therapeutic touch protocols. Pediatric oncology wards and dementia care units in the United States are piloting these systems for anxiety reduction protocols. The technology is automating previously manual caregiver interventions, compressing staff-to-patient ratios in understaffed facilities.
The EU AI Act's risk-classification framework for algorithmic decision-making imposes documentation and human-oversight obligations on companion systems with adaptive behavioral responses. Manufacturers must now maintain technical files demonstrating transparency in machine-learning model training data and inference logic. Therapy robot segments face the steepest compliance burden, while wellness-oriented companions navigate lighter conformity assessment routes.
Hospital procurement departments are consolidating vendor relationships around platforms offering both hardware and longitudinal outcome analytics. Bundled service agreements that include usage telemetry and therapeutic efficacy reporting are displacing transactional device sales in National Health Service trusts and integrated delivery networks. This concentration is most pronounced in the United Kingdom and Netherlands, where centralized procurement frameworks favor multi-year performance contracts over capital expenditure purchases.
Robotic Pets Market Segmentation
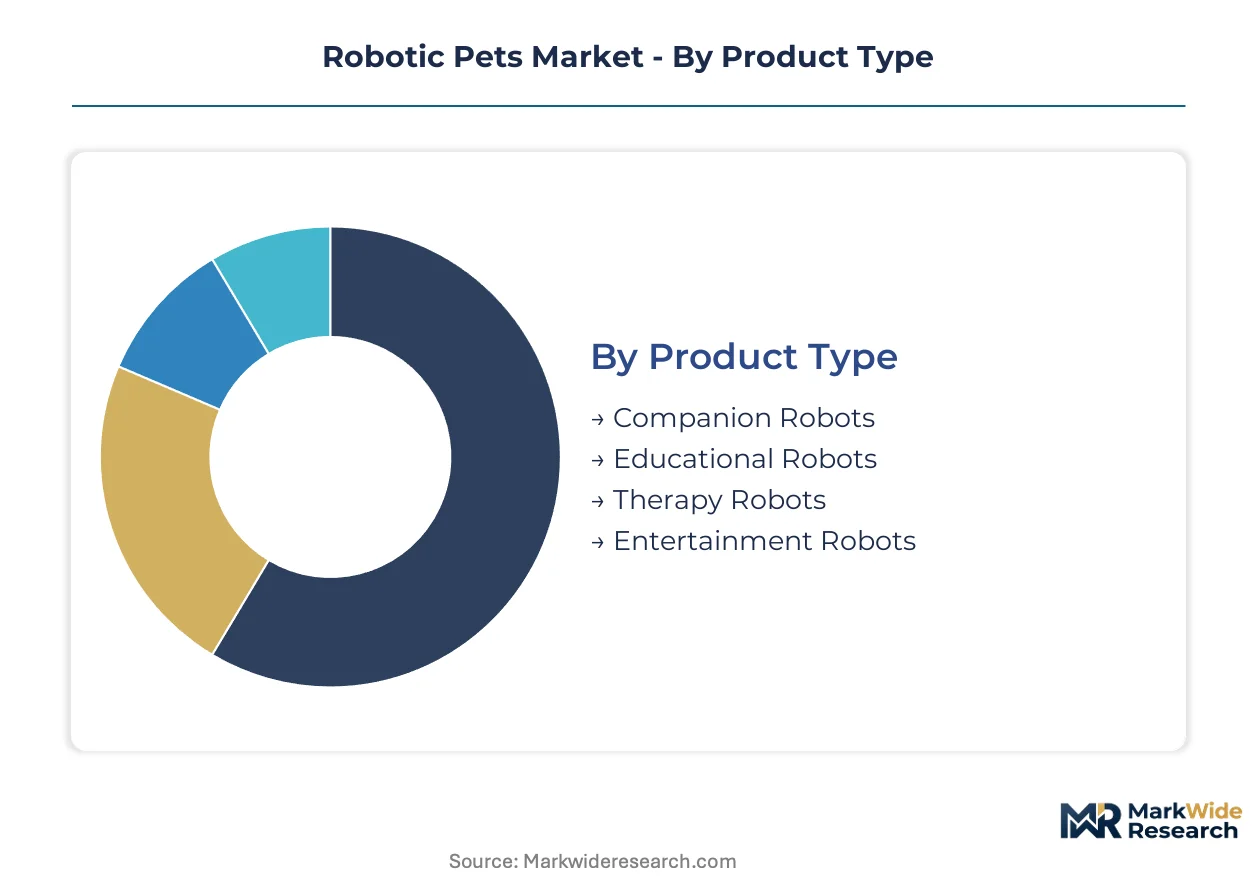
Segmentation in robotic pets reveals distinct procurement pathways and certification requirements across therapeutic versus wellness applications. Understanding these divisions enables vendors to align R&D investment with reimbursement eligibility and regulatory burden.
Product Type:
Integration depth varies sharply across this category, with standalone companion units requiring minimal infrastructure while therapy robots demand embedded clinical system connectivity.
- Companion Robots:Electromechanical systems simulate animal behaviors through servo-actuated locomotion and tactile response arrays. Demand concentrates in Japanese senior-care networks where METI reimbursement frameworks reduce procurement friction for therapeutic companion units.
- Therapy Robots:Clinical-grade devices incorporate pressure-sensitive artificial skin and adaptive behavioral algorithms for anxiety reduction protocols. Pediatric oncology wards and dementia care units in the United States pilot these systems, though FDA 510(k) pathways extend commercialization timelines.
- Educational Robots:STEM-focused units programmable through block-based coding interfaces for classroom deployment.
- Entertainment Robots:Consumer-oriented devices emphasizing novelty behaviors and app-connected customization for household leisure use.
Companion robots lead volumes today; therapy robots are gaining share fastest.
Target Consumer:
Cost tier alignment shapes this category, with institutional procurement dominating high-ASP segments and direct-to-consumer channels serving price-sensitive households.
- Seniors:Purpose-built therapeutic form factors address cognitive stimulation and social isolation in assisted-living environments. Bavarian healthcare systems in Germany prioritize EU AI Act-compliant units for procurement preference.
- Children:Autism intervention programs and child psychology clinics create specialized demand for certified therapeutic robots with natural-language processing capabilities.
- Disabled Individuals:Accessibility-optimized designs featuring simplified interfaces and enhanced sensory feedback for motor or cognitive impairment support.
- Animal Lovers:Household consumers seeking allergen-free alternatives to live pet ownership, with preference elasticity remaining significant among mobile seniors.
Seniors dominate institutional procurement today; children represent the steepest expansion trajectory through pediatric therapy channels.
Technology:
Application maturity separates embedded foundational systems from emerging capability layers still navigating standardization gaps.
- AI Integration:Machine-learning models enable adaptive behavioral responses beyond pre-scripted libraries. EU AI Act risk-classification mandates impose documentation and human-oversight obligations, compressing deployment timelines for European vendors.
- Sensor Technology:Multi-modal tactile and motion sensing architectures provide the hardware substrate for clinical certification thresholds. Sony Group Corp. leverages proprietary sensor fusion for premium positioning.
- Voice Recognition:Natural-language processing convergence with affective computing enables conversational companionship capabilities.
- Connectivity:Cloud-linked telemetry for longitudinal outcome analytics, though legacy assisted-living infrastructure with Wi-Fi bandwidth limitations complicates deployment.
Sensor technology anchors current installed base; AI integration is climbing the fastest as large language model integration accelerates.
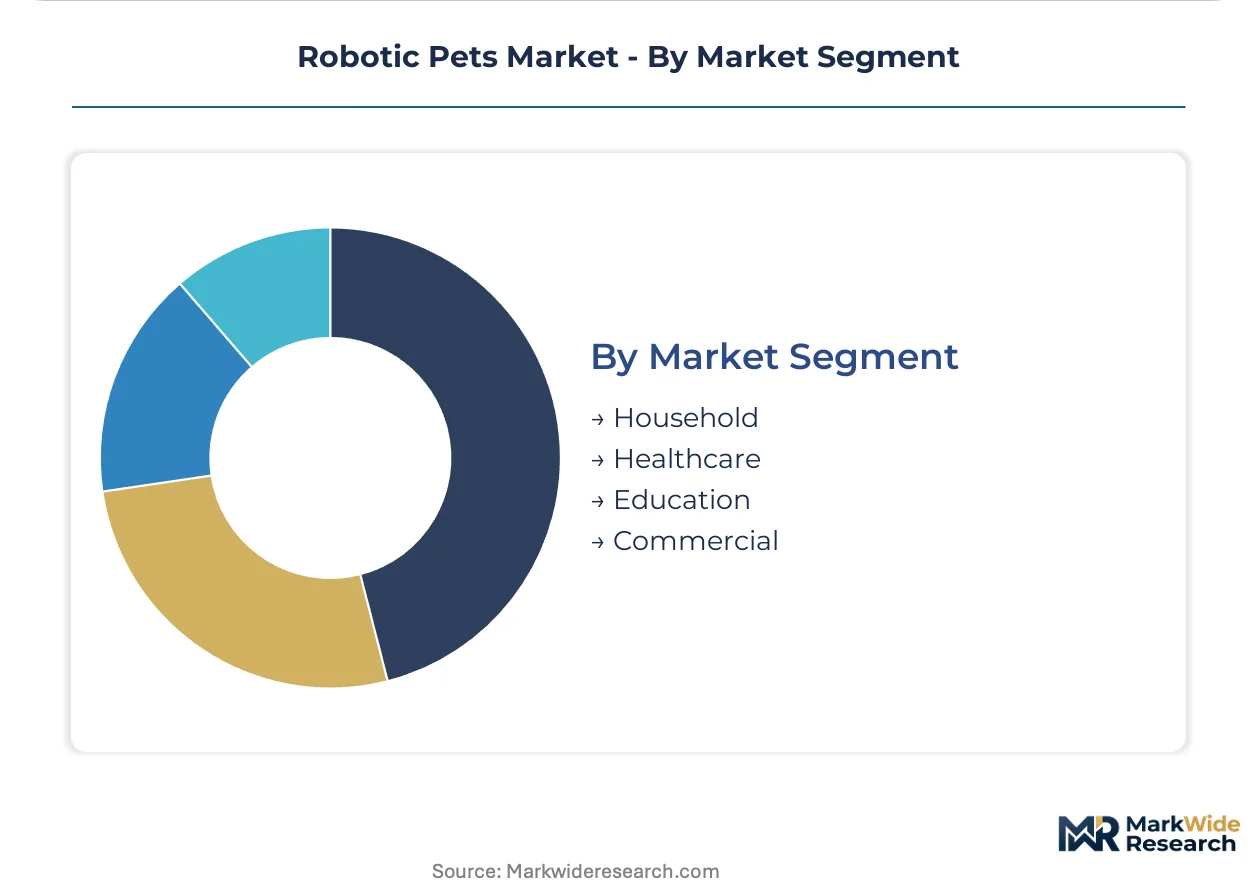
Market Segment:
Supply concentration differs across volume-driven household channels versus margin-concentrated institutional segments with certification barriers.
- Healthcare:Hospital procurement departments consolidate vendor relationships around bundled service agreements including usage telemetry and therapeutic efficacy reporting. National Health Service trusts in the United Kingdom favor multi-year performance contracts.
- Household:Direct-to-consumer telehealth channels create distribution bypass opportunities for prescription-grade companion units post-pandemic.
- Education:School district procurement cycles and curriculum alignment requirements shape volume deployment patterns for programmable robot platforms.
- Commercial:Corporate wellness programs and retail hospitality deployments seeking differentiated customer experience offerings.
Healthcare commands margin concentration today; household segments are expanding most quickly through telehealth channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered therapeutic robotic companions through PARO and subsequent iterations, establishing the regulatory and reimbursement frameworks that other markets now adapt. The industry has since diffused across North America, Europe, and select Asian markets with distinct procurement pathways and compliance requirements.
Japan
Senior-care networks in Tokyo and Osaka drive institutional procurement of therapeutic companion units. METI standardization frameworks align reimbursement codes with robotic care device categories, reducing procurement friction for certified systems. Nagoya's industrial corridor hosts concentrated manufacturing of servo-actuated components for export markets.
United States
Pediatric therapy centers and dementia care units in Boston and San Francisco pilot pressure-sensitive artificial skin systems for anxiety reduction protocols. FDA 510(k) and De Novo pathways extend commercialization timelines by 18-36 months for therapeutic claims versus wellness-oriented companions. Greater Los Angeles clusters telehealth distribution channels for prescription-grade companion units.
Germany
Bavarian healthcare systems prioritize EU AI Act-compliant units for procurement preference across integrated delivery networks. The country's national pharmaceutical regulator maintains vigilance over medical-device classification boundaries for cognitive therapy applications. North Rhine-Westphalia's hospital procurement departments consolidate vendor relationships around bundled service agreements with longitudinal outcome analytics.
United Kingdom
National Health Service trusts favor multi-year performance contracts over capital expenditure purchases for robotic companion platforms. EMA guidance on software as a medical device informs local interpretation of therapeutic versus wellness claims. London's centralized procurement frameworks concentrate vendor selection around platforms offering both hardware and usage telemetry.
China
Domestic manufacturers serve household consumer segments with price-competitive electromechanical units for allergen-free pet alternatives. NMPA medical-device classification for emotional health claims remains under development, creating regulatory uncertainty for therapeutic positioning. Shenzhen's electronics ecosystem supplies Li-ion battery systems and sensor modules to international OEMs.
Robotic Pets Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the robotic pets market, creating a tiered structure where integrated manufacturers control component supply while specialized developers focus on behavioral algorithms and clinical certification. The vendor base spans three strategic archetypes: diversified electronics conglomerates with sensor fusion capabilities, purpose-built therapeutic specialists with regulatory expertise, and consumer toy manufacturers with volume manufacturing scale. Competitive moves concentrate on M&A for regulatory compliance infrastructure and strategic partnerships for healthcare channel access.
Within the therapeutic specialist tier, Ageless Innovation LLC and Tombot Inc. exemplify purpose-built positioning through form factors optimized for senior-care and clinical environments respectively. Sony Group Corp. anchors the diversified electronics archetype with proprietary sensor architectures that support premium positioning across companion and entertainment segments. These three entities represent distinct competitive vectors: clinical certification depth, consumer electronics integration, and hyper-realistic design specialization.
| Leading Market Players |
|---|
| Ageless Innovation LLC |
| RobotShop Inc. |
| Sony Group Corp. |
| Silverlit Toys Manufactory Ltd. |
| SoundOriginal Electronics Co. Ltd. |
| WowWee Group Ltd. |
| BIRANCO Ltd. |
| Consequential Robotics Ltd. |
| Tombot Inc. |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility from East Asian spot markets cascades through component tiers, compressing margins on portable electromechanical units while amplifying cost differentials between certified therapy robots and wellness-oriented companions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared therapy platforms from METI-reimbursed companion units and direct-to-consumer novelty devices. Certification grade and embedded AI capability drive price differentiation, with clinical-grade sensor fusion architectures commanding substantial premiums. Pricing pressure stems from Li-ion battery supply concentration and 510(k) pathway delays extending commercialization timelines. Pediatric therapy centers exhibit lowest price sensitivity due to reimbursement alignment, while household animal lovers face highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Sony Group Corp. and Ageless Innovation LLC, while specialized distributors serve clinical procurement networks. Component manufacturing concentrates in Japan, South Korea, and China, with Shenzhen supplying sensor modules and Nagoya's industrial corridor producing servo-actuated systems. Supply chains draw from concentrated Li-ion cell production, rare-earth magnet processing, and pressure-sensitive artificial skin fabrication. Single-source vulnerability in East Asian battery supply creates exposure to logistics disruption and input cost spikes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic pets market functions as a regulatory compounder where EU AI Act compliance infrastructure and FDA classification pathways create durable competitive moats for certified vendors.
For Market Incumbents: Acquire regulatory compliance infrastructure including ISO 13485 quality management systems and EU AI Act technical documentation capabilities. Deepen backward integration into sensor fusion architectures to defend margin position against emerging software-centric entrants. METI reimbursement alignment and FDA 510(k) clearance represent defensible assets that compress rival deployment timelines. For New Entrants and Emerging Players: Mid-market pricing gaps between premium Sony positioning and economy-tier Chinese household units create entry space for clinically positioned challengers. Pediatric therapy channels in the United States offer most penetrable institutional segment given autism intervention program demand. Direct-to-consumer telehealth distribution bypasses entrenched hospital procurement relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with therapeutic specialists possessing dual FDA-EU regulatory clearance and embedded healthcare channel contracts. Five-to-ten year viability favors vendors bundling hardware with longitudinal outcome analytics rather than transactional device sellers. Watch EU AI Act enforcement consistency across Bavarian and North Rhine-Westphalia procurement decisions as inflection signal for compliance-premium durability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA 510(k) and EU AI Act compliance compress rival deployment timelines across healthcare networks. |
| Sensor Fusion Architecture Development | Proprietary multi-modal tactile systems enable premium positioning in clinical companion segments. |
| Hospital System Partnership | Bundled service agreements with NHS trusts displace transactional sales in institutional procurement. |
| Reimbursement Strategy Alignment | METI framework navigation reduces procurement friction in Japanese senior-care networks. |
| Software Companion Development | Natural-language processing integration transcends pre-scripted behavioral libraries for conversational engagement. |
Research Methodology
Bottom-up assisted-living and pediatric therapy modeling reconciled against top-down sensor module and Li-ion battery supply tracking forms the analytical core. Primary interviews with biomedical engineers, hospital GPO contracts managers, senior-care facility procurement directors, and FDA regulatory consultants combined with secondary validation against FDA 510(k) filings, METI standardization documents, EU AI Act technical guidance, and Japanese reimbursement code databases.
Input-output matrices map unit demand across product type, target consumer, technology layer, and market segment dimensions throughout the forecast period. CAGRs derive from regression analysis of historical adoption curves in comparable therapeutic device categories, stress-tested against regulatory timeline assumptions and reimbursement policy trajectories. Forecast inputs include METI framework expansion scenarios and FDA medical-device classification boundary evolution.
Caveats apply where EU AI Act enforcement intensity or FDA classification reinterpretation could materially shift the outlook for therapy robot commercialization. Forecasts embed assumptions regarding Li-ion supply stability and pediatric therapy reimbursement continuity that warrant periodic reassessment. Periodic stress-testing of base assumptions against regulatory milestone delays and raw material price spikes is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Parrot Cage Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Cat Harness Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Cat Mat Market
Pet Care Products
Dog Hats Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Pet Grooming Gloves Market