
 Non-Chocolate Candy Market | 2026-2036
Non-Chocolate Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Chocolate Candy Market Outlook
Asset-light contract manufacturing and third-party co-packing is tilting competitive dynamics toward brands that outsource production rather than build captive facilities. Mars, Incorporated leverages its vertically integrated supply chain to control ingredient costs across gummy and hard candy lines. Haribo GmbH & Co. K.G. anchors its position through specialized fruit-flavor formulation expertise and European manufacturing density. Mondelez International competes by extending its snack-food distribution infrastructure into non-chocolate confectionery shelving in North American retail.
Non-chocolate candy comprises sugar-based or sugar-substitute confections excluding cocoa mass, typically manufactured through starch molding, depositing, or cold extrusion processes to achieve chewable, brittle, or elastic textures for recreational consumption. Gummies dominate value contribution due to premium positioning and gelatin-alternative innovation, while hard candy remains structurally mature with stable margin pools in bulk and seasonal formats. Fruit flavoring leads volume across retail channels, though sour profiles attract adult trial in convenience and specialty stores.
FDA nutrition-labeling rules and EFSA health-claim restrictions shape permissible on-pack messaging and reformulation targets for sugar and additive content. REACH chemical standards in Europe and evolving FDA GRAS reviews for novel sweeteners determine which ingredients gain market access in key jurisdictions. Stakeholders must monitor regulatory divergence between transatlantic frameworks when allocating R&D budgets and plant-certification investments.
Market Dynamics
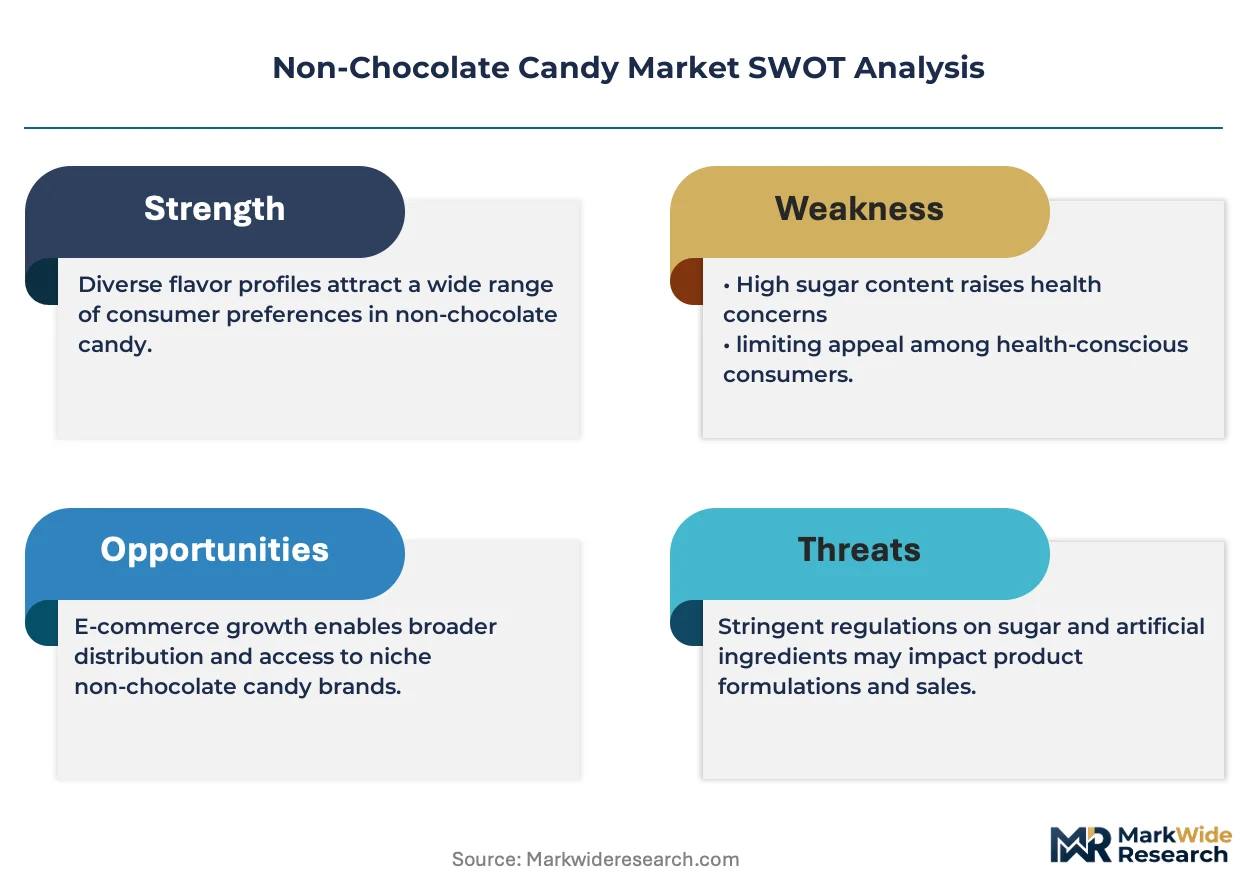
EFSA and FDA sugar-reduction mandates are forcing systematic reformulation across developed markets, compressing traditional glucose-syrup formulations while accelerating clean-label ingredient substitution. Contract manufacturing concentration tilts competitive advantage toward brands with flexible outsourced production networks rather than captive asset bases.
Growth Catalysts
- Permissive Adult Snacking Norms:Workplace candy consumption and permissible indulgence culture normalize non-chocolate confectionery beyond childhood demographics, expanding addressable demand pools in office and convenience channels.
- Gelatin-Alternative Innovation:Pectin and agar-agar starch molding technologies unlock vegan-positioned gummy segments, capturing dietary-restriction households previously excluded from traditional gelatin-based products.
- Seasonal Merchandising Intensity:United States convenience-store chains deploy Halloween and holiday-themed display programming that drives impulse volume through high-visibility checkout placement.
Market Restraints
- Input Cost Volatility:Corn syrup and citric acid feedstock prices fluctuate with agricultural commodity cycles, squeezing margin predictability for depositing-process manufacturers.
- Regulatory Friction:FDA GRAS review timelines for novel sweeteners extend 18-24 months, delaying reformulated product launches and freezing pipeline innovation.
- Substitution Threat:Protein-enriched snack bars and dried-fruit alternatives capture permissive-snacking occasions, diverting spend from traditional sugar confectionery.
Strategic Opportunities
- Underpenetrated Indian Urban Markets:Modern trade expansion in Tier-2 cities creates shelf-space availability for imported and domestic non-chocolate brands targeting aspirational middle-class households.
- Functional Ingredient Convergence:Collagen-infused gummies and probiotic hard candies merge wellness positioning with confectionery formats, capturing pharmacy and specialty retail distribution.
- Direct-to-Consumer Subscription Channels:Curated monthly candy boxes bypass traditional retail slotting fees, enabling niche flavor experimentation and customer data capture.
Industry Challenges
- Clean-Label Reformulation Expertise Gap:Food scientists skilled in natural color stability and reduced-sugar texture engineering command premium compensation, constraining R&D team scaling.
- Multi-Jurisdiction Certification Complexity:Simultaneous FDA facility registration, EFSA health-claim substantiation, and BIS compliance for Indian export create timeline coordination burdens.
- Cold Extrusion Equipment Lead Times:Specialized starch molding and depositing machinery from European suppliers extend 14-18 months, delaying capacity expansion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Chocolate Candy Market |
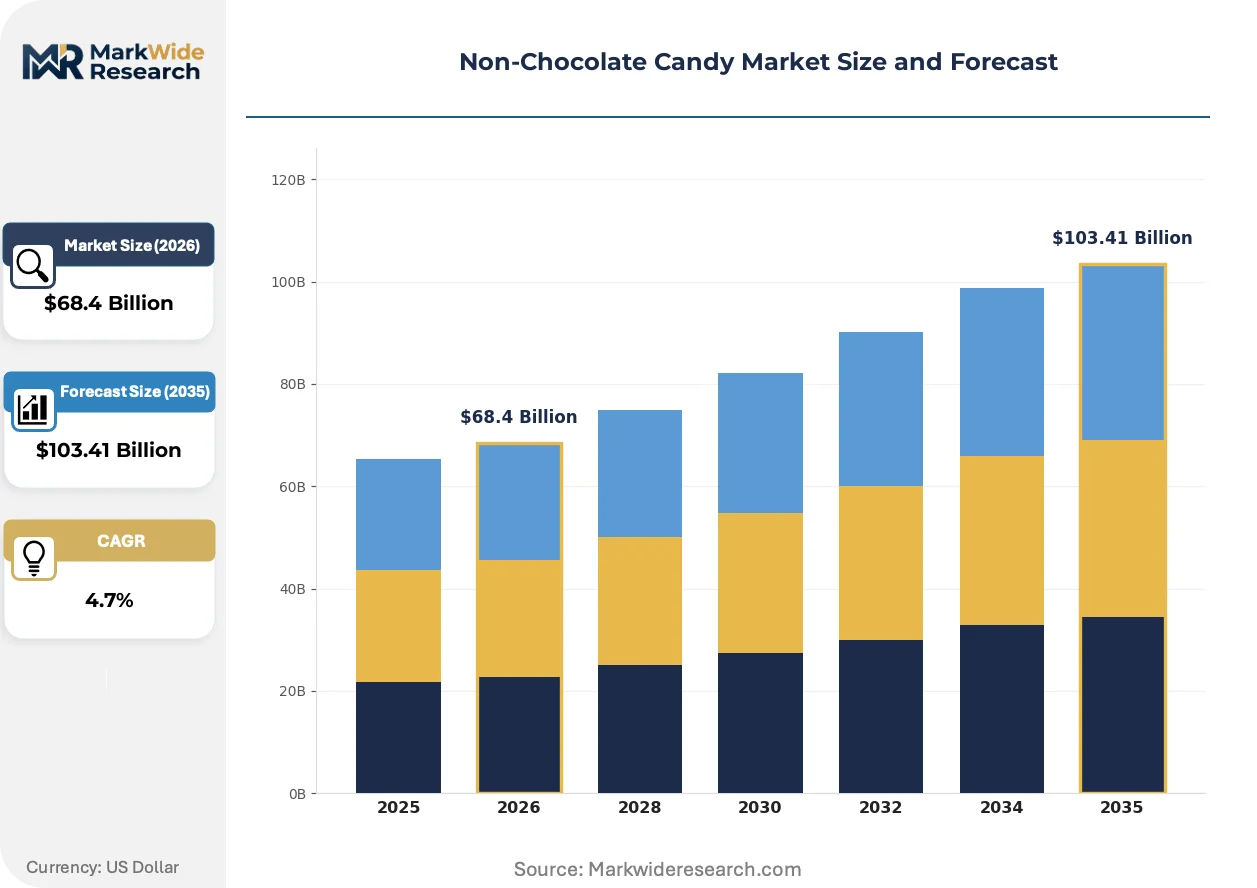
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Hard Candy, Licorice, Taffy End User: Children, Adults, Retailers, Distributors Flavor: Fruit, Sour, Mint, Herbal Packaging Type: Bags, Boxes, Jars, Bulk |
| Companies Covered | Nestlé SA, Haribo GmbH & Co. K.G., Mars, Incorporated, Pladis, Chocoladefabriken Lindt & Sprüngli AG, Mondelez International, The Hershey Company, Meiji Co. Ltd., Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Chocolate Candy Market Strategic Shifts
Reformulation chemistry and manufacturing process adaptation dominate competitive investment, as regulatory pressure and consumer ingredient scrutiny converge to reshape product architecture and supply chain configuration simultaneously.
Pectin-based gummy matrices is migrating from niche vegan positioning toward mainstream formulation standards as adult consumers reject gelatin sourcing transparency concerns. Mid-market brands in Germany and the United States adopt pectin at accelerated pace, compressing cost premiums that previously confined plant-based alternatives to premium tiers. The technology is migrating from specialty channels into mass-market retail, eroding gelatin's structural dominance across fruit-flavored chewy segments.
EFSA nutrient profiling and health-claim restrictions are tightening permissible on-pack messaging for sugar-reduced variants, forcing manufacturers to invest in clinical substantiation for functional positioning. The industrial consequence shifts marketing spend from front-of-pack claims toward back-panel ingredient storytelling and third-party certification badges. Sugar-free hard candy lines in France and Italy face the strictest compliance scrutiny, with several major portfolios undergoing 2024-2025 label revision cycles.
Convenience-store merchandising contracts are compressing supplier assortment breadth as chains consolidate shelf sets around proven velocity SKUs. Single-serve peg bags and seasonal clip strips displace bulk bin formats in United States petroleum retail, privileging branded manufacturers with promotional programming budgets. This concentration is most visible in the southeastern United States, where regional c-store operators have reduced non-chocolate candy facings by 15-20 percent while expanding energy drink adjacencies.
Non-Chocolate Candy Market Segmentation
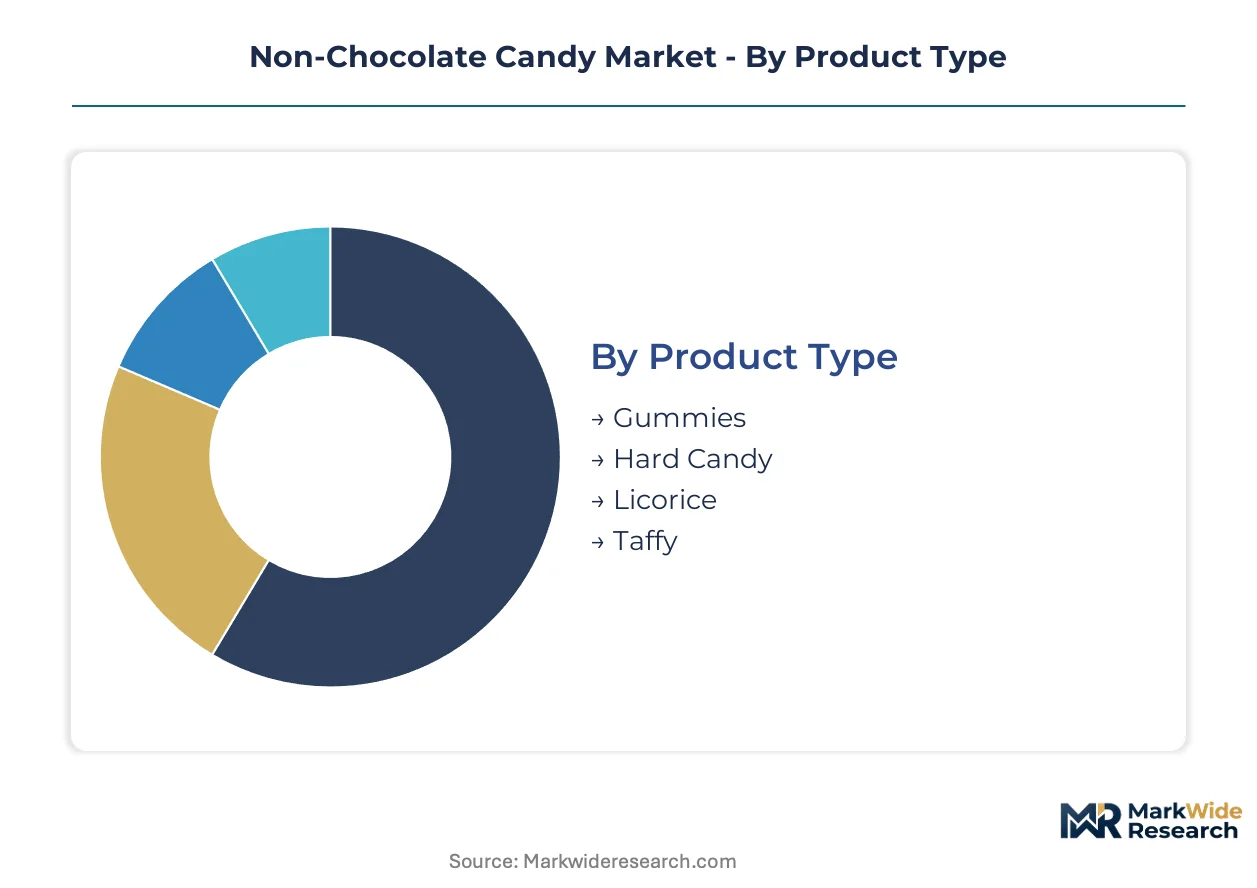
Segmentation in non-chocolate confectionery reveals divergent margin profiles and inventory velocity patterns. Product texture determines manufacturing asset requirements, while end-user demographics dictate channel placement and permissible indulgence messaging strategies.
Product Type:
Gummy and hard candy segments rotate through retail shelves at markedly different velocities, with chewable formats turning faster due to trial-size packaging and seasonal impulse programming.
- Gummies:Gelatin or pectin-based matrices formed through starch molding deliver elastic, chewable textures. Adult consumers in the United States and Germany drive demand for vegan pectin variants as permissive snacking normalizes workplace consumption. Pectin-alternative R&D compresses cost premiums that previously confined plant-based positioning to specialty tiers.
- Hard Candy:Glassy amorphous solids produced via depositing or cold extrusion yield brittle, slow-dissolve formats. Seasonal merchandising in United States convenience stores stabilizes volume despite structural maturity, with bulk and peg-bag formats maintaining predictable margin pools. EFSA sugar-reduction mandates force reformulation of traditional glucose-syrup bases.
- Licorice:Wheat flour and molasses-based extruded ropes dominate Northern European preference clusters, with Dutch and Finnish consumers sustaining niche export demand.
- Taffy:Aerated sugar-gelatin pulls manufactured through batch pulling or continuous extrusion serve regional United States coastal markets and tourist-destination retail.
Hard candy anchors the volume base while gummies gain share at the steepest rate.
End User:
Customer type stratification follows permissive indulgence culture diffusion, with adult-targeted positioning commanding shelf-space expansion in office and convenience channels previously dominated by juvenile demographics.
- Adults:Workplace snacking normalization and permissible indulgence framing expand addressable occasions beyond traditional treat contexts. United States convenience-store chains deploy checkout placement and clip-strip programming to capture commuter and office-worker trial. Sugar-reduced and functional-infused variants target pharmacy and specialty retail distribution.
- Children:Parental gatekeeping and school nutrition policies constrain traditional glucose-heavy formats, though licensed character merchandising and portion-controlled packaging sustain volume in mass retail. Halloween and holiday seasonal programming in the United States drives concentrated demand spikes.
- Retailers:United States petroleum retail and drugstore chains consolidate shelf sets around velocity-proven SKUs, compressing supplier assortment breadth and privileging promotional programming budgets.
- Distributors:Foodservice and vending channel intermediaries manage bulk-format logistics for institutional and away-from-home consumption occasions.
Children sustain the installed demand base while adult-targeted segments expand most quickly.
Flavor:
Flavor preference maps to channel type and permissible indulgence occasion, with fruit profiles dominating mass retail and sour variants capturing adult trial in convenience and specialty formats.
- Fruit:Citrus, berry, and tropical profiles formulated through natural and nature-identical flavor systems constitute the volume backbone across retail channels. Clean-label ingredient storytelling displaces front-of-pack health claims as EFSA restrictions tighten.
- Sour:Citric acid and malic acid coating technologies deliver palate-stimulating profiles attracting adult trial seekers in United States convenience stores and specialty candy shops. pH stability challenges constrain shelf-life extension.
- Mint:Menthol and peppermint oils serve breath-freshening occasions and pharmacy-channel positioning, with sugar-free variants dominating dental-office and clinic-adjacent retail.
- Herbal:Botanical extracts and traditional medicine-inspired formulations capture wellness-positioned segments in European and Asian specialty channels.
Fruit flavoring commands the volume base while sour profiles climb the fastest.
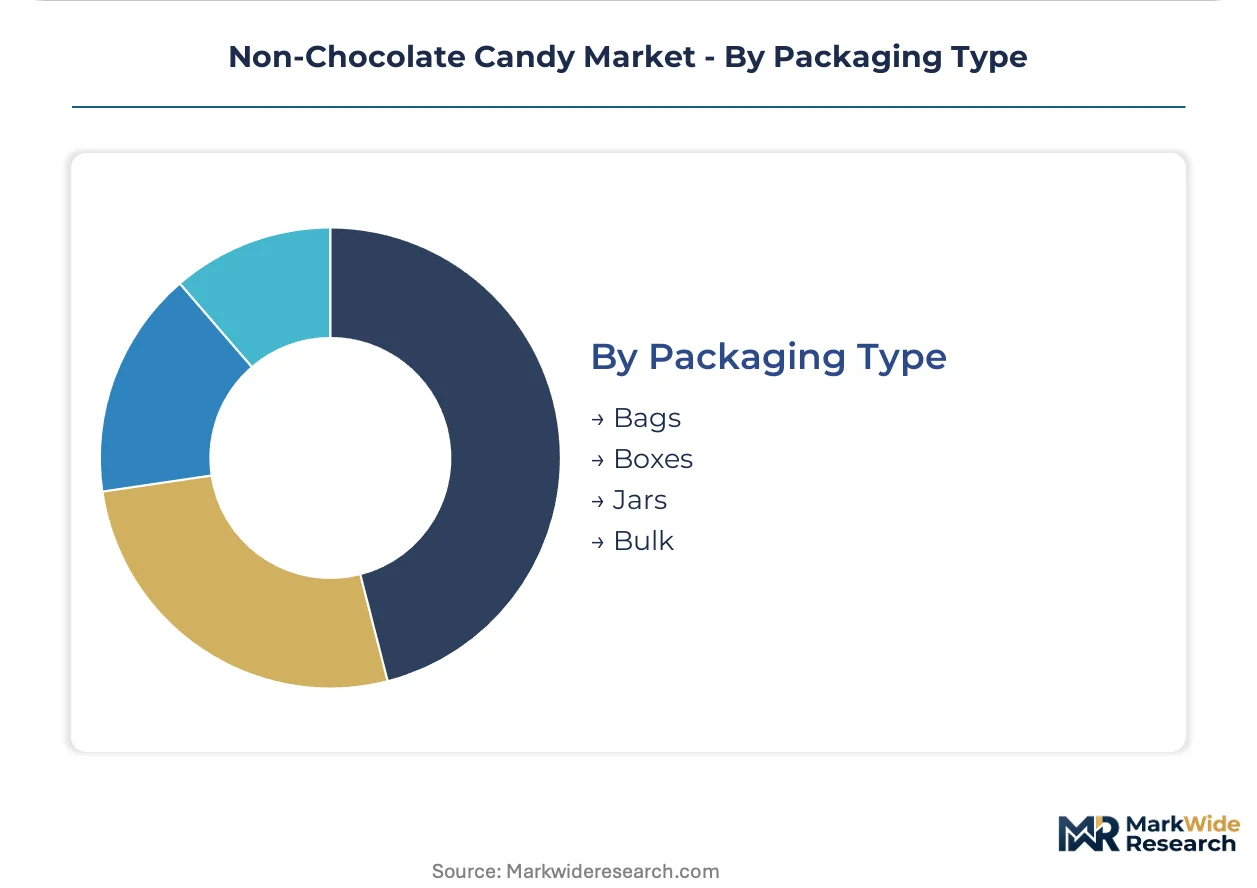
Packaging Type:
Packaging configuration determines channel access and margin capture, with single-serve formats displacing bulk in United States petroleum retail while subscription and direct-to-consumer channels experiment with curated assortment boxes.
- Bags:Flexible pillow pouches and stand-up pouches dominate peg-hook and clip-strip merchandising in United States convenience stores, with seasonal graphics programming driving impulse conversion at checkout.
- Boxes:Rigid cartons and gift tins serve seasonal gifting occasions and premium-positioned pharmacy and specialty retail, with EFSA labeling compliance costs absorbed through higher price points.
- Jars:Rigid plastic and glass containers target pantry-stocking and sharing occasions in club and mass retail, with resealability extending consumption windows.
- Bulk:Bin and case formats persist in club retail and foodservice channels despite United States convenience-store displacement, with portion-control concerns constraining expansion.
Bags anchor the volume base while boxes gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances reveal divergent consumption patterns across major economies, with developed markets importing specialty formulations while emerging economies build domestic manufacturing capacity to serve growing middle-class demand.
United States
Convenience-store distribution networks and seasonal merchandising programs drive impulse volume through petroleum retail and drugstore channels. FDA nutrition-labeling rules and GRAS review timelines shape permissible on-pack messaging and reformulation targets for sugar-reduced variants. The southeastern United States shows concentrated c-store operator consolidation, with regional chains reducing non-chocolate candy facings while expanding checkout placement for velocity-proven SKUs.
Germany
Fruit-flavor formulation expertise and pectin-based gummy innovation attract adult consumers seeking clean-label alternatives to traditional gelatin products. EFSA health-claim restrictions and nutrient profiling standards tighten compliance requirements for sugar-reduced positioning. The Baden-Württemberg and Bavaria industrial clusters host specialized starch molding equipment suppliers serving mid-market brands adopting vegan formulation standards.
India
Modern trade expansion in Tier-2 cities creates shelf-space availability for domestic and imported brands targeting aspirational middle-class households. FSSAI labeling mandates and BIS certification requirements for imported confectionery create multi-jurisdiction compliance burdens for exporters. Maharashtra and Gujarat manufacturing zones are developing contract manufacturing capacity to serve both domestic demand and regional export markets.
Japan
Functional ingredient convergence and wellness-positioned confectionery formats capture pharmacy and specialty retail distribution channels. METI standards and PMDA guidance influence permissible claims for collagen-infused and probiotic candy variants. The Kanto region around Tokyo anchors premium product development, with Osaka-Kansai manufacturers focusing on portion-controlled packaging for aging demographic segments.
Brazil
Sugar-based traditional confectionery consumption sustains volume in mass retail while imported brands test premium positioning in urban centers. ANVISA food additive regulations and labeling standards determine which reformulated products gain market access. São Paulo state concentrates distribution infrastructure, with regional distributors managing logistics for both domestic manufacturers and Mercosur-sourced imports.
Non-Chocolate Candy Market Competitive Environment
On the supply side, the industry is consolidating around asset-light contract manufacturing networks rather than captive production facilities, with competitive advantage tilting toward brands that outsource manufacturing while retaining formulation and marketing capabilities. Three archetypes dominate: vertically integrated multinationals controlling ingredient costs through captive supply chains, specialized flavor houses leveraging European manufacturing density, and snack-food conglomerates extending distribution infrastructure into confectionery shelving. Dominant competitive moves include strategic co-packing partnerships and portfolio diversification into functional ingredient segments.
Among multinational confectionery conglomerates, Mars, Incorporated and Mondelez International occupy positions exemplifying divergent supply chain strategies, with the former maintaining in-house production control and the latter leveraging snack-food distribution reach. Haribo GmbH & Co. K.G. represents the specialized formulation archetype, with its European manufacturing footprint supporting fruit-flavor expertise. These three companies anchor the competitive structure, with their strategic choices influencing industry-wide patterns in outsourcing, reformulation investment, and channel placement priorities.
| Leading Market Players |
|---|
| Nestlé SA |
| Haribo GmbH & Co. K.G. |
| Mars, Incorporated |
| Pladis |
| Chocoladefabriken Lindt & Sprüngli AG |
| Mondelez International |
| The Hershey Company |
| Meiji Co. Ltd. |
| Ferrero Group |
| Others |
Value Chain & Pricing Dynamics
Corn syrup and citric acid feedstock volatility determines both pricing tier spreads and supply chain shape across non-chocolate confectionery manufacturing, compressing margin predictability for depositing-process manufacturers while accelerating asset-light contract manufacturing adoption.
Pricing Analysis
Convenience-store chains and petroleum retail buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on gelatin versus pectin formulation grades and seasonal merchandising programming budgets. Pricing pressure stems from EFSA sugar-reduction mandates forcing costly reformulation of traditional glucose-syrup bases. Private-label and contract-manufactured entrants exhibit highest price sensitivity, while vertically integrated multinationals with captive ingredient sourcing maintain pricing flexibility.
Supply Chain Analysis
Upstream corn syrup and gelatin feedstock supply concentrates in the United States, Brazil, and Argentina agricultural belts, with European pectin and natural colorant suppliers in Germany and France providing clean-label alternatives. Raw material dependencies include corn-derived sweeteners, bovine and porcine gelatin, and citric acid from fermentation processes. Single-source vulnerability in specialized starch molding equipment from German and Italian suppliers creates 14-18 month capacity expansion bottlenecks. Distribution runs through United States convenience-store chains and European modern trade networks, with direct-to-consumer subscription channels emerging as alternative downstream pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-chocolate confectionery functions as a service-attach opportunity where curated subscription boxes and seasonal merchandising programming generate recurring revenue streams expanding faster than base product manufacturing.
For Market Incumbents: Insulate core margin pools by deepening backward integration into pectin and natural colorant supply chains, while accelerating FDA GRAS substantiation investments to preempt regulatory chokepoints on novel sweetener formulations. Defend shelf-space positioning through promotional programming budgets that match convenience-store chain consolidation trends. For New Entrants and Emerging Players: Build out contract manufacturing partnerships in Maharashtra and Gujarat industrial zones to serve underpenetrated Indian Tier-2 urban markets, where modern trade expansion creates shelf-space availability absent entrenched competitor presence. Capture trial through direct-to-consumer subscription channels enabling flavor experimentation without retail slotting fee burdens. For Investors and Strategic Acquirers: The market sits at a reformulation-intensive phase that favors asset-light brands with flexible outsourced production networks over captive facility operators. Acquisition targets should demonstrate clean-label R&D capabilities and established co-packer relationships. Monitor FDA GRAS review timeline acceleration as the signal indicating pipeline innovation thaw and valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin-Based Reformulation Investment | Captures vegan-positioned segments as gelatin alternatives migrate from premium to mass-market tiers. |
| Contract Manufacturing Partnership | Enables asset-light scaling in Maharashtra and Gujarat zones serving domestic and regional export demand. |
| Seasonal Merchandising Programming | Secures high-visibility checkout placement in United States petroleum retail during Halloween and holiday periods. |
| Direct-to-Consumer Subscription Launch | Bypasses consolidated shelf sets while capturing customer data for flavor innovation pipelines. |
| Functional Ingredient Convergence | Opens pharmacy and specialty retail distribution through collagen-infused and probiotic candy variants. |
Study Parameters
Desk research of FDA GRAS submission databases, EFSA health-claim registers, and Nielsen retail audit data preceded structured interviews with brand managers, category buyers at United States convenience-store chains, contract manufacturing operations heads, and food science R&D directors. Primary fieldwork combined with secondary validation from customs records and SEC filings of publicly traded confectionery conglomerates. Bottom-up SKU-level volume modeling and top-down category expenditure analysis provided triangulation checks across the analysis window.
Assumptions held fixed include EFSA nutrient profiling standards and FDA labeling rules throughout the projection horizon, with variables tested across pectin cost compression scenarios and convenience-store facing reduction rates. Segmentation dimensions modeled encompass product texture, end-user demographic, flavor profile, and packaging configuration. CAGRs were derived from trend extrapolation of permissive adult snacking normalization rates and seasonal merchandising intensity indices.
Stress conditions across corn syrup price volatility, FDA GRAS review timeline extension, and United States c-store operator consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with sugar-substitute technology breakthroughs and alternative protein snack substitution rates representing primary revision risks. Cross-checking against Circana retail velocity data and FSSAI import registration trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Green Tea Chocolate Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Cookie Dough Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Sugar Free Mints Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Europe Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Sugar Free Candy Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Chocolate Flavors Market
Confectionery
Carob Chocolate Market
Confectionery
Global Confectionery Market